
Market Overview:
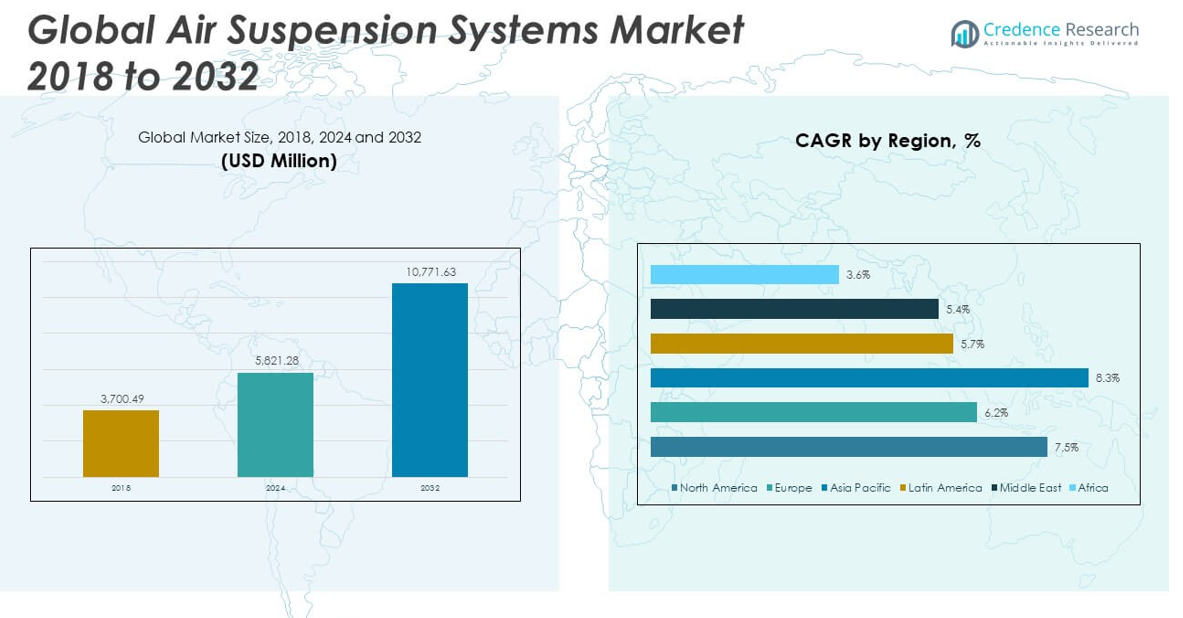
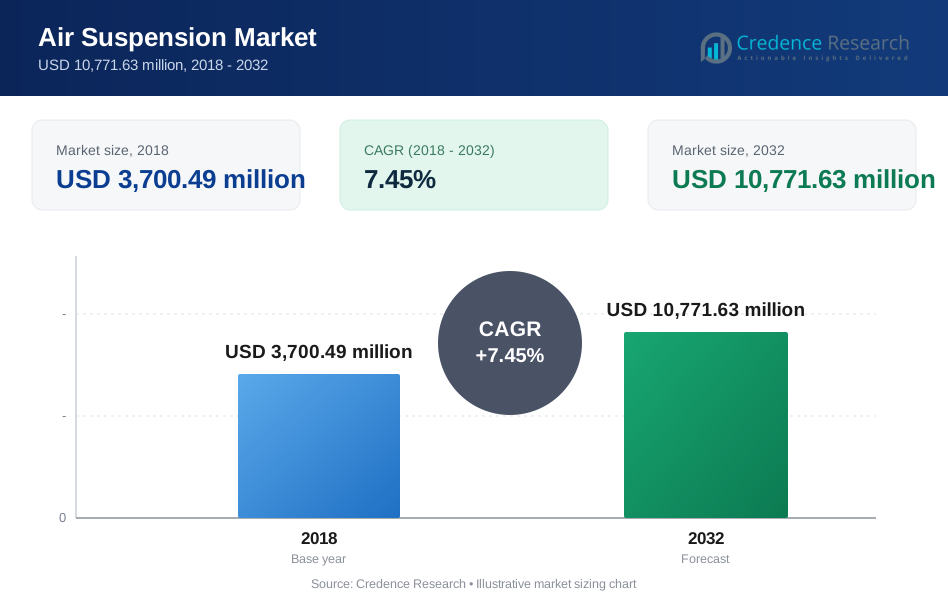
The Global Air Suspension Systems Market size was valued at USD 3,700.49 million in 2018 to USD 5,821.28 million in 2024 and is anticipated to reach USD 10,771.63 million by 2032, at a CAGR of 7.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Air Suspension Market Size 2024 | USD 5,821.28 million |
| Air Suspension Market, CAGR | 7.45% |
| Air Suspension Market Size 2032 | USD 10,771.63 million |
The growth of the global air suspension systems market is primarily driven by the increasing demand for improved ride comfort, vehicle safety, and load-handling capabilities. Consumers are seeking smoother driving experiences, especially in luxury and premium vehicles, where air suspension systems enable superior shock absorption and adjustable ride height. In the commercial vehicle sector, air suspension enhances load stability, reduces cargo damage, and improves driver comfort—key factors for fleet operators. Moreover, the adoption of electronically controlled air suspension (ECAS) is gaining traction due to its intelligent, real-time response to road and load conditions, contributing to fuel efficiency and reduced maintenance. The shift toward electric and autonomous vehicles also supports market expansion, as these platforms require lightweight, adaptable suspension systems. Additionally, stringent emission regulations and government mandates focused on vehicle safety and efficiency are pushing OEMs to adopt air suspension technologies, further boosting global demand across passenger and commercial vehicle segments.
North America holds a substantial share of the global air suspension systems market, driven by a high concentration of premium vehicles, commercial fleets, and technologically advanced infrastructure. The U.S. leads the region, with strong demand from both OEMs and the aftermarket, particularly in the luxury SUV and heavy-duty truck segments. In Europe, market growth is fueled by established automotive manufacturing hubs in Germany, France, and the U.K., where brands like Mercedes-Benz, BMW, and Audi integrate air suspension as a standard or optional feature. The region benefits from supportive regulatory policies encouraging safety, emission reduction, and advanced suspension technologies. Asia Pacific is the fastest-growing region, led by China, Japan, and India, where rising disposable incomes, urbanization, and expanding EV and commercial fleets are accelerating adoption. China, in particular, is witnessing significant deployment of air suspension in electric buses and logistics trucks. Meanwhile, Latin America and the Middle East & Africa show gradual growth, driven by modernization of transport infrastructure.
Market Insights:
- The Global Air Suspension Systems Market reached USD 5,821.28 million in 2024 and is projected to grow to USD 10,771.63 million by 2032 at a CAGR of 7.45%.
- Rising demand for enhanced ride comfort, stability, and shock absorption in luxury and commercial vehicles is fueling global market growth.
- Electronically Controlled Air Suspension (ECAS) is gaining traction for its real-time load response, supporting better control, fuel efficiency, and system automation.
- OEMs are increasingly integrating air suspension systems into electric and autonomous vehicles to manage varying load weights and optimize ride quality.
- Regulatory mandates focused on emission control and safety standards are encouraging widespread adoption in commercial transport and logistics fleets.
- High system costs and complex installation procedures continue to challenge adoption, particularly in cost-sensitive and emerging markets.
- Asia Pacific leads global growth, with China, India, and Japan driving demand, while North America and Europe maintain strong shares through premium automotive and freight sectors.
Market Drivers:
Rising Demand for Ride Comfort and Driving Stability in Luxury and Commercial Vehicles
Consumers increasingly prioritize vehicle comfort, stability, and driving experience. Air suspension systems offer superior ride quality by adjusting the suspension based on road conditions and load weight. This technology minimizes road vibrations and enhances passenger comfort, especially in luxury sedans, SUVs, and long-haul commercial trucks. The Global Air Suspension Systems Market benefits from this shift toward comfort-oriented vehicle features. Manufacturers in both premium passenger and commercial segments are integrating these systems to enhance overall vehicle performance. The ability to maintain consistent ride height and reduce body roll during sharp turns or heavy braking positions air suspension as a preferred technology. Demand from luxury vehicle buyers and fleet operators continues to support steady market expansion.
- For instance, Dunlop Systems & Componentshas supplied over 250,000 ECAS (Electronically Controlled Air Suspension) systems globally, working closely with major vehicle manufacturers to deliver advanced air bellows that enhance stability and comfort by providing automatic vehicle leveling and selectable ride height configurations.
Growing Integration of Electronically Controlled Systems for Precision and Safety
Electronically Controlled Air Suspension (ECAS) is transforming the way vehicles manage load and stability. ECAS adjusts air pressure in real time to maintain optimal ride height, improving control and handling. It contributes to better fuel efficiency and reduced tire wear, making it appealing for both passenger and freight applications. The Global Air Suspension Systems Market is witnessing rapid integration of ECAS in new vehicle models. Automakers are focusing on system reliability, diagnostics, and automation to meet safety standards and customer expectations. ECAS also supports advanced driving assistance systems (ADAS), aligning well with the future of connected and autonomous vehicles. Its role in enhancing both comfort and operational efficiency is shaping purchasing decisions.
Regulatory Push for Emissions Reduction and Safer Heavy-Duty Transport
Governments worldwide are tightening regulations on emissions, fuel economy, and transport safety. Air suspension systems help vehicles meet these standards by optimizing aerodynamic profiles through adjustable ride height. In heavy-duty transport, air suspension reduces axle loads and improves braking performance, making it a practical solution for regulatory compliance. The Global Air Suspension Systems Market is gaining momentum in regions with strict vehicle performance laws. Truck and trailer manufacturers increasingly adopt air suspension to qualify for incentives and comply with evolving regulations. These systems also support lower environmental impact by improving road wear and fuel usage. Policy-driven demand is expected to accelerate technology upgrades across commercial fleets.
Shift Toward Electric and Autonomous Vehicle Platforms Requires Adaptive Suspension
Electric and autonomous vehicles require lighter, smarter, and adaptive components. Air suspension fits this requirement by delivering load-leveling and responsive chassis control without adding excessive weight. It ensures passenger comfort and stability in EVs, where battery placement and weight distribution vary significantly. The Global Air Suspension Systems Market is adapting to serve this shift by offering modular, electronically managed systems. OEMs are customizing air suspension solutions for electric platforms to enhance performance and cabin experience. Its ability to integrate with digital vehicle controls makes it an essential component for future-ready mobility solutions. The need for intelligent suspension in next-generation vehicles continues to drive innovation and adoption.
- For instance, Corteco, through its partnership with Vibracoustic, has developed and patented stand-alone air springs that are now being adopted as original equipment in electric vehicles to protect battery technology and ensure optimal ride comfort.
Market Trends:
Rising Popularity of Modular and Scalable Air Suspension Architectures
Vehicle manufacturers are shifting toward modular air suspension platforms to streamline production and reduce integration costs. These systems can be easily adapted to various vehicle models, from sedans to commercial trucks, without requiring major structural changes. The Global Air Suspension Systems Market is witnessing higher demand for scalable solutions that support both standard and premium variants within a vehicle lineup. OEMs benefit from reduced development time and greater design flexibility by adopting modular architectures. It allows manufacturers to introduce advanced suspension features across broader price ranges. This trend supports economies of scale and enhances compatibility with electrified powertrains. Automakers increasingly prioritize modularity in their chassis design strategies.
- For example, ZF’s AIRTRAC and OptiRide ECAS systems exemplify the latest achievements in modular, scalable air suspension platforms for commercial vehicles. AIRTRAC is individually configurable for 4x2, 6x4, or 6x2 applications and supports both low-deck and standard ride heights, enabling adaptation across multiple vehicle types without major structural changes.
Growing Adoption of Lightweight Materials for Efficiency and Performance
The industry is moving toward the use of lightweight materials such as high-strength aluminum and composite plastics in air suspension components. These materials help reduce overall vehicle weight without compromising strength or performance. The Global Air Suspension Systems Market is evolving to meet fuel efficiency and range requirements, particularly in electric and hybrid vehicles. Lighter suspension systems improve energy efficiency and lower emissions in internal combustion engine vehicles. It also enables better handling and quicker suspension response, which improves both comfort and safety. Suppliers are investing in new manufacturing techniques to produce durable and lightweight parts at scale. This material innovation supports regulatory compliance and next-generation vehicle requirements.
- For example, Kenworth Truck Company reduced suspension system weight by 400 pounds using air-ride suspension, and SAF Holland’s CBX23 AeroBeam fixed frame air suspension leverages textile-reinforced rubber air springs for further weight savings.
Expansion of Aftermarket Air Suspension Upgrades for Customization and Performance
The aftermarket segment is experiencing notable growth as vehicle enthusiasts and fleet operators seek advanced suspension upgrades. Consumers are investing in retrofitting air suspension systems to improve comfort, aesthetics, and load-handling capabilities. The Global Air Suspension Systems Market is benefiting from the rising demand for customized performance features in both light and heavy vehicles. It reflects a shift in consumer behavior toward enhancing vehicle lifespan and driving dynamics. Aftermarket players are offering electronically controlled conversion kits that are compatible with a wide range of models. This trend also opens new revenue streams for service centers and specialist suppliers. The demand for personalization and performance optimization continues to strengthen aftermarket sales.
Integration with Predictive Maintenance and Telematics for Operational Efficiency
Air suspension systems are increasingly being integrated with vehicle telematics to enable predictive diagnostics and maintenance scheduling. This development allows fleet managers to monitor suspension health in real time and plan servicing more effectively. The Global Air Suspension Systems Market is aligning with broader automotive digitization trends through such innovations. It supports reduced vehicle downtime, longer component lifespan, and improved safety. Predictive maintenance tools help identify wear patterns and prevent unexpected failures. It also enhances fleet cost control and operational visibility. Suspension systems with built-in sensors and connectivity features are becoming key components in intelligent transportation networks.
Market Challenges Analysis:
High Cost of Air Suspension Systems Limits Broader Market Penetration
Air suspension systems are significantly more expensive than conventional coil or leaf spring setups. The high initial cost, along with complex installation and maintenance requirements, poses a major barrier to widespread adoption. The Global Air Suspension Systems Market faces challenges in price-sensitive regions where vehicle affordability remains a key concern. Manufacturers struggle to balance advanced performance features with cost-effective production, especially in entry-level and mid-range vehicles. It becomes difficult for OEMs to justify the added expense in markets with low customer willingness to pay for premium features. Replacement parts and system calibration require specialized equipment and trained technicians, which adds to long-term ownership costs. This financial hurdle slows adoption in both the passenger and commercial segments.
Technical Complexity and Reliability Concerns Impact Adoption Across Regions
Air suspension systems rely on a combination of electronic sensors, air compressors, control modules, and actuators, making them technically complex. Failure in any component can affect overall ride quality, leading to concerns about reliability among fleet operators and vehicle owners. The Global Air Suspension Systems Market must address issues related to long-term durability, especially under harsh environmental conditions. Dust, moisture, and extreme temperatures can compromise system performance over time. It requires ongoing R&D investment to improve reliability and reduce susceptibility to breakdowns. Limited availability of trained service professionals in emerging markets also hampers maintenance and repair services. These technical and operational challenges can reduce consumer confidence in adopting air suspension technologies.
Market Opportunities:
Expansion of Electric and Autonomous Vehicles Creates New Application Scope
The rapid growth of electric and autonomous vehicles opens new avenues for air suspension system integration. These vehicles require advanced chassis technologies to manage varying loads and ensure smooth operation. The Global Air Suspension Systems Market stands to benefit as EV manufacturers seek systems that support adaptive ride height, better aerodynamics, and increased passenger comfort. It offers significant value in vehicles with underfloor battery packs, where load leveling and ride stability are essential. Air suspension also enhances occupant experience in autonomous vehicles by minimizing vibrations and maintaining balance during automated maneuvers. This alignment with next-generation mobility trends positions the market for long-term growth.
Rising Demand for Smart Cities and Connected Mobility Solutions
The push for smart cities and intelligent transportation systems is creating strong demand for connected, sensor-driven automotive components. Air suspension systems with telematics and predictive maintenance capabilities align well with these urban mobility goals. The Global Air Suspension Systems Market can leverage this trend by offering data-enabled solutions that improve vehicle uptime and optimize maintenance cycles. It creates opportunities for integration with fleet management platforms and real-time diagnostics tools. Governments and city planners are investing in technology-driven public and freight transport solutions, which could accelerate adoption in buses and logistics vehicles. This shift presents a clear growth path for innovative suppliers.
Market Segmentation Analysis:
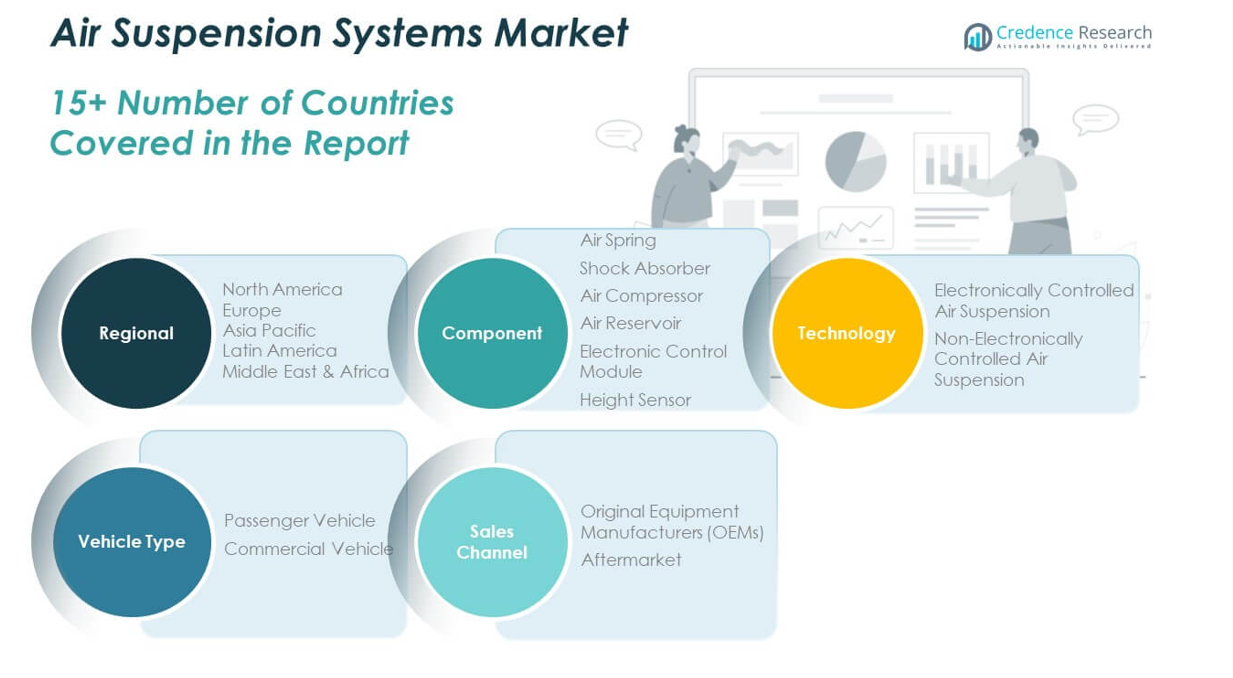
The Global Air Suspension Systems Market is segmented by component, technology, vehicle type, and sales channel.
By components, air springs hold a dominant share due to their role in maintaining ride height and comfort across varying loads. Shock absorbers and air compressors also contribute significantly, supporting stability and smooth performance. The electronic control module and height sensor segments are gaining importance with the rising integration of advanced driver assistance systems.
- For example, Continental’s Air Spring Systemsare widely used in commercial vehicles for maintaining consistent ride height and comfort regardless of load. According to Continental, their air springs can support axle loads up to 13 tons and are engineered to provide optimal damping and ride quality across varying cargo weights.
By technology, Electronically Controlled Air Suspension (ECAS) leads the market due to its precision, adaptability, and compatibility with connected vehicle platforms. It offers real-time ride adjustments and supports integration with telematics and predictive maintenance systems. Non-electronically controlled air suspension maintains relevance in cost-sensitive markets where basic performance is sufficient.
- For example, Mercedes-Benz AIRMATICis a flagship ECAS system, offering automatic and driver-selectable ride height adjustments, integration with ADAS, and real-time adaptation to road and load conditions.
By vehicle type, commercial vehicles dominate due to the need for load stability and ride comfort in logistics and transport. Passenger vehicles, particularly in the premium segment, continue to adopt air suspension for enhanced driving experience.
By sales channel, OEMs account for the majority share, while the aftermarket segment grows steadily due to rising demand for customization and replacements. The market shows balanced growth across all segments, driven by both functional and technological demands.
Segmentation:
By Component:
- Air Spring
- Shock Absorber
- Air Compressor
- Air Reservoir
- Electronic Control Module
- Height Sensor
By Technology:
- Electronically Controlled Air Suspension (ECAS)
- Non-Electronically Controlled Air Suspension
By Vehicle Type:
- Passenger Vehicle
- Commercial Vehicle
By Sales Channel:
- Original Equipment Manufacturers (OEMs)
- Aftermarket
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Air Suspension Systems Market size was valued at USD 1,156.03 million in 2018 to USD 1,792.17 million in 2024 and is anticipated to reach USD 3,329.14 million by 2032, at a CAGR of 7.5% during the forecast period. North America accounts for 26% of the Global Air Suspension Systems Market, driven by strong adoption in both luxury passenger vehicles and commercial trucks. The U.S. dominates regional demand due to high consumer preference for SUVs and heavy-duty vehicles equipped with advanced comfort systems. The presence of leading automakers and Tier 1 suppliers supports innovation and deployment across vehicle categories. It benefits from a mature automotive infrastructure and favorable regulatory environment promoting safety and vehicle efficiency. Fleet operators increasingly invest in air suspension to enhance driver comfort and vehicle uptime. The region also sees rising aftermarket demand for retrofitting air suspension kits in pickup trucks and off-road vehicles.
The Europe Air Suspension Systems Market size was valued at USD 693.66 million in 2018 to USD 1,031.66 million in 2024 and is anticipated to reach USD 1,736.63 million by 2032, at a CAGR of 6.2% during the forecast period. Europe holds 15% of the Global Air Suspension Systems Market, led by Germany, the U.K., and France. Premium vehicle manufacturers such as Mercedes-Benz, Audi, and BMW integrate air suspension as a core feature in sedans and SUVs. It also finds wide use in trailers and heavy-duty trucks across the region, supported by EU transport regulations focused on load distribution and ride safety. European consumers favor advanced ride technologies, pushing OEMs to expand air suspension offerings. Growing urban mobility projects and investment in electric buses further stimulate regional demand. Europe's strong aftermarket ecosystem also enables widespread servicing and upgrades.
The Asia Pacific Air Suspension Systems Market size was valued at USD 1,522.16 million in 2018 to USD 2,488.45 million in 2024 and is anticipated to reach USD 4,902.33 million by 2032, at a CAGR of 8.3% during the forecast period. Asia Pacific dominates with 37% share of the Global Air Suspension Systems Market, fueled by rising vehicle production and urbanization. China leads in adoption, particularly in electric buses and long-haul logistics vehicles, where ride control is critical. India and Japan are also witnessing steady integration across high-end passenger cars and commercial fleets. It benefits from government-led electrification and infrastructure development programs. OEMs in the region are investing in locally manufactured systems to reduce costs and improve scalability. The demand for luxury vehicles with advanced comfort features continues to grow across urban centers.
The Latin America Air Suspension Systems Market size was valued at USD 167.78 million in 2018 to USD 260.52 million in 2024 and is anticipated to reach USD 424.32 million by 2032, at a CAGR of 5.7% during the forecast period. Latin America holds 4% share of the Global Air Suspension Systems Market, with Brazil and Mexico as key contributors. It shows gradual growth driven by the modernization of commercial fleets and increased use of long-distance transport. Governments are encouraging safer and more efficient freight vehicles, creating opportunities for advanced suspension technologies. OEMs are expanding product lines to include air suspension options in mid-range trucks and buses. Market expansion remains limited by cost sensitivity and lack of aftermarket support in some areas. Still, rising demand for durability and load stability supports future adoption.
The Middle East Air Suspension Systems Market size was valued at USD 115.57 million in 2018 to USD 167.79 million in 2024 and is anticipated to reach USD 267.39 million by 2032, at a CAGR of 5.4% during the forecast period. The Middle East contributes 3% to the Global Air Suspension Systems Market, supported by commercial vehicle demand in logistics and oilfield transport. Countries like Saudi Arabia and the UAE lead adoption due to their robust construction and infrastructure sectors. It supports smooth operations over varied terrains and under extreme temperatures, which are common across the region. Luxury SUV adoption also boosts demand for advanced ride control systems. OEMs are collaborating with local partners to offer vehicles equipped with air suspension tailored for desert and off-road conditions. Growth is steady but constrained by limited local manufacturing capacity.
The Africa Air Suspension Systems Market size was valued at USD 45.29 million in 2018 to USD 80.69 million in 2024 and is anticipated to reach USD 111.82 million by 2032, at a CAGR of 3.6% during the forecast period. Africa accounts for 2% of the Global Air Suspension Systems Market and represents an emerging opportunity. South Africa remains the primary market due to its relatively mature automotive sector and fleet modernization initiatives. Demand for air suspension is mainly centered in the commercial vehicle segment, particularly in mining, logistics, and long-haul transportation. It offers operational benefits such as reduced maintenance and improved load handling. Limited awareness, high import costs, and lack of technical support hinder faster adoption. However, infrastructure investment and regional trade initiatives may support gradual growth in air suspension deployment.
Key Player Analysis:
- Continental AG
- Thyssenkrupp AG
- Hendrickson USA, L.L.C.
- ZF Friedrichshafen AG
- Wabco Holdings Inc. (ZF)
- Air Lift Company
- Firestone Industrial Products Company, LLC
- Dunlop Systems and Components
- Hitachi Automotive Systems, Ltd.
- Mando Corporation
Competitive Analysis:
The Global Air Suspension Systems Market features a mix of established players and emerging companies competing on innovation, quality, and cost efficiency. Leading manufacturers such as Continental AG, SAF-Holland, Hendrickson, WABCO, Firestone Industrial Products, and Thyssenkrupp AG dominate with extensive product portfolios and strong OEM partnerships. It sees continuous investment in electronically controlled systems and lightweight materials to align with evolving vehicle technologies. Companies focus on expanding manufacturing capacity and regional presence to meet rising demand across Asia Pacific, North America, and Europe. Strategic collaborations, mergers, and acquisitions help key players enhance their technological capabilities and customer base. The aftermarket segment remains highly competitive, driven by performance upgrades and customization trends. New entrants face challenges in terms of regulatory compliance, reliability assurance, and pricing pressure. The market favors suppliers that offer scalable, durable, and smart air suspension solutions tailored to both passenger and commercial vehicle platforms.
Recent Developments:
- In May 2025, Air Lift Companylaunched a new LoadLifter air suspension kit with air spring cradles specifically designed for the 2020–2025 Jeep Gladiator 4WD. This kit is engineered to improve vehicle leveling and ride quality during towing or hauling, addressing issues like squat and unresponsive steering, and is tailored for off-road and overlanding applications
- In April 2025, Continental AGannounced a major transformation by introducing its new brand, Aumovio, following the planned spin-off of its Automotive Group Sector. The new brand, officially unveiled at Auto Shanghai 2025, will focus on innovative electronic products and mobility solutions, emphasizing safety, connectivity, and autonomous technologies.
- In March 2025, Link Manufacturing unveiled RespondAir, a heavy‑duty rear air suspension system designed specifically for fire and rescue vehicles. The company introduced this non‑torque‑reactive platform at FDIC International 2025. It features larger rubber bushings, V‑Rod configuration, and rapid air‑dump functionality for easier station access. OEM availability is scheduled for late 2025, and Link backs it with an industry‑leading structural and wear warranty
- In March 2024, Hendrickson USA, L.L.C. launched ROADMAAX® Z, its lightest 46,000 lb. capacity rear air suspension system for trucks and tractors. The new system features Zero Maintenance Damping® technology, designed to enhance ride quality while minimizing maintenance requirements. This innovation reinforces Hendrickson’s commitment to delivering advanced suspension solutions tailored for heavy-duty commercial vehicles.
Market Concentration & Characteristics:
The Global Air Suspension Systems Market exhibits a moderately concentrated structure, with a few dominant players holding significant market share across OEM and aftermarket channels. It is characterized by high entry barriers due to technical complexity, stringent quality standards, and the need for strong OEM relationships. The market favors vertically integrated suppliers with capabilities in design, electronics, and manufacturing. It relies heavily on innovation in electronically controlled systems and lightweight materials to meet evolving performance and efficiency standards. Product differentiation, cost competitiveness, and regional customization define the competitive dynamics. The market also reflects strong demand from premium vehicle segments and commercial applications, driving consistent innovation and strategic partnerships among key players.
Report Coverage:
The research report offers an in-depth analysis based on component, technology, vehicle type, and sales channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for electronically controlled air suspension systems will grow with the rise of autonomous and connected vehicles.
- Integration of predictive maintenance features will enhance adoption in commercial and fleet applications.
- Expansion of electric vehicle production will increase the need for adaptive suspension technologies.
- OEMs will focus on modular suspension platforms to reduce costs and simplify integration across models.
- Asia Pacific will continue to lead in volume, driven by rapid urbanization and logistics growth.
- Luxury vehicle manufacturers will increasingly offer air suspension as standard across premium models.
- Investment in lightweight materials will support compliance with global emission and efficiency standards.
- Aftermarket upgrades and retrofitting solutions will gain popularity among performance-focused users.
- Strategic partnerships between component suppliers and automakers will accelerate product innovation.
- Regulatory support for safer and more efficient transport will continue to shape market demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Air Suspension Market?
What factors are driving the growth of the Air Suspension Market?
What are the key segments within the Air Suspension Market?
What are some challenges faced by the Air Suspension Market?
Who are the major players in the Air Suspension Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Air Suspension Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Air Suspension Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 3,700.49 million → 2032: USD 10,771.63 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Air Suspension Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Air Suspension Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Air Suspension Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Air Suspension Market Drivers
- 3.3 Air Suspension Market Restraints & Challenges
- 3.4 Air Suspension Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Air Suspension Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Air Suspension Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Air Suspension category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Air Suspension Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Air Suspension Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Air Suspension market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Air Suspension Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Air Suspension Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Air Suspension Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Air Suspension (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Air Suspension Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Air Suspension Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Air Suspension Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Air Suspension Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Air Suspension Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Air Suspension Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Air Suspension Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Air Suspension Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Air Suspension Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
