
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aspirin Drug Market Size 2024 | USD 1,907.17 million |
| Aspirin Drug Market, CAGR | 3.23% |
| Aspirin Drug Market Size 2032 | USD 2,506.47 million |
Market Overview
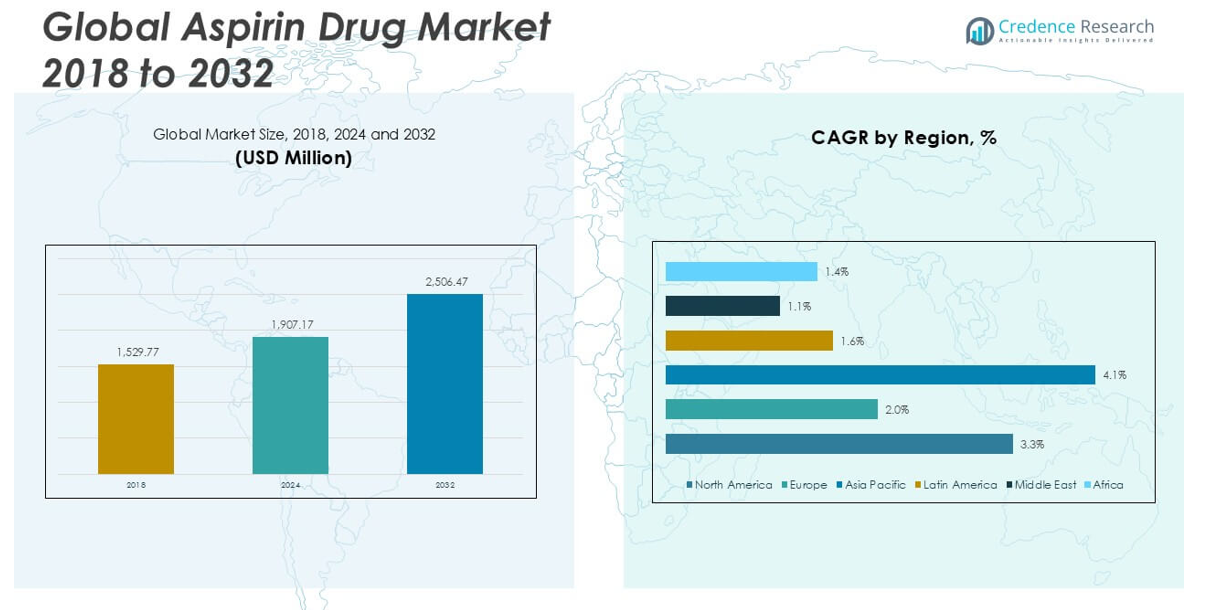
The Aspirin Drug Market size was valued at USD 1,529.77 million in 2018, reached USD 1,907.17 million in 2024, and is anticipated to reach USD 2,506.47 million by 2032, at a CAGR of 3.23% during the forecast period.
The aspirin drug market is led by key players such as Bayer AG, Allegiant Health, Perrigo Company plc., Cardinal Health, Par Pharmaceutical, Bal Pharma Limited, Trumac Healthcare, Globela Pharma Pvt Ltd, JQC (Huayin) Pharmaceutical Co., Ltd., and Nanjing Pharmaceutical Factory Co., Ltd. Bayer AG holds a significant competitive edge due to its well-established brand and global reach. These companies focus on expanding their product portfolios, enhancing formulations, and strengthening distribution networks to maintain market positions. Asia Pacific dominates the global market with a 37.7% share in 2024, driven by growing healthcare awareness and increasing cardiovascular disease prevalence. North America follows, supported by strong preventive healthcare adoption and high over-the-counter aspirin consumption.
Market Insights
- The global aspirin drug market was valued at USD 2.09 billion in 2024 and is projected to grow at a CAGR of 3.1% to reach USD 2.71 billion by 2032; Asia Pacific holds the largest regional share of 37.7%, while the tablet segment dominates by dosage form.
- Market growth is primarily driven by the rising prevalence of cardiovascular diseases, increasing adoption of preventive therapies, and expanding over-the-counter availability worldwide.
- Key trends include the growing demand for low-dose and controlled-release formulations, along with increasing aspirin consumption in emerging markets due to improved healthcare access.
- The competitive landscape is moderately fragmented, with major players like Bayer AG, Cardinal Health, and Perrigo focusing on product innovation, distribution expansion, and strategic partnerships to strengthen their market presence.
- The market faces restraints due to the risk of gastrointestinal complications, restricted pediatric usage, and competition from safer alternative therapies like acetaminophen and ibuprofen.
Market Segmentation Analysis:
By Dosage Form:
The tablet segment dominates the aspirin drug market, accounting for the largest market share due to its widespread availability, ease of administration, and patient preference. Tablets are commonly prescribed for pain relief, fever reduction, and cardiovascular disease prevention, which significantly drives their demand. Capsules and injections hold smaller shares, primarily used for patients with specific medical needs or those requiring rapid drug action. Suppositories occupy a niche segment, typically used when oral administration is not feasible. The dominance of tablets is reinforced by their cost-effectiveness and long shelf life.
- For instance, Bayer AG manufactures over 30 billion aspirin tablets annually at its Bitterfeld plant in Germany, highlighting the scale and reliability of tablet production.
By Route of Administration:
The oral segment holds the largest share in the aspirin drug market, driven by its convenience, non-invasive delivery, and suitability for both acute and chronic treatments. Oral aspirin, particularly in tablet form, is widely used for cardiovascular prophylaxis and common pain management, contributing to its high adoption rate. The rectal and parenteral routes represent smaller portions of the market, typically reserved for hospital settings or patients unable to take medications orally. The dominance of oral administration is supported by its accessibility, ease of dosing, and broad acceptance across healthcare providers.
- For instance, Perrigo Company plc. produces over 8 billion doses of oral aspirin annually across its manufacturing facilities in the United States, ensuring high-volume supply to meet market demand.
By Age Group:
The adult segment leads the aspirin drug market, capturing the highest market share, primarily due to the prevalent use of aspirin in managing cardiovascular conditions, arthritis, and general pain relief in adult populations. Increased incidence of heart-related disorders and the widespread recommendation of low-dose aspirin for heart attack and stroke prevention significantly drive this segment. The pediatric segment holds a limited market share, as aspirin use in children is generally restricted due to the risk of Reye's syndrome. Adult-centric applications and strong clinical guidelines support the dominance of this age group.
Market Overview
Increasing Cardiovascular Disease Prevalence
The rising global burden of cardiovascular diseases (CVDs) serves as a major growth driver for the aspirin drug market. Aspirin is widely recommended for the prevention of heart attacks and strokes, particularly among high-risk patients. Growing awareness of aspirin’s cardioprotective benefits, coupled with an aging population more susceptible to CVDs, continues to fuel demand. Preventive healthcare initiatives and physician-endorsed low-dose aspirin therapy further strengthen the market's expansion, making cardiovascular applications a critical contributor to long-term growth.
- For instance, Allegiant Health supplies over 500 million low-dose aspirin tablets per year specifically for cardiovascular disease prevention through its cardiovascular product line.
Growing Use in Pain and Inflammation Management
Aspirin’s extensive use as an over-the-counter (OTC) analgesic for treating mild to moderate pain, fever, and inflammatory conditions significantly drives market growth. Its affordability, ease of access, and well-established safety profile encourage both self-medication and physician prescriptions. The demand is particularly strong for managing conditions such as headaches, arthritis, and musculoskeletal pain. This broad therapeutic application, combined with increasing consumer preference for OTC solutions, supports the market’s continuous expansion across both developed and emerging regions.
- For instance, Cardinal Health distributes more than 400 million units of OTC aspirin-based pain relief products annually across North America.
Expansion of Preventive Medicine Practices
The increasing adoption of preventive medicine globally boosts the aspirin drug market as it plays a pivotal role in prophylactic treatments. Physicians frequently prescribe low-dose aspirin to individuals at risk of thrombotic events, reflecting a growing focus on disease prevention over treatment. This shift is further reinforced by supportive clinical guidelines and the availability of aspirin in low-dose, daily regimens. The preventive medicine trend, particularly in aging demographics and populations with lifestyle-related risks, continues to create sustained demand for aspirin-based therapies.
Key Trends & Opportunities
Shift Towards Low-Dose and Controlled-Release Formulations
There is a growing trend toward the development of low-dose and controlled-release aspirin formulations to minimize gastrointestinal side effects while maintaining therapeutic efficacy. These advanced formulations improve patient compliance and are gaining significant traction in chronic preventive therapies, especially for cardiovascular diseases. Pharmaceutical companies are increasingly investing in safer and more effective delivery systems, presenting a key opportunity to differentiate products and capture market share in an otherwise mature segment.
- For instance, Bal Pharma Limited has introduced controlled-release aspirin formulations with 12-hour release profiles and currently manufactures over 150 million such tablets annually for both domestic and export markets.
Rising Demand in Emerging Economies
The aspirin drug market is witnessing considerable growth potential in emerging economies due to increasing healthcare awareness, rising disposable incomes, and improved access to OTC medications. Expansion of retail pharmacy chains and government initiatives to promote cardiovascular health are also driving aspirin consumption in these regions. Emerging markets present an attractive opportunity for manufacturers to introduce affordable, mass-market aspirin products, capitalizing on the growing need for accessible preventive and pain management therapies.
- For instance, Trumac Healthcare supplies over 200 million aspirin tablets annually to India, Bangladesh, and African countries through its extensive retail pharmacy partnerships and government health programs
Key Challenges
Risk of Gastrointestinal Complications
One of the major challenges limiting aspirin’s use is its well-documented risk of gastrointestinal (GI) complications, including ulcers and bleeding, especially with long-term or high-dose use. These side effects can deter both physicians and patients from recommending or using aspirin, particularly when safer alternatives are available. Addressing these safety concerns remains critical for market players, necessitating continuous development of gastroprotective formulations and clear patient education on risk management.
Restricted Pediatric Use
The limited application of aspirin in the pediatric population, due to the risk of Reye’s syndrome, significantly constrains market expansion. Regulatory restrictions and strict clinical guidelines discourage aspirin use among children, limiting the drug’s potential in pediatric pain and fever management. This restriction narrows the target demographic and reinforces the need for alternative medications in the pediatric space, thereby capping growth opportunities within this segment.
Availability of Alternative Therapies
The increasing availability of alternative drugs, such as acetaminophen, ibuprofen, and newer anticoagulants, poses a challenge to the aspirin market. These alternatives often offer similar therapeutic benefits with lower risks of gastrointestinal side effects, leading to shifts in physician and patient preferences. The competition from such substitutes may restrict aspirin’s growth potential, especially in pain management and cardiovascular prevention where newer drugs are gaining clinical favor.
Regional Analysis
North America
North America holds a significant position in the global aspirin drug market, accounting for approximately 28.5% of the market share in 2024, with a market size of USD 596.57 million, up from USD 485.46 million in 2018. The region is projected to grow at a CAGR of 3.3% through 2032, reaching USD 787.04 million. This growth is driven by the high prevalence of cardiovascular diseases, strong adoption of preventive healthcare, and widespread over-the-counter aspirin availability. Favorable clinical guidelines and a mature healthcare infrastructure continue to support consistent demand across the region.
Europe
Europe contributes around 16.0% to the global aspirin drug market in 2024, with a market size of USD 335.88 million, rising from USD 285.06 million in 2018. The region is expected to grow at a moderate CAGR of 2.0%, reaching USD 401.32 million by 2032. Growth in Europe is supported by an aging population and the increasing use of aspirin in cardiovascular disease prevention. However, market expansion is relatively steady due to mature healthcare systems and the availability of alternative therapies. The strong regulatory framework ensures consistent, though measured, market development.
Asia Pacific
Asia Pacific leads the global aspirin drug market with the largest share of approximately 37.7% in 2024, driven by a robust market size of USD 788.78 million, up from USD 608.01 million in 2018. The region is forecast to grow at the fastest CAGR of 4.1%, reaching USD 1,105.92 million by 2032. Rapid urbanization, growing healthcare awareness, and increasing cardiovascular disease prevalence in countries like China and India significantly propel market growth. Expanding access to over-the-counter drugs and government health initiatives further enhance aspirin consumption across the region.
Latin America
Latin America holds a modest share of around 4.1% in the global aspirin drug market in 2024, with a market size of USD 85.27 million, increasing from USD 69.30 million in 2018. The market is projected to grow at a CAGR of 1.6%, reaching USD 98.64 million by 2032. Growth in this region is driven by improving healthcare access, rising self-medication practices, and a growing focus on preventive care. However, limited healthcare infrastructure in some countries and the slow pace of regulatory advancements may constrain faster market penetration.
Middle East
he Middle East accounts for approximately 2.4% of the aspirin drug market in 2024, with a market value of USD 49.67 million, up from USD 43.52 million in 2018. The region is expected to expand at a CAGR of 1.1%, reaching USD 55.25 million by 2032. Growth is supported by increasing cardiovascular disease awareness and gradual improvements in healthcare systems. However, aspirin consumption remains relatively low compared to more developed regions, with market expansion primarily limited by restricted over-the-counter access and comparatively smaller healthcare budgets.
Africa
Africa represents about 2.4% of the global aspirin drug market in 2024, with a market size of USD 51.00 million, rising from USD 38.43 million in 2018. The market is anticipated to grow at a CAGR of 1.4%, reaching USD 58.30 million by 2032. Growth in Africa is driven by expanding healthcare access, increased over-the-counter drug availability, and improving public health awareness. Despite these positive trends, market growth is somewhat restrained by economic limitations, underdeveloped healthcare infrastructure, and lower awareness regarding aspirin’s preventive cardiovascular benefits in several regions.
Market Segmentations:
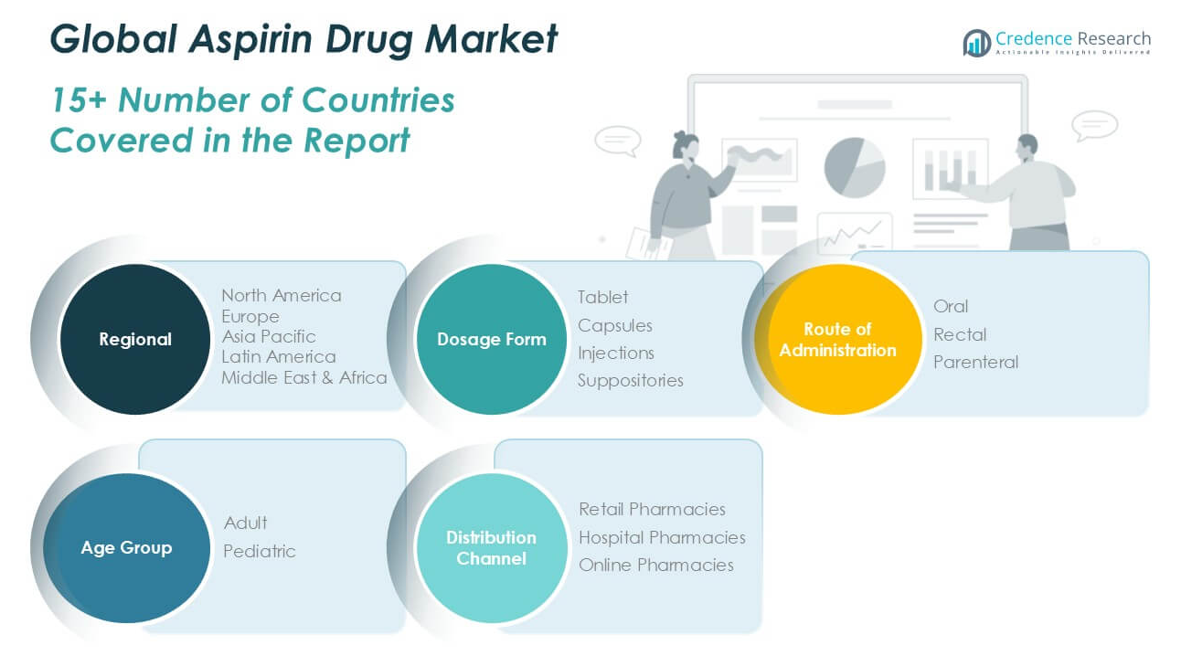
By Dosage Form
- Tablet
- Capsules
- Injections
- Suppositories
By Route of Administration
- Oral
- Rectal
- Parenteral
By Age Group
- Adult
- Pediatric
By Distribution Channel
- Retail Pharmacies
- Hospital Pharmacies
- Online Pharmacies
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The aspirin drug market is moderately fragmented, with the presence of several key players competing on product quality, pricing, and geographic reach. Leading companies such as Bayer AG, Perrigo Company plc., and Cardinal Health maintain strong market positions through their extensive product portfolios, well-established distribution networks, and consistent investments in research and development. These players focus on enhancing formulations, such as low-dose and enteric-coated aspirin, to improve patient safety and compliance. Regional manufacturers like Bal Pharma Limited, Trumac Healthcare, and Globela Pharma Pvt Ltd also contribute significantly, especially in price-sensitive markets across Asia Pacific and Latin America. Strategic initiatives, including mergers, acquisitions, product launches, and geographic expansion, are frequently adopted to strengthen market presence and gain competitive advantage. Additionally, partnerships with healthcare providers and retail pharmacies support wider accessibility. However, the market faces increasing competition from alternative analgesics and anticoagulants, prompting aspirin manufacturers to focus on innovation and differentiation strategies.
Key Player Analysis
- Allegiant Health
- Bayer AG
- Bal Pharma Limited
- Cardinal Health
- Par Pharmaceutical
- JQC (Huayin) Pharmaceutical Co., Ltd.
- Perrigo Company plc.
- Nanjing Pharmaceutical Factory Co., Ltd.
- Trumac Healthcare
- Globela Pharma Pvt Ltd
Recent Developments
- In February 2025, Boryung launched Rebetrix Capsules a combination of aspirin and rabeprazole, designed to reduce gastrointestinal bleeding risks associated with aspirin use through the protective effects of rabeprazole
- In February 2025, on the occasion of Bayer’s 125th anniversary of the aspirin discovery, Bayers focused and developed innovative approaches to cardiovascular health, and aimed to increase access to personalized care and prevent cardiovascular disease. This research emphasized viewing cardiovascular risk as a continuum and using affordable tools such as Carotid Ultrasound to assess individual risk, enhancing treatment options of aspirin. This research was supported by a Bayer grant.
- In January 2025, Preeclampsia Foundation in partnership with Patients & Purpose introduced GAP SPIRIN, an evidence-based education campaign promoting the use of low-dose aspirin to prevent preeclampsia and address maternal health disparities
- In November 2023, Janssen presented new data at the American Heart Association's (AHA) 2023 Scientific Sessions, highlighting that combining XARELTO with aspirin can help reduce critical cardiovascular and adverse limb events
- In March 2023, the FDA approved Plx Pharma Inc.’S Sndas for Vazalore 325 mg and 81 mg, a liquid-filled aspirin capsule intended for patients with vascular disease and diabetes
Market Concentration & Characteristics
The Aspirin Drug Market demonstrates moderate market concentration, with a mix of global and regional players competing across diverse geographies. It is characterized by a high degree of product standardization, which limits differentiation based on formulation alone. Leading companies focus on brand strength, pricing strategies, and distribution efficiency to maintain competitive advantage. The market supports significant over-the-counter sales, making accessibility and affordability critical factors driving consumer preference. Prescription-based use remains essential in preventive cardiovascular care, particularly in developed regions. Competitive pressures from alternative analgesics and anticoagulants influence pricing dynamics and strategic positioning. Companies actively pursue geographic expansion and product portfolio enhancement to strengthen their market share. The presence of stringent regulatory frameworks in several countries emphasizes safety and quality compliance, shaping product development and approval pathways. Demand for low-dose and gastroprotective formulations continues to increase, supported by the growing need for long-term use in cardiovascular applications. The market remains sensitive to public health guidelines, medical community recommendations, and consumer awareness, all of which impact product uptake.
Report Coverage
The research report offers an in-depth analysis based on Dosage Form, Route of Administration, Age Group, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The aspirin drug market is expected to witness steady growth driven by the increasing prevalence of cardiovascular diseases worldwide.
- Rising adoption of low-dose aspirin for preventive care will continue to support long-term market expansion.
- The demand for over-the-counter aspirin products will grow due to increasing self-medication practices and consumer health awareness.
- Emerging economies will offer significant growth opportunities with improving healthcare access and expanding retail pharmacy networks.
- Development of gastroprotective and controlled-release formulations will attract more consumers seeking safer long-term options.
- Competition from alternative pain relievers and anticoagulants may challenge aspirin’s market share in key therapeutic areas.
- Expansion of preventive healthcare guidelines endorsing aspirin use will strengthen its role in chronic disease management.
- Regulatory scrutiny and updated clinical recommendations may influence prescribing patterns and product approvals.
- Strategic collaborations and product diversification will be key focus areas for companies to sustain competitive advantage.
- Increasing patient education and awareness campaigns will likely enhance the adoption of aspirin for both acute and preventive treatments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aspirin Drug Market?
What are the key segments within the Aspirin Drug Market?
What are some challenges faced by the Aspirin Drug Market?
Who are the major players in the Aspirin Drug Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aspirin Drug Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aspirin Drug Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,907.17 million → forecast year: USD 2,506.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aspirin Drug Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aspirin Drug Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aspirin Drug Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aspirin Drug Market Drivers
- 3.3 Aspirin Drug Market Restraints & Challenges
- 3.4 Aspirin Drug Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aspirin Drug Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aspirin Drug Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aspirin Drug category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aspirin Drug Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aspirin Drug Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aspirin Drug market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aspirin Drug Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aspirin Drug Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aspirin Drug Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aspirin Drug (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aspirin Drug Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aspirin Drug Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aspirin Drug Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aspirin Drug Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aspirin Drug Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aspirin Drug Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aspirin Drug Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aspirin Drug Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aspirin Drug Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
