
Market Overview:
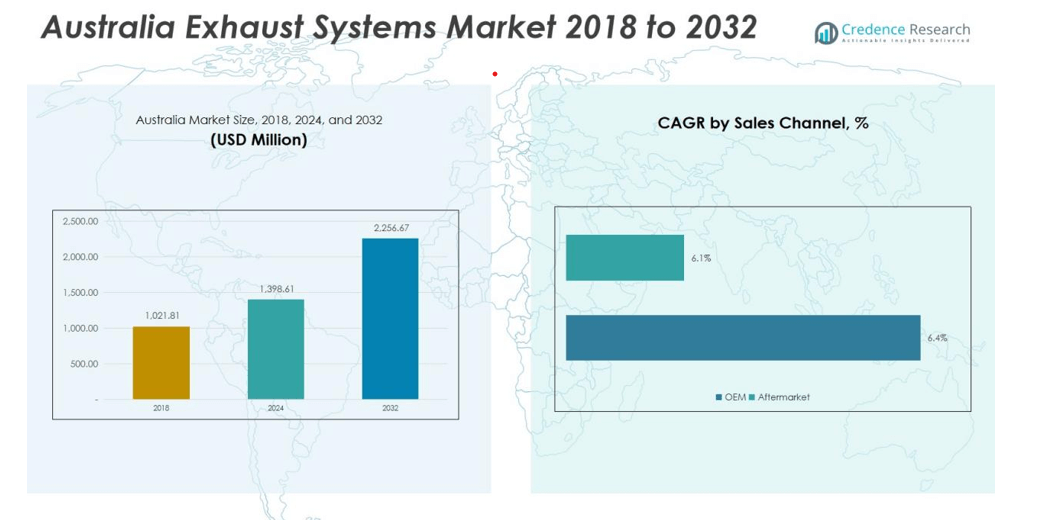
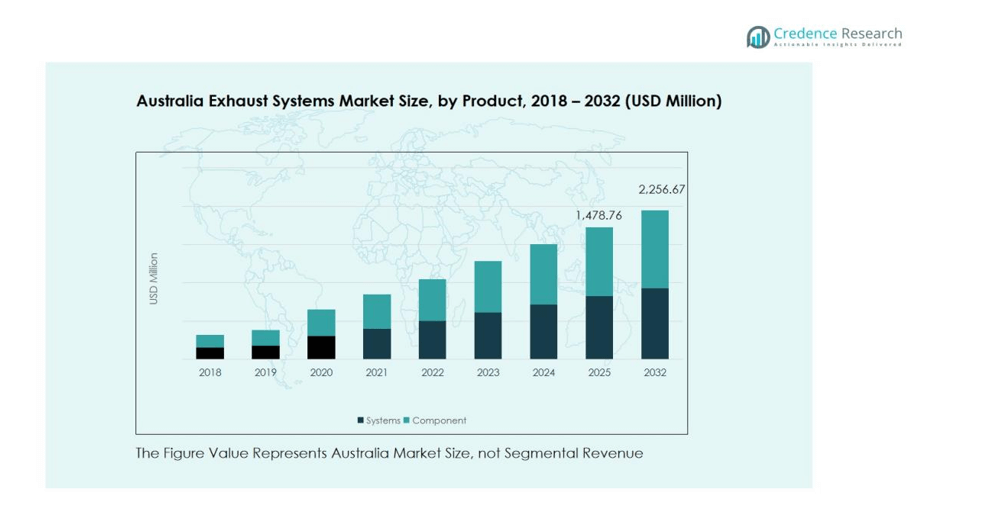
The Australia Exhaust Systems Market size was valued at USD 1,021.81 million in 2018 to USD 1,398.61 million in 2024 and is anticipated to reach USD 2,256.67 million by 2032, at a CAGR of 5.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Exhaust Systems Market Size 2024 | USD 1,398.61 million |
| Australia Exhaust Systems Market, CAGR | 5.8% |
| Australia Exhaust Systems Market Size 2032 | USD 2,256.67 million |
The market growth is primarily driven by stricter emission norms under Australian Design Rules (ADR) and rising consumer demand for eco-friendly and fuel-efficient vehicles. Continuous innovation by manufacturers in selective catalytic reduction (SCR), diesel particulate filters (DPF), and exhaust gas recirculation (EGR) technologies is enhancing system performance and reducing harmful emissions. Furthermore, the ongoing transition toward hybrid and electric vehicles is encouraging the integration of advanced exhaust thermal management systems.
Regionally, New South Wales and Victoria represent major demand centers due to their high vehicle density and active automotive aftermarket sectors. Queensland and Western Australia are emerging markets supported by expanding logistics and mining vehicle fleets. Increasing investments in sustainable transport infrastructure and stricter environmental compliance standards are further strengthening the exhaust systems market across Australia.
Market Insights:
- The Australia Exhaust Systems Market was valued at USD 1,021.81 million in 2018, reaching USD 1,398.61 million in 2024, and projected to hit USD 2,256.67 million by 2032, registering a CAGR of 5.8%.
- New South Wales holds around 34% of the market, followed by Victoria at 28% and Queensland at 18%, driven by dense vehicle populations, strong aftermarket networks, and strict emission standards.
- Western Australia is the fastest-growing region with a 7% share, supported by expanding logistics, mining fleets, and rising adoption of hybrid and low-emission vehicles.
- By product type, catalytic converters account for nearly 32% of the market share due to their essential role in meeting ADR emission norms.
- Passenger vehicles dominate the vehicle segment with a 55% share, reflecting high urban mobility and replacement demand for efficient, lightweight exhaust systems.
Market Drivers:
Stringent Emission Regulations Driving Advanced Exhaust Technologies
The Australia Exhaust Systems Market is growing due to the enforcement of strict emission standards under the Australian Design Rules (ADR). These regulations require automakers to reduce harmful gases such as nitrogen oxides and carbon monoxide. Manufacturers are developing selective catalytic reduction (SCR) and diesel particulate filter (DPF) systems to meet compliance. It promotes cleaner combustion and enhanced fuel efficiency across vehicle segments. The shift toward low-emission technologies is encouraging OEMs to invest in continuous exhaust innovation.
- For instance, Hino Australia introduced its 500 Series Standard Cab trucks meeting Japan's post Post New Long Term (pPNLT) emissions standard equivalent to Euro 6, featuring both SCR and DPR systems that convert nitrogen oxides into nitrogen and water while filtering particulate matter.
Rising Vehicle Production and Expanding Aftermarket Demand
Steady growth in vehicle production and the expanding automotive aftermarket are strengthening the Australia Exhaust Systems Market. High demand for passenger and light commercial vehicles drives replacement and upgrade cycles for exhaust components. Increasing consumer awareness about fuel economy and noise reduction enhances adoption of performance exhaust systems. Local manufacturers and distributors benefit from the need for timely replacements due to harsh road and climate conditions. It creates continuous revenue opportunities for OEMs and service providers.
- For instance, Swift Industries expanded its aftermarket exhaust product portfolio to 19,000 product lines, featuring advanced catalytic converters and Diesel Particulate Filters, positioning the company to serve diverse replacement needs across Australia's automotive sector
Growing Adoption of Hybrid and Fuel-Efficient Vehicles
Hybrid and fuel-efficient vehicle adoption is reshaping the Australia Exhaust Systems Market. Automakers are integrating compact, lightweight, and thermally optimized exhaust systems to support new powertrains. These designs improve performance while reducing emissions and engine heat. It strengthens compliance with national sustainability goals and supports fuel economy standards. Continuous R&D investment in hybrid-compatible exhaust systems drives competitive differentiation among suppliers.
Technological Advancements and Material Innovation
Advancements in exhaust materials and design innovation are boosting market competitiveness. The use of stainless steel, titanium, and composite alloys improves durability and reduces weight. It enhances corrosion resistance, crucial for Australia’s diverse weather conditions. Automation and precision manufacturing are improving production efficiency and design consistency. The adoption of smart sensors and advanced coatings further increases the performance and lifespan of exhaust systems.
Market Trends:
Increasing Focus on Lightweight Materials and Emission Efficiency
The Australia Exhaust Systems Market is witnessing a strong shift toward lightweight materials to improve efficiency and durability. Manufacturers are replacing conventional steel with stainless steel, titanium, and composite alloys to reduce vehicle weight and fuel consumption. The demand for high-temperature and corrosion-resistant materials is increasing due to Australia’s diverse climate and long-distance driving conditions. It encourages OEMs to integrate advanced thermal coatings and modular designs for extended component life. These innovations support compliance with emission standards while enhancing overall performance and fuel economy.
- For instance, Vandemon Performance in Australia offers titanium exhaust headers for the Suzuki GSX-8S that are approximately 45 percent lighter than stainless steel, dissipating heat twice as fast and featuring superior corrosion resistance without requiring polishing.
Integration of Smart Sensors and Electrified Powertrain Compatibility
Smart exhaust sensors and electronic monitoring systems are emerging as key trends in the Australia Exhaust Systems Market. Automakers are embedding advanced sensors for real-time analysis of temperature, pressure, and gas composition to optimize performance. It supports predictive maintenance and helps meet strict emission monitoring standards. The growing adoption of hybrid and plug-in hybrid vehicles also drives demand for compact exhaust systems compatible with electrified powertrains. Manufacturers are designing adaptive exhaust technologies that regulate sound and heat output efficiently. The trend reflects the industry’s broader move toward intelligent, connected, and sustainable automotive solutions.
- For instance, DENSO developed NTC-type exhaust gas temperature sensors that detect temperature ranges from -40 to 1000 degrees Celsius with response times taking less than 7 seconds to transition from room temperature to 1000 degrees Celsius.
Market Challenges Analysis:
High Cost of Advanced Exhaust Technologies and Material Constraints
The Australia Exhaust Systems Market faces rising costs due to the integration of advanced catalytic converters, sensors, and thermal coatings. These technologies require high-grade materials such as titanium and stainless steel, which increase overall production expenses. It creates pricing pressure for manufacturers and limits affordability for cost-sensitive consumers. Supply chain disruptions and fluctuating raw material prices further challenge consistent output. Local manufacturers struggle to balance quality, compliance, and cost efficiency in a highly regulated environment.
Transition Toward Electric Mobility Reducing Traditional Demand
The growing shift toward electric vehicles (EVs) poses a structural challenge to the Australia Exhaust Systems Market. Battery electric vehicles eliminate the need for conventional exhaust systems, directly impacting long-term demand. It compels suppliers to diversify into hybrid-compatible or alternative thermal management solutions. Limited EV infrastructure currently slows the transition, but government incentives may accelerate adoption. Manufacturers must innovate to stay relevant in a gradually electrifying market landscape.
Market Opportunities:
Expansion of Hybrid Vehicle Segment and Aftermarket Growth
The Australia Exhaust Systems Market offers significant growth opportunities in the hybrid vehicle segment. Automakers are integrating compact exhaust systems optimized for hybrid engines to balance efficiency and emission control. It supports ongoing government initiatives promoting cleaner transport technologies. The growing aftermarket sector also provides revenue potential through replacement parts and performance upgrades. Increasing consumer interest in customized exhaust solutions enhances opportunities for local fabricators and service providers.
Adoption of Smart and Lightweight Exhaust Technologies
Rising demand for smart and lightweight exhaust technologies creates strong prospects for innovation. Manufacturers are investing in digital sensors, real-time emission tracking, and advanced coatings to improve system reliability. It aligns with Australia’s environmental goals and encourages sustainable vehicle manufacturing. The trend toward lightweight materials such as aluminum and titanium allows better fuel efficiency and lower carbon footprints. Expanding R&D capabilities and partnerships with global technology suppliers strengthen future opportunities in performance-driven exhaust systems.
Market Segmentation Analysis:
By Product Type
The Australia Exhaust Systems Market includes systems and components such as mufflers, catalytic converters, exhaust pipes, and other accessories. Catalytic converters hold a significant share due to stricter emission norms and rising environmental awareness. Mufflers also show steady demand for their role in noise reduction and improved engine performance. It benefits from technological advancements and material innovations that enhance exhaust efficiency and durability.
- For instance, Hushpak Engineering custom designed a muffler for CAT 793D haul trucks that reduced noise levels to 122 dB, meeting compliance standards while adding less than 450 kg to the vehicle.
By Vehicle Segment
Passenger vehicles dominate the Australia Exhaust Systems Market, driven by strong consumer demand and expanding urban mobility. The commercial vehicle segment follows, supported by logistics and mining fleet operations requiring durable exhaust systems. Two-wheelers hold a smaller yet growing share, supported by the rise in compact urban transportation. It continues to see innovation focused on lightweight and corrosion-resistant materials suited for long-distance driving.
- For Instance, SC-Project introduced a Rally-S titanium muffler for the Benelli TRK 702 in 2024, achieving a greater than 60% reduction in exhaust weight and a performance uplift of 2.5 hp at 7,900 rpm.
By Fuel Type
Gasoline vehicles account for the largest share of the Australia Exhaust Systems Market due to widespread passenger car usage. Diesel vehicles remain important in commercial and heavy-duty applications, relying on selective catalytic reduction (SCR) and diesel particulate filter (DPF) technologies. It reflects Australia’s focus on emission control and fuel efficiency improvement. The gradual transition toward hybrid vehicles is creating scope for hybrid-compatible exhaust solutions.
Segmentations:
By Product Type Segment:
- Systems
- Components
- Mufflers
- Catalytic Converters
- Exhaust Pipes
- Others
By Vehicle Segment:
- Passenger Vehicles
- Commercial Vehicles
- Two-wheelers
By Fuel Type Segment:
- Gasoline
- Diesel
By Sales Channel Segment:
- OEM
- Aftermarket
Regional Analysis:
New South Wales and Victoria Leading Market Growth through Strong Automotive Base
New South Wales and Victoria dominate the Australia Exhaust Systems Market, supported by dense vehicle populations and a strong automotive service network. These regions record the highest demand for exhaust replacement and performance upgrades due to heavy urban traffic and vehicle aging. It benefits from a well-developed aftermarket and large distribution networks catering to passenger and light commercial vehicles. Stringent emission standards and government initiatives promoting cleaner transportation drive continuous system upgrades. Local manufacturing hubs in these states also support innovation in exhaust materials and assembly technologies.
Queensland and Western Australia Emerging with Rising Fleet and Industrial Activity
Queensland and Western Australia show robust market potential driven by growth in mining, logistics, and commercial fleet operations. Demand for durable exhaust systems is high due to harsh terrain and heavy-duty vehicle usage. It encourages manufacturers to develop high-performance systems with superior corrosion resistance and longer operational life. The growing adoption of hybrid and low-emission vehicles in urban centers further supports regional expansion. Local distributors and service centers are enhancing their capacity to meet aftermarket demand effectively.
South Australia and Tasmania Supporting Growth through Aftermarket and Sustainability Initiatives
South Australia and Tasmania contribute steadily to the Australia Exhaust Systems Market through focused sustainability efforts and growing aftermarket demand. Both regions are emphasizing eco-friendly transport solutions aligned with national emission targets. It promotes the integration of advanced exhaust technologies compatible with hybrid and fuel-efficient vehicles. The expanding presence of authorized service networks ensures timely replacement and maintenance of exhaust systems. Continued investments in regional transport infrastructure are expected to enhance long-term market stability.
Key Player Analysis:
- Manta
- Berklee
- MagnaFlow
- Akrapovic
- AP Emissions
- The Axces Group
- BOSAL
- Exhaust Control Industries
- Yutaka Giken Company Limited
- Continental AG
Competitive Analysis:
The Australia Exhaust Systems Market features both global and regional manufacturers competing through innovation and quality. Major players include Manta, Berklee, MagnaFlow, Akrapovic, AP Emissions, The Axces Group, and BOSAL. It is characterized by a mix of local suppliers providing tailored exhaust solutions and international brands offering advanced emission-reduction technologies.
The market competition centers on product performance, noise control, durability, and compliance with emission regulations. Companies are focusing on lightweight materials and precision engineering to meet fuel efficiency standards and sustainability goals. Strategic partnerships with automotive OEMs and aftermarket distributors strengthen distribution networks and brand visibility. Price competitiveness and customization capabilities are key differentiators among domestic producers. Continuous R&D investment supports innovation in catalytic converters, mufflers, and particulate filters, helping companies maintain an edge in the evolving regulatory and performance-driven automotive landscape.
Recent Developments:
- In March 2025, Manta Aircraft announced continued refinement of its hybrid propulsion system and test benches for avionics and system integration, targeting certification of the ANN 6 as a civil passenger aircraft within 3.5 years through the CAAC.
- In June 2025, Akrapovic introduced a titanium exhaust system for the 2025 BMW M5 (G90 sedan and G99 wagon), improving engine output by 7.1 horsepower and reducing overall vehicle weight by 6.1 kilograms while enhancing the vehicle’s sound profile.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Vehicle, Fuel Type and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Australia Exhaust Systems Market will witness strong growth driven by tightening emission norms and fuel efficiency goals.
- Manufacturers will increase the use of lightweight stainless steel, titanium, and composite materials to reduce vehicle weight.
- Demand for hybrid and electric vehicle-compatible exhaust systems will expand as automakers transition toward cleaner technologies.
- It will see more investment in advanced catalytic converter technologies to achieve lower carbon and nitrogen oxide emissions.
- Smart exhaust monitoring systems using sensors and onboard diagnostics will become more common in premium vehicles.
- Aftermarket upgrades and performance exhaust products will attract enthusiasts seeking higher efficiency and enhanced sound.
- Local manufacturers will collaborate with global OEMs to strengthen supply chains and production capabilities.
- Sustainability initiatives will push suppliers to adopt recyclable materials and cleaner production processes.
- Growing infrastructure and logistics sectors will drive steady demand for exhaust systems in commercial vehicles.
- Digital design tools and 3D manufacturing will enable faster product customization and improved thermal management.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Australia Exhaust Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Exhaust Systems Market projected to grow between 2024 and 2032?
Which market segment held the largest share in the Australia Exhaust Systems Market in 2024?
What are the primary factors fueling the growth of the Australia Exhaust Systems Market?
Who are the leading companies in the Australia Exhaust Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,021.81 million → 2032: USD 2,256.67 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Exhaust Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Exhaust Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Exhaust Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Exhaust Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Exhaust Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Exhaust Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Exhaust Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Exhaust Systems Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,021.81 million → 2032: USD 2,256.67 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Exhaust Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Exhaust Systems Geographic Market Outlook, 2018-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2018-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Exhaust Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Exhaust Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

