
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Authentication solutions market Size 2023 | USD 19338 Million |
| Authentication solutions market , CAGR | 14.6 % |
| Authentication solutions market Size 2032 | USD 57529.2 Million |
Market Overview:
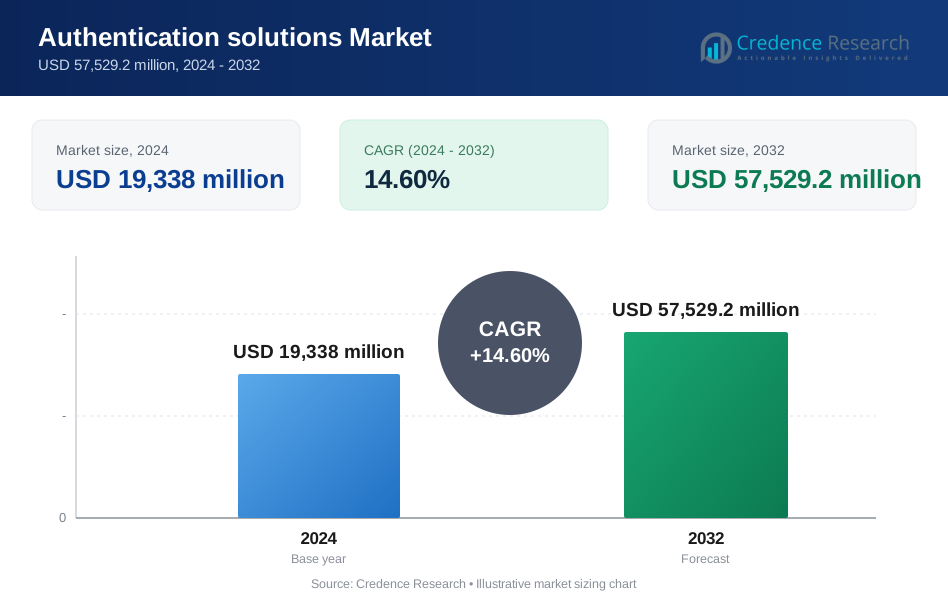
Authentication solutions market size was valued at USD 19338 million in 2024 and is anticipated to reach USD 57529.2 million by 2032, at a CAGR of 14.6 % during the forecast period (2024-2032).
Several factors are fueling the adoption of advanced authentication solutions. The rapid growth of e-commerce, digital banking, and remote work has heightened exposure to cyberattacks and identity theft, compelling organizations to invest in robust access controls. Regulatory mandates such as GDPR, PSD2, and CCPA are further compelling enterprises to strengthen authentication processes for customer and employee interactions. Technological advancements—including AI-powered authentication, adaptive authentication, and passwordless access—are enhancing the efficacy and user experience of authentication systems. The proliferation of Internet of Things (IoT) devices and the shift toward zero-trust security models are also broadening the scope of authentication requirements across industries. Organizations are also responding to the increasing sophistication of phishing and credential theft attacks by integrating behavioral biometrics and continuous authentication solutions. Furthermore, the rise of cloud computing and SaaS models is driving the need for secure, scalable authentication frameworks that can protect data across hybrid and multi-cloud environments.
Regionally, leading players such as ManageEngine, Microsoft, and 1Password are shaping the authentication solutions market landscape. North America accounts for the largest share, supported by early adoption of digital technologies, a mature cybersecurity ecosystem, and stringent data protection regulations. Europe follows closely, propelled by comprehensive regulatory initiatives and a heightened focus on privacy compliance, which further accelerates the adoption of advanced authentication solutions across sectors.The Asia Pacific region is poised for the fastest growth, fueled by rapid digitization, increasing cybersecurity awareness, and substantial investments in IT infrastructure across emerging economies like India, China, and Southeast Asia. Latin America, the Middle East, and Africa are gradually expanding adoption as digital transformation gains momentum, creating opportunities for authentication solution providers. Regional governments continue to launch initiatives for secure digital identities and financial inclusion, while the rise of local startups and strategic partnerships with global leaders foster innovation and tailored solutions to address region-specific security challenges.
Market Insights:
- The authentication solutions market was valued at USD 19,338 million in 2024 and is projected to reach USD 57,529.2 million by 2032, registering a CAGR of 14.6%.
- Surge in e-commerce, digital banking, and remote work is driving higher demand for advanced authentication technologies.
- Strict regulations like GDPR, PSD2, and CCPA are compelling organizations to deploy multi-factor and biometric authentication for compliance.
- Advances in AI, adaptive authentication, and passwordless methods are enhancing both security and user experience across sectors.
- Increasing IoT adoption and the shift toward zero-trust security models are expanding authentication requirements in new domains.
- Integration complexities and legacy IT systems present significant deployment challenges, especially for large organizations.
- North America leads the market with 36.2% share, while Asia Pacific emerges as the fastest-growing region due to rapid digital transformation and rising security investments.
Market Drivers:
Rising Cybersecurity Threats Across Digital Ecosystems Drive Demand for Authentication Solutions
The rapid escalation of cyber threats has intensified the focus on secure access and identity verification worldwide. With organizations increasingly operating online and the expansion of remote work, the potential for data breaches and identity theft has soared. The Authentication Solutions Market responds to this challenge by enabling organizations to secure digital assets and sensitive information through advanced authentication protocols. High-profile security incidents in banking, healthcare, and government sectors have underscored the critical need for robust solutions. Enterprises seek to minimize business disruptions and financial losses by investing in technology that prevents unauthorized access. Consumer-facing platforms, from e-commerce to mobile banking, rely on these tools to protect both user data and brand reputation.
- For instance, in 2024, Microsoft’s Azure Active Directory blocked over 25.6 billion brute force authentication attacks using advanced risk-based sign-in protocols, as disclosed in the company’s annual Digital Defense Report.
Evolving Regulatory Landscape and Compliance Mandates Accelerate Market Growth
Regulatory compliance is a primary catalyst for the adoption of authentication technologies. Stringent mandates such as GDPR in Europe, CCPA in California, and PSD2 for financial services require organizations to deploy secure and auditable authentication systems. These frameworks hold companies accountable for customer and employee data protection, prompting rapid deployment of multi-factor authentication, biometrics, and risk-based access controls. It is necessary for organizations to align their IT strategies with evolving legal requirements to avoid penalties and maintain trust. Regulatory scrutiny is also driving the implementation of standardized processes and cross-border interoperability, particularly for multinational enterprises. Compliance-related investments now form a significant portion of cybersecurity budgets.
- For instance, in March 2024, Okta processed over 12 billion authentication requests in a single month for its enterprise customers, demonstrating large-scale compliance with new regulatory access requirements.
Proliferation of Digital Transformation and Cloud Adoption Expands Authentication Needs
Digital transformation initiatives are reshaping business models and operational processes in nearly every sector. The transition to cloud-based environments and adoption of SaaS platforms create a pressing need for scalable and flexible authentication solutions. Organizations require seamless user experiences across multiple devices and locations, driving demand for adaptive authentication and password less systems. The Authentication Solutions Market supports these digital ambitions by offering technologies that balance security with usability. Secure access to cloud applications, remote workforces, and third-party integrations relies on identity-centric security. The growing importance of digital trust in customer journeys continues to propel investment in this sector.
Advances in Technology and User Experience Foster Innovation and Market Expansion
Innovation remains central to the evolution of authentication solutions. Breakthroughs in artificial intelligence, machine learning, and behavioral biometrics are enabling more accurate, real-time verification methods. AI-powered authentication can identify anomalies in user behavior, reducing the risk of credential theft or account takeover. Organizations are also focusing on frictionless authentication to enhance the customer experience without compromising security. The integration of mobile biometrics, facial recognition, and voice authentication exemplifies how user-friendly solutions are becoming standard. Investment in research and development is leading to the introduction of customizable and industry-specific offerings, ensuring the market remains dynamic and competitive.
Market Trends:
Widespread Shift Toward Multi-Factor and Password less Authentication Technologies
Organizations are moving beyond traditional password-based systems, driving the adoption of multi-factor authentication (MFA) and password less technologies across industries. The Authentication Solutions Market is seeing rapid integration of biometric methods, such as fingerprint, facial, and voice recognition, to enhance security and improve user experience. Enterprises now prioritize seamless, secure authentication journeys to address consumer demand and regulatory compliance. FIDO2 standards and mobile-based authentication apps are gaining significant traction, enabling users to access services with minimal friction. The convergence of device, behavioral, and contextual factors is leading to more sophisticated, risk-based authentication frameworks. This trend underscores a shift from static credentials to dynamic, user-centric security measures.
- For instance, Microsoft announced in a May 2025 blog that more than 15 billion user accounts worldwide now support passkey-based sign-ins (e.g., Windows Hello or FIDO2 security keys)Growing Role of Artificial Intelligence and Machine Learning in Adaptive Authentication
Artificial intelligence and machine learning have become central to the evolution of adaptive authentication, transforming how organizations detect threats and validate users. The Authentication Solutions Market leverages AI-powered tools to analyze user behavior, device context, and transaction patterns in real time, allowing for dynamic responses to anomalies or suspicious activities. Continuous authentication and behavioral biometrics are emerging as vital components for protecting digital identities, especially in financial services and healthcare. AI-driven analytics enable organizations to detect emerging fraud schemes and prevent credential-based attacks before they escalate. The ongoing integration of advanced analytics with authentication platforms signals a new era of proactive, intelligent security. Organizations recognize the competitive advantage of AI-driven authentication, leading to continued investments in these technologies.
Market Challenges Analysis:
Integration Complexities and Legacy System Limitations Hinder Deployment
Many organizations struggle to implement advanced authentication solutions due to integration challenges with existing IT infrastructure. The Authentication Solutions Market often faces obstacles from legacy systems that lack compatibility with new protocols, making upgrades costly and time-consuming. Disparate platforms and fragmented data environments can create security gaps if not managed effectively. Businesses must invest in specialized expertise to ensure seamless deployment and interoperability, which raises operational costs. The complexity of migrating critical processes without disruption also slows the pace of digital transformation. Organizations that operate across multiple regions encounter additional barriers when aligning systems with diverse regulatory and technical standards.
User Resistance and Balancing Security with Convenience Remain Persistent Issues
End users often resist changes to authentication processes, particularly when new methods increase friction or disrupt established workflows. The market must address concerns about privacy, data sharing, and usability to ensure broad acceptance of advanced solutions. Achieving the right balance between robust security and seamless user experiences continues to challenge providers and enterprises alike. Excessive authentication requirements can result in user fatigue, increased support needs, and reduced productivity. The Authentication Solutions Market must continuously innovate to develop intuitive, low-friction solutions that do not compromise protection. Enterprises risk losing customer trust if they fail to deliver secure yet convenient authentication methods.
Market Opportunities:
Expanding Digital Ecosystems and Emerging Technologies Unlock New Growth Prospects
The accelerating adoption of cloud computing, IoT devices, and digital services across sectors creates significant opportunities for advanced authentication solutions. The Authentication Solutions Market stands to benefit from organizations’ need to secure complex, distributed environments while ensuring compliance with evolving regulations. Demand is surging for scalable, cloud-based authentication platforms that can support remote workforces and global operations. Rapid digitalization in sectors such as healthcare, banking, and e-commerce calls for innovative solutions tailored to industry-specific needs. The expansion of 5G networks and smart city initiatives further drives requirements for identity-centric security measures. Market players that invest in flexible and interoperable authentication technologies can capture growing demand from both large enterprises and SMEs.
Rising Focus on User Experience and Privacy-Enhancing Technologies Presents New Avenues
Organizations are prioritizing user-centric authentication methods to streamline access while addressing privacy concerns and regulatory mandates. The market is well-positioned to introduce password less, biometric, and adaptive authentication solutions that enhance both convenience and security. Growing consumer expectations for seamless digital experiences fuel demand for frictionless verification processes across mobile and web applications. The adoption of privacy-by-design principles and decentralized identity frameworks creates opportunities for solution providers to differentiate offerings. Investments in AI-driven analytics and continuous authentication will enable the market to address emerging threats while supporting evolving business models. Enterprises seeking to improve customer engagement and trust are expected to drive the next wave of innovation in authentication solutions.
Market Segmentation Analysis:
By Authentication Method
The Authentication Solutions Market includes multi-factor authentication, biometrics, password less authentication, smart cards, and behavioral biometrics. Multi-factor authentication leads adoption, driven by rising security concerns and regulatory mandates. Biometrics, especially fingerprint and facial recognition, gain traction due to their convenience and high accuracy in identity verification. Passwordless and behavioral authentication methods are gaining momentum for their ability to deliver a seamless user experience and combat credential-based attacks.
- For instance, Microsoft reported over 100 million users actively utilizing Windows Hello biometric authentication across consumer and enterprise Windows 10 devices in 2024, as documented in Microsoft’s official device usage report.
By Deployment Model
The market is segmented into on-premise and cloud-based authentication solutions. Organizations increasingly favor cloud-based deployment due to its scalability, ease of integration, and cost-effectiveness. It enables businesses to secure remote access and manage digital identities across distributed environments. On-premise solutions remain relevant for enterprises with strict data sovereignty and compliance requirements, particularly in regulated industries.
By Organization Size
The Authentication Solutions Market addresses both large enterprises and small-to-medium-sized enterprises (SMEs). Large enterprises drive demand for comprehensive, scalable authentication frameworks that protect extensive digital ecosystems and critical infrastructure. SMEs, facing similar threats but with limited resources, seek cost-effective, easy-to-deploy solutions that ensure compliance and reduce operational risks. The market continues to innovate across these segments, supporting organizations as they strengthen identity protection in an evolving threat landscape.
- For instance, Duo Security (Cisco) documented that over 36,000 businesses, including SMEs, deployed its multi-factor authentication suite in 2024 according to Cisco’s official product adoption reports.
Segmentations:
By Authentication Method
- Multi-factor Authentication
- Biometrics
- Passwordless Authentication
- Smart Cards
- Behavioral Biometrics
By Deployment Model
- On-premise
- Cloud-based
By Organization Size
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa
Regional Analysis:
North America’s
North America accounted for 36% of the global Authentication Solutions Market in 2024, maintaining its position as the largest regional segment. The region’s advanced digital infrastructure and stringent regulatory mandates drive widespread adoption of multi-factor and biometric authentication technologies. Organizations in the United States and Canada invest heavily in cybersecurity to address rising threats and comply with frameworks such as HIPAA, CCPA, and SOX. Global technology providers and an established innovation ecosystem accelerate product development and deployment. Cloud adoption and the expansion of remote workforces continue to amplify demand for robust authentication solutions. Enterprises across banking, healthcare, government, and retail sectors actively deploy advanced identity management systems. North America’s strong focus on privacy and user experience fosters continuous innovation and sustained market growth.
Europe’s
Europe held a 29% share of the Authentication Solutions Market in 2024, ranking as the second-largest regional market. Stringent data protection regulations such as GDPR and PSD2 compel organizations to implement strong authentication practices for both personal and financial information. Collaboration between public and private sectors promotes adoption of standardized identity management systems and cross-border interoperability. Growing investments in smart cities, fintech, and e-government platforms expand the scope of authentication applications. Europe’s diverse regulatory landscape necessitates adaptable, multilingual authentication frameworks. Innovation hubs in Germany, France, and the UK play a pivotal role in advancing authentication technologies. The region’s sustained investment in digital transformation drives ongoing demand.
Asia Pacific’s
Asia Pacific accounted for 24% of the global Authentication Solutions Market in 2024 and represents the fastest-growing regional segment. Rapid digital transformation across China, India, Japan, and Australia underpins robust investment in cybersecurity infrastructure. The proliferation of smartphones, digital payments, and e-governance services fuels demand for mobile-centric authentication solutions. Governments launch large-scale digital identity and financial inclusion programs, supporting widespread market adoption. The region’s expanding base of small and medium-sized enterprises drives demand for scalable, cost-effective platforms. Collaborations with global technology firms and the rise of local innovators ensure Asia Pacific remains at the forefront of authentication technology advancement.
Latin America
Latin America’s Authentication Solutions Market is advancing with more than 60% of large enterprises deploying multi-factor authentication or biometric solutions to secure operations. Stricter data protection regulations are prompting banks, retailers, and government agencies to prioritize secure access technologies. Technology providers report a double-digit increase in regional solution adoption, supported by local partnerships and tailored service models to address the needs of digitally active populations.
Middle East and Africa
In the Middle East and Africa, over 55% of financial institutions and public sector organizations have implemented advanced authentication systems to safeguard sensitive data and critical infrastructure. Major cities are accelerating digital transformation, driving demand for robust identity management and secure transaction platforms. Regional market expansion is further supported by national cybersecurity initiatives and a rising number of public-private collaborations focused on building digital trust.
Key Player Analysis:
- ManageEngine
- Microsoft
- 1Password
- CyberArk
- SAP
- IBM
- LastPass
- Dashlane
- Identity Automation
Competitive Analysis:
The Authentication Solutions Market features intense competition, with leading players focusing on innovation, scalability, and global reach. Key companies such as Microsoft, IBM, LastPass and Dashlane. Global continuously invest in research and development to deliver advanced authentication technologies. It remains highly dynamic, with providers offering diverse portfolios that include multi-factor authentication, biometrics, adaptive authentication, and risk-based solutions. Strategic acquisitions, partnerships, and product launches enable firms to expand their customer base and strengthen market presence. The rise of cloud computing and digital transformation drives vendors to enhance integration and interoperability across platforms. Start-ups and regional players also contribute to market diversity by introducing specialized solutions tailored to industry-specific requirements. Continuous focus on user experience, compliance, and emerging threats shapes the ongoing evolution of the competitive landscape.
Recent Developments:
- In July 2025, ManageEngine launched MSP Central, a unified platform designed for managed service providers, combining RMM, PSA, AI-driven automation, endpoint protection, and server monitoring in a single console.
- In June 2025, CyberArk launched the CyberArk MSP Hub, an enhanced SaaS-based management console for MSPs, and introduced a refreshed MSP-optimized partner program to enable delivery of converged identity security services.
- In March 2025, Google announced a definitive agreement to acquire Wiz, a leading cloud security platform, for $32 billion in an all-cash transaction.
Market Concentration & Characteristics:
The Authentication Solutions Market demonstrates moderate concentration, with a mix of global technology leaders and specialized regional vendors competing for market share. It features diverse product offerings, including multi-factor authentication, biometrics, and AI-driven identity solutions tailored to various industries. The market values innovation, interoperability, and compliance, prompting providers to focus on seamless integration with legacy and modern IT infrastructures. Rapid digital transformation and evolving regulatory requirements shape product development and competitive strategies. Strategic alliances, acquisitions, and a continuous stream of new technologies define its dynamic nature. The market rewards adaptability, security, and user-centric design, ensuring sustained growth and resilience.
Report Coverage:
The research report offers an in-depth analysis based on Authentication Method, Deployment Model, Organization Size, Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Biometric authentication converges with wearable and mobile technologies to deliver seamless access.
- Zero-trust models expand reliance on continuous and contextual authentication throughout digital ecosystems.
- AI-driven adaptive authentication strengthens real-time risk assessment through continuous monitoring of behavior and context.
- Passwordless experiences gain momentum, shifting user identification toward device-based and biometric credentials.
- Identity orchestration platforms unify multiple authentication methods under a centralized, policy-driven framework.
- Widespread adoption of decentralized identity standards promotes greater user control and interoperability across services.
- IoT security demands increase focus on lightweight, scalable authentication solutions tailored to edge devices.
- Cloud-native and microservices architectures require embedded authentication modules that support dynamic scaling and container environments.
- Regulatory evolution triggers demand for built-in audit trails, analytics, and compliance capabilities within authentication systems.
- Partnerships between traditional cybersecurity providers and fintech startups accelerate innovation and broaden solution portfolios.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Authentication Solutions Market?
What factors are driving the growth of the Authentication Solutions Market?
What are the key segments within the Authentication Solutions Market?
What are some challenges faced by the Authentication Solutions Market?
Who are the major players in the Authentication Solutions Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Authentication solutions Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Authentication solutions Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 19,338 million → 2032: USD 57,529.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Authentication solutions Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Authentication solutions Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Authentication solutions Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Authentication solutions Market Drivers
- 3.3 Authentication solutions Market Restraints & Challenges
- 3.4 Authentication solutions Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Authentication solutions Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Authentication solutions Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Authentication solutions category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Authentication solutions Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Authentication solutions Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Authentication solutions market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Authentication solutions Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Authentication solutions Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Authentication solutions Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Authentication solutions (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Authentication solutions Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Authentication solutions Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Authentication solutions Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Authentication solutions Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Authentication solutions Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Authentication solutions Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Authentication solutions Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Authentication solutions Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Authentication solutions Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
