
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Engineering Services Outsourcing Market Size 2024 | USD 94,382.25 million |
| Automotive Engineering Services Outsourcing Market, CAGR | 11.4% |
| Automotive Engineering Services Outsourcing Market Size 2032 | USD 223,857.6 million |
Market Overview
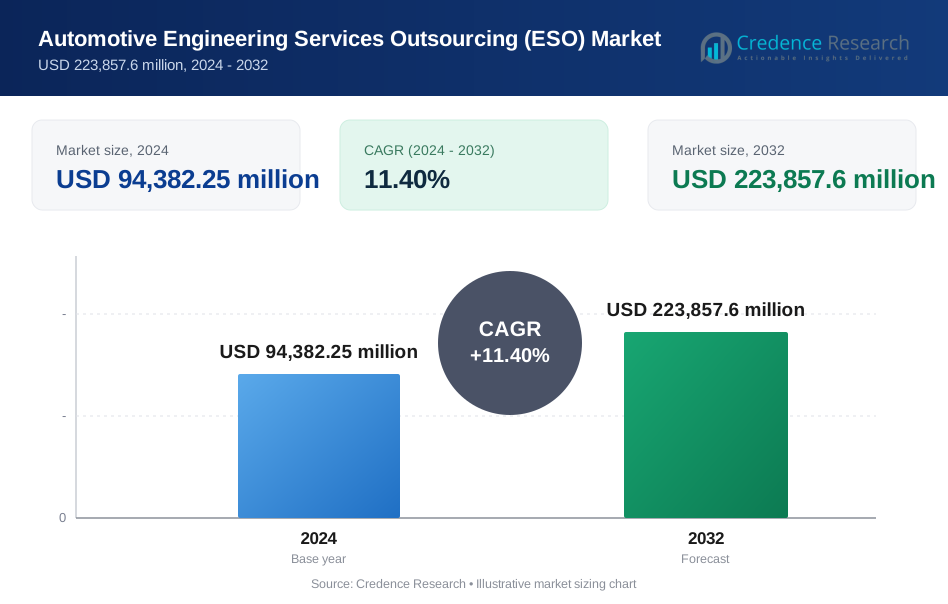
The Automotive Engineering Services Outsourcing (ESO) market is projected to grow from USD 94,382.25 million in 2024 to USD 223,857.6 million by 2032, with a compound annual growth rate (CAGR) of 11.4% during the forecast period.
The Automotive Engineering Services Outsourcing (ESO) market is being driven by the rapid advancements in automotive technologies, such as electric vehicles (EVs), autonomous driving, and connected car systems. OEMs (Original Equipment Manufacturers) are increasingly outsourcing engineering services to reduce costs, improve efficiency, and accelerate innovation, particularly in response to the growing demand for complex vehicle design and development. The push for sustainability, driven by stringent government regulations on emissions and fuel efficiency, is further fueling the need for specialized expertise in electric powertrains and lightweight materials. Additionally, the increasing adoption of digital tools such as simulation, AI, and machine learning is transforming automotive engineering, enabling faster and more accurate product development. As the industry shifts toward smart and autonomous vehicles, the need for external expertise in software, electronics, and connectivity is expected to further boost market growth, positioning ESO as a critical element in driving innovation and competitiveness.
The Automotive Engineering Services Outsourcing (ESO) market is geographically diverse, with North America holding a 25% share, Europe at 30%, and Asia-Pacific leading with 40% of the market in 2024. North America’s growth is driven by technological innovation and the demand for electric and autonomous vehicles. Europe is shaped by stringent regulations and a focus on sustainability, while Asia-Pacific thrives due to cost-efficiency and high production volumes, particularly in China and Japan. The Rest of the World, including Latin America, the Middle East, and Africa, holds a smaller share but is growing due to emerging automotive industries. Leading players in these regions include Wipro, IBM Corporation, Tech Mahindra, Capgemini, HCL Technologies, Infosys, L&T Technology Services, Akkodis, EPAM Systems, Altran, and QUEST GLOBAL, driving market expansion through strategic innovations and partnerships.
Market Insights
- The Automotive Engineering Services Outsourcing (ESO) market is projected to grow from USD 119,934 million in 2024 to USD 272,433.43 million by 2032, with a CAGR of 10.8%.
- Rapid advancements in automotive technologies like electric vehicles (EVs), autonomous driving, and connected car systems are driving the demand for ESO services.
- OEMs increasingly outsource engineering services to reduce costs, improve efficiency, and accelerate innovation, especially in response to growing complexity in vehicle design and development.
- The push for sustainability, driven by emissions regulations, boosts the demand for specialized expertise in electric powertrains and lightweight materials.
- The adoption of digital tools such as simulation, AI, and machine learning is transforming automotive engineering, enhancing development speed and accuracy.
- North America holds a 25% share of the ESO market, driven by technological innovation and the demand for electric and autonomous vehicles.
- Asia-Pacific leads with a 40% share, benefiting from high production volumes, cost efficiency, and growing investments in electric vehicles and autonomous technologies.
Market Drivers
Technological Advancements in Automotive Industry
The rapid evolution of automotive technologies, including electric vehicles (EVs), autonomous driving systems, and connected car solutions, is a key driver for the Automotive Engineering Services Outsourcing (ESO) market. For instance, Ford's F-150 Lightning has bidirectional charging capabilities, allowing it to act as a backup power source for homes during outages or provide electricity to the grid during peak demand periods. As the complexity of vehicle designs increases, Original Equipment Manufacturers (OEMs) are seeking specialized expertise to integrate these advanced technologies. ESO providers are crucial in enabling manufacturers to keep pace with innovations while maintaining high performance and safety standards in vehicles.
Cost Efficiency and Focus on Core Competencies
Automotive companies are increasingly outsourcing engineering services to enhance cost efficiency and focus on their core business operations. By leveraging external engineering expertise, OEMs can reduce in-house development costs, optimize resource allocation, and shorten product development cycles. ESO providers offer tailored solutions that allow manufacturers to manage expenses while maintaining innovation, ultimately boosting profitability and competitiveness in a highly dynamic market.
Demand for Sustainable and Eco-Friendly Solutions
The growing emphasis on environmental sustainability is shaping the automotive industry, with stringent regulations on emissions and fuel efficiency pushing OEMs to develop eco-friendly solutions. Engineering services are increasingly focused on the development of electric and hybrid powertrains, lightweight materials, and energy-efficient designs. ESO providers, with their specialized skills in these areas, help OEMs meet regulatory requirements and align with the global transition toward greener mobility solutions.
Digitalization and Smart Vehicle Development
The automotive industry is undergoing significant digital transformation, with increasing demand for smart, connected, and autonomous vehicles. ESO providers play a pivotal role in integrating advanced software, artificial intelligence (AI), and Internet of Things (IoT) technologies into automotive systems. For instance, Toyota is pioneering Vehicle-to-Everything (V2X) communications, enabling vehicles to interact with their surroundings, enhancing road safety by sharing data on road conditions and traffic signals. The growing need for software-driven innovation, combined with the pressure to launch new features faster, is driving OEMs to outsource engineering tasks, making ESO a critical enabler of next-generation vehicle development.
Market Trends
Shift Toward Electric Vehicle (EV) Development
A major trend in the Automotive Engineering Services Outsourcing (ESO) market is the growing emphasis on electric vehicle (EV) development. As global regulations become more stringent regarding emissions and fuel efficiency, OEMs are turning to ESO providers for expertise in designing electric powertrains, battery systems, and charging infrastructure. For instance,Honda, in a joint venture with LG Energy Solution, will begin producing 40GWh of batteries per year in the U.S. starting in 2025 to realize competitive battery costs and enhance the value of their Honda 0 Series models. This shift toward electrification is pushing companies to develop sustainable and energy-efficient solutions, and outsourcing engineering services enables them to meet these demands efficiently.
Focus on Autonomous Driving Technologies
The rising demand for autonomous vehicles is driving OEMs to collaborate with ESO providers to advance self-driving technologies. ESO firms are assisting in developing complex systems for sensors, machine learning algorithms, and control systems essential for autonomous driving. With increasing investments in research and development, ESO providers are helping automotive companies address the challenges of safety, regulation compliance, and the integration of autonomous features, which are expected to shape the future of mobility.
Integration of Connectivity and IoT Solutions
The integration of connected car systems and IoT technologies is a growing trend in the automotive industry, and ESO providers are at the forefront of enabling this transformation. Automakers are relying on outsourced engineering expertise to develop infotainment systems, vehicle-to-everything (V2X) communication technologies, and telematics solutions that enhance driver experience and safety. This trend is accelerating the adoption of smart vehicle technologies, positioning ESO providers as essential partners in digital innovation.
Increased Use of Simulation and AI in Engineering
The use of simulation, artificial intelligence (AI), and data analytics in automotive engineering is becoming more widespread. ESO providers are leveraging these digital tools to streamline product design, testing, and validation processes. For instance, Ford Motor Company utilizes AI to create aerodynamic designs, running thousands of digital simulations before building any physical prototype. By integrating AI-driven simulations, companies can reduce physical prototyping costs and speed up development timelines, making ESO a critical component of future-oriented automotive engineering.
Market Challenges Analysis
Complexity of Managing Multi-Vendor Outsourcing
One of the key challenges in the Automotive Engineering Services Outsourcing (ESO) market is the complexity involved in managing multi-vendor outsourcing. As OEMs increasingly rely on external engineering providers for specialized services, they often engage with multiple vendors for different aspects of vehicle development. Coordinating these diverse service providers and ensuring seamless collaboration across various engineering disciplines can be difficult. Misalignment between vendors can lead to delays in project timelines, communication gaps, and inconsistencies in product development, ultimately affecting the quality of the final product. OEMs need robust vendor management strategies to streamline coordination, minimize risks, and ensure that outsourced services align with their objectives and timelines. Additionally, tracking performance, quality assurance, and accountability among multiple vendors requires a highly structured and transparent management approach, which can become resource-intensive and complex for OEMs to handle effectively without a strong internal governance structure.
Intellectual Property (IP) and Data Security Concerns
The outsourcing of critical engineering functions also raises concerns about intellectual property (IP) protection and data security. Automotive companies are increasingly developing innovative solutions in areas like autonomous driving, electric mobility, and vehicle connectivity, making their proprietary technology a valuable asset. Outsourcing engineering services to third-party providers, especially in different geographic regions, can expose companies to risks related to IP theft, unauthorized data access, and compliance with data protection regulations. Ensuring that ESO providers adhere to stringent security protocols and data governance practices is crucial for OEMs to safeguard their competitive edge. For instance, Toyota faced a data exposure in 2022 due to a development subcontractor's error of inadvertently publishing source code on GitHub, which contained access keys to the company's data server. Additionally, navigating varying IP laws and regulations across countries can pose legal challenges, making it essential for companies to establish strong contractual agreements and legal frameworks when engaging with ESO providers. This can significantly increase the complexity of managing partnerships, as companies must continuously monitor compliance, enforce IP protection clauses, and mitigate potential risks of data breaches in an increasingly interconnected global market.
Market Opportunities
The Automotive Engineering Services Outsourcing (ESO) market presents significant opportunities as the demand for electric vehicles (EVs) and autonomous driving technologies continues to grow. With governments worldwide implementing stricter emissions regulations and promoting cleaner energy alternatives, OEMs are under pressure to innovate and develop advanced electric powertrains and battery systems. ESO providers offer specialized expertise in EV technologies, allowing automakers to accelerate development timelines, reduce costs, and meet regulatory requirements. Additionally, the rising interest in autonomous driving solutions creates further opportunities for ESO providers to contribute to the development of cutting-edge sensor systems, artificial intelligence algorithms, and autonomous driving platforms, enabling OEMs to keep pace with evolving industry trends.
As the automotive industry moves towards digitalization, there are also significant opportunities in the integration of smart vehicle technologies, such as vehicle-to-everything (V2X) communication, connectivity solutions, and infotainment systems. ESO providers play a critical role in helping OEMs adapt to the increasing demand for connected and intelligent vehicles by offering software development, data analytics, and system integration services. The growing use of artificial intelligence (AI) and machine learning in automotive engineering further enhances the need for outsourced expertise, as these technologies can improve vehicle design, performance testing, and predictive maintenance. Overall, ESO providers are well-positioned to capitalize on the industry's transition to electric, autonomous, and connected vehicles, offering OEMs access to the latest innovations and capabilities needed to maintain competitiveness in a rapidly evolving market.
Market Segmentation Analysis:
By Service
The Automotive Engineering Services Outsourcing (ESO) market is segmented by services, including design, prototyping, testing, and system integration. Design services dominate due to the increasing demand for innovative vehicle designs, particularly in electric and autonomous vehicles. System integration services are also growing as OEMs focus on advanced connectivity and intelligent vehicle systems.
By Application
By application, the ESO market spans across electric mobility, autonomous driving, connected cars, and traditional internal combustion engine (ICE) vehicles. Electric mobility leads the segment as the automotive industry increasingly shifts toward sustainable solutions. Autonomous driving technologies also drive substantial demand, particularly for sensor integration, AI-driven systems, and safety enhancements.
By Location
The market is also analyzed by geographic location, with Asia-Pacific, North America, and Europe being key regions. Asia-Pacific leads due to its extensive automotive manufacturing base and cost-efficient engineering services. Europe and North America follow, driven by high investments in electric mobility, digitalization, and autonomous driving technologies.
Segments:
Based on Service
- Designing
- Prototyping
- System Integration
- Testing
Based on Application
- Autonomous Driving/ADAS
- Body and Chassis
- Powertrain and After-treatment
- Infotainment and Connectivity+
Based on Location
- On-shore
- Off-shore
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Automotive Engineering Services Outsourcing (ESO) market, with a projected market share of 25% in 2024. The region is driven by a high concentration of automotive manufacturers, technology providers, and R&D centers, particularly in the United States and Canada. The adoption of electric vehicles (EVs), autonomous driving technologies, and advanced connectivity solutions has led OEMs to increasingly rely on outsourced engineering services to stay competitive. The demand for ESO services is expected to grow due to the expansion of EV infrastructure and the rising need for digitalization and autonomous features in vehicles. Additionally, regulatory pressures for environmental sustainability are encouraging OEMs to outsource specialized tasks in EV development and energy-efficient technologies. North America remains a key hub for innovation in the automotive sector, which continues to drive outsourcing opportunities.
Europe
Europe is another key region in the ESO market, commanding a market share of 30% in 2024. The region has a long-standing automotive legacy, with major OEMs like Volkswagen, BMW, and Daimler, alongside a strong presence of engineering service providers. European automotive companies are increasingly focusing on sustainability and technological advancements, such as electrification, autonomous driving, and smart vehicle solutions. The EU’s stringent environmental regulations also push manufacturers to seek expert outsourcing services to meet fuel efficiency and emission standards. Additionally, the region's leadership in automotive research and development fosters a robust demand for specialized ESO services, including design, prototyping, and advanced testing. The growing shift toward green mobility, supported by EU policies, is expected to further propel the growth of ESO services in Europe.
Asia-Pacific
Asia-Pacific is projected to be the largest regional market for ESO services, holding a market share of 40% in 2024. The region’s dominance can be attributed to the high volume of automotive production and manufacturing, particularly in countries like China, Japan, and India. China, in particular, is leading the global transition to electric vehicles, with substantial investments in EV infrastructure and manufacturing. The increasing focus on cost-efficiency and the availability of skilled engineering talent make Asia-Pacific an attractive destination for outsourced automotive services. Additionally, the region is seeing rapid growth in the development of autonomous and connected vehicle technologies, which further fuels the demand for specialized engineering services. As the largest market for vehicle production and consumption, Asia-Pacific is poised to continue driving the global ESO market.
Rest of the World
The Rest of the World, including regions like Latin America, the Middle East, and Africa, contributes a smaller portion to the global ESO market, with an estimated market share of 5% in 2024. While the automotive industry in these regions is still developing, there is growing demand for outsourced engineering services, particularly in countries with emerging automotive sectors such as Brazil, South Africa, and the UAE. The focus in these regions is primarily on vehicle manufacturing, production optimization, and adapting to global automotive trends, such as EV adoption and digital transformation. As the automotive industry continues to evolve in these regions, the demand for ESO services is expected to gradually increase.
Key Player Analysis
- Wipro
- IBM Corporation
- Akkodis
- Tech Mahindra Limited
- Capgemini
- Altran Technologies SA
- Infosys Limited
- EPAM Systems, Inc.
- L&T Technology Services Limited
- HCL Technologies Limited
- QUEST GLOBAL
Competitive Analysis
The Automotive Engineering Services Outsourcing (ESO) market is highly competitive, with several leading players driving innovation and market growth. Companies like Wipro, IBM Corporation, Tech Mahindra Limited, Capgemini, HCL Technologies Limited, Infosys Limited, L&T Technology Services Limited, Akkodis, EPAM Systems, Inc., Altran Technologies SA, and QUEST GLOBAL are at the forefront, offering a wide range of engineering services across vehicle design, testing, prototyping, and system integration. These players are capitalizing on the growing demand for electric vehicles (EVs), autonomous driving technologies, and connected car solutions. Their competitive edge lies in leveraging advanced technologies such as AI, machine learning, and digital simulation to enhance efficiency, reduce development time, and improve product quality. Additionally, these companies have established strong global footprints, enabling them to tap into emerging markets and deliver cost-effective solutions. Strategic partnerships, acquisitions, and continuous innovation are key strategies these players employ to maintain their leadership in the ESO market.
Recent Developments
- In June 2024, HORIBA, Ltd. launched the STARS Battery software, designed to address a wide range of battery testing needs. This new addition to HORIBA's STARS Automation platform provided a dedicated solution for conducting performance and longevity tests on batteries. The STARS Automation platform itself is known for its versatile collection of tools that cater to various testing tasks within the mobility sector.
- In May 2024, Bertrandt AG completed its acquisition of CENTUM SOLUTIONS, S.L.U. (Centum Digital), a company specializing in engineering services that leverage cutting-edge technologies and innovative products. This acquisition aligned with Bertrandt AG’s strategic goals of expanding its global footprint, enhancing its digital capabilities, and accelerating its innovation efforts.
- In January 2024, EDAG Engineering GmbH reinforced its international presence by opening two new facilities in Austria, located in Steyr and Neustift. Operational since December 2023, these locations offered a broad range of services in vehicle development and robotics.
- In September 2023, HCLTech acquired a full 100% stake in the German automotive engineering firm ASAP Group. ASAP Group focuses on advanced automotive technologies such as autonomous driving, e-mobility, and connectivity. The acquisition was expected to finalize by September 2023.
Market Concentration & Characteristics
The Automotive Engineering Services Outsourcing (ESO) market exhibits a moderate level of concentration, with a few key players dominating the landscape, while numerous smaller and specialized service providers also contribute to market dynamics. Large multinational firms, such as Wipro, IBM Corporation, and Tech Mahindra, command substantial market shares, leveraging their global reach, extensive service portfolios, and technological expertise to cater to a wide range of automotive OEMs. However, niche players focusing on specialized engineering areas, such as electric vehicle development, autonomous driving systems, and advanced testing, also play a crucial role in driving innovation. The market is characterized by a high degree of technological evolution, with a continuous shift toward electric mobility, connectivity, and autonomous technologies. As OEMs strive to stay competitive, they increasingly outsource complex engineering tasks to leverage external expertise, reduce costs, and accelerate time-to-market, which creates a dynamic and growing market environment.
Report Coverage
The research report offers an in-depth analysis based on Service, Aplication, Location and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for electric vehicles (EVs) will continue to drive the need for specialized engineering services, especially in battery development and energy-efficient designs.
- Autonomous driving technologies will expand the scope of outsourced services, particularly in AI, machine learning, and sensor integration.
- Increasing regulatory pressures for sustainability will push OEMs to outsource expertise in developing eco-friendly vehicle components and lightweight materials.
- The growth of connected vehicles will lead to higher demand for software and system integration services, encouraging outsourcing to meet digital transformation needs.
- OEMs will continue to prioritize cost reduction by outsourcing engineering tasks while focusing on core competencies like branding and vehicle marketing.
- The shift toward mobility-as-a-service (MaaS) will create opportunities for ESO providers to support the development of shared and on-demand transportation solutions.
- As automotive technologies become more complex, the need for highly specialized expertise in areas like cybersecurity and vehicle data analytics will rise.
- Geographic expansion into emerging markets will be critical for ESO providers to tap into new customer bases and support growing automotive sectors.
- The demand for faster product development cycles will increase, further accelerating the trend of outsourcing to streamline processes and reduce time-to-market.
- Collaboration between automotive companies and tech firms will grow, with ESO providers playing a crucial role in integrating innovative technologies into vehicles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Engineering Services Outsourcing (ESO) Market?
What factors are driving the growth of the Automotive Engineering Services Outsourcing (ESO) Market?
What are some challenges faced by the Automotive Engineering Services Outsourcing (ESO) Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 94,382.25 million → 2032: USD 223,857.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Engineering Services Outsourcing (ESO) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Engineering Services Outsourcing (ESO) Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Engineering Services Outsourcing (ESO) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Engineering Services Outsourcing (ESO) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Engineering Services Outsourcing (ESO) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Engineering Services Outsourcing (ESO) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Engineering Services Outsourcing (ESO) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Engineering Services Outsourcing (ESO) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 94,382.25 million → 2032: USD 223,857.6 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Engineering Services Outsourcing (ESO) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Engineering Services Outsourcing (ESO) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Engineering Services Outsourcing (ESO) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Engineering Services Outsourcing (ESO) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
