
Market Overview
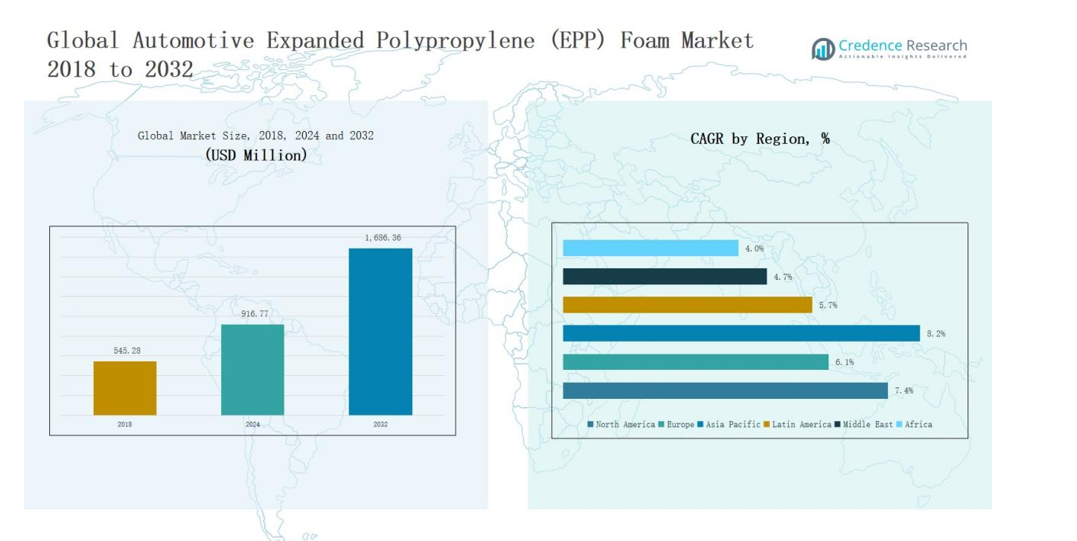
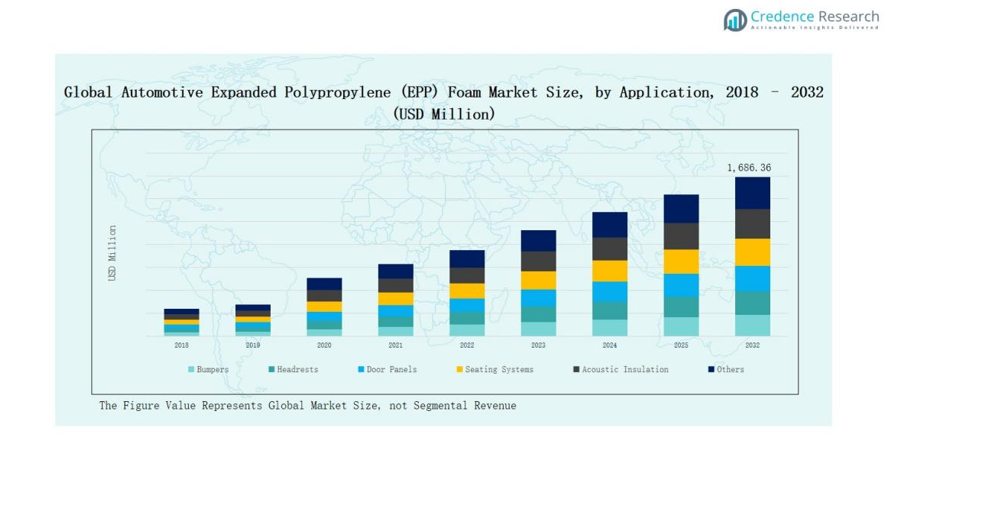
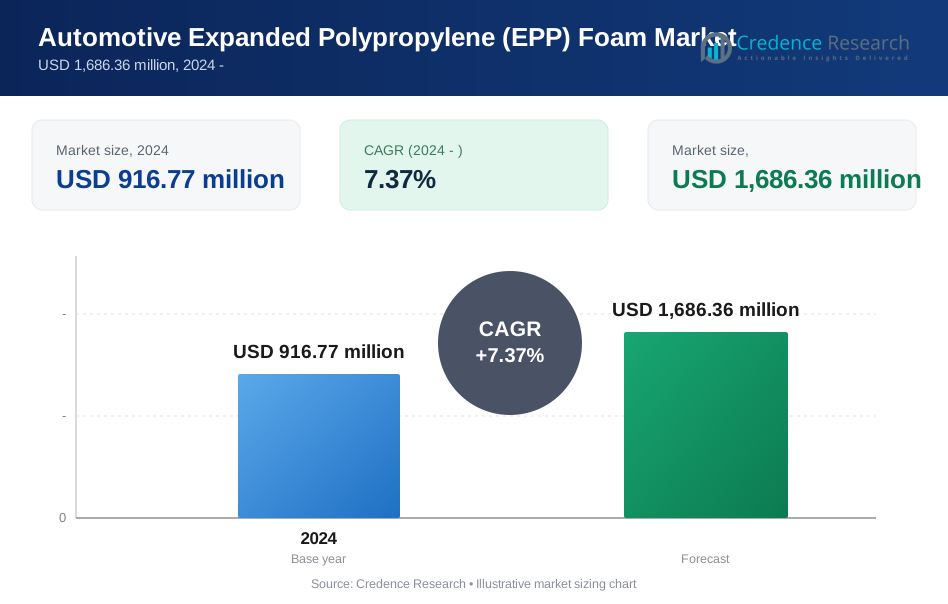
Automotive Expanded Polypropylene (EPP) Foam Market size was valued at USD 545.28 million in 2018, reached USD 916.77 million in 2024, and is anticipated to reach USD 1,686.36 million by 2032, growing at a CAGR of 7.37% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Expanded Polypropylene (EPP) Foam Market Size 2024 | USD 916.77 million |
| Automotive Expanded Polypropylene (EPP) Foam Market, CAGR | 7.37% |
| Automotive Expanded Polypropylene (EPP) Foam Market Size 2032 | USD 1,686.36 million |
The Automotive Expanded Polypropylene (EPP) Foam Market is shaped by prominent players such as BASF SE, JSP Corporation, Kaneka Corporation, Hanwha Advanced Materials, Furukawa Electric Co., Covestro AG, and Dynatek, all competing through innovation, sustainability initiatives, and partnerships with leading automakers. These companies emphasize lightweight, durable, and recyclable foam solutions to address growing demand for safety, comfort, and efficiency in modern vehicles. Asia Pacific emerged as the leading region in 2024 with a 45.7% market share, driven by large-scale vehicle production, rapid electric vehicle adoption, and strong government incentives supporting sustainable automotive materials.
Market Insights
- The Automotive Expanded Polypropylene (EPP) Foam Market grew from USD 545.28 million in 2018 to USD 916.77 million in 2024, with projections of USD 1,686.36 million by 2032.
- Seating systems led applications with a 32% share in 2024, driven by lightweight, crash-resistant, and ergonomic designs that enhance passenger safety, comfort, and fuel efficiency across vehicles.
- OEMs dominated end users with a 55% share in 2024, supported by direct EPP integration in bumpers, seats, and panels, along with rising global automotive production and safety standards.
- Asia Pacific remained the largest region with a 45.7% share in 2024, fueled by large-scale production in China, Japan, and India, alongside strong EV adoption incentives.
- Key players including BASF SE, JSP Corporation, Kaneka Corporation, Hanwha Advanced Materials, Furukawa Electric Co., Covestro AG, and Dynatek emphasized sustainability, innovation, and OEM partnerships to strengthen competitive positioning.
Market Segment Insights
By Application
Seating systems dominated the Automotive Expanded Polypropylene (EPP) Foam Market in 2024, accounting for 32% of the revenue share. The segment benefits from EPP foam’s lightweight, energy absorption, and cushioning properties that enhance passenger comfort and safety. Increasing demand for ergonomic and crash-resistant seating in both passenger and commercial vehicles drives growth. Automakers are also focusing on weight reduction to improve fuel efficiency, making seating systems the largest application segment with strong adoption across global markets.
- For instance, Faurecia developed lightweight seating structures with EPP foam to improve energy absorption and optimize interior space in next-generation vehicles.
By End User
OEMs (Original Equipment Manufacturers) held the leading position in 2024 with 55% market share. Their dominance stems from the direct integration of EPP foam into automotive design for bumpers, seats, and door panels. The segment benefits from rising vehicle production, stringent crash safety standards, and lightweighting initiatives. Growing partnerships between EPP producers and automakers also support innovation in customized foam components. OEMs remain the primary demand driver, as they integrate EPP solutions into electric, passenger, and commercial vehicles globally.
- For instance, Volkswagen Group has collaborated with JSP Corporation to incorporate advanced EPP foams into door panels and rear bumpers, improving crash safety performance without compromising design flexibility.
Market Overview
Rising Demand for Lightweight Vehicles
Lightweighting initiatives remain a central driver of EPP foam adoption. Automakers increasingly focus on reducing vehicle weight to enhance fuel efficiency and comply with strict emission standards. Expanded polypropylene offers superior strength-to-weight ratio, making it ideal for seating, bumpers, and insulation applications. The material also contributes to crash safety and thermal performance, providing multiple functional benefits. Growing consumer preference for fuel-efficient and sustainable vehicles strengthens the demand for EPP foam across passenger cars, electric vehicles, and commercial fleets globally.
Increasing Focus on Passenger Safety and Comfort
Passenger safety regulations and consumer expectations strongly influence EPP foam demand. Its excellent energy absorption, impact resistance, and cushioning properties make it a preferred material for automotive seating systems, bumpers, and headrests. Rising awareness of crash safety and growing adoption of advanced seating solutions in modern vehicles drive steady market growth. Additionally, its acoustic insulation capabilities improve cabin comfort, aligning with rising consumer demand for noise reduction. As safety and comfort become key differentiators, EPP foam gains wider acceptance.
- For instance, JSP Corporation introduced its high-performance ARPRO EPP materials designed for headrests and bumpers, offering better crash energy management and vibration resistance.
Expanding Electric Vehicle Manufacturing
The rapid growth of electric vehicle (EV) production creates significant opportunities for EPP foam integration. EV manufacturers prioritize lightweight materials to extend driving range while ensuring crash safety and thermal management. EPP foam’s heat resistance, recyclability, and design flexibility make it ideal for EV interiors, battery packaging, and insulation. Supportive government policies, subsidies, and investments in EV infrastructure further accelerate demand. With leading automakers expanding EV production lines, EPP foam adoption in electric mobility is expected to rise sharply.
- For instance, Knauf Industries uses expanded polypropylene (EPP) foam in battery packs for thermal insulation, shock absorption, and electrical insulation to protect lithium-ion cells, while reducing weight compared to traditional materials.
Key Trends & Opportunities
Sustainability and Recyclability of EPP Foam
The automotive industry’s increasing focus on sustainability has elevated interest in recyclable and eco-friendly materials. EPP foam, being 100% recyclable, addresses circular economy goals while reducing environmental impact. Manufacturers are exploring bio-based polypropylene blends to strengthen green product portfolios. Growing regulatory pressure for eco-friendly automotive components, coupled with consumer demand for sustainable mobility solutions, creates a major opportunity. This trend positions EPP foam as a strategic material, supporting both environmental compliance and brand differentiation in global automotive markets.
- For instance, Hyundai Motor Group utilizes EPP foam in electric vehicle seating systems, enhancing impact resistance, thermal stability, and recyclability, highlighting the foam’s suitability for safety-critical lightweight components.
Advancements in Material Innovation
Continuous innovations in EPP foam technology are creating new growth avenues. Development of higher-density and multi-functional foam grades enables wider use in structural components, noise insulation, and thermal management. Manufacturers are integrating nanomaterials and advanced composites to improve durability, fire resistance, and performance under extreme conditions. These innovations align with evolving requirements of next-generation vehicles, including autonomous and connected cars. Collaborations between material science firms and automakers further enhance adoption, offering opportunities for product differentiation and competitive advantage.
- For instance, BASF developed Neopolen® P expanded polypropylene foams with superior energy absorption for crash-relevant vehicle parts in electric cars.
Key Challenges
High Raw Material Price Volatility
Fluctuations in polypropylene resin prices pose a significant challenge to EPP foam manufacturers. Prices often depend on global crude oil supply and geopolitical dynamics, directly affecting production costs and profit margins. Volatility in feedstock availability can disrupt supply chains and limit consistent pricing for automakers. This unpredictability reduces planning efficiency and may force manufacturers to adjust pricing strategies. Long-term cost fluctuations remain a critical challenge, requiring companies to explore bio-based alternatives, recycling initiatives, and supply diversification strategies.
Intense Competition and Market Consolidation
The EPP foam market faces strong competition among established global players and regional producers. Large companies invest heavily in R&D, product innovation, and partnerships to secure OEM contracts, creating barriers for smaller firms. Market consolidation through mergers and acquisitions intensifies rivalry and limits new entrants. Price competitiveness also pressures margins, especially in regions with mature automotive industries. Sustaining market presence requires constant innovation and differentiation, making competition one of the key hurdles for industry players worldwide.
Limited Awareness in Emerging Markets
In several emerging economies, adoption of EPP foam in automotive manufacturing remains limited due to low awareness and cost-sensitive markets. Traditional materials such as polyurethane and polystyrene continue to dominate, especially in low- to mid-range vehicles. Lack of technical knowledge among local manufacturers and insufficient regulatory push for lightweight and eco-friendly materials restrict penetration. Building awareness through demonstration of safety, comfort, and sustainability benefits, along with training programs, will be crucial for unlocking growth potential in these regions.
Regional Analysis
North America
North America held a 29.1% share in 2018, generating USD 158.81 million, which grew to USD 262.84 million in 2024 and is projected to reach USD 485.50 million by 2032 at a CAGR of 7.4%. The region benefits from strong adoption of lightweight materials, advanced safety regulations, and high EV penetration, particularly in the United States. OEM integration of EPP foam into seating, bumpers, and insulation solutions drives demand. Robust R&D investments and collaborations between material suppliers and automakers continue to strengthen the region’s leadership position.
Europe
Europe accounted for 18.3% of the global share in 2018, valued at USD 99.85 million, and increased to USD 158.50 million in 2024. It is expected to reach USD 264.58 million by 2032, growing at a CAGR of 6.1%. Demand is driven by strict EU emission norms, rising focus on recyclability, and strong adoption of eco-friendly materials in Germany, France, and the UK. EPP foam’s acoustic and thermal benefits align with Europe’s preference for premium, high-comfort vehicles. Sustainability policies and innovation in lightweight automotive materials continue to fuel steady regional growth.
Asia Pacific
Asia Pacific dominated the market with a 44.1% share in 2018, valued at USD 240.60 million. By 2024, revenue reached USD 419.30 million and is projected to hit USD 817.90 million by 2032, expanding at the fastest CAGR of 8.2%. Growth is supported by large-scale vehicle production in China, Japan, and India, alongside rapid electric vehicle adoption. Rising consumer demand for affordable yet fuel-efficient cars boosts EPP foam use in bumpers, seating, and insulation. Government incentives for EVs and growing infrastructure investments further strengthen Asia Pacific’s leading position.
Latin America
Latin America represented a 4.6% market share in 2018, valued at USD 25.15 million, rising to USD 41.75 million in 2024 and projected at USD 67.75 million by 2032, with a CAGR of 5.7%. Brazil and Mexico drive demand due to expanding automotive production hubs and growing middle-class vehicle ownership. Adoption of EPP foam is increasing in bumpers and seating systems, supported by gradual regulatory moves toward safety and fuel efficiency. However, cost sensitivity and limited awareness restrict faster penetration, though opportunities are emerging in EV component integration.
Middle East
The Middle East accounted for a 2.4% share in 2018, valued at USD 13.21 million, reaching USD 20.01 million in 2024, and is projected at USD 30.06 million by 2032, growing at a CAGR of 4.7%. GCC countries lead adoption due to strong luxury vehicle demand and premium automotive imports. Use of EPP foam is rising in seating and acoustic insulation to enhance passenger comfort. While local automotive production remains limited, aftermarket and EV adoption in urban hubs present gradual growth opportunities, supported by government diversification programs.
Africa
Africa held the smallest share at 1.4% in 2018, generating USD 7.66 million, which rose to USD 14.37 million in 2024 and is expected to reach USD 20.56 million by 2032, at a CAGR of 4.0%. South Africa remains the key hub with its established automotive manufacturing base, while Egypt shows steady demand growth. Adoption of EPP foam is mainly seen in OEM seating and bumpers, though cost sensitivity limits widespread use. Growing automotive assembly projects and rising consumer awareness of safety are expected to slowly expand Africa’s market share.
Market Segmentations:
By Application
- Bumpers
- Headrests
- Door Panels
- Seating Systems
- Acoustic Insulation
- Others
By End User
- OEMs (Original Equipment Manufacturers)
- Automotive Aftermarket
- Electric Vehicle Manufacturers
- Others
By Region
North America
- U.S.
- Canada
- Mexico
Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
Latin America
- Brazil
- Argentina
- Rest of Latin America
Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The Automotive Expanded Polypropylene (EPP) Foam Market is characterized by the presence of leading global chemical companies and specialized material suppliers competing on innovation, product quality, and cost efficiency. Key players such as BASF SE, JSP Corporation, Kaneka Corporation, Hanwha Advanced Materials, Furukawa Electric Co., Covestro AG, and Dynatek dominate the market with extensive product portfolios and strong collaborations with OEMs. These companies emphasize lightweight, durable, and recyclable foam solutions that meet growing safety, comfort, and sustainability requirements in modern vehicles. Strategic initiatives include expanding production facilities, developing advanced foam grades, and integrating bio-based polypropylene to align with regulatory and consumer trends. Partnerships with automotive manufacturers, particularly in electric vehicle development, strengthen their competitive positions. Regional manufacturers also play a vital role by offering cost-effective solutions in emerging markets. Overall, competition is intensifying, with innovation, sustainability, and customization emerging as key differentiators for long-term market leadership.
Key Players
- BASF SE
- JSP Corporation
- Kaneka Corporation
- Hanwha Advanced Materials
- Furukawa Electric Co.
- Covestro AG
- Dynatek
Recent Developments
- In September 2025, Brose Sitech announced the acquisition of Proseat, a major foam and seat supplier, to strengthen its automotive interior and foam capabilities.
- In 2025, JSP expanded its ARPRO EPP foam portfolio by introducing recycled-content grades, certified under RecyClass in September 2025.
- In April 2025, JSP Corporation launched a next-generation production line that improves manufacturing efficiency for EPP foam by reducing bead expansion time and energy consumption.
Report Coverage
The research report offers an in-depth analysis based on Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for lightweight materials will rise as automakers focus on fuel efficiency and sustainability.
- Electric vehicle growth will boost the use of EPP foam in battery packaging and insulation.
- Safety regulations will increase adoption of EPP foam in seating, bumpers, and crash protection parts.
- Recyclability of EPP foam will strengthen its role in circular economy initiatives.
- Acoustic insulation applications will expand with rising demand for quieter cabins in premium vehicles.
- Material innovation will drive development of higher-density and multifunctional foam solutions.
- Partnerships between foam producers and OEMs will accelerate customized product development.
- Emerging markets will witness gradual adoption as awareness and production capacity increase.
- Competitive intensity will push companies to differentiate through sustainability and design flexibility.
- Regional production expansion will support stable supply chains and reduced logistics costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global automotive expanded polypropylene (EPP) foam market?
What is the expected growth rate of the automotive expanded polypropylene (EPP) foam market between 2025 and 2032?
Who are the major players in the global automotive expanded polypropylene (EPP) foam market?
What are the major market restraints of the automotive expanded polypropylene (EPP) foam industry?
What are the major market opportunities of the automotive expanded polypropylene (EPP) foam industry?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Expanded Polypropylene (EPP) Foam Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Expanded Polypropylene (EPP) Foam Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 916.77 million → forecast year: USD 1,686.36 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Expanded Polypropylene (EPP) Foam Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Expanded Polypropylene (EPP) Foam Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Expanded Polypropylene (EPP) Foam Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Expanded Polypropylene (EPP) Foam Market Drivers
- 3.3 Automotive Expanded Polypropylene (EPP) Foam Market Restraints & Challenges
- 3.4 Automotive Expanded Polypropylene (EPP) Foam Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Expanded Polypropylene (EPP) Foam Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Expanded Polypropylene (EPP) Foam Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Expanded Polypropylene (EPP) Foam category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Expanded Polypropylene (EPP) Foam Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Expanded Polypropylene (EPP) Foam Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Expanded Polypropylene (EPP) Foam market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Expanded Polypropylene (EPP) Foam Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Expanded Polypropylene (EPP) Foam Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Expanded Polypropylene (EPP) Foam Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Expanded Polypropylene (EPP) Foam (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Expanded Polypropylene (EPP) Foam Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Expanded Polypropylene (EPP) Foam Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Expanded Polypropylene (EPP) Foam Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Expanded Polypropylene (EPP) Foam Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Expanded Polypropylene (EPP) Foam Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Expanded Polypropylene (EPP) Foam Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Expanded Polypropylene (EPP) Foam Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Expanded Polypropylene (EPP) Foam Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Expanded Polypropylene (EPP) Foam Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
