
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Glow Plug Market Size 2024 | USD 3,162.72 million |
| Automotive Glow Plug Market , CAGR | 3.90% |
| Automotive Glow Plug Market Size 2032 | USD 4,295.21 million |
Market Overview:
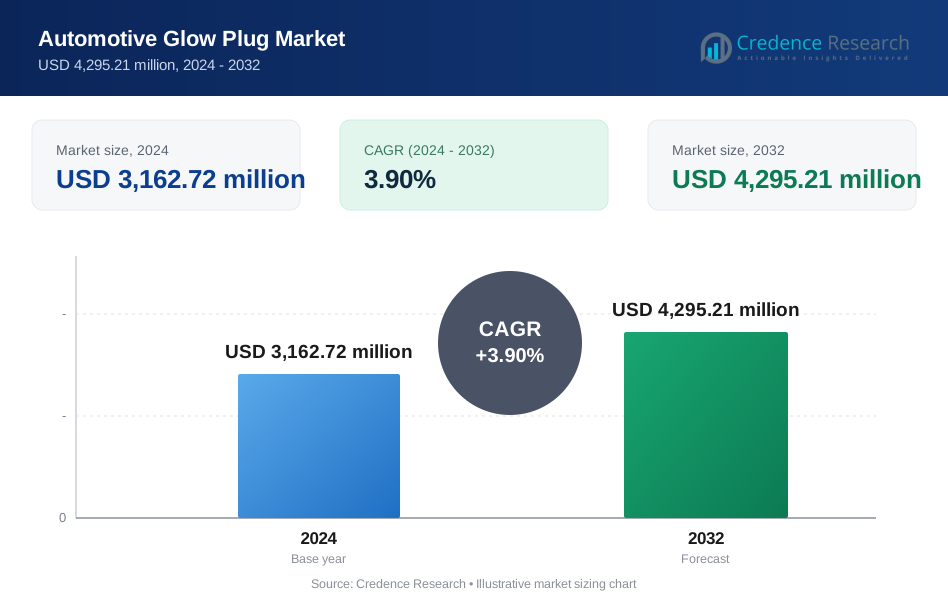
The global automotive glow plug market is poised for steady growth, with its market size expected to expand from USD 3,162.72 million in 2024 to USD 4,295.21 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.90% during the forecast period. This growth is primarily driven by the increasing demand for diesel engines in commercial vehicles and the ongoing advancements in diesel engine technology. As diesel engines remain a preferred choice for commercial and heavy-duty vehicles due to their superior fuel efficiency and torque, the demand for reliable and efficient glow plugs is set to rise. Glow plugs, essential for cold starting diesel engines, play a crucial role in ensuring engine performance and reducing emissions, making them vital components in the automotive industry.
Key drivers of the automotive glow plug market include the rising adoption of diesel-powered vehicles, particularly in emerging markets, and stringent emission regulations globally. Governments and regulatory bodies are imposing stricter emission norms, pushing manufacturers to adopt advanced technologies that reduce carbon emissions. Glow plugs, which contribute to efficient combustion and lower emissions, are becoming increasingly important in meeting these regulations. Additionally, the growing trend toward engine downsizing and the increasing production of passenger and commercial vehicles further support the market's expansion.
From a regional perspective, Europe is expected to hold a significant share of the automotive glow plug market, accounting for approximately 35% of the total market by 2032. This dominance is attributed to the region's strong automotive industry, particularly in countries like Germany, France, and Italy, where diesel engines are prevalent. Asia-Pacific is anticipated to experience the fastest growth, driven by rapid industrialization, rising disposable incomes, and increasing vehicle production in countries such as China and India. North America is also a key market, supported by the steady demand for commercial vehicles and the presence of leading automotive manufacturers. The diverse growth patterns across these regions highlight the global reach and importance of the automotive glow plug market.
Market Drivers:
Rising Demand for Diesel-Powered Vehicles:
The global demand for diesel-powered vehicles is a significant driver of the automotive glow plug market. Diesel engines are favoured in various regions, particularly in commercial vehicles, due to their superior fuel efficiency, torque, and longevity compared to gasoline engines. For instance, according to the International Energy Agency (IEA), diesel vehicles accounted for nearly 44% of all commercial vehicles sold globally in 2022. This preference for diesel engines, especially in heavy-duty applications, drives the need for high-quality glow plugs that ensure efficient cold starts and optimal engine performance, particularly in colder climates.
Stricter Emission Regulations:
Stricter global emission regulations are pushing automotive manufacturers to adopt advanced technologies that reduce carbon emissions, including improved diesel engine components like glow plugs. Governments worldwide are implementing stringent emission standards to combat air pollution, particularly from diesel engines, which are known for their higher nitrogen oxide (NOx) and particulate matter (PM) emissions. For example, the European Union's Euro 6 standards and the U.S. Environmental Protection Agency (EPA) Tier 3 regulations set tough limits on vehicle emissions, prompting manufacturers to focus on technologies that enhance fuel combustion efficiency and reduce emissions, thereby driving the demand for advanced glow plugs.
Technological Advancements in Diesel Engines:
Technological advancements in diesel engine design and manufacturing are also fuelling the growth of the automotive glow plug market. Innovations such as common rail direct injection (CRDI) systems and turbocharging have improved the efficiency and performance of diesel engines, making them more competitive with gasoline engines. These advancements require high-performance glow plugs that can withstand higher pressures and temperatures, ensuring reliable ignition and efficient combustion. Companies like Bosch and Denso are continuously investing in research and development to produce next-generation glow plugs that meet the evolving needs of modern diesel engines.
Growth in Emerging Markets:
Emerging markets, particularly in Asia-Pacific and Latin America, are witnessing robust growth in vehicle production and sales, contributing to the increased demand for automotive glow plugs. Countries like China and India are experiencing rapid urbanization and industrialization, leading to a rise in commercial vehicle usage. For instance, the Indian government’s focus on infrastructure development has spurred demand for commercial vehicles, many of which are diesel-powered. As these markets continue to expand, the need for efficient and durable glow plugs in diesel engines will grow, further driving market growth.
Market Trends:
Increasing Adoption of Ceramic Glow Plugs:
One of the significant trends in the automotive glow plug market is the increasing adoption of ceramic glow plugs. Unlike traditional metal glow plugs, ceramic glow plugs offer faster heating times and higher maximum operating temperatures, which improve cold-start performance in diesel engines. For instance, manufacturers like Bosch and NGK have developed advanced ceramic glow plugs that reach operating temperatures in a matter of seconds, enhancing engine efficiency and reducing emissions. This trend is driven by the automotive industry's focus on improving diesel engine performance while meeting stringent emission regulations.
Emphasis on Reducing Cold-Start Emissions:
Reducing emissions during cold starts is becoming a critical focus area for automotive manufacturers, leading to the development of more efficient glow plug technologies. Cold starts are typically associated with higher emissions of unburned hydrocarbons and particulates, which are harmful to the environment. To address this, companies are investing in glow plugs that can achieve rapid temperature increases, ensuring more complete combustion even at low engine temperatures. For example, Denso has introduced glow plugs with integrated temperature sensors that precisely control the heating process, reducing cold-start emissions and improving overall engine efficiency.
Integration of Advanced Materials:
The integration of advanced materials into glow plug design is another emerging trend. Automotive manufacturers are increasingly using materials like silicon nitride and other high-performance ceramics to enhance the durability and efficiency of glow plugs. These materials allow glow plugs to withstand the extreme conditions of modern diesel engines, including higher combustion pressures and temperatures. The use of advanced materials not only extends the lifespan of glow plugs but also contributes to better fuel efficiency and lower emissions, aligning with the industry's sustainability goals.
Growing Demand in Aftermarket Services:
There is a growing demand for glow plugs in the automotive aftermarket, particularly as vehicle ownership durations increase and consumers look to maintain their diesel engines efficiently. Aftermarket services are becoming more critical as drivers seek high-quality replacement parts that ensure long-term engine reliability. Companies like NGK and Beru are expanding their aftermarket offerings with a focus on providing durable and high-performance glow plugs that meet the specifications of various diesel engine models. This trend reflects the increasing importance of aftermarket sales in the overall growth strategy of glow plug manufacturers.
Market Challenges Analysis:
Decline in Diesel Vehicle Demand:
One of the primary restraints in the automotive glow plug market is the declining demand for diesel vehicles, particularly in passenger cars. In recent years, consumer preferences have shifted towards electric and hybrid vehicles, driven by concerns over diesel emissions and the global push for cleaner energy sources. For instance, several European countries have announced plans to ban the sale of new diesel vehicles in the coming decades, leading to a gradual reduction in diesel vehicle production. This shift in the automotive industry is expected to impact the demand for glow plugs, as fewer diesel vehicles on the road will result in lower overall market demand.
Increasing Stringency of Emission Regulations:
While stricter emission regulations drive the need for advanced glow plugs, they also pose challenges for manufacturers. Compliance with these regulations requires significant investment in research and development to create glow plugs that meet new standards for emission reduction. The cost of developing these advanced technologies can be prohibitive, particularly for smaller manufacturers. Additionally, as regulations continue to tighten, manufacturers may face difficulties in keeping pace with the required technological advancements, potentially limiting their ability to compete in the market.
Competition from Alternative Technologies:
The automotive glow plug market also faces challenges from alternative technologies, such as electric and hybrid powertrains, which do not require glow plugs. The growing adoption of these technologies, particularly in regions with stringent emission standards, poses a direct threat to the demand for diesel engines and, consequently, glow plugs. As more automakers transition to electric and hybrid vehicles, the market for traditional diesel engine components, including glow plugs, is likely to shrink. This trend highlights the need for glow plug manufacturers to diversify their product offerings and explore opportunities in emerging technologies.
High Costs of Advanced Materials:
The integration of advanced materials, such as high-performance ceramics, into glow plug design, while beneficial for performance, also introduces cost challenges. These materials are often more expensive to produce and require specialized manufacturing processes, leading to higher production costs. As a result, manufacturers may struggle to maintain competitive pricing, especially in cost-sensitive markets. The high cost of advanced glow plugs could limit their adoption, particularly in emerging markets where price sensitivity is a significant factor.
Market Segmentation Analysis:
By Type:
The market is divided into two main types: metal glow plugs and ceramic glow plugs. Metal glow plugs are widely used due to their cost-effectiveness and reliability in standard diesel engines. Ceramic glow plugs, on the other hand, offer superior performance and durability, making them suitable for high-performance diesel engines.
By Technology:
Technological segmentation includes standard glow plugs and advanced glow plugs with integrated sensors. Standard glow plugs are commonly used in conventional diesel engines, providing the necessary heat for ignition. Advanced glow plugs with integrated sensors offer enhanced functionality, such as real-time monitoring of temperature and pressure, improving engine efficiency and reducing emissions.
By End User:
The end-user segmentation comprises passenger cars, light commercial vehicles, and heavy commercial vehicles. Passenger cars form the largest segment, driven by the increasing demand for diesel-powered vehicles in various regions. Light commercial vehicles also contribute significantly, particularly in the logistics and transportation sectors. Heavy commercial vehicles, including trucks and buses, rely on robust glow plug systems to ensure reliable engine performance in demanding conditions.
Segmentations:
By Product Type
- Metal Glow Plug
- Ceramic Glow Plug
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
By Sales Channel
- OEM
- Aftermarket
By Region
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
Europe
Europe holds a significant portion of the market, accounting for approximately 35% of the total share. This dominance is largely due to the strong presence of diesel vehicles in countries like Germany, France, and Italy, where diesel engines are prevalent, particularly in commercial vehicles. The region's stringent emission regulations, such as the Euro 6 standards, also drive the demand for advanced glow plug technologies that help reduce emissions and improve engine performance. Europe's well-established automotive industry, coupled with continuous advancements in diesel engine technology, reinforces its leadership in the global market.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the automotive glow plug market, with an expected market share of around 30% by 2032. The region's rapid industrialization, increasing vehicle production, and rising disposable incomes are key factors contributing to this growth. China and India are at the forefront of this expansion, driven by the increasing demand for commercial vehicles, which are predominantly diesel-powered. Government initiatives in these countries, such as India's focus on infrastructure development, have spurred the growth of the automotive sector, further boosting the demand for glow plugs. Additionally, the region's large and growing population, combined with urbanization trends, continues to fuel the demand for reliable and efficient diesel vehicles, thus supporting market growth.
North America
North America accounts for approximately 20% of the global market share. The United States and Canada are the primary contributors, where the demand for diesel-powered commercial vehicles remains strong. The region's focus on reducing emissions and improving fuel efficiency has led to the adoption of advanced glow plug technologies. Moreover, the presence of leading automotive manufacturers and the growing popularity of diesel trucks in the U.S. further bolster the market. However, the gradual shift towards electric and hybrid vehicles in the region poses a challenge to the growth of the glow plug market in the long term.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively hold the remaining 15% of the market share, with Latin America leading at 10%. In Latin America, countries like Brazil and Mexico are experiencing a steady increase in vehicle production, particularly in the commercial vehicle segment, which drives the demand for glow plugs. The Middle East & Africa, although a smaller market, is gradually expanding as the region invests in infrastructure development and increases vehicle production to meet growing transportation needs. These regions present significant growth opportunities for the automotive glow plug market, particularly as they continue to develop their automotive industries and increase their focus on reducing vehicle emissions.
Key Player Analysis:
Top Key Players
- NGK Spark Plug Co. Ltd.
- Denso Corporation
- Robert Bosch GmbH
- BorgWarner Inc.
- Valeo S.A.
- Federal-Mogul Corporation
- Weichai Power Co., Ltd.
- ACDelco Corporation
- Marelli Holdings Co., Ltd.
- Tenneco Inc.
Competitive Analysis:
The automotive glow plug market is moderately competitive, with several key players holding significant market shares. Leading companies like BorgWarner Inc., Denso Corporation, Robert Bosch GmbH, and NGK Spark Plug Co., Ltd. dominate the market by offering a comprehensive range of glow plugs designed for both passenger and commercial diesel vehicles. These companies leverage their extensive research and development capabilities to innovate and produce advanced glow plugs that meet stringent emission standards and enhance engine performance. Additionally, these market leaders benefit from their global distribution networks and strong relationships with major automotive manufacturers. Regional players and specialized manufacturers also contribute to the competitive landscape by focusing on niche markets and providing cost-effective solutions. The competition is further intensified by the need for continuous technological advancements, as companies strive to develop glow plugs that are more efficient, durable, and capable of operating under extreme conditions. As the market evolves, innovation and the ability to adapt to changing emission regulations will remain key differentiators for companies competing in this space.
Recent Developments:
- Denso Corporation expanded its product offerings by introducing a new range of glow plugs designed to meet the latest emission regulations. In 2022, Denso launched advanced glow plugs that improve cold-start performance while reducing NOx emissions, aligning with global trends toward stricter environmental standards.
- Robert Bosch GmbH invested in the development of next-generation ceramic glow plugs in 2023, which offer faster heating times and are capable of withstanding higher operating temperatures. This development supports Bosch's commitment to advancing diesel engine technologies while meeting stringent emission norms.
Market Concentration & Characteristics:
The automotive glow plug market is moderately concentrated, with a few dominant players holding significant market shares globally. Leading companies such as BorgWarner Inc., Denso Corporation, Robert Bosch GmbH, and NGK Spark Plug Co., Ltd. are key players, recognized for their extensive product portfolios and strong focus on research and development. These companies leverage their technological expertise and global distribution networks to maintain their market positions. The market is characterized by continuous innovation, driven by the need to meet increasingly stringent emission regulations and improve diesel engine performance. Additionally, the market is shaped by the growing demand for advanced materials and technologies that enhance the efficiency and durability of glow plugs, especially in commercial vehicles. Smaller regional players also contribute to the competitive landscape by offering cost-effective and tailored solutions for specific markets, further intensifying competition in this sector.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Vehicle Type, Sales Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Despite the global shift towards electrification, diesel engines will continue to play a significant role in commercial vehicles, sustaining the demand for advanced glow plugs.
- The market will witness ongoing innovation in glow plug technology, including faster heating times and improved durability, driven by the need to meet stringent emission regulations and enhance engine performance.
- Ceramic glow plugs, known for their high-temperature resistance and rapid heating capabilities, are expected to see increased adoption, particularly in newer diesel engines.
- Emerging markets, especially in Asia-Pacific and Latin America, will see robust growth in the automotive glow plug market, fuelled by rising vehicle production and the continued prevalence of diesel engines.
- Stricter global emission standards will drive demand for more efficient glow plugs that contribute to lower NOx and particulate emissions, aligning with environmental goals.
- The aftermarket segment will grow as vehicle owners seek high-quality replacement glow plugs to maintain diesel engine efficiency and compliance with emission standards.
- Leading manufacturers will continue to invest in research and development to innovate and stay competitive, focusing on enhancing the efficiency and longevity of glow plugs.
- Integration of smart technologies in glow plugs, such as temperature sensors for precise control, will become more common, improving engine performance and reducing emissions.
- The rise of electric vehicles (EVs) presents a long-term challenge, gradually reducing the overall market size for traditional diesel engine components, including glow plugs.
- Manufacturers will increasingly focus on sustainability, developing glow plugs with lower environmental impact, both in terms of production processes and end-of-life recyclability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Glow Plug Market?
What factors are driving the growth of the Automotive Glow Plug Market?
What are some challenges faced by the Automotive Glow Plug Market?
Who are the major players in the Automotive Glow Plug Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Glow Plug Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Glow Plug Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,162.72 million → 2032: USD 4,295.21 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Glow Plug Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Glow Plug Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Glow Plug Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Glow Plug Market Drivers
- 3.3 Automotive Glow Plug Market Restraints & Challenges
- 3.4 Automotive Glow Plug Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Glow Plug Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Glow Plug Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Glow Plug category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Glow Plug Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Automotive Glow Plug Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Automotive Glow Plug. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Glow Plug Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Glow Plug Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Automotive Glow Plug Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Glow Plug (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Automotive Glow Plug
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Glow Plug Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Automotive Glow Plug Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Glow Plug Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Glow Plug Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Glow Plug Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Glow Plug Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Glow Plug Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Glow Plug Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
