
Market Overview
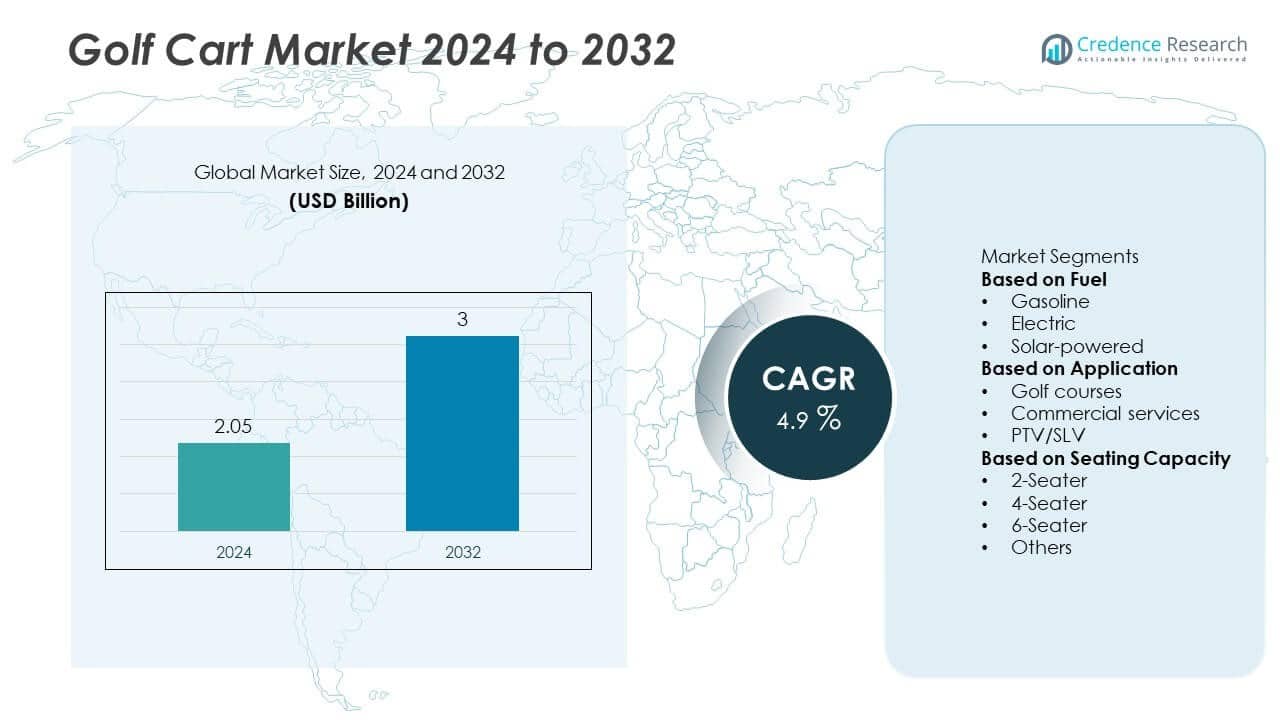
The Golf Cart market size was valued at USD 2.05 billion in 2024 and is projected to reach USD 3 billion by 2032, growing at a CAGR of 4.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Golf Cart market Size 2024 | USD 2.05 Billion |
| Golf Cart market, CAGR | 4.9% |
| Golf Cart market Size 2032 | USD 3 Billion |
The Golf Cart market is led by key players such as Yamaha Motor Co., Ltd., Club Car, LLC, EZ-GO (Textron Inc.), Marshell Green Power Co., Ltd., Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd., Guangdong Lvtong New Energy Electric Vehicle Technology Co., Ltd., GUANGZHOU LANGQING ELECTRIC CAR CO., LTD., JH Global Services, Inc. (Star EV), Tomberlin Electric Vehicles, and HDK Electric Vehicles. These companies focus on electric mobility innovations, smart connectivity, and lithium-ion battery integration to enhance performance and sustainability. North America dominates the market with a 47% share, supported by strong demand in golf courses and residential communities. Europe holds a 24% share, driven by eco-friendly tourism, while Asia-Pacific follows with 23%, supported by rapid urbanization and growing recreational infrastructure.
Market Insights
- The Golf Cart market was valued at USD 2.05 billion in 2024 and is projected to reach USD 3 billion by 2032, expanding at a CAGR of 4.9% during the forecast period.
- Market growth is driven by increasing demand for electric and solar-powered carts, rising golf participation, and growing use in resorts, airports, and gated communities beyond traditional golf courses.
- Key trends include the adoption of lithium-ion batteries, integration of smart connectivity features, and development of customizable, multi-purpose carts for commercial and recreational applications.
- The market remains competitive with key players such as Yamaha Motor, Club Car, EZ-GO, Marshell Green Power, and Star EV, focusing on product innovation, fleet electrification, and sustainability initiatives.
- North America leads with a 47% share, followed by Europe at 24% and Asia-Pacific at 23%, while the electric segment dominates the market with a 61% share due to lower emissions and operating costs.
Market Segmentation Analysis:
By Fuel
The electric segment dominated the Golf Cart market in 2024 with a 61% share. Growing environmental awareness and the shift toward sustainable mobility solutions are driving electric golf cart adoption. These carts offer lower operating costs, quieter performance, and reduced emissions compared to gasoline models. Advancements in lithium-ion batteries have extended driving range and reduced charging time, increasing operational efficiency. Resorts, golf clubs, and gated communities are rapidly electrifying their fleets to meet green mobility standards, reinforcing the electric segment’s leadership across both developed and emerging regions.
- For instance, Club Car’s Onward High Performance model uses a 7.0 kWh lithium-ion battery and enables steep hill climbing with no need for frequent maintenance.
By Application
The golf course segment held the largest share of 48% in 2024, supported by the rising number of golf facilities worldwide and growing participation in the sport. Golf courses rely heavily on carts for efficient player mobility, course maintenance, and transportation of equipment. The segment’s growth is strengthened by modernization initiatives at golf resorts and clubs adopting electric fleets to enhance the player experience. Increasing tourism and luxury hospitality investments further stimulate golf infrastructure expansion, ensuring consistent demand for high-performance and eco-friendly carts.
- For instance, Yamaha’s DRIVE2 electric carts are widely deployed across golf courses, offering improved torque via its lithium-ion powertrain and enabling smooth operation on inclines up to 25°.
By Seating Capacity
The 4-seater segment accounted for a 39% share of the Golf Cart market in 2024, driven by its versatility across commercial, recreational, and residential uses. These models are widely used in resorts, gated communities, and event venues for passenger transport. Their balanced capacity, compact design, and enhanced comfort features make them ideal for both leisure and utility operations. Manufacturers are introducing customizable seating and modular storage designs to meet varied consumer needs. The rising popularity of multi-passenger electric carts continues to sustain the dominance of the 4-seater configuration.
Key Growth Drivers
Rising Adoption Beyond Golf Courses
The Golf Cart market is expanding rapidly due to increasing use beyond traditional golf settings. Resorts, airports, industrial parks, and residential communities now deploy carts for efficient mobility and short-distance transport. Their compact size, low emissions, and cost efficiency make them ideal for these applications. The growing popularity of tourism destinations and large event venues continues to drive adoption, positioning golf carts as a practical urban mobility solution across commercial and recreational environments.
- For instance, EZ-GO, a division of Textron Inc., produces the Freedom RXV cart, which features IntelliBrake technology and AC drive motors for improved energy efficiency. The electric RXV models are capable of reaching speeds up to 31 km/h (19 mph) on level ground.
Shift Toward Electric and Sustainable Mobility
The growing demand for eco-friendly vehicles has significantly boosted electric golf cart adoption. Electric models provide lower operational costs, reduced noise, and zero tailpipe emissions compared to gasoline versions. Government incentives promoting clean mobility and technological improvements in lithium-ion batteries further enhance performance and charging efficiency. As sustainability becomes a core purchasing factor across industries, electric golf carts are emerging as the preferred choice for resorts, clubs, and residential developments.
- For instance, Star EV, under JH Global Services Inc., offers the Capella series with options for lithium battery packs, such as a 105 Ah model with a power capacity of 5.04 kWh. These vehicles have an estimated range of 30 to over 60 miles per charge, depending on the model and battery configuration.
Expansion of Smart and Connected Golf Carts
The integration of digital and telematics technologies is transforming the golf cart market. Connected golf carts equipped with GPS tracking, fleet monitoring, and mobile app control improve navigation and operational management. These smart systems enhance user convenience, enable predictive maintenance, and ensure efficient fleet utilization. Manufacturers are leveraging IoT and cloud-based platforms to deliver real-time analytics and performance optimization, supporting demand for intelligent, user-friendly mobility solutions in both recreational and commercial environments.
Key Trends & Opportunities
Integration of Lithium-Ion Battery Technology
The transition from lead-acid to lithium-ion batteries marks a major technological shift in the market. Lithium-ion technology offers longer battery life, faster charging, and reduced maintenance requirements. It also lowers vehicle weight, improving energy efficiency and driving range. Manufacturers are investing in advanced battery management systems to ensure safety and optimize performance. The increasing affordability of lithium-ion batteries presents strong growth opportunities, especially for fleet operators seeking durable and sustainable solutions.
- For instance, HDK Electric Vehicles offers various golf carts, utility vehicles, and electric shuttles featuring lithium-ion batteries and other advancements for improved performance and reliability. The company has a global dealer network and uses advanced technology from the USA.
Growing Popularity of Customizable and Multi-Purpose Carts
Demand for personalized and multi-purpose golf carts is on the rise, driven by user preferences for comfort and functionality. Modern designs now feature advanced suspension systems, infotainment options, and weather-resistant enclosures. Commercial users, including hotels and industrial facilities, seek customized carts with enhanced cargo capacity and safety features. This trend encourages manufacturers to offer modular models with flexible seating and storage configurations, expanding their appeal across diverse applications.
- For instance, Guangdong Lvtong New Energy Electric Vehicle Technology Co., Ltd. launched its LT-A627.H8 cargo car series, which is equipped with a 4,000-watt motor and has a loading capacity of 2 people and a cargo box. The LT-A627.GC model, a 2-seater housekeeping car, also has a 4,000-watt motor and a 450 kg loading capacity.
Key Challenges
High Initial Costs and Battery Replacement Expenses
The high upfront cost of advanced golf carts, especially electric models, remains a major restraint. Incorporating lithium-ion batteries and smart technologies increases production costs, limiting accessibility for smaller businesses. Battery replacement expenses and maintenance further impact ownership economics. Although long-term operating costs are lower, the initial investment poses a challenge for widespread adoption, particularly in price-sensitive regions.
Limited Charging Infrastructure and Range Constraints
Despite improvements in battery technology, limited charging infrastructure hinders electric golf cart expansion in some regions. Restricted access to fast-charging facilities and concerns about driving range discourage adoption in large resorts and commercial complexes. Manufacturers must focus on extending range capacity and developing portable charging solutions. Addressing these limitations through infrastructure investment and innovation will be critical to ensuring steady market growth and broader electric vehicle integration.
Regional Analysis
North America
North America held a 47% share of the Golf Cart market in 2024, driven by widespread adoption across golf courses, resorts, and residential communities. The United States remains the leading contributor due to the strong golfing culture, well-developed leisure infrastructure, and growing preference for electric models. Expanding applications in airports, universities, and industrial complexes also fuel demand. Manufacturers in the region focus on smart fleet management and sustainable mobility solutions. Supportive regulations for low-speed electric vehicles further strengthen North America’s leadership in both recreational and commercial segments of the market.
Europe
Europe accounted for a 24% share of the Golf Cart market in 2024, supported by the region’s strong focus on sustainability and tourism development. Countries such as the United Kingdom, France, and Germany are investing in electric mobility solutions within resorts, golf clubs, and public parks. The rise of eco-friendly tourism and urban mobility programs is boosting electric cart deployment. Strict emission norms and government incentives for clean transport promote fleet electrification. Manufacturers are introducing compact, energy-efficient models tailored to European infrastructure, enhancing adoption across hospitality and recreational sectors.
Asia-Pacific
Asia-Pacific captured a 23% share of the Golf Cart market in 2024, fueled by rapid infrastructure development and expanding leisure activities. China, Japan, India, and South Korea are major markets, with growing adoption in resorts, gated communities, and industrial parks. The rising popularity of golf as a recreational sport, combined with increasing urbanization, drives steady market growth. Government initiatives supporting electric mobility and technological innovation in battery systems strengthen regional competitiveness. Expanding tourism and hospitality sectors continue to create opportunities for both local and international golf cart manufacturers.
Rest of the World
The Rest of the World region accounted for a 6% share of the Golf Cart market in 2024, driven by growing tourism infrastructure and adoption in commercial services. Countries in the Middle East, Africa, and Latin America are witnessing rising use of golf carts in resorts, airports, and real estate developments. Expanding investments in hospitality and luxury tourism projects further stimulate demand. However, limited charging infrastructure and high import costs constrain widespread adoption. Ongoing partnerships between global manufacturers and regional distributors are improving product availability and supporting gradual market expansion
Market Segmentations:
By Fuel
- Gasoline
- Electric
- Solar-powered
By Application
- Golf courses
- Commercial services
- PTV/SLV
By Seating Capacity
- 2-Seater
- 4-Seater
- 6-Seater
- Others
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The competitive landscape of the Golf Cart market is shaped by leading players such as Yamaha Motor Co., Ltd., Club Car, LLC, EZ-GO (Textron Inc.), Marshell Green Power Co., Ltd., Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd., Guangdong Lvtong New Energy Electric Vehicle Technology Co., Ltd., GUANGZHOU LANGQING ELECTRIC CAR CO., LTD., JH Global Services, Inc. (Star EV), Tomberlin Electric Vehicles, and HDK Electric Vehicles. These companies compete through innovations in electric and solar-powered golf carts, battery technology, and design efficiency. Yamaha and Club Car focus on expanding smart electric models with enhanced performance and connectivity. EZ-GO emphasizes lithium-ion battery integration and fleet management systems for commercial applications. Chinese manufacturers such as Marshell and Lvtong lead in affordable electric carts, supporting strong export growth. Strategic partnerships, technological upgrades, and sustainability-driven product lines define the market’s competition as companies aim to serve diverse applications across leisure, tourism, and mobility sectors.
Key Player Analysis
- Yamaha Motor Co., Ltd.
- Club Car, LLC
- EZ-GO (Textron Inc.)
- Marshell Green Power Co., Ltd.
- Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd.
- Guangdong Lvtong New Energy Electric Vehicle Technology Co., Ltd.
- GUANGZHOU LANGQING ELECTRIC CAR CO., LTD.
- JH Global Services, Inc. (Star EV)
- Tomberlin Electric Vehicles
- HDK Electric Vehicles
Recent Developments
- In August 2025, EZ-GO (Textron Inc.) introduced an enhanced RXV for the 2026 model year. The update targets fleet performance and golfer comfort.
- In August 2024, Club Car delivered a new fleet of golf and utility vehicles to St Andrews Links, one of the world's most renowned golf destinations. This delivery underscores Club Car's role in providing high-quality vehicles to prestigious golf courses globally.
- In January 2024, Yamaha Golf-Car Company (YGC) developed a hydrogen-powered engine golf cart concept model, the DRIVE H2. The concept model is the first of its kind and is currently on display at the PGA Show in Orlando, Florida.
- In 2023, Yamaha Motor Europe N.V. introduced its 2024 line-up of lightweight vehicles, which includes golf cars, light utility vehicles, and personal transport vehicles.
Report Coverage
The research report offers an in-depth analysis based on Fuel, Application, Seating Capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of electric golf carts will continue to rise due to sustainability goals.
- Lithium-ion battery technology will improve efficiency and extend driving range.
- Smart connectivity and GPS-enabled fleet management systems will become standard features.
- Manufacturers will focus on lightweight materials to enhance performance and reduce maintenance costs.
- Solar-powered golf carts will gain traction in resorts and eco-friendly facilities.
- Customizable designs will attract both commercial and residential buyers.
- Demand for multi-passenger carts will increase across resorts, airports, and campuses.
- Asia-Pacific will experience strong growth with expanding tourism and leisure infrastructure.
- North America will maintain leadership through technological innovation and high adoption in golf resorts.
- Partnerships between manufacturers and fleet operators will strengthen after-sales service and distribution networks.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion Beyond Golf Courses
Golf carts are increasingly used in resorts, airports, industrial parks, and residential communities for efficient short-distance transport, driven by their compact size, low emissions, and cost efficiency. This diversification of applications is broadening the market beyond traditional golf course use.
Shift Toward Electric and Sustainable Mobility
Growing environmental awareness and government incentives are accelerating the adoption of electric golf carts, which offer lower operational costs, reduced noise, and zero tailpipe emissions. Technological advancements in lithium-ion batteries further enhance performance and charging efficiency.
Integration of Smart and Connected Technologies
The adoption of GPS tracking, fleet monitoring, and mobile app controls in golf carts is improving operational management and user convenience. These smart features are increasingly demanded by fleet operators in both recreational and commercial settings.
Rising Demand for Customizable and Multi-Purpose Carts
End-users are seeking golf carts with advanced comfort, modular seating, and enhanced cargo capacity for diverse applications in hospitality, tourism, and industrial sectors. Manufacturers are responding with customizable designs, expanding the market’s appeal.
Growth in Tourism and Leisure Infrastructure
Investments in golf resorts, luxury hospitality, and recreational facilities, especially in Asia-Pacific and emerging markets, are driving demand for high-performance and eco-friendly golf carts to support expanding tourism and leisure activities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Golf Cart market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Golf Cart market projected to grow between 2025 and 2032?
Which Golf Cart market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Golf Cart market?
Who are the leading companies in the Golf Cart market?
Which region commanded the largest share of the Golf Cart market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel
- 1.2.1 Gasoline
- 1.2.2 Electric
- 1.2.3 Solar-powered
- 1.3 By Application
- 1.3.1 Golf courses
- 1.3.2 Commercial services
- 1.3.3 PTV/SLV
- 1.4 By Seating Capacity
- 1.4.1 2-Seater
- 1.4.2 4-Seater
- 1.4.3 6-Seater
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.05 billion → 2032: USD 3 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Golf Cart Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Golf Cart Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Golf Cart Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Golf Cart Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Golf Cart Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Golf Cart Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Golf Cart Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Golf Cart Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.05 billion → 2032: USD 3 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Golf Cart Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gasoline
- 12.3.7.2 Electric
- 12.3.7.3 Solar-powered
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Golf courses
- 12.4.7.2 Commercial services
- 12.4.7.3 PTV/SLV
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Seating Capacity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 2-Seater
- 12.5.7.2 4-Seater
- 12.5.7.3 6-Seater
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Golf Cart End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Golf Cart Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Golf Cart Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Golf Cart Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yamaha Motor Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Club Car, LLC
- 18.4 EZ-GO (Textron Inc.)
- 18.5 Marshell Green Power Co., Ltd.
- 18.6 Suzhou Eagle Electric Vehicle Manufacturing Co., Ltd.
- 18.7 Guangdong Lvtong New Energy Electric Vehicle Technology Co., Ltd.
- 18.8 GUANGZHOU LANGQING ELECTRIC CAR CO., LTD.
- 18.9 JH Global Services, Inc. (Star EV)
- 18.10 Tomberlin Electric Vehicles
- 18.11 HDK Electric Vehicles
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

