
Market Overview
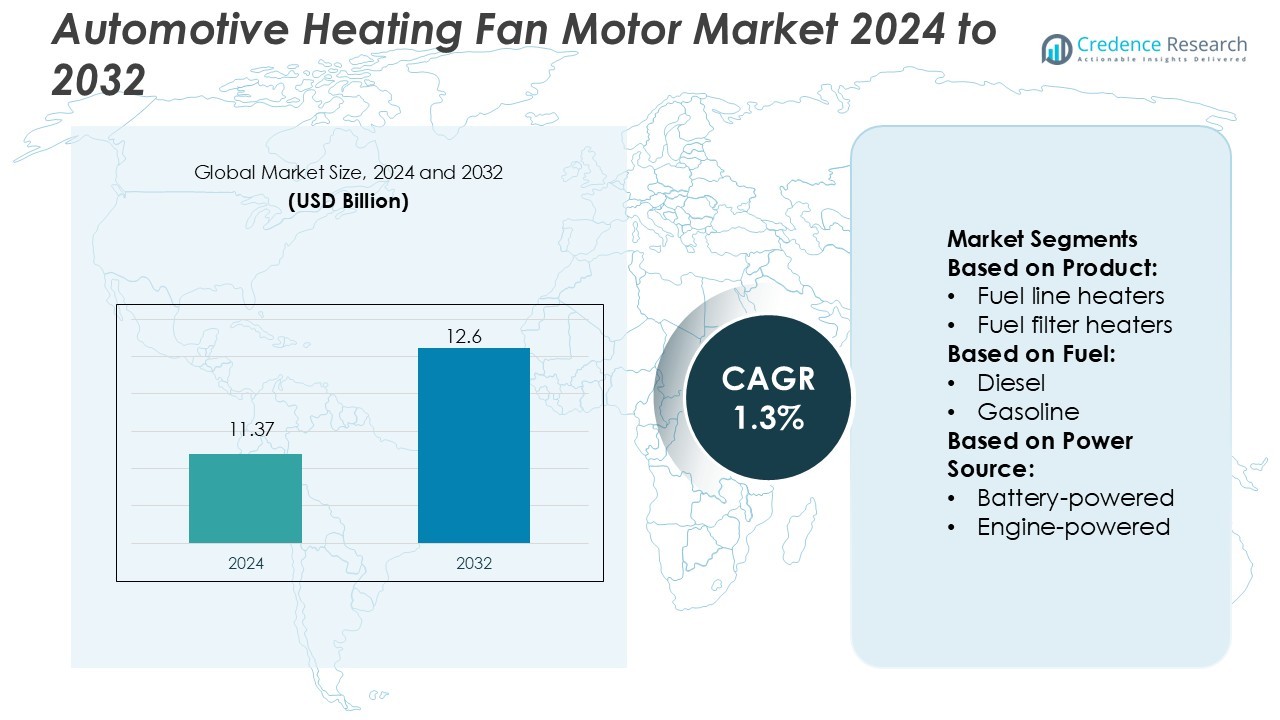
Automotive Heating Fan Motor Market size was valued USD 11.37 billion in 2024 and is anticipated to reach USD 12.6 billion by 2032, at a CAGR of 1.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Heating Fan Motor Market Size 2024 | USD 11.37 Billion |
| Automotive Heating Fan Motor Market, CAGR | 1.3% |
| Automotive Heating Fan Motor Market Size 2032 | USD 12.6 Billion |
The market is headed by major players such as Daikin Industries Ltd, Hitachi Ltd., Lennox International, Mitsubishi Electric Corporation, Rheem Manufacturing Company, Johnson Controls Inc., Emerson Electric Co., Midea Group, Robert Bosch GmbH, and Trane, each leveraging advanced technology, strong OEM ties, and global service networks to shape the landscape. In regional terms, North America leads the Automotive Heating Fan Motor Market with exactly 31.2% market share, driven by its mature automotive ecosystem, high penetration of electric vehicles, and demand for premium cabin comfort systems.
Market Insights
- The Automotive Heating Fan Motor Market was valued at USD 11.37 billion in 2024 and is projected to reach USD 12.6 billion by 2032, growing at a CAGR of 1.3%.
- Rising adoption of electric and hybrid vehicles drives demand for energy-efficient and battery-powered heating fan motors.
- Trends such as miniaturization, brushless DC motors, and integration with advanced HVAC systems enhance performance and passenger comfort.
- The market is moderately consolidated, with key players focusing on OEM partnerships, technological innovation, and global service networks to maintain competitive positioning.
- North America leads with 31.2% market share, followed by Asia-Pacific with growing adoption in electric and hybrid vehicles, Europe with strong regulatory standards, and emerging markets in Latin America and the Middle East & Africa contributing to aftermarket and fleet expansion.
Market Segmentation Analysis:
By Product
The Automotive Heating Fan Motor Market is segmented into fuel line heaters, fuel filter heaters, tank heaters, and fuel pump heaters. Fuel line heaters dominate with a 37% market share due to their critical role in preventing fuel thickening and maintaining flow efficiency in cold environments. These heaters are widely adopted in commercial and passenger vehicles operating in low-temperature regions. Their effectiveness in improving cold-start performance and reducing engine wear drives steady demand. Advancements in electric heating elements and compact designs further enhance efficiency, supporting growth in hybrid and diesel-powered vehicles.
- For instance, Daikin Industries, Ltd. has developed a fluoro‑polymer‑based fuel‑line hose material that supports continuous operation at temperatures down to −40 °C and withstands 100 000 cycles of flexing while maintaining less than 0.1 g/day fuel permeation.
By Fuel
Diesel-based systems lead the market with a 54% share, supported by their extensive use in commercial trucks, buses, and off-highway vehicles. Diesel engines are more susceptible to fuel gelling and viscosity changes at low temperatures, making heating solutions essential for reliability. The growing adoption of diesel vehicles in logistics and construction sectors reinforces this dominance. Gasoline and alternative fuel categories also witness gradual adoption, driven by innovations in biofuel compatibility and energy-efficient heating mechanisms designed for emerging hybrid powertrains.
- For instance, Mitsubishi Electric offers fan-blower motors for HVAC applications with a 30 W power rating and 5/16" shaft diameter and 1½" shaft length. Search results confirm a specific model, the E22C30300 Indoor Fan Motor, matches these output and bracket dimensions.
By Power Source
Engine-powered systems account for a 61% share in the Automotive Heating Fan Motor Market, primarily due to their established use in conventional vehicles. These systems utilize engine waste heat for fuel warming, offering reliable performance and low maintenance. However, the battery-powered segment is expanding rapidly with the rise of electric and hybrid vehicles. Growing demand for energy-efficient, electronically controlled heating systems accelerates innovation in compact, low-voltage designs. The transition toward electrified mobility is expected to shift market preference gradually toward battery-powered heating fan motors for enhanced efficiency and sustainability.
Key Growth Drivers
Increasing Vehicle Comfort and Climate Control Expectations
Consumers now expect enhanced thermal comfort and sophisticated climate control systems in vehicles. Heating fan motors have become integral to delivering rapid cabin heating and defrost functions, especially in cold climates. OEMs are responding by integrating variable‑speed brushless motors and electronically controlled modules in HVAC systems to improve response times and durability. As vehicle listings include multi‑zone heating and remote pre‑conditioning features, demand for more advanced and reliable heating fan motors increases further.
- For instance, Bosch’s EC motor for electric cooling fans supports a power range of 500 W to 850 W, offers a service life exceeding 8,000 h and retains high efficiency in harsh ambient conditions.
Rise of Electric and Hybrid Vehicles Requiring Dedicated Heating Systems
Electrified vehicles often lack the waste‑heat resources of internal combustion engines, which drives the need for electrically powered heating fan motors. Manufacturers are developing compact, high‑efficiency motors capable of low‑voltage operation and rapid airflow generation for cabin climate control. These motors help preserve driving range by optimizing energy consumption. Automakers offering EV and PHEV models are accelerating adoption of such dedicated heating fan solutions.
- For instance, Lochinvar’s CENTRUS™ Residential Hydronic Heat Pump delivers up to 41,000 Btu/hr (approximately 12.0 kW). It delivers up to 34,800 Btu/hr (approximately 10.2 kW). The unit has a peak Coefficient of Performance (COP) of up to 6.0 at a 95°F leaving-water temperature.
Expansion of Vehicle Production and After‑Replacement Markets in Emerging Regions
Emerging markets are experiencing rising vehicle ownership alongside growing environmental and regulatory pressures. This trend catalyzes demand for heating fan motors that support varied powertrains (diesel, gasoline, electric) and cabin climate systems. In addition, as fleets age in these regions, aftermarket demand for heating fan motor replacements grows significantly. Manufacturers and suppliers are expanding production capacity and localization to address these growth opportunities.
Key Trends & Opportunities
Adoption of Brushless DC (BLDC) and Variable‑Speed Motor Technologies
Automotive heating fan motors are increasingly shifting from traditional brushed designs to brushless DC and variable‑speed configurations. These offer quieter operation, longer life, and fine motor speed control for optimized airflow and energy efficiency. Suppliers are leveraging these motor innovations to target premium vehicle segments and enhance passenger comfort without compromising powertrain efficiency.
- For instance, Daikin’s FIT heat pump model DH6VS features a variable-speed swing compressor and inverter technology, with rated performance of up to 19.0 SEER2, up to 12 EER2 and up to 8.8 HSPF2 for capacities from 1.5 to 5 tons.
Integration with Smart HVAC Systems and IoT Connectivity
Heating fan motors are now being integrated into connected HVAC systems that monitor cabin conditions, user preferences, and vehicle data. Real‑time control enables dynamic motor speed adjustment and predictive maintenance alerts. This digitalization presents an opportunity for suppliers to offer motors with telemetry, diagnostics, and adaptive control capabilities-especially relevant in connected vehicles and upcoming autonomous platforms.
- For instance, Bosch has released new inverter-driven mini-split and ducted heat pump systems that use the low-GWP refrigerant R-454B (GWP: 470). These include the Climate 5000 Ductless Systems and IDS Family heat pumps.
Key Challenges
Balancing Motor Efficiency, Size, and Cost for Diverse Powertrains
Designing heating fan motors that meet efficiency, compactness, and affordability requirements across gasoline, diesel, hybrid, and electric platforms is complex. Motors must perform reliably in harsh automotive environments while minimizing energy draw and cost. Suppliers face the challenge of aligning design innovation with stringent cost and packaging constraints to achieve broad market applicability.
Supply Chain and Material Pressure Amid Increasing Electrification
As electrification accelerates, demand for precise motor components such as rare earth magnets and high‑grade copper wire rises sharply. Supply chain constraints and fluctuating raw material prices can impact motor cost, production timelines, and scalability. Suppliers need to secure resilient sourcing strategies and adapt manufacturing processes to maintain competitiveness and meet growing global vehicle production.
Regional Analysis
North America
North America holds approximately 31% of the Automotive Heating Fan Motor Market, supported by strong vehicle production, advanced comfort features, and harsh winter climates that demand efficient heating solutions. The region benefits from early adoption of electric vehicle technologies and deep aftermarket penetration. Automated climate control systems in the U.S. and Canada fuel replacement demand while OEMs integrate advanced fan motors for enhanced cabin comfort. Manufacturers are expanding localized manufacturing and service networks to support rapid growth in this market.
Europe
Europe captures an estimated 27% market share in the Automotive Heating Fan Motor sector, driven by stringent emission and energy‑efficiency regulations and high consumer expectations for vehicle comfort. Sales in Germany, France, and the U.K. lead due to large premium vehicle markets and cold‑weather conditions. The region sees growth from both OEM‑fit and aftermarket heating fan motors as fleets age and climate demands rise. Local suppliers are investing in green manufacturing and lightweight motor solutions to align with regional sustainability goals.
Asia‑Pacific
Asia‑Pacific accounts for around 35% of the Automotive Heating Fan Motor Market. Rapid growth in China, India, Japan, and South Korea drives demand through rising vehicle production and adoption of premium features. Emerging markets within the region also present strong aftermarket potential as vehicle ownership expands. Local OEMs and suppliers focus on cost‑efficient heater‑fan systems adapted for varied fuel types and powertrains. The region’s growing EV and hybrid fleet further underscores the need for electrically‑powered heating fan motors.
Latin America
Latin America holds roughly 5% of the global Automotive Heating Fan Motor Market, with Brazil and Mexico leading demand. The region’s growth stems from rising vehicle production, improving wealth levels, and increasing aftermarket replacement needs. Harsh seasonal conditions in certain areas boost demand for robust heating fan motors in commercial and passenger vehicles. Infrastructure improvements and expansion of vehicle fleets create opportunities for suppliers to enter localized markets and develop region‑specific heating solutions.
Middle East & Africa
The Middle East & Africa region commands about 2% of the market share for automotive heating fan motors. Growth is influenced by fleet expansion in GCC countries and increased demand for vehicle comfort systems under extreme ambient conditions. Local vehicle manufacturers and regional service providers are beginning to offer upgraded HVAC components, including heating fan motors. While the region’s manufacturing base is limited, ongoing infrastructure development and rising mobility demand signal future growth opportunities for heating fan motor suppliers.
Market Segmentations:
By Product:
- Fuel line heaters
- Fuel filter heaters
By Fuel:
- Diesel
- Gasoline
By Power Source:
- Battery-powered
- Engine-powered
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Automotive Heating Fan Motor Market players such as Daikin Industries, Ltd, Hitachi, Ltd., Lennox International, Mitsubishi Electric Corporation, Rheem Manufacturing Company, Johnson Controls, Inc., Emerson Electric Co., Midea Group, Robert Bosch GmbH, and Trane. The Automotive Heating Fan Motor Market features moderate consolidation, driven by technological innovation and efficiency improvements. Manufacturers focus on developing compact, durable, and energy-efficient motors suitable for passenger cars, commercial vehicles, and electric mobility platforms. The market emphasizes advanced brushless DC motors for high airflow with minimal noise, integrated climate control modules, and high-temperature-resistant components for harsh operating conditions. Continuous R&D and adoption of battery-powered and engine-powered designs enhance performance and reliability. Growing OEM integration, aftermarket replacement demand, and the expansion of electric and hybrid vehicle fleets further strengthen market growth and competitive dynamics across global regions.
Key Player Analysis
- Daikin Industries, Ltd
- Hitachi, Ltd.
- Lennox International
- Mitsubishi Electric Corporation
- Rheem Manufacturing Company
- Johnson Controls, Inc.
- Emerson Electric Co.
- Midea Group
- Robert Bosch GmbH
- Trane
Recent Developments
- In January 2025, Midea introduced its Energy-Efficient Heat Pump Water Heater (HPWH) in North America. This innovative product highlights transitioning from conventional water heating methods to more sustainable, energy-efficient air-source technology.
- In December 2024, Daikin launched a new line of residential air-to-water heat pumps for single-family homes, utilizing propane (R290) as the refrigerant. This environmentally friendly solution offers efficient heating and hot water, supporting the growing demand for sustainable and energy-efficient heating technologies in residential markets.
- In September 2024, Mitsubishi Electric Corporation launched a new series of water-to-water heat pumps, branded Climaveneta EW-HT-G05, for commercial and industrial use, capable of producing high-temperature water.
- In August 2024, Carrier collaborated with Sibi, a technology platform for supply chains. Through this collaboration, Carrier aims to change the HVAC industry through improved data-driven efficiency and develop a new, enhanced supply chain management system.
Report Coverage
The research report offers an in-depth analysis based on Product, Fuel, Power Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow with increasing adoption of electric and hybrid vehicles.
- Demand will rise for energy-efficient, low-noise heating fan motors.
- OEM integration of advanced HVAC systems will drive motor adoption.
- Expansion of aftermarket replacement services will boost regional sales.
- Miniaturization and lightweight motor designs will support compact vehicle applications.
- Battery-powered motors will gain traction with electrification trends.
- Increasing focus on cabin comfort and climate control will stimulate demand.
- Technological innovations in brushless DC and variable-speed motors will enhance performance.
- Regional manufacturing and localized supply chains will improve market resilience.
- Government regulations on energy efficiency and emissions will encourage high-performance motor development.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Automotive Heating Fan Motor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automotive Heating Fan Motor Market projected to grow between 2025 and 2032?
Which Automotive Heating Fan Motor Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automotive Heating Fan Motor Market?
Who are the leading companies in the Automotive Heating Fan Motor Market?
Which region commanded the largest share of the Automotive Heating Fan Motor Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11.37 billion → 2032: USD 12.6 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Heating Fan Motor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Heating Fan Motor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Heating Fan Motor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Heating Fan Motor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Heating Fan Motor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Heating Fan Motor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Heating Fan Motor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Heating Fan Motor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11.37 billion → 2032: USD 12.6 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Heating Fan Motor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Heating Fan Motor Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Heating Fan Motor Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Heating Fan Motor Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

