
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Pillar Market Size 2024 | USD 7,524 million |
| Automotive Pillar Market, CAGR | 4.2% |
| Automotive Pillar Market Size 2032 | USD 10,456.6 million |
Market Overview:
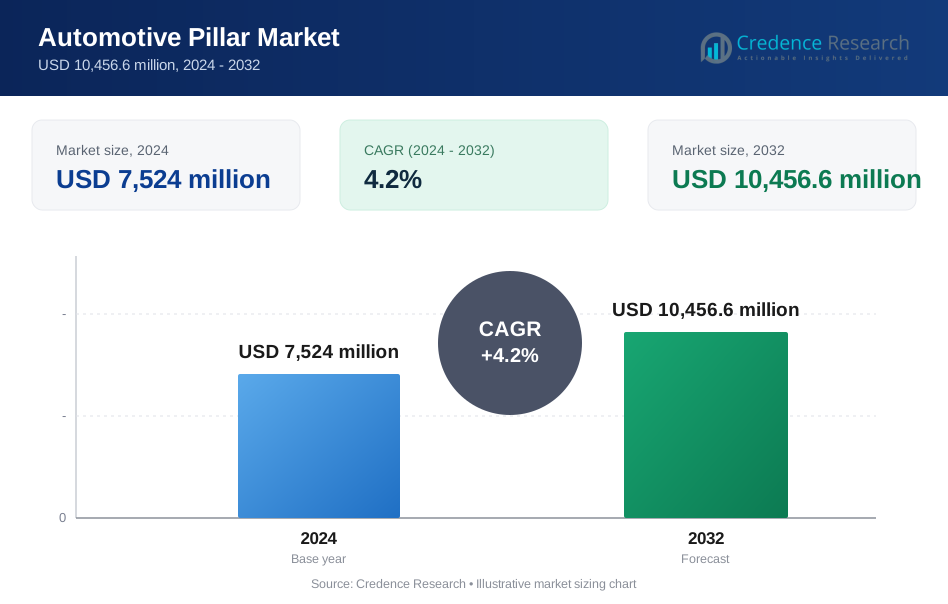
The Automotive Pillar Market is projected to grow from USD 7,524 million in 2024 to an estimated USD 10,456.6 million by 2032, with a compound annual growth rate (CAGR) of 4.2% from 2024 to 2032.
Key drivers of the automotive pillar market include the increasing demand for electric vehicles (EVs), advancements in autonomous driving technologies, and the ongoing evolution of smart manufacturing processes. As consumer preferences shift toward more sustainable and energy-efficient transportation options, automakers are investing heavily in the development of electric powertrains, battery technologies, and lightweight materials that support energy efficiency. Government regulations promoting fuel efficiency standards and emissions reductions are also driving innovation and market growth. Additionally, the rise of connected vehicle technologies, which enable real-time data exchange between vehicles, infrastructure, and service providers, is transforming the automotive landscape. Automakers are focusing on building next-generation vehicles with enhanced connectivity features, automation, and advanced driver-assistance systems (ADAS), which further stimulate demand for automotive pillars such as sensors, software platforms, and computing hardware.
Regionally, North America and Europe are leading the automotive pillar market due to robust government policies incentivizing the adoption of green vehicles, such as subsidies for electric vehicles and stricter emission standards. Major automakers in these regions are accelerating their transition to electric mobility and investing in innovative production technologies. In Asia Pacific, China, Japan, and South Korea are expected to witness significant growth, driven by rapid urbanization, increasing infrastructure for EV charging, and rising consumer adoption of advanced automotive technologies. Emerging markets in Latin America and the Middle East & Africa are also witnessing growth, as automakers expand their presence and cater to the growing demand for both conventional and electric vehicles.
Market Drivers:
Growing Demand for Electric Vehicles (EVs):
The increasing shift towards electric vehicles (EVs) is one of the key drivers of the automotive pillar market. As consumer preferences evolve towards more sustainable and energy-efficient transportation options, automakers are heavily investing in electric powertrains, battery technologies, and lightweight materials that support the growing demand for EVs. This shift is being propelled by government policies, incentives, and advancements in battery technology that have significantly reduced the cost of EVs. For instance, global electric vehicle sales reached approximately 14 million units in 2023, accounting for 14% of total global vehicle sales. According to the International Energy Agency (IEA), the number of electric vehicles on the road is projected to exceed 230 million by 2030, up from 26 million in 2023. In China, the world’s largest EV market, the sales of EVs accounted for over 25% of all car sales in 2023, driven by strong government incentives and the growing availability of EV charging infrastructure. In Europe, the adoption rate of electric vehicles is expected to rise to over 30% of new car sales by 2030, influenced by stricter emissions regulations and national EV programs such as subsidies and tax breaks.
Technological Advancements in Autonomous and Connected Vehicles:
Advancements in autonomous driving and connected vehicle technologies are reshaping the automotive industry. As automakers invest in autonomous vehicle (AV) technologies and smart manufacturing processes, there is a growing need for high-tech automotive pillars, including sensors, data processors, and vehicle-to-everything (V2X) systems. Autonomous vehicles (AVs) and the rise of advanced driver-assistance systems (ADAS) are becoming integral to modern transportation, improving safety, reducing accidents, and enhancing driving efficiency. For instance, the U.S. Department of Transportation invested over $1 billion in 2021 to promote the development of self-driving technologies. According to a report by the National Highway Traffic Safety Administration (NHTSA), fully autonomous vehicles could reduce traffic fatalities by up to 90%, which will directly impact the demand for ADAS components, including radar, lidar, cameras, and control units. As a result, the market for autonomous driving technologies is expected to grow rapidly, with the global autonomous vehicle market projected to exceed $60 billion by 2030, according to McKinsey & Company.
Government Regulations and Incentives:
Government regulations, particularly in the areas of fuel efficiency and carbon emissions, are major drivers of innovation in the automotive pillar market. Countries around the world are tightening emissions standards, incentivizing the transition to electric vehicles, and pushing for cleaner and more energy-efficient manufacturing processes. These regulations are creating a significant shift in the automotive industry, forcing companies to adapt and invest in new technologies. For instance, the European Union’s “Fit for 55” package aims to reduce carbon emissions by 55% by 2030 compared to 1990 levels, with the target for new cars to have 37.5% lower CO2 emissions by 2030. In the United States, the Biden administration’s target is for 50% of new car sales to be electric by 2030, with additional incentives such as $7,500 federal tax credits for consumers purchasing EVs. According to the World Bank, the adoption of EVs is projected to cut emissions in transportation by up to 30% by 2050, driving the demand for electric powertrains, battery systems, and related automotive pillars.
Advancements in Smart Manufacturing and Industry 4.0:
Industry 4.0 technologies such as artificial intelligence (AI), robotics, 3D printing, and data analytics are revolutionizing automotive manufacturing, leading to greater efficiency, cost savings, and production capabilities. These innovations allow automakers to streamline their production processes, reduce waste, and improve overall vehicle quality. As the demand for electric and autonomous vehicles increases, these technologies are becoming essential for automotive manufacturers to meet evolving market needs. For instance, the World Economic Forum (WEF) estimates that the adoption of smart manufacturing technologies in the automotive sector could increase productivity by 20-30% by 2030. Leading manufacturers like Volkswagen are already incorporating smart manufacturing solutions, including automation and AI-driven quality control, to enhance vehicle production. In 2022, Volkswagen reported that 60% of its production lines in Europe had been digitized, and the company aims to expand this further to meet future demand for electric vehicles. This shift toward Industry 4.0 is expected to help automakers achieve up to a 25% reduction in production costs by optimizing supply chain and assembly processes.
Market Trends:
Increasing Electrification and EV Infrastructure Development:
The global push for electrification in the automotive sector is one of the most significant market trends shaping the future of the industry. As governments and automakers continue to focus on reducing carbon emissions and promoting sustainable transport, electric vehicles (EVs) have become the central focus of innovation. This trend is not just about the vehicles themselves but also the entire ecosystem surrounding them, including EV infrastructure, battery technology, and charging solutions. The shift towards EVs is supported by strong governmental policies. For example, the European Commission has set ambitious targets under its “Green Deal,” aiming to have at least 30 million electric cars on European roads by 2030. Similarly, in the United States, the Biden administration’s $7.5 billion infrastructure investment in 2021 aims to accelerate the development of a national network of EV chargers. The expansion of EV charging stations is crucial to alleviating consumer range anxiety and is expected to drive widespread adoption of electric vehicles. For instance, the U.S. Department of Energy (DOE) reports that as of 2022, there were over 100,000 public charging stations across the country, with plans to increase that number to 500,000 by 2030. In China, the world’s largest EV market, the government invested $9 billion in 2021 to expand its electric vehicle infrastructure, with the aim to build over 1 million EV charging stations by 2025. The widespread infrastructure development is expected to boost EV adoption further, directly benefiting the automotive pillar market by increasing demand for EV-related components such as charging systems, battery technologies, and powertrains.
Focus on Autonomous Vehicle Technology and Smart Mobility Solutions:
The rapid advancement of autonomous vehicle (AV) technology is another critical trend influencing the automotive market. Autonomous vehicles are seen as the future of mobility, promising to improve road safety, reduce traffic congestion, and create more efficient transportation systems. As a result, automakers, technology companies, and governments are investing heavily in autonomous driving research, smart mobility solutions, and the necessary infrastructure to support these technologies. For instance, the U.S. National Highway Traffic Safety Administration (NHTSA) has established guidelines to facilitate the safe deployment of autonomous vehicles, emphasizing the need for standardized systems and data sharing between vehicles and infrastructure. In 2022, California’s Department of Motor Vehicles (DMV) reported that over 70 autonomous vehicle companies were testing vehicles on public roads in the state, highlighting the rapid development and testing of AVs. Furthermore, the U.S. Department of Transportation has allocated $200 million in 2022 to fund the development of smart transportation infrastructure, such as connected vehicle systems and vehicle-to-infrastructure communication, which is essential for the successful integration of AVs on public roads. The adoption of AVs is expected to generate substantial growth in demand for advanced sensors, machine learning algorithms, and AI-powered systems that are crucial for autonomous driving. A report from the World Economic Forum (WEF) estimates that the autonomous vehicle industry could generate over $800 billion in revenue by 2035. This trend is driving a significant transformation in the automotive pillar market, particularly in areas related to vehicle connectivity, sensors, and artificial intelligence.
Market Challenge Analysis:
High Costs of Electric Vehicle (EV) Production and Charging Infrastructure:
One of the primary challenges facing the automotive pillar market is the high cost of electric vehicle (EV) production and the associated charging infrastructure. Despite the significant advances in battery technology, the cost of electric vehicle batteries remains a substantial barrier to mass EV adoption. Although prices have decreased over the past decade, high-performance batteries still account for a large portion of an EV’s production cost. The automotive industry faces pressure to produce affordable electric vehicles that appeal to a broader consumer base. Additionally, automakers must balance performance and energy density with affordability, which adds further complexity to the manufacturing process. In addition to production costs, the development of EV charging infrastructure is another major challenge. Expanding the number of charging stations to support the growing EV fleet requires significant investment from both governments and private companies. For instance, the U.S. Department of Energy’s goal to install 500,000 charging stations by 2030 represents a massive undertaking, requiring billions in funding for new infrastructure and retrofitting existing ones. The lack of sufficient charging stations in certain regions contributes to “range anxiety” among consumers, further limiting EV adoption. Developing a robust and widely accessible charging infrastructure is necessary to overcome the challenge of EV adoption, but the costs and logistics involved create significant hurdles.
Regulatory Uncertainty and Evolving Emissions Standards:
Another critical challenge facing the automotive pillar market is the regulatory uncertainty and the evolving landscape of emissions standards. Governments around the world are introducing stringent emissions reduction targets to combat climate change, which is pushing the automotive industry toward electric and hybrid solutions. However, the regulatory environment is still in flux, with regulations varying greatly between regions, creating complexity for global automakers. For example, while the European Union has set clear targets through its “Fit for 55” package, the United States’ emissions standards are shifting with changes in leadership and political priorities. This inconsistency presents challenges for automakers, as they must navigate the evolving regulatory landscape and ensure compliance across different jurisdictions. Additionally, as environmental regulations tighten, automakers face increasing pressure to meet new fuel efficiency and carbon emissions standards. The European Union has mandated that all new cars sold from 2035 onwards be zero-emission, pushing the industry to accelerate EV production. Similarly, in the U.S., the Environmental Protection Agency (EPA) is tightening emissions standards, particularly for light-duty vehicles, which will require automakers to further invest in clean technologies and alternative fuel solutions. These evolving regulations, while aimed at reducing environmental impact, add uncertainty to long-term planning for automakers, as they must anticipate changes in policies and adapt their product lines accordingly. Furthermore, stricter emissions laws increase the need for investment in clean technologies, which can strain the financial resources of automakers, especially smaller companies that lack the capital to make the necessary changes.
Market Segmentation Analysis:
By Type
The automotive pillar market is segmented based on the types of vehicles and automotive components that utilize these pillars. This includes electric vehicles (EVs), hybrid vehicles, and traditional internal combustion engine (ICE) vehicles. The increasing shift towards EVs is expected to dominate the market, as demand for components that support electric powertrains, batteries, and energy-efficient features grows. Additionally, hybrid vehicles, which combine traditional combustion engines with electric power, will continue to see strong adoption. The demand for lightweight materials and advanced manufacturing processes is also increasing across these vehicle types to improve energy efficiency and performance.
By Technology
Technological advancements are key to the growth of the automotive pillar market. The major technologies driving the market include electric powertrain technologies, autonomous driving systems, connected vehicle solutions, and advanced driver-assistance systems (ADAS). As automakers invest heavily in electric mobility, the demand for advanced battery technologies, electric motors, and charging infrastructure will rise. Autonomous driving technologies, including sensors, machine learning algorithms, and V2X communication, are also shaping the market as vehicles become more connected and automated. Additionally, innovations in smart manufacturing processes, such as 3D printing and robotics, are improving production efficiency and reducing costs.
By End-User
The automotive pillar market caters to various end-users, primarily including original equipment manufacturers (OEMs) and aftermarket suppliers. OEMs, including large automotive manufacturers, are the primary consumers of automotive pillars, as they integrate these components into the production of new vehicles. With the shift towards electric and autonomous vehicles, OEMs are investing in cutting-edge technologies that meet the evolving market demands. Aftermarket suppliers, which provide replacement parts and services, are also a significant segment, catering to vehicle maintenance, repairs, and upgrades, especially in regions with a large number of legacy vehicles. The growing trend of vehicle electrification will drive aftermarket growth, as more consumers seek to retrofit existing vehicles with EV-compatible components.
Segmentation:
Based on Product Type:
- Electric Vehicles (EVs)
- Hybrid Vehicles
- Internal Combustion Engine (ICE) Vehicles
- Advanced Driver-Assistance Systems (ADAS)
- Autonomous Driving Components
- Connected Vehicle Technologies
Based on Technology:
- Electric Powertrain Technologies
- Autonomous Driving Systems
- Connected Vehicle Solutions
- Advanced Driver-Assistance Systems (ADAS)
- Battery Technologies
- Lightweight Materials & Manufacturing Technologies
- Smart Manufacturing Solutions
Based on End-User:
- Original Equipment Manufacturers (OEMs)
- Aftermarket Suppliers
- Vehicle Fleet Operators
- Automotive Component Suppliers
- Maintenance and Repair Service Providers
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America has emerged as a significant player in the automotive pillar market, driven primarily by the increasing adoption of electric vehicles (EVs) and government support for sustainable mobility. In the U.S., the electric vehicle market is projected to account for a growing share of the overall automotive market. As of 2023, EVs made up around 8-10% of total vehicle sales in the U.S., a figure that is expected to rise substantially by 2030 due to federal incentives and stricter emission regulations. The Biden administration has committed to ensuring that 50% of all new car sales are electric by 2030, which is expected to accelerate the transition toward EVs and stimulate demand for related automotive pillar technologies, including EV powertrains, batteries, and charging infrastructure. The U.S. Department of Energy has allocated funding to develop charging infrastructure, which is a key element for EV adoption. Currently, North America has over 100,000 public charging stations and plans to expand this network to 500,000 by 2030. Additionally, the North American Free Trade Agreement (NAFTA), now replaced by the United States-Mexico-Canada Agreement (USMCA), continues to provide an integrated market that supports automotive manufacturers in the region, facilitating the free flow of auto parts and vehicle production across borders. Canada has also committed to phasing out internal combustion engine (ICE) vehicles by 2035, which is pushing automakers to adapt to electric mobility. In Mexico, where automotive production has traditionally been a major economic sector, the demand for electric and hybrid vehicles is on the rise. The North American region collectively holds a significant share of the global automotive pillar market, estimated at 22-25% in 2023, and this is expected to grow as the region transitions toward a more sustainable and technologically advanced automotive future.
Europe
Europe has long been a leader in adopting green technologies and stricter environmental standards, making it a key region in the automotive pillar market. The European Union’s “Green Deal” and Fit for 55 packages are setting ambitious targets to reduce carbon emissions by 55% by 2030 and ensure that all new vehicles sold by 2035 are zero-emission. These policies are driving rapid growth in the electric vehicle market, with Europe accounting for over 20% of global EV sales in 2023. The European market is expected to continue expanding as governments across the continent introduce subsidies, tax incentives, and other policies to promote electric mobility. Germany, France, and the United Kingdom are leading the way, with the EU accounting for about 30-35% of the global automotive pillar market share. Germany, home to major automakers like Volkswagen, BMW, and Mercedes-Benz, has been at the forefront of transitioning toward electric and autonomous vehicle technologies. The German government has invested heavily in EV infrastructure, with plans to install 1 million charging stations by 2030. The UK, meanwhile, has committed to banning the sale of new petrol and diesel cars by 2030, further accelerating the shift to electric and hybrid vehicles. Other European countries, such as Norway and the Netherlands, are also seeing rapid adoption of electric vehicles. Norway has already reached 54% EV market share for new car sales, with the government offering tax breaks, exemptions from tolls, and free parking for EV owners.
Asia Pacific
The Asia Pacific region is poised to dominate the global automotive pillar market, with China being the largest and fastest-growing market for both electric and conventional vehicles. In 2023, China accounted for nearly 50% of global EV sales, with over 6 million electric vehicles sold in the country, more than any other region. The Chinese government’s aggressive policies, including subsidies for electric vehicles, mandates for automakers to produce a certain percentage of electric or hybrid vehicles, and an extensive charging infrastructure rollout, have positioned the country as a global leader in EV adoption. Japan and South Korea are also critical markets for automotive pillar technologies, with companies like Toyota, Honda, Hyundai, and Kia heavily investing in electric and hybrid vehicle development. Japan, with its emphasis on hybrid vehicles and hydrogen fuel cell technologies, holds a significant share of the global automotive pillar market, particularly in the area of advanced powertrains. South Korea, home to Hyundai and LG Chem, is driving growth in battery production and EV component manufacturing. India, while still in the early stages of EV adoption, is seeing rapid growth in electric mobility due to government incentives and the rising availability of EV models. The Indian government has set a target to achieve 30% EV penetration by 2030, and the country is rapidly expanding its charging infrastructure to accommodate this growth.
Key Player Analysis:
- Magna International Inc.
- Faurecia
- Lear Corporation
- Benteler International AG
- Plastic Omnium
- Continental AG
- Toyota Boshoku Corporation
- Adient PLC
- Sejong Industrial Co. Ltd.
- Kautex Textron
Competitive Analysis:
The competitive landscape of the automotive pillar market is highly dynamic, driven by a mix of established automakers, new entrants, and technology firms focused on electric vehicles (EVs), autonomous driving, and advanced manufacturing solutions. Major global automakers such as Volkswagen, Toyota, General Motors (GM), and Ford are leading the charge, investing heavily in EV production, battery technologies, and autonomous vehicle systems. Volkswagen, for example, has committed to becoming the world's largest producer of electric cars by 2025, with plans to invest billions in electrifying its vehicle lineup. In North America, GM is transitioning its production lines to fully electric vehicles, with a target of launching 30 new electric vehicles by 2025. Alongside traditional automakers, tech companies such as Tesla, Google’s Waymo, and Nvidia are significant players in the autonomous vehicle space. Tesla continues to dominate the electric vehicle market with its innovative battery technologies and AI-driven autonomous features. Waymo, a leader in self-driving technology, has been making strides in developing fully autonomous, commercial-level ride-sharing services. Emerging market players, especially from Asia Pacific-including BYD and NIO in China-are challenging traditional automakers with more affordable EV options and rapid technological innovations in battery production and vehicle connectivity. The intense competition is further amplified by alliances and partnerships within the industry, such as GM’s collaboration with Honda on autonomous vehicle platforms and the growing collaboration between automakers and tech firms to develop autonomous and smart mobility solutions. Overall, the market is characterized by heavy investments in research and development, a drive towards vertical integration, and strategic partnerships aimed at capturing a larger share of the rapidly growing EV and autonomous vehicle sectors.
Recent Developments:
- In January 2024, Chevrolet launched the new Chevy Traverse, a full-size crossover SUV. The redesigned model features an innovative exterior, including a shark fin-style C-pillar that rises sharply just behind the rear door, levels off, and then slopes back down to the vehicle’s shoulder line.
- In March 2022, General Motors filed a patent for a transparent A-pillar design, aimed at enhancing the driver’s field of view through the windshield.
Market Concentration & Characteristics:
The automotive pillar market is moderately concentrated, with a few key players holding a significant share, but also a growing number of smaller companies and new entrants contributing to innovation and market growth. Large multinational automakers such as Volkswagen, Toyota, General Motors, Ford, and BMW dominate the industry, controlling a substantial portion of the market due to their extensive production capacity, global distribution networks, and established brand equity. These companies are heavily investing in electric vehicles (EVs), autonomous technologies, and smart manufacturing processes, which are expected to continue shaping the future of the automotive sector. Despite the dominance of traditional automakers, the market has seen the rise of disruptive new entrants, particularly in the electric vehicle space, including Tesla, NIO, and BYD, which are challenging established players with innovative technologies, more affordable EVs, and agile production methods. The market is also marked by a high degree of technological collaboration. Automakers are increasingly forming strategic partnerships with technology firms to accelerate the development of autonomous driving systems, battery technologies, and vehicle-to-everything (V2X) communication. For instance, General Motors has partnered with Cruise (its autonomous driving subsidiary) and Honda for joint development of next-gen EVs and autonomous platforms. Moreover, the rise of Asia Pacific companies like BYD in China, alongside Tesla, has contributed to a shift in global market dynamics, increasing competition and driving technological advancements. Overall, the automotive pillar market is evolving toward greater diversification, with a mix of established giants and agile startups vying for leadership in the fast-growing sectors of electric mobility and autonomous driving.
Report Coverage:
This report provides a comprehensive analysis of the automotive pillar market, focusing on key market dynamics, growth drivers, challenges, and trends shaping the industry from 2024 to 2032. It covers a broad range of factors influencing the market, including the increasing adoption of electric vehicles (EVs), advancements in autonomous vehicle technologies, and the growing emphasis on sustainability and energy efficiency in vehicle production. The report delves into the regional landscape, providing detailed insights into the performance and outlook of key regions, such as North America, Europe, and Asia Pacific, highlighting their respective market shares, growth drivers, and competitive dynamics. In particular, the rise of EV infrastructure, government policies promoting green transportation, and technological advancements in battery production and charging networks are examined. Additionally, the report covers market segmentation by product type, technology, and end-user, providing a granular view of the market’s structure and identifying emerging opportunities in areas such as connected vehicle technologies and smart mobility solutions. It also provides an in-depth competitive analysis, profiling leading players, such as Volkswagen, Tesla, Toyota, and General Motors, alongside emerging players and tech companies making significant contributions to EV and autonomous vehicle development. The market challenges, including high production costs, regulatory uncertainties, and evolving emissions standards, are also addressed. Overall, this report offers a forward-looking perspective on the automotive pillar market, helping stakeholders make informed decisions as they navigate a rapidly evolving industry.
Future Outlook:
- The Automotive Pillar Market will continue to benefit from increasing consumer preference for electric vehicles (EVs), which will drive demand for advanced components and technologies.
- Technological advancements in autonomous driving and smart manufacturing will further accelerate innovation in the automotive sector, creating new market opportunities.
- The ongoing shift towards sustainable transportation solutions will lead to greater investments in battery technologies, energy-efficient materials, and lightweight design features.
- Connected vehicle technologies, including real-time data exchange and vehicle-to-everything (V2X) communication, will reshape the way vehicles interact with infrastructure and other systems.
- The adoption of advanced driver-assistance systems (ADAS) will expand, increasing the demand for sensors, computing hardware, and software platforms that support vehicle automation.
- Stringent government regulations on emissions and fuel efficiency will continue to drive automakers towards green technologies and cleaner production methods.
- Increasing urbanization, particularly in Asia Pacific, will fuel the demand for more energy-efficient and compact vehicles that align with city living needs.
- OEMs will increasingly collaborate with tech companies to integrate AI, machine learning, and data analytics into vehicle systems, enhancing performance and safety.
- The development of EV charging infrastructure will support wider EV adoption, boosting growth in the automotive pillar market.
- Emerging markets will present significant growth opportunities as automakers expand their offerings to meet the rising demand for both conventional and electric vehicles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Electric Vehicles (EVs)
The rapid shift toward electric vehicles, supported by government incentives and consumer preference for sustainable transport, is driving demand for advanced automotive pillars such as battery systems, lightweight materials, and EV-specific components.
Technological Advancements in Autonomous and Connected Vehicles
Investments in autonomous driving and connected vehicle technologies are increasing the need for high-tech automotive pillars, including sensors, V2X systems, and computing hardware, as automakers race to deliver safer and smarter vehicles.
Government Regulations and Incentives
Stricter emissions standards and fuel efficiency regulations worldwide are compelling automakers to innovate, accelerating the adoption of electric powertrains, advanced driver-assistance systems, and energy-efficient manufacturing processes.
Advancements in Smart Manufacturing and Industry 4.0
The integration of AI, robotics, and digital manufacturing is enabling automakers to streamline production, reduce costs, and improve quality, which supports the efficient scaling of new automotive pillar technologies for EVs and autonomous vehicles.
Expansion of EV Charging and Mobility Infrastructure
Significant investments in EV charging networks and smart mobility infrastructure are alleviating range anxiety and supporting the broader adoption of electric and connected vehicles, thereby boosting demand for related automotive pillar components.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Automotive Pillar Market?
What factors are driving growth in the Automotive Pillar Market?
How does the rise of connected vehicle technologies impact the market?
Which regions are leading the Automotive Pillar Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Original Equipment Manufacturers (OEMs)
- 1.2.2 Aftermarket Suppliers
- 1.2.3 Vehicle Fleet Operators
- 1.2.4 Automotive Component Suppliers
- 1.2.5 Maintenance and Repair Service Providers
- 1.3 By Technology
- 1.3.1 Electric Powertrain Technologies
- 1.3.2 Autonomous Driving Systems
- 1.3.3 Connected Vehicle Solutions
- 1.3.4 Advanced Driver-Assistance Systems (ADAS)
- 1.3.5 Battery Technologies
- 1.3.6 Lightweight Materials & Manufacturing Technologies
- 1.3.7 Smart Manufacturing Solutions
- 1.4 By Product Type
- 1.4.1 Electric Vehicles (EVs)
- 1.4.2 Hybrid Vehicles
- 1.4.3 Internal Combustion Engine (ICE) Vehicles
- 1.4.4 Advanced Driver-Assistance Systems (ADAS)
- 1.4.5 Autonomous Driving Components
- 1.4.6 Connected Vehicle Technologies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,524 million → 2032: USD 10,456.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Pillar Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Pillar Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Pillar Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Pillar Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Pillar Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Pillar Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Pillar Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Pillar Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,524 million → 2032: USD 10,456.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Pillar Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Original Equipment Manufacturers (OEMs)
- 12.3.7.2 Aftermarket Suppliers
- 12.3.7.3 Vehicle Fleet Operators
- 12.3.7.4 Automotive Component Suppliers
- 12.3.7.5 Maintenance and Repair Service Providers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Electric Powertrain Technologies
- 12.4.7.2 Autonomous Driving Systems
- 12.4.7.3 Connected Vehicle Solutions
- 12.4.7.4 Advanced Driver-Assistance Systems (ADAS)
- 12.4.7.5 Battery Technologies
- 12.4.7.6 Lightweight Materials & Manufacturing Technologies
- 12.4.7.7 Smart Manufacturing Solutions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric Vehicles (EVs)
- 12.5.7.2 Hybrid Vehicles
- 12.5.7.3 Internal Combustion Engine (ICE) Vehicles
- 12.5.7.4 Advanced Driver-Assistance Systems (ADAS)
- 12.5.7.5 Autonomous Driving Components
- 12.5.7.6 Connected Vehicle Technologies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Pillar End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Pillar Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Pillar Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Pillar Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Magna International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Faurecia
- 18.4 Lear Corporation
- 18.5 Benteler International AG
- 18.6 Plastic Omnium
- 18.7 Continental AG
- 18.8 Toyota Boshoku Corporation
- 18.9 Adient PLC
- 18.10 Sejong Industrial Co. Ltd.
- 18.11 Kautex Textron
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

