
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aviation Crew Management System Market Size 2024 | USD 3,150 million |
| Aviation Crew Management System Market, CAGR | 7.3% |
| Aviation Crew Management System Market Size 2032 | USD 5,535 million |
Market Overview
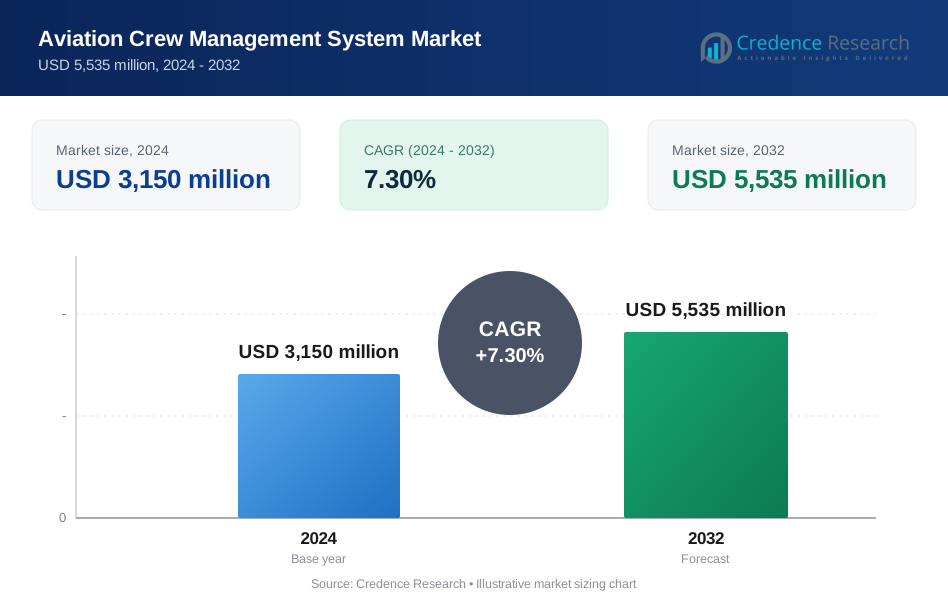
Aviation Crew Management System Market size was valued at USD 3,150 million in 2024 and is anticipated to reach USD 5,535 million by 2032, at a CAGR of 7.3% during the forecast period.
The Aviation Crew Management System market is driven by the rising demand for efficient crew scheduling, regulatory compliance, and cost reduction within the airline industry. As airlines strive to optimize operational efficiency and minimize delays, the adoption of advanced digital solutions for crew planning and management is accelerating. Integration of artificial intelligence and cloud-based technologies is further enhancing real-time decision-making and workforce management. The growing emphasis on crew safety, well-being, and fatigue management also supports market expansion. Additionally, the increasing complexity of flight operations and the need to adapt to dynamic flight schedules are encouraging airlines to invest in robust crew management systems. Market trends indicate a shift toward mobile-enabled platforms and data-driven analytics, empowering airlines to enhance crew productivity and passenger service quality. The continued digital transformation across the aviation sector is expected to propel further innovation and growth in the Aviation Crew Management System market.
The geographical analysis of the Aviation Crew Management System Market highlights strong adoption in North America and Europe due to advanced digital infrastructure, established airlines, and stringent regulatory requirements. Asia Pacific is experiencing rapid growth, driven by expanding airline fleets and increasing air traffic across countries like China, India, and Southeast Asia. The Middle East and Africa region is witnessing steady adoption as major airlines invest in operational excellence and advanced crew management solutions, while Latin America sees gradual progress as airlines modernize their IT systems. Among the key players shaping this market are CAE Inc. (U.S.), renowned for its comprehensive aviation training and management solutions, Jeppesen (U.S.), a Boeing subsidiary providing advanced digital crew management tools, and Lufthansa Systems GMBH & Co (Germany), a leading provider of integrated IT solutions for airlines worldwide. These companies drive innovation and set industry benchmarks in crew management technology.
Market Insights
- The Aviation Crew Management System Market is valued at USD 3,150 million in 2024 and is expected to reach USD 5,535 million by 2032, registering a CAGR of 7.3% during the forecast period.
- The market is driven by increasing airline operations, a strong focus on regulatory compliance, and the growing need for efficient crew scheduling and cost optimization.
- Leading trends include the rapid adoption of artificial intelligence, predictive analytics, and a shift toward cloud-based and mobile-enabled crew management platforms.
- Competitive analysis shows that established players like CAE Inc., Jeppesen, and Lufthansa Systems GMBH & Co are leading with advanced digital solutions, while regional providers also gain ground with tailored offerings.
- Market restraints include high initial implementation costs, integration challenges with legacy IT infrastructure, and rising concerns over data security and privacy.
- North America and Europe dominate the market due to advanced aviation ecosystems and early digital adoption, while Asia Pacific exhibits the fastest growth fueled by expanding fleets and increasing air traffic.
- Overall, the market is marked by continued digital transformation, with stakeholders focusing on innovation, operational efficiency, and improved crew well-being to stay competitive in a dynamic aviation environment.
Market Drivers
Surge in Airline Operations Drives Need for Efficient Crew Management
The rapid expansion of global airline operations fuels demand for advanced crew management solutions. Airlines increase fleet sizes and add more destinations, creating greater complexity in crew scheduling and assignment. Efficient management becomes critical for meeting operational requirements and maintaining flight punctuality. The Aviation Crew Management System Market addresses these challenges by providing airlines with integrated tools for scheduling, rostering, and real-time resource allocation. By automating manual processes, it reduces human error and improves overall efficiency. Airlines leverage these solutions to better match crew availability with flight needs, ensuring optimal resource utilization.
- For instance, the International Air Transport Association (IATA) reported that air traffic increased significantly in 2024, prompting airlines to enhance crew scheduling efficiency.
Regulatory Compliance and Safety Standards Shape System Adoption
Strict regulatory frameworks and evolving safety standards drive airlines to adopt sophisticated crew management systems. Authorities worldwide enforce compliance with labor laws, flight time limitations, and rest requirements for crew members. The Aviation Crew Management System Market offers functionalities that help airlines monitor compliance and generate accurate records. Automated alerts and audit trails support transparency and accountability in crew management. Meeting these requirements is essential to avoid penalties and maintain a strong reputation in the industry. It also supports airlines in achieving higher standards of operational safety.
- For instance, aviation regulatory bodies enforce strict compliance with flight time limitations and crew rest requirements to ensure operational safety.
Digital Transformation and Integration with Advanced Technologies
The ongoing digital transformation in aviation propels demand for modern crew management platforms. Airlines invest in cloud-based and mobile-enabled solutions that offer scalability and flexibility. The Aviation Crew Management System Market benefits from integration with artificial intelligence and data analytics, enabling predictive scheduling and real-time decision-making. These technologies help airlines anticipate disruptions, optimize crew deployment, and respond swiftly to operational changes. Enhanced connectivity supports seamless communication between crew members and operations control. This digital shift ensures higher efficiency and responsiveness in daily airline operations.
Focus on Crew Well-being and Operational Cost Control
Airlines place growing importance on crew well-being and cost control, further driving market growth. Fatigue management and support for crew work-life balance become key considerations for modern airlines. The Aviation Crew Management System Market provides tools to monitor fatigue risks and automate compliance with rest regulations. Automated scheduling also helps reduce overtime costs and administrative workload. By improving crew satisfaction, airlines achieve better retention rates and service quality. Investment in advanced management systems enables carriers to achieve both financial and operational objectives.
Market Trends
Growing Adoption of AI and Predictive Analytics in Crew Management
Artificial intelligence and predictive analytics have emerged as major trends in the Aviation Crew Management System Market. Airlines use AI-driven algorithms to optimize crew assignments, forecast disruptions, and automate rescheduling. It enhances operational efficiency and minimizes costly delays by analyzing large volumes of operational data in real time. Predictive tools help airlines anticipate challenges related to crew availability, flight delays, or regulatory compliance. AI-powered features support scenario planning and dynamic decision-making. These advancements position airlines to manage complex operations with greater agility.
- For instance, CAE signed a multi-year contract to provide its advanced Crew Management and Operations Control solutions to the Air India Group airlines, demonstrating the growing reliance on AI-powered crew management.
Integration with Broader Airline Operations and Ecosystem Platforms
Seamless integration with broader airline operational platforms has become a key market trend. The Aviation Crew Management System Market evolves to offer interoperability with flight operations, maintenance, and passenger service systems. This interconnected approach enables real-time data sharing and coordinated responses to operational changes. Airlines leverage integrated platforms to streamline processes, reduce duplication, and improve overall situational awareness. Enhanced data flow supports faster, data-driven decision-making at every level of the organization. It leads to stronger collaboration and greater operational resilience for airlines.
- For instance, airlines are increasingly adopting integrated platforms that combine crew management with other operational areas, such as flight operations and maintenance, leading to more cohesive management practices.
Increasing Shift Toward Cloud-Based and Mobile-Enabled Solutions
The transition to cloud-based and mobile-enabled crew management systems shapes the current market landscape. The Aviation Crew Management System Market witnesses a steady migration from legacy on-premises solutions to flexible cloud platforms. Cloud systems offer scalability, easier updates, and secure remote access, which cater to the needs of modern, distributed airline workforces. Mobile apps allow crew members to access schedules, swap shifts, and receive instant notifications on the go. This shift supports better communication and responsiveness across airline operations. It enables airlines to ensure business continuity even in dynamic environments.
Emphasis on Enhanced Crew Experience and Well-Being Tools
Airlines prioritize solutions that enhance crew experience and promote well-being, driving innovation in the Aviation Crew Management System Market. Modern systems incorporate tools for fatigue monitoring, work-life balance, and automated compliance with rest regulations. Airlines seek to reduce administrative burdens and increase transparency in scheduling. Improved digital interfaces allow crew members greater autonomy and visibility over their work commitments. These enhancements contribute to higher job satisfaction and improved staff retention. It reflects a broader industry trend toward supporting the mental and physical health of aviation professionals.
Market Challenges Analysis
Data Security Concerns and Regulatory Complexities
Ensuring robust data security is another key challenge for the Aviation Crew Management System Market. Airlines collect and manage sensitive personal information about crew members, which exposes them to risks of data breaches and cyberattacks. Stringent data protection regulations across different regions add layers of complexity to system deployment and management. Compliance with evolving legal frameworks demands continuous updates and proactive risk management. Failure to maintain high standards in data privacy can damage brand reputation and erode customer trust. It places significant pressure on vendors and airlines to prioritize security and compliance throughout the system lifecycle.
- For instance, aviation cybersecurity remains under pressure as legacy systems struggle to meet rising demand, with recent disruptions highlighting vulnerabilities even without direct cyberattacks.
High Implementation Costs and Legacy Integration Hurdles
High initial implementation costs present a significant challenge for airlines adopting advanced crew management systems. The Aviation Crew Management System Market faces barriers when airlines must invest in new hardware, software licenses, and extensive staff training. Many carriers operate with legacy IT infrastructure, which complicates integration and prolongs deployment timelines. Compatibility issues between new platforms and existing systems can disrupt daily operations and increase overall costs. Smaller airlines may hesitate to invest due to limited budgets and uncertain return on investment. It requires vendors to offer scalable and flexible solutions that minimize operational risks and transition costs.
Market Opportunities
Expansion of Digital Transformation Across Airlines Creates Growth Prospects
The acceleration of digital transformation in the aviation industry opens new opportunities for the Aviation Crew Management System Market. Airlines increasingly prioritize investment in advanced IT solutions to streamline crew management, improve decision-making, and enhance operational agility. The shift toward cloud-based platforms and mobile applications presents vendors with a chance to deliver scalable, user-friendly systems tailored to evolving airline needs. Emerging markets, where many carriers seek to modernize outdated infrastructure, offer significant potential for market expansion. It enables providers to tap into regions with rising air travel demand and a focus on efficiency. Tailored solutions for these markets can address unique regulatory and operational challenges, driving adoption.
Integration with Advanced Analytics and Ecosystem Platforms Drives Value
Integrating crew management systems with advanced analytics and broader airline ecosystem platforms creates valuable opportunities for the Aviation Crew Management System Market. Airlines benefit from seamless data exchange and coordinated workflows between crew scheduling, flight operations, and maintenance systems. Predictive analytics, powered by artificial intelligence, allows for proactive resource allocation and disruption management. It enhances airlines’ ability to anticipate operational challenges and adapt strategies quickly. The move toward interoperable platforms supports improved efficiency and fosters innovation across airline operations. Vendors can capitalize by developing solutions that deliver actionable insights and measurable performance gains.
Market Segmentation Analysis:
By Deployment Type:
The Aviation Crew Management System Market segments by deployment into On-Premise, Cloud-Based, and Hybrid solutions. On-premise systems offer airlines greater control over data and customization but often require significant upfront investments and in-house IT management. Many legacy carriers favor this model to maintain tight security protocols. Cloud-based solutions gain traction due to their scalability, cost-efficiency, and remote accessibility. Airlines adopting cloud platforms benefit from easier system upgrades and real-time data access, which support dynamic scheduling and operational flexibility. Hybrid models, combining on-premise and cloud elements, address the needs of airlines seeking a balance between security, compliance, and innovation. It allows organizations to transition gradually while maintaining business continuity.
By Application:
The market organizes by application into Crew Scheduling, Flight Operations, Training Management, and Compliance Management. Crew scheduling remains a critical focus, enabling airlines to allocate resources efficiently and minimize delays. Advanced algorithms and automated workflows enhance crew utilization and reduce manual workload. Flight operations applications integrate crew management with real-time flight data, supporting quick responses to disruptions and operational changes. Training management systems help carriers track qualifications, manage certifications, and schedule recurrent training, ensuring regulatory compliance and crew readiness. Compliance management modules further support adherence to complex labor regulations, flight time limitations, and safety standards.
By End Use:
Segmentation by end use divides the market into Commercial Aviation, Cargo Aviation, and Military Aviation. Commercial aviation leads the Aviation Crew Management System Market, driven by high passenger volumes, complex scheduling demands, and the need for stringent regulatory compliance. Airlines in this segment prioritize solutions that enhance operational efficiency and service quality. Cargo aviation operators invest in crew management tools to optimize staffing, especially as global logistics networks expand. Military aviation represents a specialized market segment with unique operational requirements, strict security standards, and an emphasis on mission readiness. It relies on robust, customizable systems that support both routine operations and rapid deployment scenarios.
Segments:
Based on Deployment Type:
- On-Premise
- Cloud-Based
- Hybrid
Based on Application:
- Crew Scheduling
- Flight Operations
- Training Management
- Compliance Management
Based on End Use:
- Commercial Aviation
- Cargo Aviation
- Military Aviation
Based on Component:
- Software
- Services
- Support & Maintenance
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest market share in the Aviation Crew Management System Market, accounting for approximately 35% of the global revenue in 2024. The region benefits from the presence of major airlines, a mature aviation sector, and rapid adoption of advanced digital solutions. U.S. and Canadian carriers consistently invest in crew management platforms to optimize operations, ensure regulatory compliance, and enhance workforce productivity. High labor costs and stringent safety standards push airlines to leverage automation and analytics for effective resource allocation. It maintains a leading position due to early cloud adoption, robust IT infrastructure, and a culture of innovation. North American airlines set industry benchmarks for digital transformation, which further accelerates market growth and attracts technology providers aiming to expand their footprint.
Europe Europe represents the second-largest share, capturing around 28% of the global Aviation Crew Management System Market. The region’s aviation sector faces rigorous regulatory requirements, including the European Union’s strict labor laws, flight time limitations, and crew rest mandates. European airlines prioritize crew management solutions that streamline compliance, automate documentation, and minimize operational risk. The market experiences steady adoption of cloud-based and hybrid systems to improve flexibility and enable cross-border operations within the Schengen area. It sees growth from established flag carriers, low-cost airlines, and expanding regional operators, all seeking to enhance efficiency and maintain profitability amid competitive pressures. Europe’s commitment to digitalization and sustainable aviation practices continues to drive investment in next-generation crew management technologies.
Asia Pacific Asia Pacific accounts for roughly 22% of the global Aviation Crew Management System Market, and is projected to witness the fastest growth rate through 2032. The region’s dynamic airline industry benefits from rising passenger volumes, increasing fleet sizes, and ambitious network expansion strategies in countries such as China, India, Japan, and Southeast Asian nations. Airlines in Asia Pacific adopt crew management systems to address complex scheduling needs, language diversity, and regulatory differences across multiple jurisdictions. Government investments in airport infrastructure and a push toward digital transformation accelerate market development. It presents significant opportunities for vendors offering scalable, cloud-based, and mobile-enabled solutions. The shift toward automation supports improved efficiency and helps carriers meet the evolving demands of a rapidly growing travel market.
Middle East & Africa
The Middle East & Africa region holds about 10% of the Aviation Crew Management System Market. Airlines in the Middle East, led by prominent Gulf carriers, invest heavily in crew management technologies to support long-haul international operations and complex rostering requirements. The region’s aviation hubs, such as Dubai and Doha, foster the adoption of innovative IT solutions for seamless crew deployment across vast global networks. African airlines, while smaller in scale, begin integrating crew management systems to enhance safety, efficiency, and compliance with international standards. It provides growth prospects as governments and airlines collaborate to modernize aviation infrastructure and expand connectivity.
Latin America Latin America accounts for approximately 5% of the global Aviation Crew Management System Market. The region’s airlines focus on improving efficiency, reducing costs, and navigating economic fluctuations. Market growth is supported by increased international travel, rising demand for digital solutions, and efforts to comply with regional aviation regulations. Latin American carriers face challenges related to legacy systems, limited IT budgets, and uneven infrastructure development. It creates demand for flexible, scalable solutions that can be customized to address local market conditions and operational needs. The region is expected to show steady, albeit moderate, growth as economic stability improves and airlines invest in digital modernization.
Key Player Analysis
- CAE Inc. (U.S.)
- Advanced Optimization Systems Inc. (AOS) (U.S.)
- IBS Software Services (India)
- Jeppesen (U.S.)
- NAVBLUE (France)
- Lufthansa Systems GMBH & Co (Germany)
- InteliSys Aviation Systems Inc. (Canada)
- Hexaware Technologies Ltd (India)
- Hitit Computer Services (Turkey)
- AIMS International Ltd (UAE)
Competitive Analysis
The competitive landscape of the Aviation Crew Management System Market features leading players such as CAE Inc., Advanced Optimization Systems Inc. (AOS), IBS Software Services, Jeppesen, NAVBLUE, Lufthansa Systems GMBH & Co, InteliSys Aviation Systems Inc., Hexaware Technologies Ltd, Hitit Computer Services, and AIMS International Ltd. These companies drive market growth through continuous innovation, comprehensive service portfolios, and global reach. Leading players invest heavily in research and development to deliver advanced digital platforms equipped with artificial intelligence, predictive analytics, and real-time data integration. Their solutions help airlines optimize crew scheduling, ensure regulatory compliance, and enhance operational efficiency. Strategic partnerships, mergers, and acquisitions further strengthen their competitive positions and expand their client bases across commercial, cargo, and military aviation sectors. Market leaders maintain robust customer support, offer scalable deployment models, and focus on seamless integration with airline IT ecosystems. By responding to evolving industry demands and regulatory changes, these key players set industry benchmarks and secure long-term relationships with major airlines worldwide, solidifying their dominance in the Aviation Crew Management System Market.
Recent Developments
- In December 2022, Laminaar Aviation Infotech's ARMS crew management and mobile applications technology package was selected by Uganda Airlines to enhance their scheduling, training, and decision-making capabilities. By utilizing the innovative technology of ARMS, the airline will have access to a real-time, integrated platform for managing and tracking all crew operations, including mobile app-based features.
- In September 2022, Cebu Pacific, the top airline in the Philippines, selected IBS Software to enhance its crew scheduling processes and improve operational efficiency. As the airline expands its domestic and international networks, it is essential to manage staff schedules more efficiently with the increase in flights.
- In October 2022, Lufthansa Systems collaborated with Ditto, a peer-to-peer database company, and created a new Crew App using Apple's SwiftUI framework to convert conventional (paper-based) processes into digital ones. The Crew App operates on Ditto's Intelligent Edge Solution, a cross-platform peer-to-peer (P2P) database that enables syncing of data among the crew, even when there is no network connectivity.
- In July 2022, Air France, a France-based air carrier, signed an agreement with Boeing’s Jeppesen Crew Rostering solution as part of a five-year contract signed at the Farnborough Airshow to optimize crew schedules for nearly 13,000 cabin crew at the airline.
Market Concentration & Characteristics
The Aviation Crew Management System Market demonstrates a moderately concentrated landscape, with a few global leaders holding significant market share and numerous regional or specialized providers serving niche requirements. It features high barriers to entry due to complex regulatory standards, integration demands, and the need for advanced technological expertise. The market favors vendors that deliver scalable, customizable, and secure solutions capable of integrating with broader airline operations. Long sales cycles and high switching costs characterize the industry, leading to strong customer retention and long-term contracts with major carriers. It values innovation, reliability, and compliance, with airlines prioritizing solutions that offer automation, real-time data access, and robust support. The market's evolution reflects a strong focus on digital transformation, operational efficiency, and continuous adaptation to changing regulatory and operational environments
Report Coverage
The research report offers an in-depth analysis based on Deployment Type, Application, End Use, Component and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Aviation Crew Management System Market is projected to grow steadily, driven by increasing demand for efficient crew scheduling and compliance management.
- Airlines are adopting advanced technologies to enhance operational efficiency and reduce costs associated with crew management.
- Integration of artificial intelligence and machine learning is enabling predictive analytics for better crew utilization and disruption management.
- Cloud-based deployment models are gaining popularity due to their scalability, flexibility, and cost-effectiveness.
- The market is witnessing a trend towards mobile-enabled solutions, allowing crew members to access schedules and updates in real-time.
- Regulatory compliance remains a critical factor, prompting airlines to invest in systems that ensure adherence to labor laws and safety standards.
- North America and Europe are leading in market adoption, while Asia Pacific is experiencing rapid growth due to expanding airline operations.
- High initial implementation costs and integration challenges with legacy systems are potential restraints for market growth.
- Key players are focusing on strategic partnerships and product innovations to strengthen their market position.
- The market is expected to continue evolving with advancements in technology and increasing emphasis on crew well-being and operational efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Airline Operations
The rapid growth in global airline fleets and routes increases the complexity of crew scheduling and resource allocation, driving airlines to adopt advanced crew management systems to maintain operational efficiency and punctuality.
Regulatory Compliance and Safety Standards
Stringent labor laws, flight time limitations, and rest requirements enforced by aviation authorities require airlines to implement sophisticated systems that automate compliance monitoring and reporting, reducing the risk of penalties and enhancing safety.
Digital Transformation and AI Integration
The shift toward digitalization in aviation, including the adoption of artificial intelligence and cloud-based platforms, enables predictive scheduling, real-time decision-making, and seamless integration with broader airline operations, significantly improving crew management efficiency.
Focus on Crew Well-being and Cost Optimization
Airlines are increasingly prioritizing crew fatigue management, work-life balance, and cost control, leveraging crew management systems to automate scheduling, monitor fatigue risks, and reduce overtime and administrative costs, which enhances crew satisfaction and retention.
Integration with Broader Airline Ecosystems
The need for interoperability between crew management, flight operations, and maintenance systems is driving demand for integrated platforms, enabling airlines to streamline workflows, improve situational awareness, and respond more effectively to operational disruptions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aviation Crew Management System Market?
What factors are driving the growth of the Aviation Crew Management System Market?
What are the key segments within the Aviation Crew Management System Market?
Who are the major players in the Aviation Crew Management System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Commercial Aviation
- 1.2.2 Cargo Aviation
- 1.2.3 Military Aviation
- 1.3 By Component
- 1.3.1 Software
- 1.3.2 Services
- 1.3.3 Support & Maintenance
- 1.4 By Application
- 1.4.1 Crew Scheduling
- 1.4.2 Flight Operations
- 1.4.3 Training Management
- 1.4.4 Compliance Management
- 1.5 By Deployment Type
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
- 1.5.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,150 million → 2032: USD 5,535 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aviation Crew Management System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aviation Crew Management System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aviation Crew Management System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aviation Crew Management System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aviation Crew Management System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aviation Crew Management System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aviation Crew Management System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aviation Crew Management System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,150 million → 2032: USD 5,535 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aviation Crew Management System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial Aviation
- 12.3.7.2 Cargo Aviation
- 12.3.7.3 Military Aviation
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Software
- 12.4.7.2 Services
- 12.4.7.3 Support & Maintenance
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Crew Scheduling
- 12.5.7.2 Flight Operations
- 12.5.7.3 Training Management
- 12.5.7.4 Compliance Management
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Premise
- 12.6.7.2 Cloud-Based
- 12.6.7.3 Hybrid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aviation Crew Management System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aviation Crew Management System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aviation Crew Management System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aviation Crew Management System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CAE Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Jeppesen
- 18.4 Lufthansa Systems GMBH & Co
- 18.5 IBS Software Services
- 18.6 NAVBLUE
- 18.7 Advanced Optimization Systems Inc. (AOS)
- 18.8 InteliSys Aviation Systems Inc.
- 18.9 Hexaware Technologies Ltd
- 18.10 Hitit Computer Services
- 18.11 AIMS International Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

