
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Domestic Aviation Market Size 2024 | USD 922127 million |
| Domestic Aviation Market, CAGR | 3.6% |
| Domestic Aviation Market Size 2032 | USD 1223682.59 million |
Market Overview:
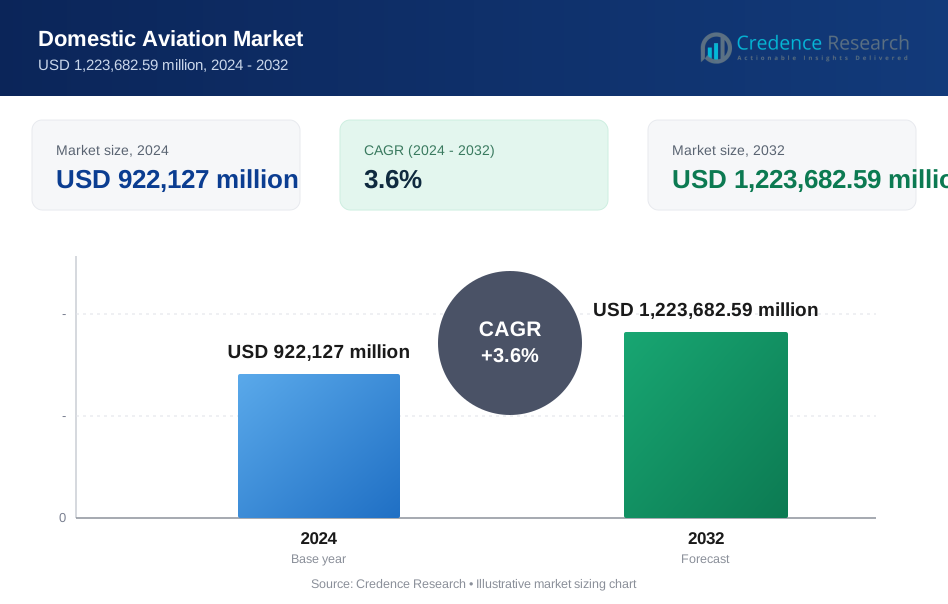
The Domestic Aviation Market is projected to grow from USD 922127 million in 2024 to an estimated USD 1223682.59 million by 2032, with a compound annual growth rate (CAGR) of 3.6% from 2024 to 2032.
Several factors are fueling the growth of the Domestic Aviation Market. Rising disposable incomes, particularly in emerging economies, are enabling more people to afford air travel, which boosts domestic aviation demand. The increasing urbanization and expansion of low-cost carriers (LCCs) have made air travel more accessible, prompting greater competition and fare reductions that attract a wider range of passengers. Additionally, governments are investing in airport infrastructure, aiming to improve connectivity between cities and rural areas, which in turn supports economic growth and tourism within countries. Advances in aviation technology, including fuel-efficient aircraft and sustainable aviation fuel (SAF), are also important drivers as airlines seek to reduce operational costs and meet environmental regulations. Furthermore, shifting consumer preferences for quicker travel options due to increased time sensitivity contribute to the expansion of the domestic aviation sector.
Regionally, North America holds a significant share of the Domestic Aviation Market, accounting for approximately 35% of the total market. The United States is the primary driver, with its extensive network of airports and strong consumer demand for domestic air travel. Europe follows closely, where countries like the UK, Germany, and France see high levels of domestic travel supported by well-established transportation networks and a growing preference for air travel over rail for short-haul journeys. The Asia-Pacific region is anticipated to experience the most substantial growth, particularly in China and India, driven by rising middle-class populations and large-scale investments in aviation infrastructure. In Latin America, Brazil and Mexico lead the domestic aviation sector, focusing on expanding airport capacity and improving connectivity within national borders. Meanwhile, the Middle East & Africa show slower growth, but countries like Saudi Arabia and South Africa are making strides in domestic aviation to boost tourism and improve regional connectivity.
Market Drivers:
Rising Disposable Incomes and Growing Middle-Class Population:
One of the primary drivers of the Domestic Aviation Market is the increase in disposable incomes, particularly in emerging economies. As incomes rise, more individuals and families are able to afford air travel, contributing to a surge in domestic passenger traffic. This trend is especially prevalent in countries like China, India, and Brazil, where the middle class is expanding rapidly. For instance, between 2019 and 2030, the number of households with an annual disposable income of USD45,000-100,000 (PPP) across developing countries is set to rise by 5.6% per year on average. This growing demographic values air travel for its speed and convenience, particularly for work-related travel and tourism. The affordability of air travel in these regions, combined with increasing purchasing power, is making domestic flights a preferred choice over other modes of transportation, supporting the market’s expansion.
Expansion of Low-Cost Carriers (LCCs):
The proliferation of low-cost carriers (LCCs) is another significant driver of the Domestic Aviation Market. LCCs offer competitive pricing and simplified services, making air travel accessible to a broader range of passengers. This model has proven particularly effective in countries with large domestic markets, such as the United States, China, and India, where LCCs cater to both leisure and business travelers. By focusing on high-frequency routes between major cities and secondary airports, LCCs have stimulated demand for domestic air travel by lowering fares and increasing the frequency of flights. The presence of LCCs in emerging markets has also intensified competition, encouraging traditional carriers to improve their services and reduce fares, which benefits consumers and further drives market growth.
Government Investments in Infrastructure and Connectivity:
Government investments in airport infrastructure and regional connectivity are crucial drivers of the Domestic Aviation Market. Many governments recognize the importance of aviation as a catalyst for economic development and tourism, prompting large-scale investments in expanding and modernizing airport facilities. In countries like India, China, and the United States, governments are actively working to improve domestic connectivity by building new airports, upgrading existing ones, and developing regional airstrips to connect remote areas with major urban centers. For instance, from 2013 to 2021, China provided $679 billion for infrastructure projects through the Belt and Road Initiative (BRI) in key infrastructure sectors. These efforts enhance the accessibility and efficiency of domestic travel, enabling airlines to serve a broader range of destinations. Furthermore, improved infrastructure reduces congestion and delays, creating a more reliable experience for travelers and increasing the attractiveness of domestic air travel.
Advancements in Aviation Technology and Sustainability Efforts:
Technological advancements in the aviation industry are also driving the Domestic Aviation Market. New aircraft designs, improved fuel efficiency, and the development of sustainable aviation fuel (SAF) are reducing operational costs and environmental impacts for airlines. Modern aircraft consume less fuel per passenger, making domestic flights more economically viable and environmentally friendly. Airlines are also investing in digital technologies, such as automated check-in systems and in-flight Wi-Fi, to enhance the passenger experience and streamline operations. Additionally, as governments and consumers alike prioritize sustainability, airlines are exploring SAF and carbon offset programs to reduce their carbon footprints. These technological advancements not only make domestic aviation more sustainable but also support airlines in meeting regulatory requirements and maintaining competitive operating costs, which strengthens the overall market.
Market Trends:
Increased Adoption of Digital Technologies:
A major trend in the Domestic Aviation Market is the increased adoption of digital technologies to enhance the passenger experience and streamline operations. Airlines are leveraging mobile apps, automated check-in kiosks, and biometric identification systems to create a more seamless and efficient travel experience. For instance, in 2022, airlines spent $37 billion on technology investments to meet rising expectations in demand and service. Mobile apps, for example, allow passengers to manage bookings, check flight status, and receive real-time updates, reducing the need for physical interactions at airports. Additionally, biometric technologies, such as facial recognition, are being implemented for quicker boarding and security checks, cutting down on wait times. Airlines are also investing in in-flight Wi-Fi and entertainment systems, responding to consumer demand for connectivity. This digital transformation enhances convenience, increases customer satisfaction, and allows airlines to optimize their operations, thus becoming a key component of growth in the domestic aviation sector.
Focus on Sustainable Aviation Practices:
Sustainability is becoming a core focus within the Domestic Aviation Market as airlines and governments work to reduce the industry’s environmental impact. There is a growing emphasis on sustainable aviation fuel (SAF), which can significantly lower carbon emissions compared to conventional jet fuel. Some airlines are entering into agreements with SAF providers to integrate these fuels into their operations, particularly on domestic routes where carbon reduction is most feasible. In addition to SAF, airlines are exploring new aircraft designs that improve fuel efficiency and reduce noise pollution. Fleet modernization efforts are ongoing, as older, less efficient planes are replaced with newer models that use advanced technology to minimize fuel consumption. As environmental concerns continue to influence consumer preferences and regulatory policies, airlines are increasingly adopting sustainable practices that appeal to eco-conscious travelers and align with global sustainability goals.
Expansion of Regional Connectivity:
The expansion of regional connectivity is another significant trend in the Domestic Aviation Market, especially in large and emerging economies. In countries like India, China, and the United States, airlines are focusing on connecting secondary cities and underserved regions, making air travel more accessible to a broader population. For instance, the Asia Pacific region, led by strong growth in India and China, is expected to remain the fastest expanding domestic market worldwide. This trend is supported by government initiatives aimed at improving regional infrastructure and developing new airports or airstrips in remote areas. By enhancing regional connectivity, airlines can tap into new customer segments, including travelers who previously relied on slower modes of transport. Regional expansion not only fosters economic growth by improving access to essential services and opportunities but also boosts tourism within national borders. As airlines and governments prioritize regional connectivity, this trend is expected to play a significant role in the market’s continued growth.
Growth of Low-Cost Carriers (LCCs):
The growth of low-cost carriers (LCCs) is reshaping the Domestic Aviation Market by making air travel more affordable and accessible. LCCs focus on short-haul, high-frequency routes and offer lower fares by operating with simplified services and reduced operating costs. This business model appeals to budget-conscious travelers, driving significant demand for domestic flights, particularly among first-time flyers and leisure travelers. In countries like the United States, India, and Brazil, the presence of LCCs has intensified competition, leading to fare reductions and increased options for passengers. LCCs also play a crucial role in expanding the reach of air travel by operating routes between smaller cities and less-trafficked airports. As more consumers seek affordable travel options, the expansion of LCCs is expected to continue, contributing to market growth and further diversifying the domestic aviation landscape.
Market Restraints and Challenges:
Rising Fuel Costs and Volatility:
One of the primary challenges in the Domestic Aviation Market is the volatility of fuel prices. Fuel expenses constitute a significant portion of operational costs for airlines, and fluctuations in oil prices can have a substantial impact on profitability. When fuel prices rise, airlines are often forced to increase ticket prices to maintain margins, which can reduce consumer demand for domestic flights. For low-cost carriers, in particular, rising fuel costs present a challenge, as their business models are heavily dependent on keeping fares low. This volatility complicates financial planning for airlines and makes it challenging to maintain stable pricing, impacting market growth.
Stringent Environmental Regulations:
The push for environmental sustainability poses another challenge for the Domestic Aviation Market. As governments enforce stricter regulations on carbon emissions, airlines face increasing pressure to adopt sustainable practices. Compliance with these regulations often requires significant investment in newer, more fuel-efficient aircraft and the adoption of sustainable aviation fuel (SAF). While these initiatives help reduce the environmental impact of domestic aviation, they also come with substantial costs that can strain an airline’s financial resources. Furthermore, some regions lack the infrastructure for SAF distribution, limiting its feasibility as a widespread solution. Meeting these regulatory demands is essential, but balancing environmental goals with cost efficiency remains a critical challenge for airlines.
Infrastructure Limitations and Congestion:
Infrastructure limitations and airport congestion are persistent issues in the Domestic Aviation Market, especially in rapidly growing regions. Many airports, particularly in emerging markets, are experiencing capacity constraints as passenger volumes increase. This congestion can lead to delays, reduce operational efficiency, and diminish the overall passenger experience. Additionally, some regions lack sufficient airport infrastructure to accommodate growth in domestic aviation, which restricts airlines from expanding their route networks. While governments in countries such as India and China are investing in new airport construction and expansions, these projects are time-consuming and require significant financial resources. Infrastructure constraints therefore remain a bottleneck, limiting the potential for market expansion.
Intense Competition and Price Sensitivity:
The domestic aviation sector is highly competitive, with numerous airlines vying for market share. The presence of both full-service carriers and low-cost carriers has intensified competition, leading to downward pressure on ticket prices. While this benefits consumers, it presents a challenge for airlines, as intense competition can erode profitability. Price sensitivity among consumers, particularly in the low-cost segment, means that even small fare increases can reduce demand. Airlines are therefore constantly balancing the need to attract customers with the challenge of maintaining sustainable profit margins, which can limit opportunities for investment and growth within the market.
Market Segmentation Analysis:
By Type, the market is primarily driven by commercial aircraft, which represent the majority of domestic aviation activity. Commercial aircraft include narrow-body planes used by airlines to operate high-frequency routes between major cities and regional destinations. These aircraft are essential for serving large passenger volumes and meeting the demands of both business and leisure travelers. The “Others” segment includes smaller aircraft, such as regional jets and turboprops, which are used for short-haul flights and provide connectivity to underserved or remote areas. These aircraft are often deployed by regional carriers or low-cost airlines to access niche markets, enhancing the overall accessibility of air travel.
By Application, the market is divided into government, commercial, and private sectors. The commercial segment holds the largest share, driven by domestic airlines serving passengers traveling for business, tourism, and personal purposes. This segment includes both full-service carriers and low-cost airlines that compete to meet consumer demands for affordable and efficient travel options. The government sector includes flights operated by state-owned airlines or aircraft used for governmental operations, such as transporting officials and supporting emergency services. The private segment encompasses private jets and charters, catering to high-net-worth individuals and corporate clients seeking exclusive, flexible travel solutions. While smaller in scale, the private and government segments add diversity to the domestic aviation market and highlight its varied applications beyond standard passenger flights.
Segmentation:
By Type:
- Commercial Aircraft
- Others
By Application:
- Government,
- Commercial,
- Private
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds a significant share of the Domestic Aviation Market, accounting for approximately 35% of global revenue. The United States drives this demand, boasting a highly developed aviation infrastructure and a strong consumer base with a preference for air travel over longer surface transportation options. Major carriers in the U.S. operate extensive domestic networks, connecting cities and regions with high-frequency flights. Canada also contributes to regional growth, especially within its larger provinces, where air travel is necessary due to long distances between cities. The region benefits from robust infrastructure, a mature aviation market, and continuous investments in airport expansions, all of which support the high demand for domestic flights.
Europe
Europe represents around 25% of the Domestic Aviation Market. The region’s domestic aviation is highly developed in countries like the United Kingdom, Germany, and France, where strong transport networks and high population density drive demand for short-haul air travel. Additionally, the European Union’s open skies agreements promote competition and enable airlines to operate more freely, increasing the number of domestic routes available. However, environmental regulations and the emphasis on sustainable travel alternatives, such as high-speed rail, slightly moderate growth in the region. Despite this, Europe remains a substantial market, particularly in countries where air travel is faster and more convenient than surface transport options for domestic routes.
Asia-Pacific
Asia-Pacific leads the Domestic Aviation Market in terms of growth potential, holding about 30% of the global market share. Rapid urbanization, rising disposable incomes, and a growing middle class in countries like China, India, and Indonesia are driving demand for affordable domestic flights. Governments across the region are investing heavily in airport infrastructure to support increased passenger volumes and expand regional connectivity. China’s extensive high-speed rail network competes with domestic aviation on certain routes, but air travel remains the preferred choice for many due to its speed and convenience over longer distances. India, with its rapidly expanding low-cost airline sector, also contributes significantly to the regional market, aiming to make air travel more accessible to a wider population. As urban centers expand, the Asia-Pacific region is anticipated to continue its strong growth trajectory in domestic aviation.
Latin America
Latin America accounts for roughly 5% of the global Domestic Aviation Market. Brazil and Mexico dominate this region, where demand for domestic flights is driven by economic growth, increasing tourism, and expanding infrastructure. Both countries are focused on improving airport facilities and enhancing connectivity between urban centers and remote regions. Latin America’s domestic aviation market also benefits from favorable policies supporting airline competition, though challenges such as economic instability and regulatory complexities impact growth in some countries. As infrastructure investments continue, the region is expected to see steady growth in its domestic aviation market.
Middle East & Africa
The Middle East & Africa hold approximately 5% of the global market share. In the Middle East, countries like Saudi Arabia and the UAE are focusing on strengthening domestic aviation to boost tourism and connect secondary cities. Meanwhile, in Africa, the domestic aviation market is developing gradually, with South Africa leading in terms of established infrastructure and frequency of domestic flights. Infrastructure limitations and high operational costs present challenges in many African countries, but investments in airport expansions and efforts to improve regional connectivity are laying the groundwork for future growth. As these regions develop further, they are expected to contribute more significantly to the global Domestic Aviation Market.
Key Player Analysis:
- Singapore Airlines
- Air New Zealand
- Qantas
- Qatar Airways
- Virgin Australia
- Emirates
- All Nippon Airways
- EVA Air
- American Airline
- Spicejet
- The Boeing Company
- Airbus SE
- Lockheed Martin Corporation
- Textron Inc
- Embraer S.A.
Competitive Analysis:
The Domestic Aviation Market is highly competitive, with both full-service and low-cost carriers vying for market share. Major players include well-established airlines like American Airlines, Delta Air Lines, and United Airlines in North America; Lufthansa and Air France in Europe; and China Southern and Indigo in Asia-Pacific. These airlines leverage expansive domestic networks and frequent flight schedules to attract a broad customer base. Low-cost carriers (LCCs) such as Southwest Airlines, Ryanair, and AirAsia also play a crucial role, driving demand by offering competitive fares on high-traffic routes. LCCs focus on cost efficiency, simplified services, and high-frequency routes, catering to budget-conscious travelers and expanding air travel accessibility. Intense competition has led airlines to invest in digital technologies, sustainability initiatives, and customer experience enhancements. Additionally, alliances and partnerships are common strategies as airlines seek to expand their networks and optimize route efficiencies, further shaping the competitive landscape of domestic aviation.
Recent Developments:
- In March 2024, Boeing and Air India Engineering Services Ltd. (AIESL), a company specializing in maintenance, repair, and overhaul of aircraft and components, announced a partnership to enhance aircraft training activities in India. Under this agreement, Boeing will provide AIESL with training materials, aids, and instructor support to standardize their training programs. AIESL, in turn, will contribute its infrastructure and instructors, while also obtaining the necessary Civil Aviation Regulation (CAR) 147 approval from Indian regulatory authorities to offer maintenance training services to its customers.
- In February 2024, Airbus and TotalEnergies entered into a strategic partnership focused on decarbonizing aviation by promoting sustainable aviation fuels (SAF). This collaboration aligns with the aviation industry’s goal of reaching net-zero carbon emissions by 2050, with SAF playing a crucial role in reducing CO2 emissions. TotalEnergies’ SAF can lower lifecycle CO2 emissions by up to 90% compared to conventional jet fuel, supporting the industry’s environmental objectives and commitment to sustainability.
Market Concentration & Characteristics:
The Domestic Aviation Market is moderately concentrated, with major airlines holding significant shares due to their extensive route networks, established brand presence, and operational efficiencies. Full-service carriers like American Airlines, Delta Air Lines, and United Airlines dominate in regions such as North America, while low-cost carriers (LCCs) such as Southwest Airlines, Ryanair, and AirAsia play crucial roles by offering affordable, high-frequency routes and simplified services. This dual presence intensifies competition, with airlines continuously striving to differentiate through customer experience, digital innovation, and loyalty programs. The market is characterized by high competition, price sensitivity, and a strong emphasis on operational efficiency. Rising consumer expectations for convenience and sustainability are pushing airlines to adopt digital technologies, reduce emissions, and invest in fuel-efficient fleets. Additionally, regional partnerships and code-sharing agreements are common, enabling airlines to expand their networks and optimize route coverage while responding to varying demand across diverse geographic markets.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Domestic Aviation Market is expected to grow as rising disposable incomes and increased urbanization drive demand for domestic air travel.
- Expansion of low-cost carriers (LCCs) will make air travel more affordable, attracting a broader range of passengers.
- Investments in airport infrastructure will enhance connectivity, especially in emerging economies, supporting regional aviation growth.
- Adoption of digital technologies, such as biometric check-ins and mobile apps, will improve operational efficiency and passenger experience.
- Airlines will focus on fleet modernization, prioritizing fuel-efficient and environmentally friendly aircraft to meet sustainability goals.
- Increased use of sustainable aviation fuels (SAF) will support efforts to reduce carbon emissions within domestic aviation.
- Regional connectivity initiatives will expand access to air travel in underserved areas, tapping into new passenger segments.
- Competitive pricing strategies and enhanced loyalty programs will drive consumer retention and market expansion.
- Partnerships between airlines and technology providers will accelerate innovation, particularly in customer service and operational management.
- Government support for aviation sector recovery and growth will play a key role, particularly in regions heavily reliant on domestic air travel.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Incomes and Growing Middle-Class Population
As disposable incomes increase, especially in emerging economies like China, India, and Brazil, more people can afford air travel, leading to higher domestic passenger volumes and expanding the market.
Expansion of Low-Cost Carriers (LCCs)
The proliferation of LCCs has made air travel more accessible and affordable, stimulating demand by lowering fares and increasing flight frequency, particularly on high-traffic domestic routes.
Government Investments in Infrastructure and Connectivity
Significant government spending on airport infrastructure and regional connectivity projects is improving access to air travel, reducing congestion, and enabling airlines to serve more destinations within national borders.
Advancements in Aviation Technology and Sustainability Efforts
New fuel-efficient aircraft, adoption of sustainable aviation fuels (SAF), and digital innovations are reducing operational costs, meeting environmental regulations, and enhancing the passenger experience, all of which support market growth.
Urbanization and Changing Consumer Preferences
Increasing urbanization and a growing preference for fast, convenient travel options are driving more people to choose domestic flights over other transportation modes, further boosting market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate for the Domestic Aviation Market?
What will the market size be by 2032?
Which region holds the largest share of the Domestic Aviation Market?
What challenges does the Domestic Aviation Market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Commercial Aircraft
- 1.2.2 Others
- 1.3 By Application
- 1.3.1 Government
- 1.3.2 Commercial
- 1.3.3 Private
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 922,127 million → 2032: USD 1,223,682.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Domestic Aviation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Domestic Aviation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Domestic Aviation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Domestic Aviation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Domestic Aviation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Domestic Aviation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Domestic Aviation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Domestic Aviation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 922,127 million → 2032: USD 1,223,682.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Domestic Aviation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial Aircraft
- 12.3.7.2 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Government
- 12.4.7.2 Commercial
- 12.4.7.3 Private
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Domestic Aviation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Domestic Aviation Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Domestic Aviation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Domestic Aviation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 American Airlines
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Delta Air Lines
- 18.4 United Airlines
- 18.5 Southwest Airlines
- 18.6 Lufthansa
- 18.7 Air France
- 18.8 China Southern Airlines
- 18.9 Indigo
- 18.10 Ryanair
- 18.11 AirAsia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

