
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Baby & Infant Toys Market Size 2024 | 14,984.63 million |
| Baby & Infant Toys Market, CAGR | 4.42% |
| Baby & Infant Toys Market, Size 2032 | USD 21,182.46 million |
Market Overview
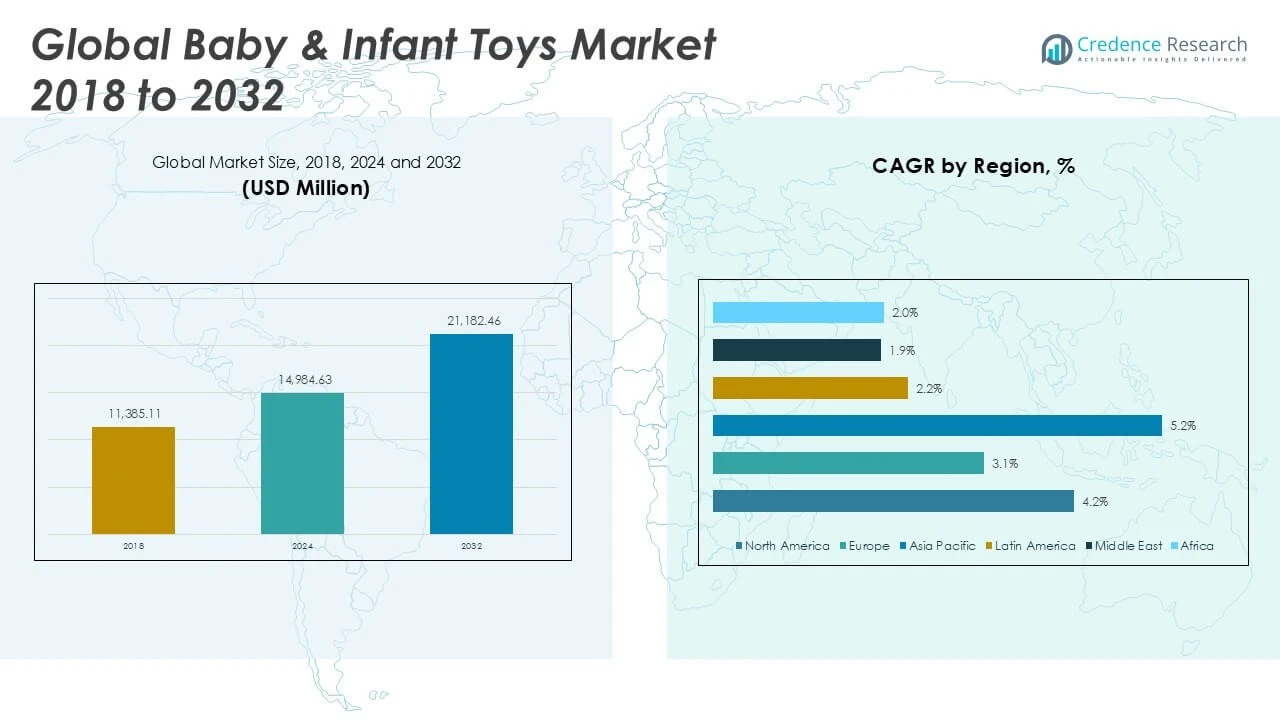
Baby & Infant Toys Market size was valued at USD 11,385.11 million in 2018 to USD 14,984.63 million in 2024 and is anticipated to reach USD 21,182.46 million by 2032, at a CAGR of 4.42% during the forecast period.
The Baby & Infant Toys Market gains momentum from rising birth rates, increasing parental awareness of early childhood development, and higher disposable incomes among young families. Parents seek educational and sensory-stimulating toys that support cognitive and motor skill growth, driving demand for innovative products designed for safety and learning. Manufacturers respond by introducing eco-friendly, non-toxic, and smart toys, incorporating features such as interactive sounds, lights, and mobile connectivity to enhance engagement. Trends indicate a preference for gender-neutral designs and sustainable materials, aligning with broader shifts toward responsible consumption. E-commerce platforms and targeted digital marketing expand access to a wider range of toys, while collaborations with healthcare professionals and child development experts reinforce product credibility. These factors, combined with continuous product innovation and evolving consumer preferences, position the Baby & Infant Toys Market for sustained growth and diversification across global regions.
The Baby & Infant Toys Market shows robust growth across key global regions, led by North America, Europe, and Asia Pacific. North America stands out for its strong focus on innovative, high-quality, and safety-certified products, supported by established retail infrastructure and high consumer awareness. Europe follows closely, driven by demand for eco-friendly and educational toys, with parents showing strong preferences for sustainability and developmental value. Asia Pacific emerges as a high-potential market due to increasing birth rates, rising disposable incomes, and expanding access to international brands through e-commerce. Prominent players shaping the industry include Mattel Inc., Hasbro Inc., The LEGO Group, and VTech Holdings Limited, each leveraging product innovation, strategic partnerships, and diverse portfolios to maintain leadership and respond to evolving consumer preferences in these dynamic regions.
Market Insights
- The Baby & Infant Toys Market was valued at USD 14,984.63 million in 2024 and is projected to reach USD 21,182.46 million by 2032, registering a CAGR of 4.42% during the forecast period.
- Rising parental awareness of early childhood development and increased disposable incomes fuel steady demand for educational, interactive, and safe toys.
- Manufacturers introduce eco-friendly, sustainable, and gender-neutral toys to align with evolving consumer values and regulatory standards.
- Digital marketing, influencer partnerships, and omnichannel retail strategies expand brand reach and enhance consumer engagement across regions.
- Intense competition and the prevalence of low-cost, unbranded alternatives present ongoing challenges for established brands to maintain quality and profitability.
- North America and Europe remain leaders in product innovation and premium offerings, while Asia Pacific displays rapid market growth driven by high birth rates and urbanization.
- The market navigates challenges such as stringent safety regulations, price sensitivity, and the need to balance innovation with affordability in a competitive global landscape.
Market Drivers
Rising Parental Focus on Early Childhood Development
The Baby & Infant Toys Market benefits significantly from heightened parental awareness regarding the importance of early childhood development. Parents increasingly seek toys that promote cognitive, sensory, and motor skill advancement in infants. They look for products that encourage exploration, creativity, and learning through play. Educational toys, sensory playsets, and activity gyms gain traction, driven by endorsements from child development specialists and pediatricians. The trend towards early skill-building supports steady demand for a variety of developmental toys. This focus not only sustains the market’s growth but also drives manufacturers to invest in research and product design tailored to early learning outcomes.
- For instance, Indian parents are increasingly investing in toys that stimulate cognitive, motor, and social skills, with educational toys accounting for approximately 30% of total toy sales.
Expansion of Disposable Incomes Among Young Families
Increasing disposable incomes, particularly in emerging economies, serve as a major growth driver for the Baby & Infant Toys Market. Young families are more willing to invest in high-quality, branded, and premium toys for their infants. This financial flexibility leads to higher adoption rates for educational, interactive, and tech-enabled products. The market responds with diverse offerings across different price ranges, catering to both value-conscious and luxury-seeking customers. Retailers and manufacturers expand their product portfolios to address varying purchasing capacities. The availability of premium and innovative toys stimulates repeat purchases and enhances overall market value.
Emphasis on Product Safety and Regulatory Compliance
The Baby & Infant Toys Market places strong emphasis on product safety, non-toxic materials, and adherence to international quality standards. Parents prioritize toys that comply with safety certifications and regulatory requirements, ensuring the well-being of their children. Manufacturers invest in rigorous testing, certifications, and transparent labeling to build consumer trust. The adoption of eco-friendly and sustainable materials aligns with growing environmental concerns, further enhancing brand reputation. Companies that prioritize safety and sustainability strengthen their competitive position and appeal to a broader customer base. This focus on compliance and transparency shapes product development and marketing strategies industry-wide.
- For instance, the global baby toys market is witnessing a growing emphasis on eco-friendly and sustainable products, with parents seeking toys made from safe, non-toxic materials.
Technological Advancements and Product Innovation
Technological progress fuels ongoing innovation within the Baby & Infant Toys Market. Companies introduce smart toys featuring interactive sounds, lights, and mobile connectivity to enhance engagement and learning. The integration of artificial intelligence and sensor technology provides personalized and adaptive play experiences for infants. Product designers develop multifunctional toys that address developmental milestones, convenience, and entertainment. These innovations help brands differentiate themselves in a crowded market and appeal to tech-savvy parents. Digital marketing and e-commerce platforms further amplify the reach of innovative products. The continuous cycle of technological advancement supports sustained market growth and dynamic consumer engagement.
Market Trends
Rise of Eco-Friendly and Sustainable Products
The Baby & Infant Toys Market reflects a significant shift toward eco-friendly and sustainable product offerings. Manufacturers introduce toys made from natural, biodegradable, and non-toxic materials, aligning with consumer demand for responsible consumption. Parents prefer brands that demonstrate a commitment to environmental stewardship and child safety. Certifications and transparent supply chains enhance consumer trust and set new benchmarks for quality. The adoption of recyclable packaging further distinguishes brands in a crowded marketplace. This trend supports the overall reputation of the industry and appeals to environmentally conscious families seeking safe and sustainable choices.
- For instance, Playmobil has transformed 90% of its toddler range to plant-based materials, while its Wiltopia range incorporates 80% recycled and bio-based materials.
Integration of Smart Technology and Interactive Features
The Baby & Infant Toys Market integrates advanced technologies, leading to a surge in smart and interactive toys. Companies invest in products equipped with sensors, interactive sounds, lights, and mobile app connectivity, offering a more engaging play experience. These smart toys provide personalized responses and adaptive learning, keeping infants entertained and fostering developmental progress. Parents value products that blend traditional play with educational technology. The expansion of the Internet of Things (IoT) in toys enables real-time feedback and monitoring, further driving market differentiation. This focus on innovation creates opportunities for premium pricing and brand loyalty.
Growth of Gender-Neutral and Inclusive Toy Designs
Toy manufacturers in the Baby & Infant Toys Market shift toward gender-neutral and inclusive product designs. Brands move away from traditional gender-based color schemes and themes, introducing toys that encourage open-ended play for all children. Parents support these inclusive options, recognizing their role in promoting creativity and self-expression. Marketing strategies highlight diversity and equality, resonating with modern family values. This trend influences product development, packaging, and in-store displays across retail channels. Gender-neutral toys expand the customer base and strengthen the market’s adaptability to evolving social attitudes.
- For instance, modern toy companies are moving away from traditional gender-based color schemes and themes, introducing toys that encourage open-ended play for all children.
Expansion of Omnichannel Retail and Digital Marketing
The Baby & Infant Toys Market sees strong growth in omnichannel retailing, combining online and offline sales strategies. E-commerce platforms provide convenience and access to a broad range of products, supported by targeted digital marketing campaigns. Influencer collaborations and social media promotions help brands reach tech-savvy parents and younger families. Brick-and-mortar stores maintain relevance by offering experiential retail and personalized service. The integration of virtual product demonstrations and online reviews influences purchasing decisions and increases consumer confidence. Omnichannel strategies ensure brands remain visible and accessible in a highly competitive environment.
Market Challenges Analysis
Stringent Regulatory Requirements and Product Safety Concerns
The Baby & Infant Toys Market faces significant challenges from strict regulatory standards and growing parental concerns about product safety. Global regulations demand rigorous testing, certification, and compliance with evolving safety norms, which increases operational costs for manufacturers. Companies must adapt quickly to changes in material standards, chemical restrictions, and labeling requirements. Recalls due to non-compliance or product defects can damage brand reputation and erode consumer trust. The market must invest in ongoing research and development to ensure that toys meet safety benchmarks across different regions. Navigating diverse regulatory environments presents complexity for international brands and may slow product launches or market expansion.
- For instance, global toy safety regulations, including the European Union’s Toy Safety Directive and the U.S. Consumer Product Safety Improvement Act, mandate rigorous testing and certification to ensure compliance with evolving safety norms.
Price Sensitivity and Competition from Unbranded Products
The Baby & Infant Toys Market encounters strong price sensitivity, particularly in developing regions where consumers prioritize affordability. The presence of low-cost, unbranded, or counterfeit products creates intense competition for established brands. These alternatives often bypass strict safety checks, putting infants at risk and undermining consumer confidence in the market. Leading brands must balance innovation and quality with cost efficiency to remain competitive without sacrificing product standards. Economic downturns and fluctuations in raw material prices further pressure margins. The challenge to offer high-value products at accessible price points persists across all segments of the industry.
Market Opportunities
Expansion into Emerging Markets and New Demographics
The Baby & Infant Toys Market holds strong growth opportunities through strategic expansion into emerging markets and the targeting of new consumer segments. Rising birth rates and increasing disposable incomes in Asia Pacific, Latin America, and parts of Africa create robust demand for safe, innovative, and affordable toys. Companies can develop region-specific products and localized marketing campaigns to engage young families and address unique cultural preferences. Partnerships with local retailers and e-commerce platforms support broader distribution and brand recognition. The market’s ability to adapt its portfolio for varying price points and developmental needs positions it well to capture new growth in these dynamic regions. Proactive outreach to untapped demographic groups, such as working parents and grandparents, expands the consumer base further.
Innovation in Smart Toys and Sustainability Initiatives
The Baby & Infant Toys Market offers substantial potential for brands that invest in product innovation and sustainability. Companies can leverage advancements in sensor technology, artificial intelligence, and mobile connectivity to develop smart toys that deliver personalized, educational experiences. These innovations attract tech-savvy parents seeking tools to support early development. Brands that embrace sustainable materials, recyclable packaging, and ethical sourcing differentiate themselves in a competitive landscape and build long-term trust with environmentally conscious consumers. Collaborations with child development experts and healthcare professionals enhance product credibility and drive adoption. This focus on technology and sustainability ensures continued relevance and market leadership.
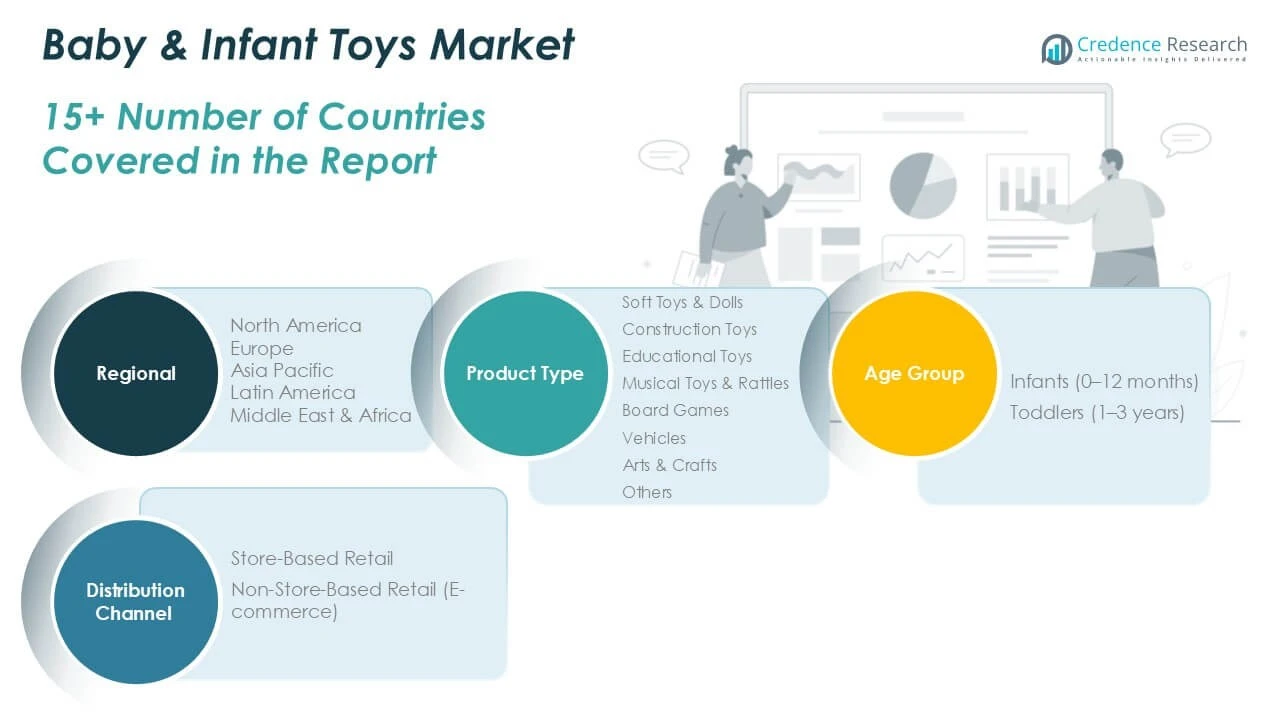
Market Segmentation Analysis:
By Product Type:
The Baby & Infant Toys Market presents a comprehensive segment structure that enables brands to address diverse consumer preferences, developmental stages, and purchasing behaviors. By product type, the market includes soft toys and dolls, construction toys, educational toys, musical toys and rattles, board games, vehicles, arts and crafts, and others. Soft toys and dolls remain a staple due to their perceived safety and comforting attributes, particularly favored by parents for newborns and infants. Construction toys and educational toys see rising demand as families and early learning centers emphasize cognitive development, problem-solving, and creativity from an early age. Musical toys and rattles stimulate sensory perception and auditory skills in infants, while board games and vehicle toys foster group play, coordination, and imaginative thinking, appealing more to toddlers. Arts and crafts products encourage fine motor skill development and creative expression, supporting holistic early childhood growth.
By Age Group:
Segmentation by age group further refines the market, focusing on infants (0–12 months) and toddlers (1–3 years). The infant segment values toys that support basic sensory development, safety, and soothing, prompting a preference for simple, soft, and non-toxic materials. For toddlers, the emphasis shifts to toys that enable interactive, skill-building experiences, such as construction sets, educational puzzles, and beginner board games, reflecting the rapid development of physical and cognitive abilities during this stage.
By Distribution Channel:
Distribution channels are another crucial aspect of the Baby & Infant Toys Market. Store-based retail, including specialty toy shops, supermarkets, and department stores, retains a strong foothold by offering immediate product access and personalized service. However, non-store-based retail especially e-commerce has expanded swiftly, providing greater product variety, convenience, and the ability to compare prices and read reviews online. E-commerce platforms cater to modern shopping preferences and extend market reach to consumers in both urban and rural areas. This well-defined segmentation strategy allows the Baby & Infant Toys Market to adapt its product innovation, marketing, and distribution approaches, driving sustained growth and market relevance across regions and consumer groups.
Segments:
Based on Product Type:
- Soft Toys & Dolls
- Construction Toys
- Educational Toys
- Musical Toys & Rattles
- Board Games
- Vehicles
- Arts & Crafts
- Others
Based on Age Group:
- Infants (0–12 months)
- Toddlers (1–3 years)
Based on Distribution Channel:
- Store-Based Retail
- Non-Store-Based Retail (E-commerce)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Baby & Infant Toys Market
North America Baby & Infant Toys Market grew from USD 4,236.14 million in 2018 to USD 5,507.48 million in 2024 and is projected to reach USD 7,810.87 million by 2032, reflecting a CAGR of 4.2%. North America accounts for around 33% of the global market share in 2024. The United States leads the region, followed by Canada and Mexico, supported by high consumer spending and strong awareness of developmental benefits associated with infant toys. A mature retail landscape, coupled with high adoption of premium and tech-integrated products, drives consistent demand. E-commerce channels and specialty stores make a wide product range accessible to parents. Strict safety standards and an emphasis on educational value shape brand strategies and consumer choices.
Europe Baby & Infant Toys Market
Europe Baby & Infant Toys Market grew from USD 2,607.81 million in 2018 to USD 3,279.04 million in 2024 and is expected to reach USD 4,296.37 million by 2032, growing at a CAGR of 3.1%. Europe holds a 20% market share in 2024. Key countries such as Germany, the UK, France, and Italy drive regional demand, supported by a focus on sustainability and regulatory compliance. The market benefits from a strong tradition of educational and wooden toys. Retailers expand offerings of organic and eco-friendly products, appealing to environmentally conscious families. Cross-border e-commerce and local manufacturing support growth across both Western and Eastern Europe.
Asia Pacific Baby & Infant Toys Market
Asia Pacific Baby & Infant Toys Market grew from USD 3,513.13 million in 2018 to USD 4,865.62 million in 2024 and is projected to reach USD 7,463.58 million by 2032, reflecting a CAGR of 5.2%. Asia Pacific commands the largest regional share at 29% in 2024. China, Japan, India, South Korea, and Australia are major markets, fueled by rising birth rates, growing disposable incomes, and increasing urbanization. Regional brands focus on innovation, affordability, and safety, appealing to diverse consumer needs. E-commerce and mobile shopping drive rapid growth, while local and international players expand their presence through strategic partnerships.
Latin America Baby & Infant Toys Market
Latin America Baby & Infant Toys Market grew from USD 462.61 million in 2018 to USD 600.07 million in 2024 and is set to reach USD 734.73 million by 2032, at a CAGR of 2.2%. Latin America accounts for 4% of the global market share in 2024. Brazil, Argentina, Chile, and Colombia represent the region’s largest markets, supported by expanding middle classes and a cultural emphasis on family care. Retailers introduce a wider range of developmental and affordable toys. E-commerce penetration is rising, enabling brands to reach underserved communities and boost market visibility. Local adaptations and seasonal marketing drive consumer engagement.
Middle East Baby & Infant Toys Market
Middle East Baby & Infant Toys Market grew from USD 322.63 million in 2018 to USD 388.57 million in 2024 and is projected to reach USD 464.55 million by 2032, registering a CAGR of 1.9%. The Middle East represents about 2% of the global market in 2024. Key countries include the UAE, Saudi Arabia, and Israel, where population growth, rising incomes, and growing awareness of child development drive demand. Brands focus on premium, certified-safe, and culturally tailored products to meet regional preferences. Retailers expand in urban centers and invest in online channels for broader reach. Educational campaigns and partnerships with healthcare providers support ongoing market development.
Africa Baby & Infant Toys Market
Africa Baby & Infant Toys Market grew from USD 242.79 million in 2018 to USD 343.85 million in 2024 and is projected to reach USD 412.35 million by 2032, reflecting a CAGR of 2.0%. Africa holds 2% of the global market in 2024. Nigeria, South Africa, and Egypt are leading countries, driven by high birth rates, urbanization, and increasing consumer awareness. International brands collaborate with local partners to enhance affordability and distribution. Retail infrastructure improvements and government initiatives supporting early childhood development are key growth drivers. The market continues to expand as economic conditions and access to quality products improve.
Key Player Analysis
- Mattel Inc.
- Hasbro Inc.
- The LEGO Group
- VTech Holdings Limited
- Melissa & Doug
- Spin Master Corp.
- Chicco (Artsana Group)
- Playgro
- Bright Starts
- Infantino LLC
- MGA Entertainment
- Bandai Namco Holdings Inc.
- LeapFrog Enterprises Inc.
- Baby Einstein
Competitive Analysis
The Baby & Infant Toys Market features strong competition among leading players, including Mattel Inc., Hasbro Inc., The LEGO Group, VTech Holdings Limited, Melissa & Doug, Spin Master Corp., Chicco (Artsana Group), Playgro, Bright Starts, Infantino LLC, MGA Entertainment, Bandai Namco Holdings Inc., LeapFrog Enterprises Inc., and Baby Einstein. These companies compete on innovation, brand recognition, safety standards, and portfolio diversity to capture and retain consumer loyalty. Market leaders consistently invest in research and development to introduce new educational, interactive, and eco-friendly products that appeal to modern parents and caregivers. Strategic collaborations with licensing partners and child development experts enhance their credibility and product offerings. Strategic partnerships with licensors and child development experts help firms enrich their product lines and enhance market credibility. Companies leverage omnichannel distribution, combining in-store experiences with strong e-commerce strategies to expand reach and improve customer engagement. Intense competition pushes all players to focus on quality, value, and innovation, ensuring the market remains responsive to changing family needs and regulatory requirements
Recent Developments
- In January 2023, the beloved baby boutique, which shut its doors in 2018, is reopening under new management. A new brick-and-mortar location will soon be opening in the American Dream mall in New Jersey.
- In July 2022, in order to develop and promote items that encourage kids and collectors to embrace their inner explorers of space, Mattel, Inc. recently announced that it had reached a multi-year agreement with SpaceX. Under its renowned Matchbox brand, Mattel will start releasing toys in 2023 that are inspired by SpaceX. Parallel to this, Mattel Creations, the company's platform for cooperation and direct sales to consumers, will begin to feature collectibles inspired by space exploration.
Market Concentration & Characteristics
The Baby & Infant Toys Market demonstrates moderate to high market concentration, with a blend of global giants and specialized regional brands shaping the industry landscape. It features strong emphasis on safety, quality, and developmental value, driving manufacturers to comply with stringent regulatory standards and invest in continuous innovation. The market includes a wide variety of products, ranging from traditional soft toys to technologically advanced and educational toys, catering to different age groups and parental expectations. Established brands leverage expansive distribution networks, digital marketing, and collaborations with child development experts to maintain competitive advantage and consumer trust. The market’s characteristics include rapid product turnover, frequent launches of new and themed toys, and growing adoption of eco-friendly materials. E-commerce growth supports broader access and diversity in product offerings, while brick-and-mortar retail remains important for experiential shopping and immediate product availability
Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to grow steadily through 2032, driven by increasing demand for both physical and digital card games.
- Digital transformation will continue to shape the industry, with mobile and online platforms expanding access and enhancing user engagement.
- Collectible and themed card games will gain popularity, attracting both traditional players and new audiences seeking unique gaming experiences.
- Sustainability initiatives, such as eco-friendly materials and packaging, will become more prominent, aligning with consumer preferences for environmentally responsible products.
- Educational and skill-based card games will see increased adoption in schools and learning centers, supporting cognitive development and collaborative learning.
- Emerging markets in Asia Pacific, Latin America, and Africa will offer significant growth opportunities due to rising disposable incomes and expanding urban populations.
- Integration of augmented reality (AR) and virtual reality (VR) technologies will enhance gameplay, providing immersive experiences that blend physical and digital elements.
- Esports and competitive card gaming will expand, with tournaments and online competitions fostering community engagement and brand loyalty.
- Strategic partnerships with entertainment franchises will drive the development of new card game themes, appealing to fans of movies, comics, and video games.
- Omnichannel distribution strategies, combining offline retail and online platforms, will ensure broad product accessibility and cater to diverse consumer preferences.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Parental Focus on Early Childhood Development
Parents are increasingly aware of the importance of early cognitive, sensory, and motor skill development, leading to higher demand for toys that promote learning and skill-building from infancy. Endorsements from child development experts and pediatricians further boost the appeal of educational and developmental toys.
Expansion of Disposable Incomes Among Young Families
Growing disposable incomes, especially in emerging markets, enable young families to invest in higher-quality, branded, and innovative toys, driving market growth across both premium and value segments.
Emphasis on Product Safety and Regulatory Compliance
Stringent safety standards and parental concerns about non-toxic materials push manufacturers to prioritize certified, safe, and eco-friendly toys, enhancing consumer trust and expanding the market for compliant products.
Technological Advancements and Product Innovation
The integration of smart technology, interactive features, and mobile connectivity in toys attracts tech-savvy parents and supports differentiated, engaging play experiences, fueling ongoing product innovation and market expansion.
Growth of E-commerce and Omnichannel Retail
The rise of e-commerce platforms and omnichannel retail strategies increases accessibility and product variety, allowing brands to reach a wider audience and adapt to modern shopping preferences, especially among younger parents.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Baby & Infant Toys Market?
What factors are driving the growth of the Baby & Infant Toys Market?
What are some challenges faced by the Baby & Infant Toys Market?
Who are the major players in the Baby & Infant Toys Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age Group
- 1.2.1 Infants (0–12 months)
- 1.2.2 Toddlers (1–3 years)
- 1.3 By Product Type
- 1.3.1 Soft Toys & Dolls
- 1.3.2 Construction Toys
- 1.3.3 Educational Toys
- 1.3.4 Musical Toys & Rattles
- 1.3.5 Board Games
- 1.3.6 Vehicles
- 1.3.7 Arts & Crafts
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,984.63 million → 2032: USD 21,182.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Baby and Infant Toys Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Baby and Infant Toys Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Baby and Infant Toys Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Baby and Infant Toys Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Baby and Infant Toys Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Baby and Infant Toys Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Baby and Infant Toys Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Baby and Infant Toys Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,984.63 million → 2032: USD 21,182.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Baby and Infant Toys Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age Group - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Infants (0–12 months)
- 12.3.7.2 Toddlers (1–3 years)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Soft Toys & Dolls
- 12.4.7.2 Construction Toys
- 12.4.7.3 Educational Toys
- 12.4.7.4 Musical Toys & Rattles
- 12.4.7.5 Board Games
- 12.4.7.6 Vehicles
- 12.4.7.7 Arts & Crafts
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Baby and Infant Toys Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Baby and Infant Toys Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Baby and Infant Toys Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Mattel Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Hasbro Inc.
- 17.4 The LEGO Group
- 17.5 VTech Holdings Limited
- 17.6 Melissa & Doug
- 17.7 Spin Master Corp.
- 17.8 Chicco (Artsana Group)
- 17.9 MGA Entertainment
- 17.10 Bandai Namco Holdings Inc.
- 17.11 LeapFrog Enterprises Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

