
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
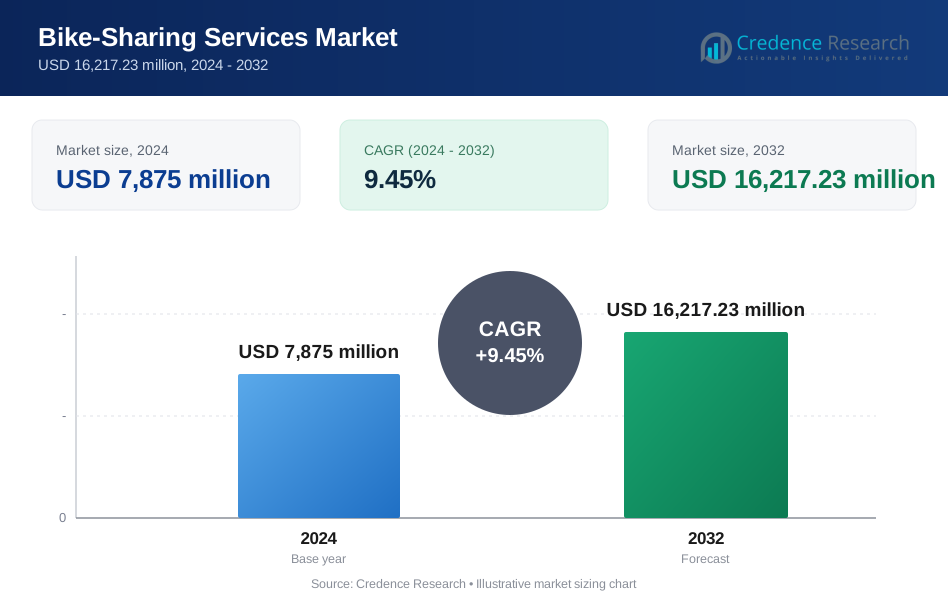
| Bike-sharing Services Market Size 2024 | USD 7,875 million |
| Bike-sharing Services Market, CAGR | 9.45% |
| Bike-sharing Services Market Size 2032 | USD 16,217.23 million |
Market Overview
The bike-sharing services market is projected to grow from USD 7,875 million in 2024 to USD 16,217.23 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 9.45%.
The bike-sharing services market is driven by increasing urbanization and the growing demand for sustainable transportation solutions. As cities aim to reduce traffic congestion and environmental impact, bike-sharing programs offer a convenient and eco-friendly alternative. Technological advancements, such as mobile applications and GPS tracking, enhance user experience and operational efficiency. Additionally, government initiatives promoting green mobility and investments in cycling infrastructure further bolster market growth. Consumer preferences are shifting towards healthier lifestyles, contributing to the rising popularity of bike-sharing services as a viable transportation option, ultimately transforming urban mobility landscapes worldwide.
The bike-sharing services market is growing globally, with prominent regions including Asia-Pacific and North America. Asia-Pacific, led by China, holds the largest market share due to high urban density and strong government support for eco-friendly transit. North America, especially the U.S. and Canada, is advancing with smart city investments and rising demand for flexible commuting options. Key players driving this market include Ofo, Meituandianping Inc., PBSC Urban Solutions, Nextbike GmbH, Donkey Republic, and Motivate Inc., all of whom offer a mix of docked, dockless, and e-bike solutions to meet varying urban mobility needs and promote sustainable transportation.
Market Drivers
Environmental Concerns
Bike-sharing services play a crucial role in addressing environmental challenges by significantly reducing carbon emissions and improving air quality. For instance, a study found that bike-sharing systems in Shanghai saved 25,240 tons of CO2 emissions. By decreasing reliance on personal vehicles, these services contribute to cleaner urban environments, promoting sustainable urban mobility solutions that minimize environmental harm. As cities strive to combat climate change and enhance livability, bike-sharing systems emerge as effective alternatives, supporting efforts to create greener, healthier communities.
Urban Congestion and Traffic
The rise of bike-sharing services presents an efficient solution for navigating congested urban areas. By encouraging more people to use bicycles, these programs help alleviate traffic congestion, resulting in reduced travel times and improved overall mobility. For example, research in Washington DC showed that bike-sharing reduced traffic congestion by 3-4%. Additionally, bike-sharing systems complement public transportation by providing convenient first and last-mile connectivity, making it easier for commuters to reach their destinations without the hassle of driving.
Technological Advancements and Government Support
Technological innovations are enhancing the bike-sharing experience, with user-friendly mobile apps simplifying bike access and payment processes. Real-time GPS tracking and smart lock technology improve bike management and security, making these services more appealing. For instance, the integration of GPS tracking and smart locks has revolutionized the user experience by making bike-sharing more convenient and efficient. Government support, including the development of bike-friendly infrastructure and financial incentives, further encourages bike usage. Public-private partnerships are also instrumental in accelerating the deployment of bike-sharing systems, ensuring they meet the evolving needs of urban populations.
Health and Wellness
Beyond environmental benefits, bike-sharing services promote physical activity and support healthier lifestyles. Cycling offers an enjoyable way to exercise, helping individuals integrate fitness into their daily routines. Additionally, riding a bike can significantly reduce stress and enhance mental well-being, making it a cost-effective fitness option for many. As people become more health-conscious, bike-sharing services align well with the growing trend of prioritizing wellness.
Market Trends
Rise of Electric Bike Sharing and Public Transportation Integration
The bike-sharing market is witnessing a significant trend with the rise of electric bike-sharing services. These electric bikes offer increased range and speed, making them ideal for longer commutes and challenging terrains. By assisting with pedaling, they reduce physical exertion, broadening accessibility for a diverse user base, including older adults and individuals with limited physical abilities. Moreover, electric bikes enhance the overall user experience, providing a smoother and more enjoyable ride, particularly in urban areas plagued by traffic congestion. Concurrently, bike-sharing services are increasingly integrating with public transportation systems, facilitating seamless first and last-mile connectivity. This integration allows users to combine bike-sharing with buses, trains, and other modes of transport, creating a more efficient and environmentally friendly commuting option. As cities strive for a more cohesive and sustainable transportation network, the collaboration between bike-sharing and public transit systems becomes a vital aspect of urban mobility strategies.
Data-Driven Operations and Sustainability Focus
Another emerging trend in the bike-sharing sector is the adoption of data-driven operations. Operators leverage real-time data analysis to optimize fleet management, predict demand, and enhance the user experience. For instance, Citi Bike in New York City uses data-driven optimization to guide their rebalancing efforts, ensuring bikes are available where needed. Predictive maintenance powered by data analytics ensures that bikes are well-maintained, reducing downtime and ensuring optimal performance. Additionally, personalized user experiences can be achieved by analyzing user data, allowing operators to offer tailored recommendations and promotions that enhance user satisfaction. In parallel, there is a growing emphasis on sustainability and social impact within the industry. Bike-sharing companies are adopting eco-friendly practices, such as utilizing renewable energy sources and recycling materials in their operations. A study noted that bike-sharing systems saved the equivalent of 13,370 tons of oil and reduced CO2 emissions by 30,070 tons. Community engagement initiatives are also on the rise, with operators partnering with local organizations to promote cycling and enhance urban infrastructure. Furthermore, efforts to ensure social equity are gaining traction, aiming to make bike-sharing services accessible to underserved communities and promote equitable access to transportation.
Market Challenges Analysis
Vandalism, Theft, and Financial Sustainability Challenges
The bike-sharing industry faces significant challenges related to vandalism and theft, which can greatly impact operational efficiency and costs. For instance, a study found that up to 10% of bike-sharing fleets can be stolen or destroyed each year. Bikes are often subject to damage from vandalism, necessitating costly repairs and replacements that burden the operating budget. Additionally, theft poses a serious threat, as stolen bikes not only diminish the available fleet but also lead to increased operational costs for bike-sharing companies. These financial pressures are compounded by high operational costs associated with bike procurement, maintenance, and technology. For many companies, generating sufficient revenue to cover these expenses and achieve profitability proves challenging, particularly in smaller markets where user demand may fluctuate.
Infrastructure, User Education, and Competition
Inadequate infrastructure presents another hurdle for bike-sharing services, as a lack of dedicated bike lanes can deter potential users and heighten safety risks. The absence of supportive cycling infrastructure often results in users feeling unsafe, especially in high-traffic areas. Furthermore, strict regulations concerning bike parking, licensing, and operational guidelines can inhibit the expansion of bike-sharing services. Additionally, user education plays a critical role in the success of these programs. Many potential users harbor safety concerns that prevent them from utilizing bike-sharing services, while others may lack knowledge of proper cycling etiquette. This can lead to improper bike usage and parking, resulting in conflicts with pedestrians and other road users. Compounding these issues is the growing competition from alternative mobility services, such as well-established public transportation systems and ride-sharing or e-scooter options. These rivals can divert users away from bike-sharing, further challenging its growth and sustainability in the urban mobility landscape.
Market Segmentation Analysis:
By Bike Type:
The bike-sharing services market is segmented by bike type into traditional/conventional bikes and electric bikes (e-bikes). Traditional bikes remain popular due to their simplicity, affordability, and low maintenance requirements. They are commonly used in areas with moderate distances and flat terrains, providing a sustainable and low-cost transportation option for short trips. E-bikes, however, are gaining substantial traction due to their ability to cover longer distances and navigate challenging terrains. With built-in motor assistance, e-bikes offer enhanced speed and convenience, making them attractive for users seeking faster commutes or less physical exertion. The rising demand for e-bikes aligns with the growth of eco-friendly transportation options, as they offer a practical alternative to motor vehicles. This segment’s growth is propelled by increased urbanization and technological advancements, making e-bikes an integral part of modern urban mobility solutions.
By Sharing System
Based on the sharing system, the bike-sharing market is divided into docked and dockless systems. Docked bike-sharing systems require users to pick up and return bikes at designated stations, providing a structured and easily manageable approach for operators. This system benefits from organized bike parking and reduced risk of vandalism, but its usage is often limited by station locations. In contrast, dockless systems provide users with greater flexibility, allowing them to pick up and park bikes at any convenient location. While dockless bike-sharing enhances accessibility and convenience, it poses challenges related to bike rebalancing, parking, and potential misuse. The dockless model is rapidly expanding, driven by user demand for flexible mobility solutions, but successful management of this system requires robust technological solutions for tracking, rebalancing, and maintaining bikes. Both systems play significant roles in urban bike-sharing markets, catering to diverse user preferences and commuting needs.
Segments:
Based on Bike Type
- Traditional/Convectional
- E-Bikes
Based on Sharing System
- Docked
- Dock-less
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds approximately 25% of the global bike-sharing services market, driven by increasing urbanization, eco-friendly government initiatives, and a focus on reducing traffic congestion in major cities. The United States and Canada lead in this region, with cities like New York, Washington D.C., and Toronto hosting established bike-sharing programs. These urban centers have invested in infrastructure such as bike lanes and docking stations, supporting the growth of both docked and dockless systems. There is also a growing demand for e-bike options, appealing to users seeking faster and more flexible transport solutions. With investments in smart city projects, North America is anticipated to advance its bike-sharing sector further by incorporating digital solutions that enhance accessibility, bike tracking, and fleet management.
Asia-Pacific
Asia-Pacific dominates the global bike-sharing market with an estimated 45% market share, led by countries like China, Japan, and India. China, in particular, has a vast and mature bike-sharing landscape fueled by high urban density and demand for affordable, sustainable transportation. Rapid urbanization in this region has led governments to promote eco-friendly mobility solutions to address pollution and congestion challenges. The popularity of dockless systems has surged, as they provide unmatched flexibility compared to traditional docked models. The adoption of e-bikes is also on the rise, supported by technological advancements and user preferences for faster, less strenuous commuting. With strong government backing and urban infrastructure development, Asia-Pacific is expected to maintain its leadership in the global bike-sharing market, driven by population density and sustainability goals.
Key Player Analysis
- Ofo
- Mobile
- Nextbike GmbH
- PBSC Urban Solutions
- Beijing Xiaoju Technology
- Meituandianping Inc.
- Motivate Inc.
- Donkey Republic
- Flick Bike
- Hello-Bike
- Urbo Solutions
- Zagster
Competitive Analysis
The bike-sharing services market is highly competitive, with leading players like Ofo, Meituandianping Inc., PBSC Urban Solutions, Nextbike GmbH, Donkey Republic, and Motivate Inc. vying for market dominance. These companies focus on expanding their services through innovative models, including docked, dockless, and e-bike options to cater to diverse user preferences. Competitive strategies vary, with some players leveraging extensive fleets and advanced technology, such as GPS tracking and mobile app integration, to enhance user convenience and safety. Other providers focus on partnerships with local governments to support infrastructure and align with urban transit systems. Environmental sustainability is a shared priority, as leading companies increasingly adopt eco-friendly practices like renewable energy sources and community engagement initiatives. This intense competition encourages continuous advancements in service quality, accessibility, and affordability, positioning these key players at the forefront of urban mobility solutions.
Recent Developments
- In January 2024, In collaboration with Transdev Portugal, the forthcoming bike-sharing system from nextbike by TIER seamlessly integrates with the local public transportation fare system, offering the potential for sustainable and accessible mobility. Nextbike by TIER, a bike-sharing operator based in Europe, has recently declared a substantial expansion into Portugal. This development marks the inaugural deployment of the company's cutting-edge bike-sharing system in the city of Barcelos. Nextbike, after its recent triumph in Spain, is poised to bring about a paradigm shift in sustainable mobility within the coastal metropolis.
- In March 2023, MYBYK launched two electric bicycle variants, MYBYK Electric and MYBYK Electric Cargo. The MYBYK Electric model is designed to cater to the needs of both citizens and tourists, offering a solution for convenient first and last-mile connectivity. On the other hand, the MYBYK Electric Cargo model targets gig-workers and aims to address the last-mile delivery challenges they face.
- In June 2022, Anywheel Pte. Ltd. expanded its business and started shared bike service in Ang Mo Kio, Pasir Ris, Punggol and Tampines. The expansion of areas covered by the firm comes after Anywheel secured approval from the Land Transport Authority (LTA) to double its fleet size to 30,000 shared bicycles.
Market Concentration & Characteristics
The bike-sharing services market demonstrates a moderate to high concentration, with major players such as Ofo, Meituandianping Inc., and PBSC Urban Solutions holding a significant share. This concentration is influenced by the substantial capital investment required for fleet expansion, technology integration, and maintenance, favoring larger, established companies. Key characteristics of this market include rapid adoption of dockless and e-bike solutions, responding to urban users’ demand for flexibility and longer commuting options. Additionally, the market is marked by its reliance on technology, with GPS tracking, mobile apps, and smart locks being crucial for seamless operations and user convenience. Despite high entry barriers, regional and local providers are entering the market, targeting niche segments or partnering with municipalities to overcome infrastructure challenges. Overall, the bike-sharing market is characterized by competition focused on innovation, environmental sustainability, and strategic collaborations with local governments, all of which shape the evolving landscape of urban mobility.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Bike Type, Sharing System and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The bike-sharing market is expected to grow as cities increasingly prioritize sustainable urban mobility solutions.
- E-bike adoption is likely to surge, attracting users seeking faster commutes and expanded range.
- Advancements in GPS and mobile technology will enhance fleet management, user convenience, and security.
- Integration with public transportation systems will improve first and last-mile connectivity for commuters.
- Governments are projected to expand bike-friendly infrastructure, supporting the demand for bike-sharing services.
- Increased data-driven operations will enable predictive maintenance and personalized user experiences.
- Subscription-based models may gain traction, offering flexible, cost-effective options for long-term users.
- Companies are expected to continue adopting eco-friendly practices, supporting global sustainability goals.
- Expanding into underserved regions and communities may create new growth opportunities for providers.
- Competition with alternative mobility solutions like e-scooters and ride-sharing is likely to shape future market dynamics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Bike-sharing Services Market?
What factors are driving the growth of the Bike-sharing Services?
What are the key segments within the Bike-sharing Services?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bike-Sharing Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bike-Sharing Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,875 million → 2032: USD 16,217.23 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bike-Sharing Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bike-Sharing Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bike-Sharing Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bike-Sharing Services Market Drivers
- 3.3 Bike-Sharing Services Market Restraints & Challenges
- 3.4 Bike-Sharing Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bike-Sharing Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bike-Sharing Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bike-Sharing Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bike-Sharing Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bike-Sharing Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bike-Sharing Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bike-Sharing Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bike-Sharing Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bike-Sharing Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bike-Sharing Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bike-Sharing Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bike-Sharing Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bike-Sharing Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bike-Sharing Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bike-Sharing Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bike-Sharing Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bike-Sharing Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bike-Sharing Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bike-Sharing Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
