
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Regulatory Affairs Outsourcing Market Size 2024 | USD 8420 million |
| Regulatory Affairs Outsourcing Market, CAGR | 10.4% |
| Regulatory Affairs Outsourcing Market Size 2032 | USD 18580.81 million |
Market Overview:
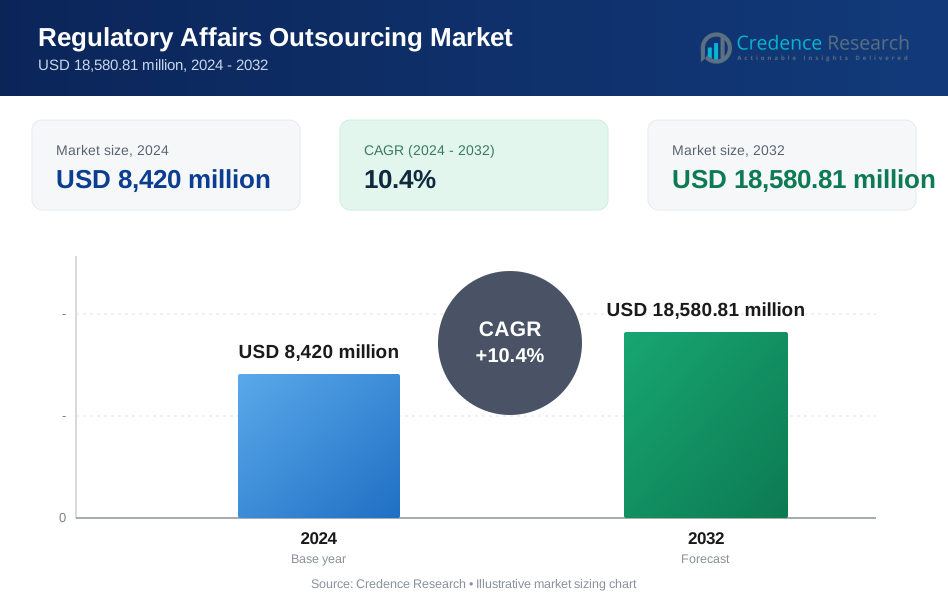
The Regulatory Affairs Outsourcing Market is projected to grow from USD 8420 million in 2024 to an estimated USD 18580.81 million by 2032, with a compound annual growth rate (CAGR) of 10.4% from 2024 to 2032.
Several factors are driving the growth of the Regulatory Affairs Outsourcing Market. The rapidly evolving regulatory environment, particularly in highly regulated sectors like pharmaceuticals, biotechnology, and medical devices, has increased the complexity and cost of compliance for companies. As a result, organizations are increasingly turning to specialized outsourcing firms to manage regulatory submissions, compliance, and post-approval processes. The need to accelerate time-to-market for new products, coupled with the challenge of keeping pace with regional regulatory differences, is pushing companies to rely on external expertise. Additionally, the growing number of clinical trials, product launches, and international expansions are further fueling demand for regulatory affairs outsourcing. Outsourcing allows companies to focus on core competencies while ensuring adherence to stringent regulations, making it a cost-effective and efficient solution.
North America dominates the Regulatory Affairs Outsourcing Market, accounting for the largest market share due to its well-established pharmaceutical and biotechnology sectors, and the presence of numerous outsourcing service providers. The United States, in particular, leads the region, driven by stringent regulatory requirements from agencies such as the U.S. Food and Drug Administration (FDA) and the need for specialized expertise. Europe follows closely, with countries like Germany and the UK emphasizing regulatory compliance in life sciences and healthcare. The Asia-Pacific region is expected to witness the fastest growth, driven by the expanding pharmaceutical and biotechnology sectors in countries like India and China. Additionally, the region’s growing focus on clinical trials and international product launches, along with lower labor costs, makes it an attractive destination for outsourcing regulatory affairs.
Market Drivers:
Increasing Complexity of Regulatory Requirements:
One of the primary drivers of the Regulatory Affairs Outsourcing Market is the increasing complexity of global regulatory requirements, particularly in highly regulated sectors such as pharmaceuticals, biotechnology, and medical devices. Regulatory agencies worldwide, including the U.S. Food and Drug Administration (FDA), European Medicines Agency (EMA), and others, have continually updated their guidelines and regulations to ensure product safety and efficacy. Keeping pace with these evolving requirements has become a challenge for companies, particularly as they expand into multiple markets. The need for specialized knowledge and expertise in navigating these regulatory environments has made outsourcing regulatory affairs a more attractive option, enabling companies to ensure compliance while focusing on their core competencies.
Rising Demand for Cost Efficiency:
Cost efficiency is a significant driver in the Regulatory Affairs Outsourcing Market. Managing regulatory compliance in-house requires substantial investment in resources, infrastructure, and personnel with specialized knowledge. For many companies, especially small to mid-sized enterprises, maintaining an internal regulatory affairs team is costly and often inefficient. Outsourcing regulatory processes allows companies to access expertise without the high costs associated with staffing, training, and maintaining a dedicated in-house team. Additionally, outsourcing provides flexibility in managing workload fluctuations, allowing organizations to scale services as needed without long-term commitments to personnel. This shift toward outsourcing regulatory affairs enables companies to optimize their operational costs while ensuring compliance with stringent regulatory requirements.
Shortening Time-to-Market:
The pressure to bring new products to market quickly is another key driver of the Regulatory Affairs Outsourcing Market. In the life sciences and healthcare industries, where competition is fierce and product lifecycles are short, companies must accelerate product development and regulatory approval processes to maintain a competitive edge. Outsourcing regulatory affairs allows businesses to leverage external expertise and resources to navigate the complexities of product approvals, reducing delays in submissions and increasing the chances of faster regulatory approvals. For instance, a report by the National Health Expenditures (NHE) prepared by the Office of the Actuary at the Centers for Medicare & Medicaid Services (CMS) forecasts that national health spending will reach nearly $6.8 trillion by 20301. This is particularly important for companies involved in clinical trials, product launches, and international expansions, where delays in regulatory processes can significantly impact time-to-market and revenue generation.
Globalization and Regional Regulatory Variations:
As companies expand their operations globally, they must navigate a patchwork of varying regulatory requirements across different regions. The need for local expertise to ensure compliance with regional regulations, while simultaneously adhering to global standards, has driven demand for outsourcing services that can offer specialized knowledge across multiple jurisdictions. A survey by Avoca found that clients outsourced $1.2 billion worth of clinical development work to manage these complexities. Outsourcing firms often have a global presence and in-depth understanding of local regulatory environments, making them invaluable partners for companies expanding into new markets. This trend is particularly strong in emerging markets like Asia-Pacific, where regulatory landscapes are evolving, and companies require expert guidance to navigate these complexities. By outsourcing regulatory affairs, companies can manage global regulatory strategies more efficiently and reduce the risk of non-compliance, which can delay market entry or lead to costly penalties.
Market Trends:
Increasing Adoption of Technology-Driven Solutions:
One of the most notable trends in the Regulatory Affairs Outsourcing Market is the growing adoption of technology-driven solutions. As the complexity of regulatory processes increases, outsourcing firms are leveraging advanced technologies such as artificial intelligence (AI), machine learning (ML), and automation to streamline regulatory submissions and compliance activities. These technologies enable faster data analysis, enhance accuracy, and reduce the time required to complete regulatory tasks. For instance, data from companies show that Accell Clinical Research, LLC has implemented AI-driven solutions that reduced their regulatory submission time by 15 days. Regulatory affairs teams are now using cloud-based platforms and digital tools to manage documentation, ensure version control, and maintain compliance records more efficiently. This technological shift is transforming the regulatory affairs landscape by improving operational efficiency and allowing companies to navigate the complex global regulatory environment with greater ease.
Growth of Strategic Partnerships and Collaborations:
Strategic partnerships and collaborations between pharmaceutical companies, biotechnology firms, and regulatory outsourcing providers are on the rise. As regulatory demands become more challenging, organizations are seeking partnerships with outsourcing firms that offer specialized knowledge and regional expertise. These partnerships enable companies to access tailored solutions that align with their specific needs and market requirements. Additionally, collaborative efforts between outsourcing providers and regulatory agencies help streamline the approval process for new products, especially in the life sciences sector. These collaborations are not only enhancing the quality of regulatory submissions but also speeding up time-to-market by ensuring that regulatory affairs are handled efficiently and effectively.
Focus on End-to-End Outsourcing Services:
Another significant trend in the Regulatory Affairs Outsourcing Market is the growing demand for end-to-end outsourcing services. Rather than outsourcing specific regulatory tasks, companies are increasingly seeking comprehensive solutions that cover the entire regulatory lifecycle, from early-stage product development through to post-approval compliance. This trend is particularly prevalent in the pharmaceutical and medical device industries, where the regulatory process is lengthy and complex. End-to-end services include regulatory strategy development, dossier preparation, submissions management, and post-market surveillance, allowing companies to focus on their core business activities while outsourcing partners handle all aspects of regulatory compliance. The demand for these full-service offerings is expected to grow as companies recognize the value of having a single point of contact for all regulatory needs.
Rising Outsourcing in Emerging Markets:
The expansion of the Regulatory Affairs Outsourcing Market into emerging markets is another important trend shaping the industry. Countries in the Asia-Pacific region, particularly India and China, have become key destinations for outsourcing regulatory processes due to their growing life sciences sectors, lower labor costs, and improving regulatory infrastructure. Many outsourcing firms have established a presence in these regions to capitalize on the rising demand for regulatory services. Additionally, as companies in these regions expand their global footprint, they are increasingly turning to outsourcing partners to help them navigate the regulatory requirements of international markets. This trend is expected to continue as the pharmaceutical and biotechnology industries in emerging markets grow, driving the demand for expert regulatory support across multiple regions. For instance, data from companies such as Accell Clinical Research LLC shows the increasing reliance on outsourcing partners in these regions. According to a study by Accell Clinical Research LLC, the number of regulatory submissions managed by outsourcing partners in India and China increased by 1,200 and 1,500 respectively over the past five years
Market Restraints and Challenges:
Regulatory Compliance and Constantly Changing Guidelines:
One of the key restraints in the Regulatory Affairs Outsourcing Market is the ever-evolving nature of regulatory guidelines. Regulatory agencies such as the U.S. Food and Drug Administration (FDA), European Medicines Agency (EMA), and others frequently update their rules and requirements to ensure product safety and efficacy. This constant change poses a challenge for outsourcing firms that must remain up to date with the latest guidelines across different regions. If an outsourcing firm fails to meet these evolving standards, it can result in delays, non-compliance penalties, and, in some cases, product rejection. Keeping pace with global regulatory changes is a significant challenge that requires continuous investment in expertise and technology, limiting the market's growth potential.
Data Security and Confidentiality Concerns:
Data security and confidentiality are major concerns in the Regulatory Affairs Outsourcing Market. Regulatory processes involve handling sensitive company data, intellectual property, and proprietary information. Outsourcing these tasks to third-party providers creates potential risks related to data breaches or leaks. Companies, particularly in highly regulated industries like pharmaceuticals and biotechnology, are often hesitant to outsource critical regulatory affairs due to concerns about the protection of their sensitive information. Ensuring that outsourcing partners adhere to strict data security protocols is crucial, but it remains a significant challenge, especially when outsourcing to firms in regions with differing data privacy regulations.
High Cost of Outsourcing and Managing Relationships:
The cost of outsourcing regulatory affairs can be another barrier for some companies, particularly small to mid-sized enterprises. While outsourcing offers cost-efficiency in some cases, the initial investment in finding a reliable outsourcing partner, ensuring compliance with various regulations, and maintaining effective communication can be substantial. Additionally, managing an outsourcing partnership requires constant oversight, including quality control and timely deliverables, which can add to the operational burden for companies. These challenges, coupled with the need to balance cost-saving with quality and reliability, can limit the full adoption of outsourcing in the regulatory affairs market.
Market Segmentation Analysis:
By Service, regulatory consulting and product registration & clinical trial applications dominate the market as companies increasingly rely on external expertise to navigate complex regulatory frameworks. Legal representation and regulatory writing & publication services are also in demand, particularly for ensuring compliance with global regulatory agencies.
By Category, the market is segmented into biologics, drugs, and medical devices. The drugs segment currently holds the largest share due to the high volume of regulatory filings in the pharmaceutical sector. However, the biologics and medical devices segments are expected to grow rapidly due to increasing innovation and product development in these areas.
By Indication, oncology, neurology, and immunology are leading segments due to the high demand for regulatory services in these therapeutic areas, driven by the number of clinical trials and new product launches. Cardiology and other therapeutic segments also contribute to the market as more treatments require regulatory approval.
By Stage, preclinical and clinical stages dominate as most companies seek regulatory outsourcing for early-stage development. The post-market authorization stage is also significant as companies must comply with ongoing regulations even after product approval.
By End User, pharmaceutical companies represent the largest segment due to the sheer volume of drug development activities, followed by biotechnology and medical device companies, which are growing rapidly as they expand into new markets and require regulatory support.
Segmentation:
By Service
- Legal Representation
- Regulatory Consulting
- Product Registration & Clinical Trial Application
- Regulatory Writing & Publication
- Others
By Category
- Biologics
- Drugs
- Medical Devices
By Indication
- Neurology
- Oncology
- Immunology
- Cardiology
- Others
By Stage
- Clinical
- Preclinical
- Post Market Authorization
By End User
- Medical Device Company
- Biotechnology Company
- Pharmaceutical Company
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis:
North America
North America holds the largest share in the Regulatory Affairs Outsourcing Market, accounting for approximately 40% of the global market. The region’s dominance is primarily driven by the robust presence of pharmaceutical, biotechnology, and medical device industries, particularly in the United States. The stringent regulatory requirements imposed by agencies like the U.S. Food and Drug Administration (FDA) have led many companies to seek external expertise to ensure compliance. Furthermore, the high number of clinical trials and product approvals in North America increases the demand for outsourcing regulatory services. Canada also contributes to the region’s market share, benefiting from its growing life sciences sector and the rising number of companies seeking to expand their operations internationally. The advanced healthcare infrastructure and strong focus on research and development further fuel market growth in this region.
Europe
Europe holds the second-largest share of the Regulatory Affairs Outsourcing Market, accounting for about 30% of the global market. Countries such as Germany, the United Kingdom, and France play a crucial role in driving market growth. The presence of the European Medicines Agency (EMA) and the region's complex regulatory framework create significant demand for outsourcing services. In addition, the growing focus on clinical trials and drug development in Europe, along with the increasing number of biopharmaceutical companies, drives the need for specialized regulatory consulting and product registration services. Europe’s commitment to innovation in the life sciences and medical device industries further supports the demand for regulatory affairs outsourcing.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the Regulatory Affairs Outsourcing Market, with its market share projected to increase from 20% to 25% by 2032. Countries like India, China, and Japan are leading this growth due to their expanding pharmaceutical and biotechnology sectors. The lower labor costs in these regions, combined with the growing focus on clinical trials and drug development, make Asia-Pacific an attractive destination for outsourcing regulatory affairs. Additionally, governments in these countries are increasingly supporting regulatory reforms and innovation in life sciences, which enhances the region’s attractiveness for multinational companies seeking cost-effective regulatory solutions. India and China, in particular, have become key hubs for regulatory outsourcing, with many global companies establishing partnerships with local firms to navigate regional regulations.
Rest of the World
The Rest of the World, including Latin America, the Middle East, and Africa, accounts for approximately 10% of the global Regulatory Affairs Outsourcing Market. These regions are witnessing gradual growth due to the expansion of pharmaceutical and medical device companies into emerging markets. Governments in these regions are increasingly focusing on improving regulatory frameworks and healthcare infrastructure, which is expected to drive further demand for outsourcing services. However, the market in these regions remains less mature compared to North America, Europe, and Asia-Pacific.
Key Player Analysis:
- Accell Clinical Research, LLC.
- Covance
- Criterium, Inc.
- Freyr
- Genpact Ltd.
- ICON Plc
- Medpace
- Pharmaceutical Product Development LLC.
- PRA Health Sciences
- WuXiAppTec, Inc.
Competitive Analysis:
The Regulatory Affairs Outsourcing Market is highly competitive, with several key players dominating due to their expertise and global presence. Major firms such as ICON Plc, Parexel International Corporation, Covance Inc., and Charles River Laboratories lead the market, offering comprehensive regulatory services across various industries like pharmaceuticals, biotechnology, and medical devices. These companies leverage their extensive knowledge of global regulatory frameworks and maintain strong relationships with regulatory agencies such as the FDA and EMA. Smaller and specialized firms are also gaining traction by offering niche services, such as regulatory writing, product registration, and clinical trial applications. The increasing complexity of global regulations has driven demand for outsourcing, leading to intense competition among both large multinational firms and regional players. Additionally, partnerships and strategic alliances between pharmaceutical companies and regulatory service providers are becoming common as companies seek to accelerate product approvals and navigate complex international regulatory landscapes more efficiently.
Recent Developments:
- In January 2023, AmerisourceBergen Corporation expanded its service portfolio in the life sciences industry by acquiring PharmaLex Holding GmbH, a leading provider of regulatory affairs services. This acquisition significantly enhanced AmerisourceBergen's market presence.
- In April 2022, VCLS partnered with EC Innovations, a global provider of translation services with extensive expertise in translating highly regulated life sciences and medical content. This collaboration bolstered VCLS's service offerings and operational capabilities.
Market Concentration & Characteristics:
The Regulatory Affairs Outsourcing Market is moderately concentrated, with a few large multinational firms, such as ICON Plc, Parexel International Corporation, and Charles River Laboratories, dominating a significant portion of the market. These companies possess vast global networks and expertise in navigating complex regulatory frameworks, which gives them a competitive edge. However, there is also a presence of smaller, specialized firms that offer niche services, such as regulatory writing and local market compliance, allowing them to carve out a market share. The market is characterized by its growing reliance on technological innovations, including automation and artificial intelligence, which are transforming the efficiency of regulatory processes. Additionally, the increasing complexity of global regulations and the push for faster time-to-market for new products are driving demand for outsourcing services. Companies value outsourcing for its ability to provide cost-effective, flexible, and scalable solutions to meet their regulatory needs across multiple regions.
Report Coverage:
The research report offers an in-depth analysis based on By Service, By Category, By Indication, By Stage and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Regulatory Affairs Outsourcing Market is expected to grow significantly, driven by increasing regulatory complexity across industries.
- Technological advancements such as AI and automation will continue to enhance the efficiency of regulatory processes.
- Demand for outsourcing services will rise as companies seek cost-effective solutions for managing global regulatory compliance.
- The pharmaceutical and biotechnology sectors will remain the largest contributors to market growth due to high regulatory requirements.
- Emerging markets in Asia-Pacific, particularly India and China, will experience rapid growth as companies look for cost-effective regulatory solutions.
- Partnerships between pharmaceutical companies and outsourcing firms will increase to streamline product approvals and accelerate time-to-market.
- Regulatory consulting and clinical trial applications will remain high-demand services as companies expand into new markets.
- The rise of biologics and biosimilars will drive additional demand for specialized regulatory expertise.
- Data security concerns may lead to greater investment in cybersecurity measures within outsourcing firms.
- The market is expected to see further consolidation, with larger firms acquiring smaller, niche players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Complexity of Regulatory Requirements
The evolving and stringent regulatory frameworks in pharmaceuticals, biotechnology, and medical devices require specialized expertise, prompting companies to outsource regulatory affairs to ensure compliance and avoid costly delays.
Need for Cost Efficiency
Outsourcing regulatory affairs allows organizations to reduce the high costs associated with maintaining in-house regulatory teams, infrastructure, and training, making it a more flexible and scalable solution, especially for small and mid-sized enterprises.
Accelerating Time-to-Market
Companies face intense competition and short product lifecycles, so outsourcing regulatory processes to experienced partners helps expedite submissions and approvals, enabling faster product launches and improved revenue generation.
Globalization and Regional Regulatory Variations
As companies expand internationally, they must navigate diverse regulatory environments; outsourcing provides access to local expertise and global compliance strategies, reducing the risk of non-compliance and facilitating smoother market entry.
Adoption of Technology-Driven Solutions
The integration of AI, automation, and digital platforms by outsourcing providers streamlines regulatory submissions and compliance management, increasing efficiency and accuracy, and making outsourcing more attractive to companies facing complex regulatory demands.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Regulatory Affairs Outsourcing Market?
What is driving the growth of the Regulatory Affairs Outsourcing Market?
Which regions dominate the Regulatory Affairs Outsourcing Market?
What challenges does the market face?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Stage
- 1.2.1 Preclinical
- 1.2.2 Clinical
- 1.2.3 Post Market Authorization
- 1.3 By Service
- 1.3.1 Legal Representation
- 1.3.2 Regulatory Consulting
- 1.3.3 Product Registration & Clinical Trial Application
- 1.3.4 Regulatory Writing & Publication
- 1.3.5 Others
- 1.4 By Category
- 1.4.1 Biologics
- 1.4.2 Drugs
- 1.4.3 Medical Devices
- 1.5 By End User
- 1.5.1 Pharmaceutical Company
- 1.5.2 Biotechnology Company
- 1.5.3 Medical Device Company
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,420 million → 2032: USD 18,580.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Regulatory Affairs Outsourcing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Regulatory Affairs Outsourcing Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Regulatory Affairs Outsourcing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Regulatory Affairs Outsourcing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Regulatory Affairs Outsourcing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Regulatory Affairs Outsourcing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Regulatory Affairs Outsourcing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Regulatory Affairs Outsourcing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,420 million → 2032: USD 18,580.81 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Regulatory Affairs Outsourcing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Stage - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Preclinical
- 12.3.6.2 Clinical
- 12.3.6.3 Post Market Authorization
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Legal Representation
- 12.4.6.2 Regulatory Consulting
- 12.4.6.3 Product Registration & Clinical Trial Application
- 12.4.6.4 Regulatory Writing & Publication
- 12.4.6.5 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Category - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Biologics
- 12.5.6.2 Drugs
- 12.5.6.3 Medical Devices
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By End User - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Pharmaceutical Company
- 12.6.6.2 Biotechnology Company
- 12.6.6.3 Medical Device Company
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Regulatory Affairs Outsourcing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Regulatory Affairs Outsourcing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Regulatory Affairs Outsourcing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Regulatory Affairs Outsourcing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ICON Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Covance
- 18.4 Charles River Laboratories
- 18.5 Parexel International Corporation
- 18.6 Accell Clinical Research, LLC
- 18.7 Genpact Ltd.
- 18.8 Medpace
- 18.9 Pharmaceutical Product Development LLC
- 18.10 WuXiAppTec, Inc.
- 18.11 Freyr
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

