
Market Overview:
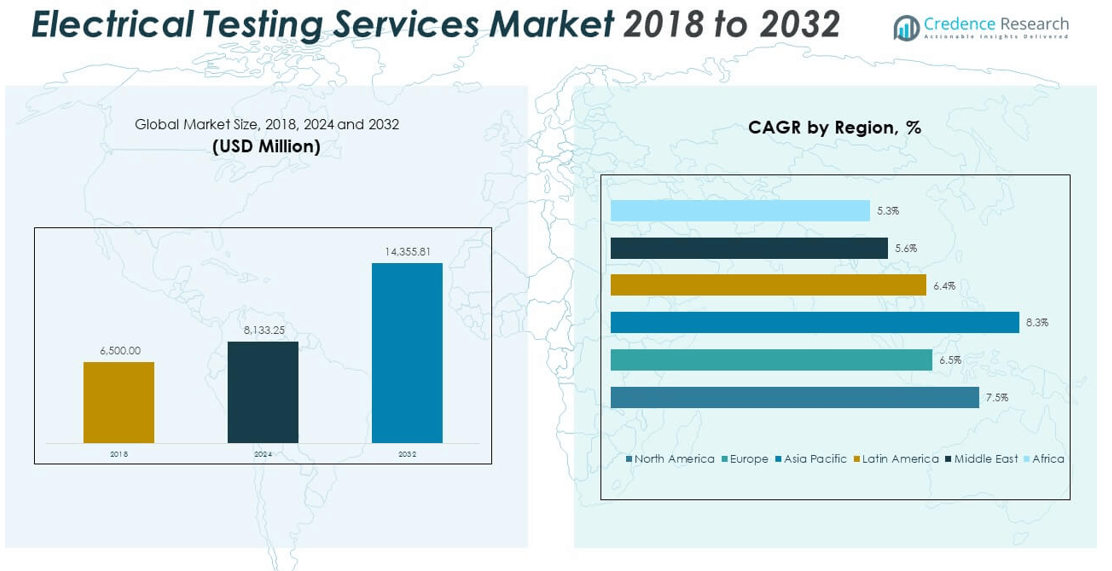
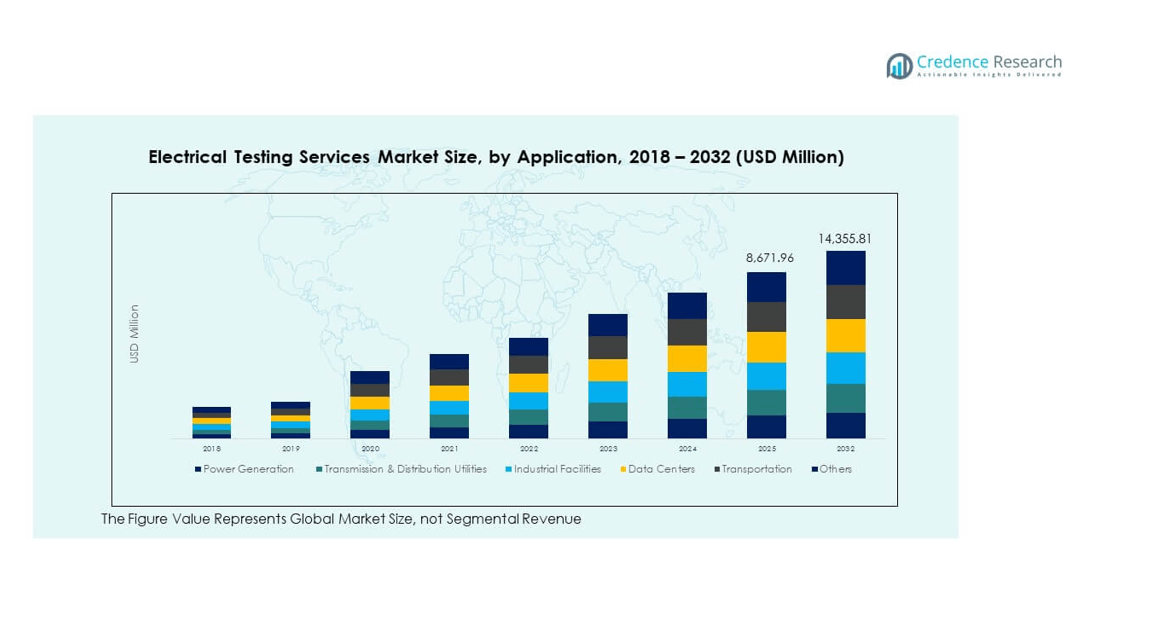
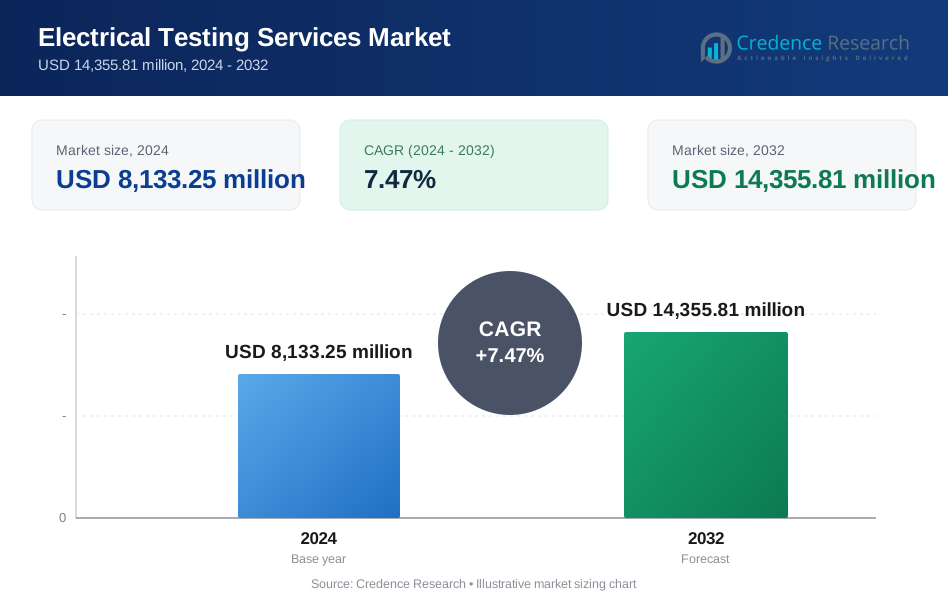
The Electrical Testing Services Market size was valued at USD 6,500.00 million in 2018, reached USD 8,133.25 million in 2024, and is anticipated to reach USD 14,355.81 million by 2032, at a CAGR of 7.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electrical Testing Services Market Size 2024 | USD 8,133.25 million |
| Electrical Testing Services Market, CAGR | 7.47% |
| Electrical Testing Services Market Size 2032 | USD 14,355.81 million |
Growing focus on safety compliance, energy efficiency, and equipment reliability drives steady demand for electrical testing services across industries. Utility operators, manufacturers, and data centers rely on periodic diagnostics to prevent equipment failure and unplanned downtime. The market benefits from technological advancements in digital testing tools, smart grid modernization, and renewable energy integration. Service providers expand offerings through predictive maintenance and automated condition monitoring to enhance performance accuracy. Rising investment in infrastructure development and aging electrical networks further increases service adoption.
Asia Pacific dominates the global market supported by rapid industrialization, smart city expansion, and high energy consumption. North America follows with robust demand from established utilities and data center networks requiring advanced testing and maintenance programs. Europe shows consistent growth led by modernization of grid infrastructure and renewable integration projects. Emerging markets in Latin America, the Middle East, and Africa gain traction with ongoing electrification, industrial projects, and regulatory emphasis on safety and operational reliability.
Market Insights:
- The Electrical Testing Services Market was valued at USD 6,500.00 million in 2018, reached USD 8,133.25 million in 2024, and is projected to reach USD 14,355.81 million by 2032, registering a CAGR of 7.47% during the forecast period.
- Asia Pacific holds the largest regional share at 33%, driven by rapid industrialization, manufacturing expansion, and large-scale energy infrastructure development in China and India.
- North America accounts for 25.6% share, supported by strong regulations, grid modernization projects, and widespread digital testing adoption in the U.S. and Canada.
- Europe captures 20% share, benefiting from renewable integration and modernization of aging power grids across Germany, the UK, and France.
- Among applications, power generation contributes around 30% of total revenue, followed by transmission and distribution utilities at nearly 25%, highlighting the dominance of core energy infrastructure in service demand.
Market Drivers
Growing Emphasis on Electrical Safety and Preventive Maintenance
The Electrical Testing Services Market grows steadily due to stricter safety standards across industries. Power utilities and manufacturers rely on regular inspections to prevent downtime and equipment failure. Governments enforce compliance with electrical safety codes, boosting demand for periodic testing. Industrial facilities schedule proactive maintenance to avoid operational losses. It gains traction from risk management programs promoting early fault detection. The integration of IoT-based diagnostic tools enhances accuracy in predictive maintenance. Service providers offer faster testing cycles with digital monitoring tools. Strong focus on workplace safety further drives service adoption.
Rising Industrial Automation and Smart Infrastructure Expansion
Automation and digital infrastructure development strengthen the need for efficient testing services. Large-scale industrial facilities deploy automated systems requiring precise electrical calibration. Smart grids and renewable power systems rely on condition-based testing for uninterrupted performance. The Electrical Testing Services Market benefits from widespread use of robotics and connected machinery. Utility operators perform voltage, insulation, and relay testing to ensure reliable operation. It supports energy optimization through advanced diagnostics. Urban infrastructure expansion creates steady demand for equipment evaluation. Increasing capital investments in smart factories amplify testing service utilization globally.
- For instance, ABB Ability™ Smart Sensor attaches to motors and pumps to monitor vibration and temperature in real-time, reducing motor downtime by up to 70%.
Stricter Regulatory Compliance and Equipment Reliability Requirements
Compliance with international safety norms pushes industries to adopt advanced testing solutions. Organizations seek certification from accredited service providers to meet ISO and IEC standards. The Electrical Testing Services Market experiences rising engagement from construction and energy firms. Equipment reliability becomes critical as grids face higher power demands. Service providers expand expertise to handle diverse electrical systems. It assists in detecting insulation breakdown, circuit faults, and overload issues early. Regular testing ensures continuity and lowers risk in high-stakes industries. Compliance-oriented testing improves long-term asset performance and operational assurance.
Growing Renewable Energy Integration and Grid Modernization Efforts
Expanding renewable projects drive fresh opportunities for system validation and safety checks. Solar and wind farms depend on accurate relay and transformer testing. The Electrical Testing Services Market supports modernization of legacy grids to handle hybrid energy flows. Utilities verify energy distribution stability through frequent inspection cycles. It underpins sustainable operations by ensuring reliable electrical connections. Service providers introduce mobile testing labs to reach remote renewable sites. Strong renewable energy adoption promotes continuous inspection culture. Grid digitization and decarbonization trends continue to sustain testing demand across energy sectors.
- For instance, Schneider Electric integrates IoT for predictive maintenance in electrical substations, enabling real-time monitoring and early alerts for equipment irregularities.
Market Trends
Adoption of Advanced Diagnostic Tools and Digital Platforms
The Electrical Testing Services Market witnesses a shift toward automated diagnostic technologies. Digital testing platforms use analytics and AI to interpret equipment health faster. Handheld devices with wireless data logging simplify field inspections. It benefits from real-time monitoring solutions connected through cloud interfaces. Portable analyzers support immediate fault detection, improving maintenance efficiency. Predictive algorithms help forecast component failures with greater precision. The demand for remote assessment tools grows as industries optimize workforce allocation. Integration of data-driven testing workflows defines the new operational standard for service providers.
Growing Popularity of Outsourced and Third-Party Testing Services
Organizations prefer outsourcing to reduce costs and gain specialized expertise. Third-party firms offer certified testing with advanced instruments and skilled technicians. The Electrical Testing Services Market sees an increase in long-term maintenance contracts. It helps industries maintain compliance without large internal testing teams. Outsourced partners deliver independent evaluations for regulatory audits. Companies benefit from tailored service packages and scheduled inspections. Many sectors, including oil, gas, and power, rely on independent verification to ensure safety. This outsourcing trend drives steady expansion across both developed and emerging markets.
- For instance, Intertek provides accredited electrical testing and certification services through its global laboratory network, using advanced automated systems to ensure product safety and compliance with international standards.
Integration of IoT, AI, and Smart Monitoring Systems in Testing Processes
IoT-enabled sensors and AI software reshape the accuracy of field diagnostics. The Electrical Testing Services Market incorporates smart systems to track asset performance in real time. Service providers develop connected platforms for continuous voltage and current analysis. AI-based testing automates fault detection with minimal human intervention. It promotes cost savings and faster report generation for clients. Continuous monitoring improves visibility into network health and asset life cycles. Utility operators implement smart testing to enhance grid resilience. Advanced connectivity becomes central to service modernization strategies globally.
Increasing Focus on Sustainable Practices and Energy Efficiency Audits
Sustainability goals redefine how testing firms design their service frameworks. The Electrical Testing Services Market aligns with green energy standards and eco-audit protocols. Companies emphasize equipment that minimizes energy waste during inspection. It encourages energy audits to improve efficiency in transmission systems. Renewable energy plants adopt periodic eco-focused performance testing. Sustainable testing reduces environmental risks linked to electrical failures. Firms adopt recyclable materials in field instruments and accessories. Growing environmental awareness reinforces the sector’s commitment to low-impact operational practices.
- For instance, Schneider Electric’s EcoStruxure platform enables real-time energy monitoring and performance analytics, helping industrial and commercial facilities identify measurable energy savings and improve operational efficiency.
Market Challenges Analysis
Shortage of Skilled Technicians and Complex Testing Standards
High skill requirements create labor gaps across service regions. The Electrical Testing Services Market faces limited access to certified professionals trained in high-voltage systems. It complicates project timelines, especially for large industrial sites. Complex testing standards require in-depth technical knowledge to interpret results accurately. Frequent updates in codes and regulations increase training demands. Many small service firms struggle to maintain accreditation or update tools. Industry-wide certification gaps restrict scalability of testing operations. Maintaining workforce competency remains a continuous challenge for both regional and global players.
High Cost of Equipment, Calibration, and Service Deployment
Testing requires sophisticated analyzers and calibration tools with heavy investment costs. The Electrical Testing Services Market experiences budget constraints, especially among mid-sized service providers. It raises barriers to expansion and delays adoption of advanced devices. Calibration and upkeep of high-precision tools add recurring expenses. Field testing in remote industrial zones further elevates logistical costs. Smaller firms face difficulty competing with global service networks. Clients often seek cost-effective alternatives, limiting premium service uptake. Price sensitivity among end-users pressures providers to balance affordability with accuracy.
Market Opportunities
Rising Expansion of Renewable Energy and Industrial Infrastructure Projects
The global shift toward renewables boosts the need for continuous system verification. The Electrical Testing Services Market benefits from energy transitions in solar, wind, and hybrid installations. It supports testing of transformers, circuit breakers, and switchgear used in green energy setups. New industrial parks and smart cities create steady service pipelines. Governments promote grid reliability through mandatory inspections. Service providers introducing mobile units reach new construction zones efficiently. Expansion of industrial infrastructure widens scope for preventive testing programs worldwide.
Emergence of Predictive Maintenance and Remote Diagnostic Solutions
Predictive testing solutions offer significant opportunities for service differentiation. The Electrical Testing Services Market integrates AI-driven predictive platforms for early fault detection. It empowers users to track voltage trends and insulation performance remotely. Cloud-based analytics platforms enhance operational continuity across utilities and plants. Firms investing in remote testing gain long-term service contracts from energy operators. Predictive insights strengthen safety assurance while minimizing equipment downtime. Growing interest in automation and digital integration opens broad growth avenues for market participants.
Market Segmentation Analysis:
By Service Type
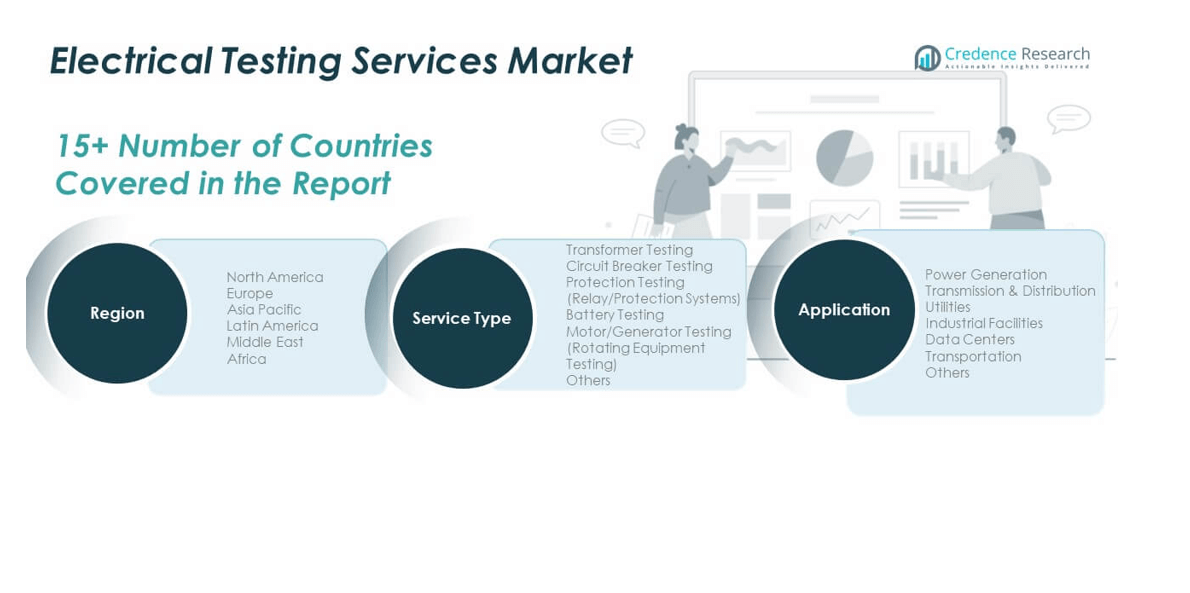
The Electrical Testing Services Market covers a broad range of testing categories that ensure safe and efficient electrical operations. Transformer testing holds the dominant position due to its critical role in monitoring voltage performance and detecting insulation faults in power networks. Circuit breaker testing follows with high demand from utilities and industrial plants where reliability and fault clearance are vital. Protection testing for relay and control systems expands rapidly with automation in grid management. Battery testing gains traction in data centers, renewable installations, and telecom infrastructure for maintaining backup efficiency. Motor and generator testing supports predictive maintenance for rotating equipment in manufacturing and energy sectors. Other specialized services, including insulation resistance, switchgear calibration, and grounding checks, enhance overall asset reliability and reduce operational risks. It continues to grow as industries prioritize proactive maintenance and equipment validation.
- For instance, Siemens’ 3WA circuit breakers feature digital testing interfaces that verify performance through over 10,000 switching cycles under IEC compliance.
By Application
By application, power generation remains the leading segment driven by ongoing maintenance needs in thermal, hydro, and renewable facilities. Transmission and distribution utilities rely heavily on electrical testing to maintain grid stability, reduce outage risks, and comply with regulatory standards. Industrial facilities invest in predictive diagnostics to ensure production continuity and equipment safety. Data centers form a high-growth application with strict uptime requirements and rising digital workloads. The transportation sector witnesses steady expansion with electrification in railways, airports, and urban transit systems. Other applications such as healthcare, construction, and commercial complexes show growing adoption for reliable energy delivery and compliance with safety norms. The market demonstrates balanced growth across these segments as global infrastructure modernization intensifies demand for consistent electrical reliability.
- For instance, Hitachi Energy’s testing and diagnostic systems use real-time monitoring and analytics to assess the condition of grid relays and transformers across multiple countries, supporting reliability and operational efficiency in global power networks.
Segmentation:
By Service Type
- Transformer Testing
- Circuit Breaker Testing
- Protection Testing (Relay/Protection Systems)
- Battery Testing
- Motor/Generator Testing (Rotating Equipment Testing)
- Others
By Application
- Power Generation
- Transmission & Distribution Utilities
- Industrial Facilities
- Data Centers
- Transportation
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Electrical Testing Services Market size was valued at USD 1,716.00 million in 2018, reached USD 2,111.34 million in 2024, and is anticipated to reach USD 3,719.62 million by 2032, at a CAGR of 7.5% during the forecast period. North America holds around 25.6% of the global market share. Strong regulatory enforcement on electrical safety drives continuous service adoption across industrial and utility sectors. The U.S. leads with high demand from power generation and data center infrastructure. It benefits from frequent upgrades in grid networks and the growing renewable energy sector. Canada supports steady service growth through large-scale transmission modernization projects. Advanced diagnostic tools and automated testing solutions are widely implemented. The region also hosts major global service providers, ensuring high-quality standards and technical expertise across electrical systems.
Europe
The Europe Electrical Testing Services Market size was valued at USD 1,384.50 million in 2018, increased to USD 1,649.20 million in 2024, and is projected to reach USD 2,709.70 million by 2032, at a CAGR of 6.5% during the forecast period. Europe captures about 20% of the global share. The region’s aging grid infrastructure and focus on decarbonization initiatives boost service requirements. Germany, the UK, and France lead due to modernization of renewable integration systems. It experiences rising use of digital tools in transformer and protection testing. Regulatory frameworks such as EU safety standards strengthen testing frequency in industrial facilities. Smart grid expansion and energy-efficient retrofits contribute to rising service contracts. The emphasis on sustainability promotes routine audits and electrical integrity verification across multiple industries.
Asia Pacific
The Asia Pacific Electrical Testing Services Market size was valued at USD 2,678.00 million in 2018, reached USD 3,439.11 million in 2024, and is expected to reach USD 6,450.08 million by 2032, at a CAGR of 8.3% during the forecast period. Asia Pacific dominates with around 33% of the global market share. Rapid industrialization, expanding manufacturing bases, and growing renewable installations drive strong demand. China, India, and Japan lead with large-scale grid modernization and industrial facility upgrades. It benefits from the expansion of high-voltage networks and smart energy systems. Data center proliferation in major cities raises testing service needs for backup systems. Government-led electrification programs enhance power reliability across rural zones. The region continues to show the fastest growth due to rising infrastructure investments and high energy consumption patterns.
Latin America
The Latin America Electrical Testing Services Market size was valued at USD 377.00 million in 2018, increased to USD 466.77 million in 2024, and is anticipated to reach USD 758.99 million by 2032, at a CAGR of 6.4% during the forecast period. Latin America holds about 8% of the global share. Brazil and Mexico dominate regional demand with significant investments in energy and industrial modernization. The Electrical Testing Services Market benefits from infrastructure projects requiring continuous equipment validation. It supports ongoing expansions in hydro and renewable power generation. Industrial growth in mining and manufacturing strengthens the requirement for transformer and motor testing. Service providers are focusing on reliability improvement to address aging electrical systems. Energy diversification initiatives continue to generate fresh service opportunities across emerging economies in the region.
Middle East
The Middle East Electrical Testing Services Market size was valued at USD 187.85 million in 2018, grew to USD 215.48 million in 2024, and is projected to reach USD 330.26 million by 2032, at a CAGR of 5.6% during the forecast period. The region represents about 6% of the global share. High power consumption across oil, gas, and infrastructure sectors drives consistent service demand. Saudi Arabia and the UAE remain leading markets due to large-scale utility investments. It benefits from advanced testing adoption for substations and grid management. Renewable energy integration projects under national diversification plans also support steady growth. Service companies are expanding regional testing hubs to manage complex high-voltage systems. The move toward energy-efficient operations encourages continuous inspection of critical electrical assets.
Africa
The Africa Electrical Testing Services Market size was valued at USD 156.65 million in 2018, increased to USD 251.35 million in 2024, and is projected to reach USD 387.17 million by 2032, at a CAGR of 5.3% during the forecast period. Africa accounts for around 7% of the global market share. South Africa leads regional activity with strong industrial and energy infrastructure development. Emerging economies like Egypt and Nigeria invest in power generation and grid reliability upgrades. It witnesses growing public and private participation in electrical maintenance programs. Service demand expands through ongoing rural electrification projects. The market benefits from utility reforms and rising interest in renewable power integration. Training programs for technical personnel enhance service quality across national utilities. The region continues to progress steadily toward stronger electrical safety and performance assurance.
Key Player Analysis:
- Intertek Group plc
- SGS SA
- Bureau Veritas
- TÜV SÜD
- DEKRA SE
- Schneider Electric SE
- Siemens AG
- Eaton Corporation plc
- ABB Ltd.
- General Electric (GE)
- Voltech Group
- Inser Hitech Engineers
- Rulka Electricals Pvt. Ltd.
- MISTRAS Group, Inc.
- Element Materials Technology
- ALS Limited
Competitive Analysis:
The Electrical Testing Services Market features strong competition among global and regional service providers offering advanced testing and certification solutions. Major players such as Intertek Group, SGS SA, Bureau Veritas, TÜV SÜD, DEKRA, and ABB lead with diversified portfolios and global service networks. It focuses on expanding capabilities in digital diagnostics, predictive maintenance, and automation-based testing. Companies invest in partnerships and acquisitions to strengthen market presence and technical depth. Regional players including Voltech Group, Rulka Electricals, and Inser Hitech Engineers enhance competitiveness through specialized local expertise. Service differentiation through faster reporting, certified compliance, and on-site support remains a key strategy. Leading firms emphasize sustainability, innovation, and remote monitoring tools to improve reliability and operational uptime. Continuous investment in advanced instruments and skilled personnel sustains long-term growth and client trust within the global electrical testing ecosystem.
Recent Developments:
- In March 2025, in Shermco Industries, the company acquired Power Products and Solutions, a NETA-accredited electrical testing and maintenance provider based in Charlotte, NC, to double its service capacity in the region and enhance capabilities in electrical testing, engineering, and breaker reconditioning.
Report Coverage:
The research report offers an in-depth analysis based on Service Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Electrical Testing Services Market will grow steadily with rising demand for preventive maintenance across utilities and industries.
- Integration of digital tools and IoT-based monitoring will transform on-site inspection efficiency and reporting accuracy.
- Renewable energy expansion will increase the need for transformer, relay, and battery testing across solar and wind farms.
- Smart grid deployment will boost specialized service demand for automation and protection system validation.
- Data center growth will sustain high requirements for backup system and circuit reliability testing.
- Industrial automation will drive predictive and condition-based testing adoption across manufacturing plants.
- Increasing regulatory pressure will strengthen certified testing standards and quality compliance frameworks.
- Service providers will expand regional presence through mergers and acquisitions to meet global client demands.
- The shortage of skilled technicians will encourage training investments and workforce development initiatives.
- Growing focus on sustainability and energy efficiency will define next-generation testing strategies worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Emphasis on Electrical Safety and Preventive Maintenance
Stricter safety standards and regulatory compliance requirements across industries are driving the need for regular electrical testing to prevent equipment failure and unplanned downtime, especially in utilities and manufacturing sectors.
Rising Industrial Automation and Smart Infrastructure Expansion
The proliferation of automated systems, smart grids, and digital infrastructure increases the demand for precise and efficient electrical testing services to ensure reliable operation and minimize disruptions in industrial and urban environments.
Stricter Regulatory Compliance and Equipment Reliability Requirements
Organizations are compelled to adopt advanced testing solutions to meet international safety norms (ISO, IEC), with regular inspections and certifications becoming essential for operational assurance and risk mitigation.
Growing Renewable Energy Integration and Grid Modernization
The expansion of solar, wind, and hybrid energy projects, along with modernization of legacy grids, creates new opportunities for system validation, transformer, and relay testing to ensure stable and safe energy distribution.
Adoption of Advanced Diagnostic Tools and Digital Platforms
Technological advancements such as IoT-enabled sensors, AI-driven diagnostics, and cloud-based monitoring are transforming testing processes, enabling predictive maintenance and real-time fault detection, which enhances service efficiency and accuracy.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Electrical Testing Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electrical Testing Services Market projected to grow between 2024 and 2032?
What is the expected CAGR for the market from 2024 to 2032?
What are the key drivers of market growth?
Why is Asia-Pacific expected to exhibit the highest growth rate?
What are the main challenges facing the market?
Who are the leading companies in the Electrical Testing Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Power Generation
- 1.2.2 Transmission & Distribution Utilities
- 1.2.3 Industrial Facilities
- 1.2.4 Data Centers
- 1.2.5 Transportation
- 1.2.6 Others
- 1.3 By Service Type
- 1.3.1 Transformer Testing
- 1.3.2 Circuit Breaker Testing
- 1.3.3 Protection Testing (Relay/Protection Systems)
- 1.3.4 Battery Testing
- 1.3.5 Motor/Generator Testing (Rotating Equipment Testing)
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,133.25 million → 2032: USD 14,355.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electrical Testing Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electrical Testing Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Electrical Testing Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Electrical Testing Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electrical Testing Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electrical Testing Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electrical Testing Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electrical Testing Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,133.25 million → 2032: USD 14,355.81 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electrical Testing Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Power Generation
- 12.3.6.2 Transmission & Distribution Utilities
- 12.3.6.3 Industrial Facilities
- 12.3.6.4 Data Centers
- 12.3.6.5 Transportation
- 12.3.6.6 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Transformer Testing
- 12.4.6.2 Circuit Breaker Testing
- 12.4.6.3 Protection Testing (Relay/Protection Systems)
- 12.4.6.4 Battery Testing
- 12.4.6.5 Motor/Generator Testing (Rotating Equipment Testing)
- 12.4.6.6 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electrical Testing Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electrical Testing Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electrical Testing Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electrical Testing Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intertek Group plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 SGS SA
- 18.4 Bureau Veritas
- 18.5 TÜV SÜD
- 18.6 DEKRA SE
- 18.7 Schneider Electric SE
- 18.8 Siemens AG
- 18.9 ABB Ltd.
- 18.10 Eaton Corporation plc
- 18.11 General Electric (GE)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

