
Media ledger spending shifts from NFT hype to provenance
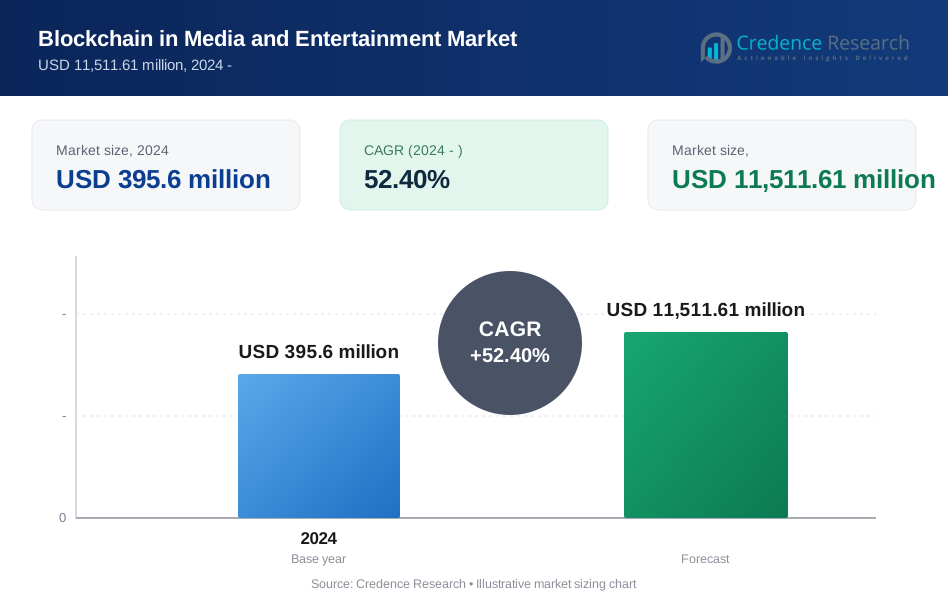
The blockchain in media and entertainment market was valued at USD 748.0 million in 2025 and is projected to increase from USD 868.5 million in 2026 to USD 3.33 billion by 2035, registering a CAGR of 16.11% during 2025–2035. Demand now rests on signed news content, fan networks owned by media groups, on-chain game items that keep the wallet out of sight, and rights records that show who made a work after the U.S. Copyright Office tied protection to human authorship. North America held the largest regional share, 35.2% in 2025, as U.S. studios, sports leagues and news groups run the biggest live programs. The main commercial change is the move away from speculative NFT drops toward provenance and licensing. Content provenance and authentication is the fastest-growing application at 25.50% a year, as publishers anchor signed content and machine-readable license terms on-chain.
What counts as media ledger spend, and what is left out?
Spending is counted where the buyer or platform operator sits. In scope are chain infrastructure, wallets and marketplace primary-sale and service fees for game items and licensed collectibles; token-based tickets, loyalty passes, fan tokens and membership programs; decentralized video, storage and ad-verification tools sold to media firms; rights registries and split-payment systems; and ledger-anchored signing and licensing protocols for news and media assets.
Secondary NFT trading volume, the market value of collectibles or tokens, price gains on fan and game tokens and crypto exchange fees are excluded, as are provenance tools that sign content without an on-chain anchor. Those exclusions explain why boom-era estimates for the field were far larger.
Blockchain in Media and Entertainment Market Insights
- The blockchain in media and entertainment market is projected to rise from USD 868.5 million in 2026 to USD 3.33 billion by 2035, a 16.11% CAGR, led by provenance and licensing uses.
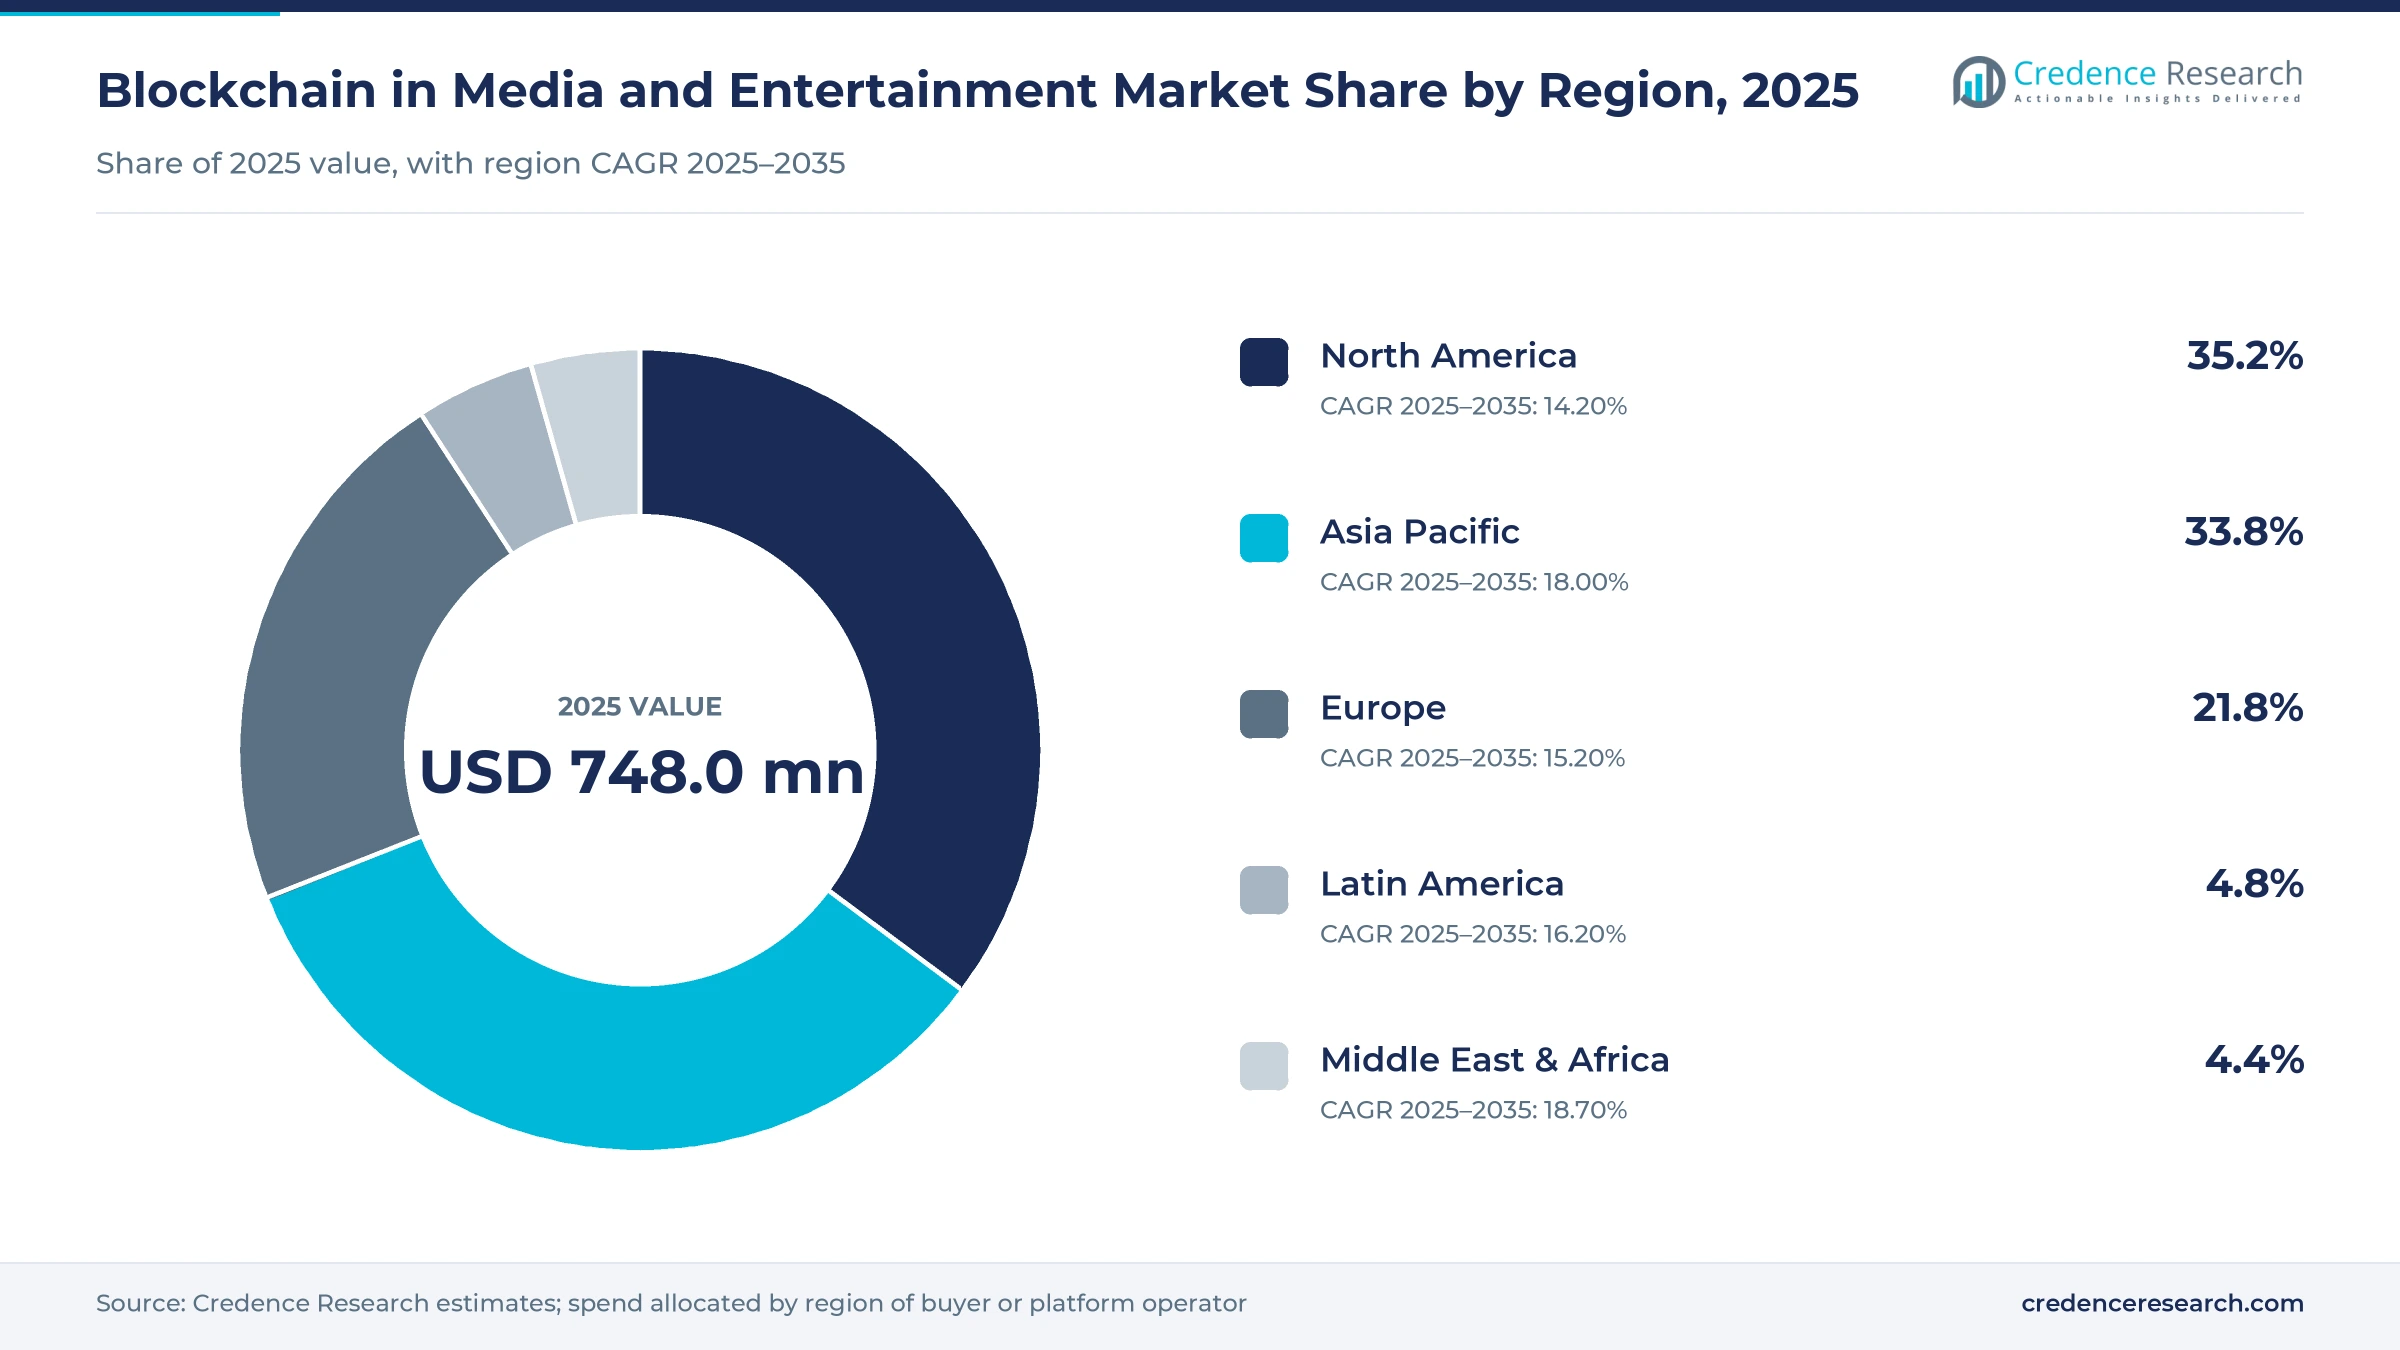
- North America held 35.2% of 2025 value, the largest regional share, because U.S. studios, sports leagues and news groups such as Fox run the biggest ledger programs.
- Digital collectibles and gaming assets accounted for 42.5% of 2025 value, the largest application, as licensed sports collectibles and game items remain the main live uses.
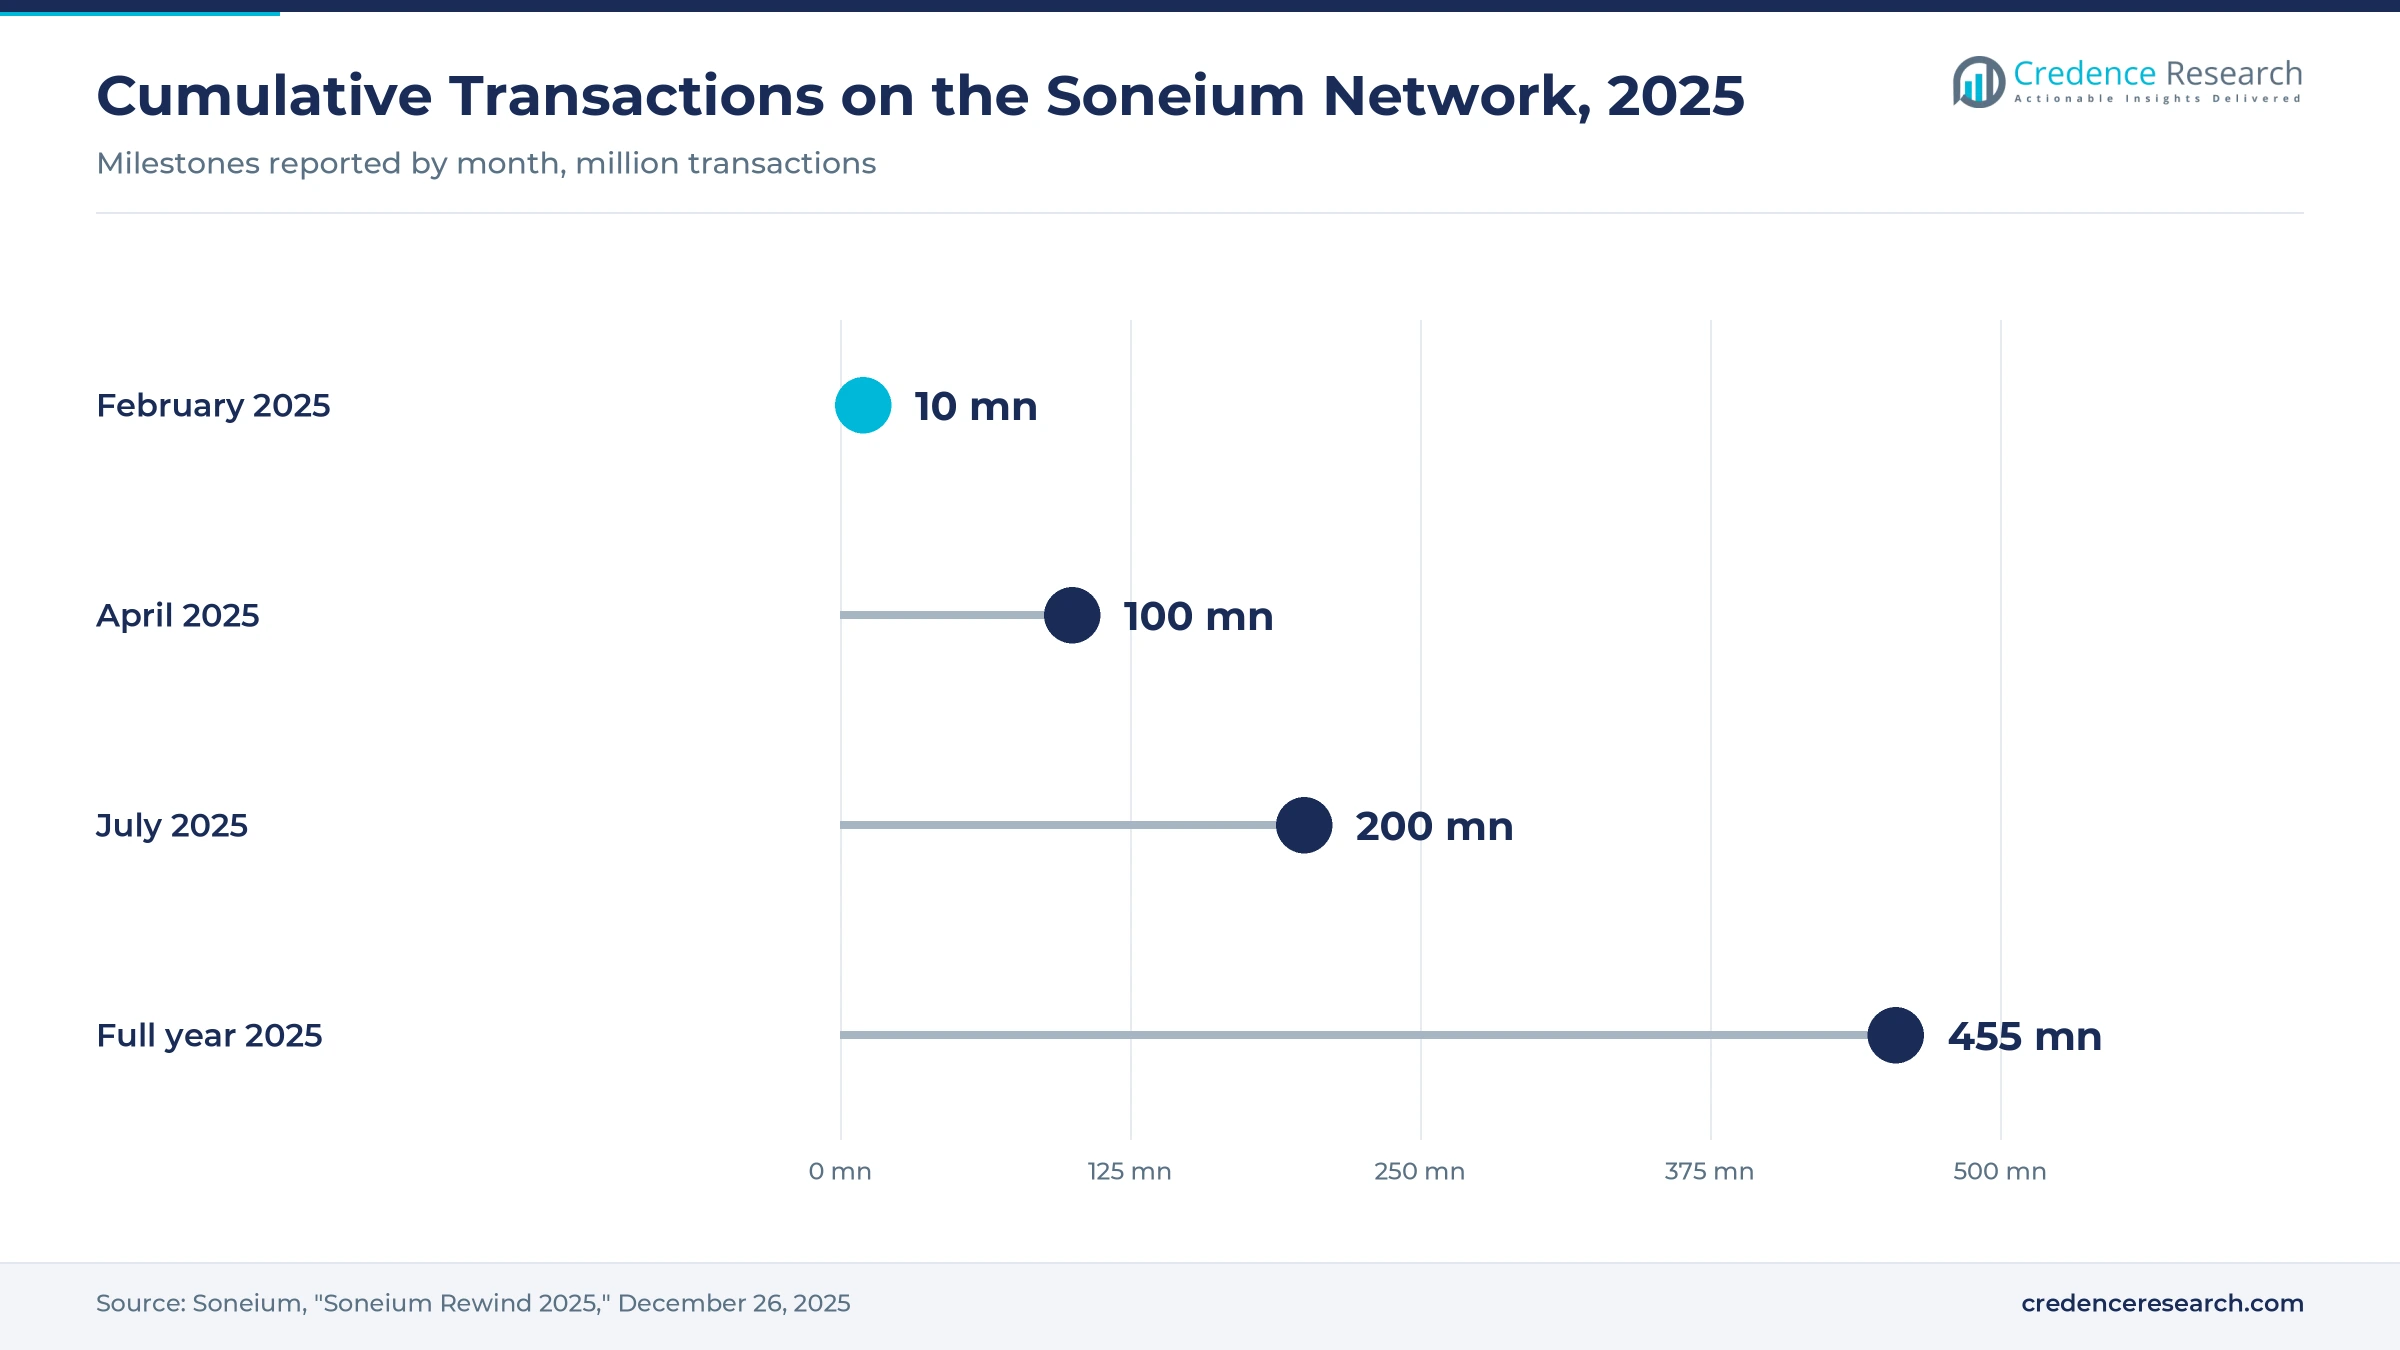
- Media groups now build their own chains. Sony's Soneium network, launched on mainnet in January 2025, processed 455 million transactions and counted 5.3 million active wallets that year.
- Capital is concentrating. Credence Research estimates the 10 largest suppliers hold just over half of 2025 value, and Animoca Brands suspended merger discussions with Currenc Group in September 2026.
Public chains and game assets lead while provenance grows
Public networks lead the type mix while consortium ledgers grow fastest
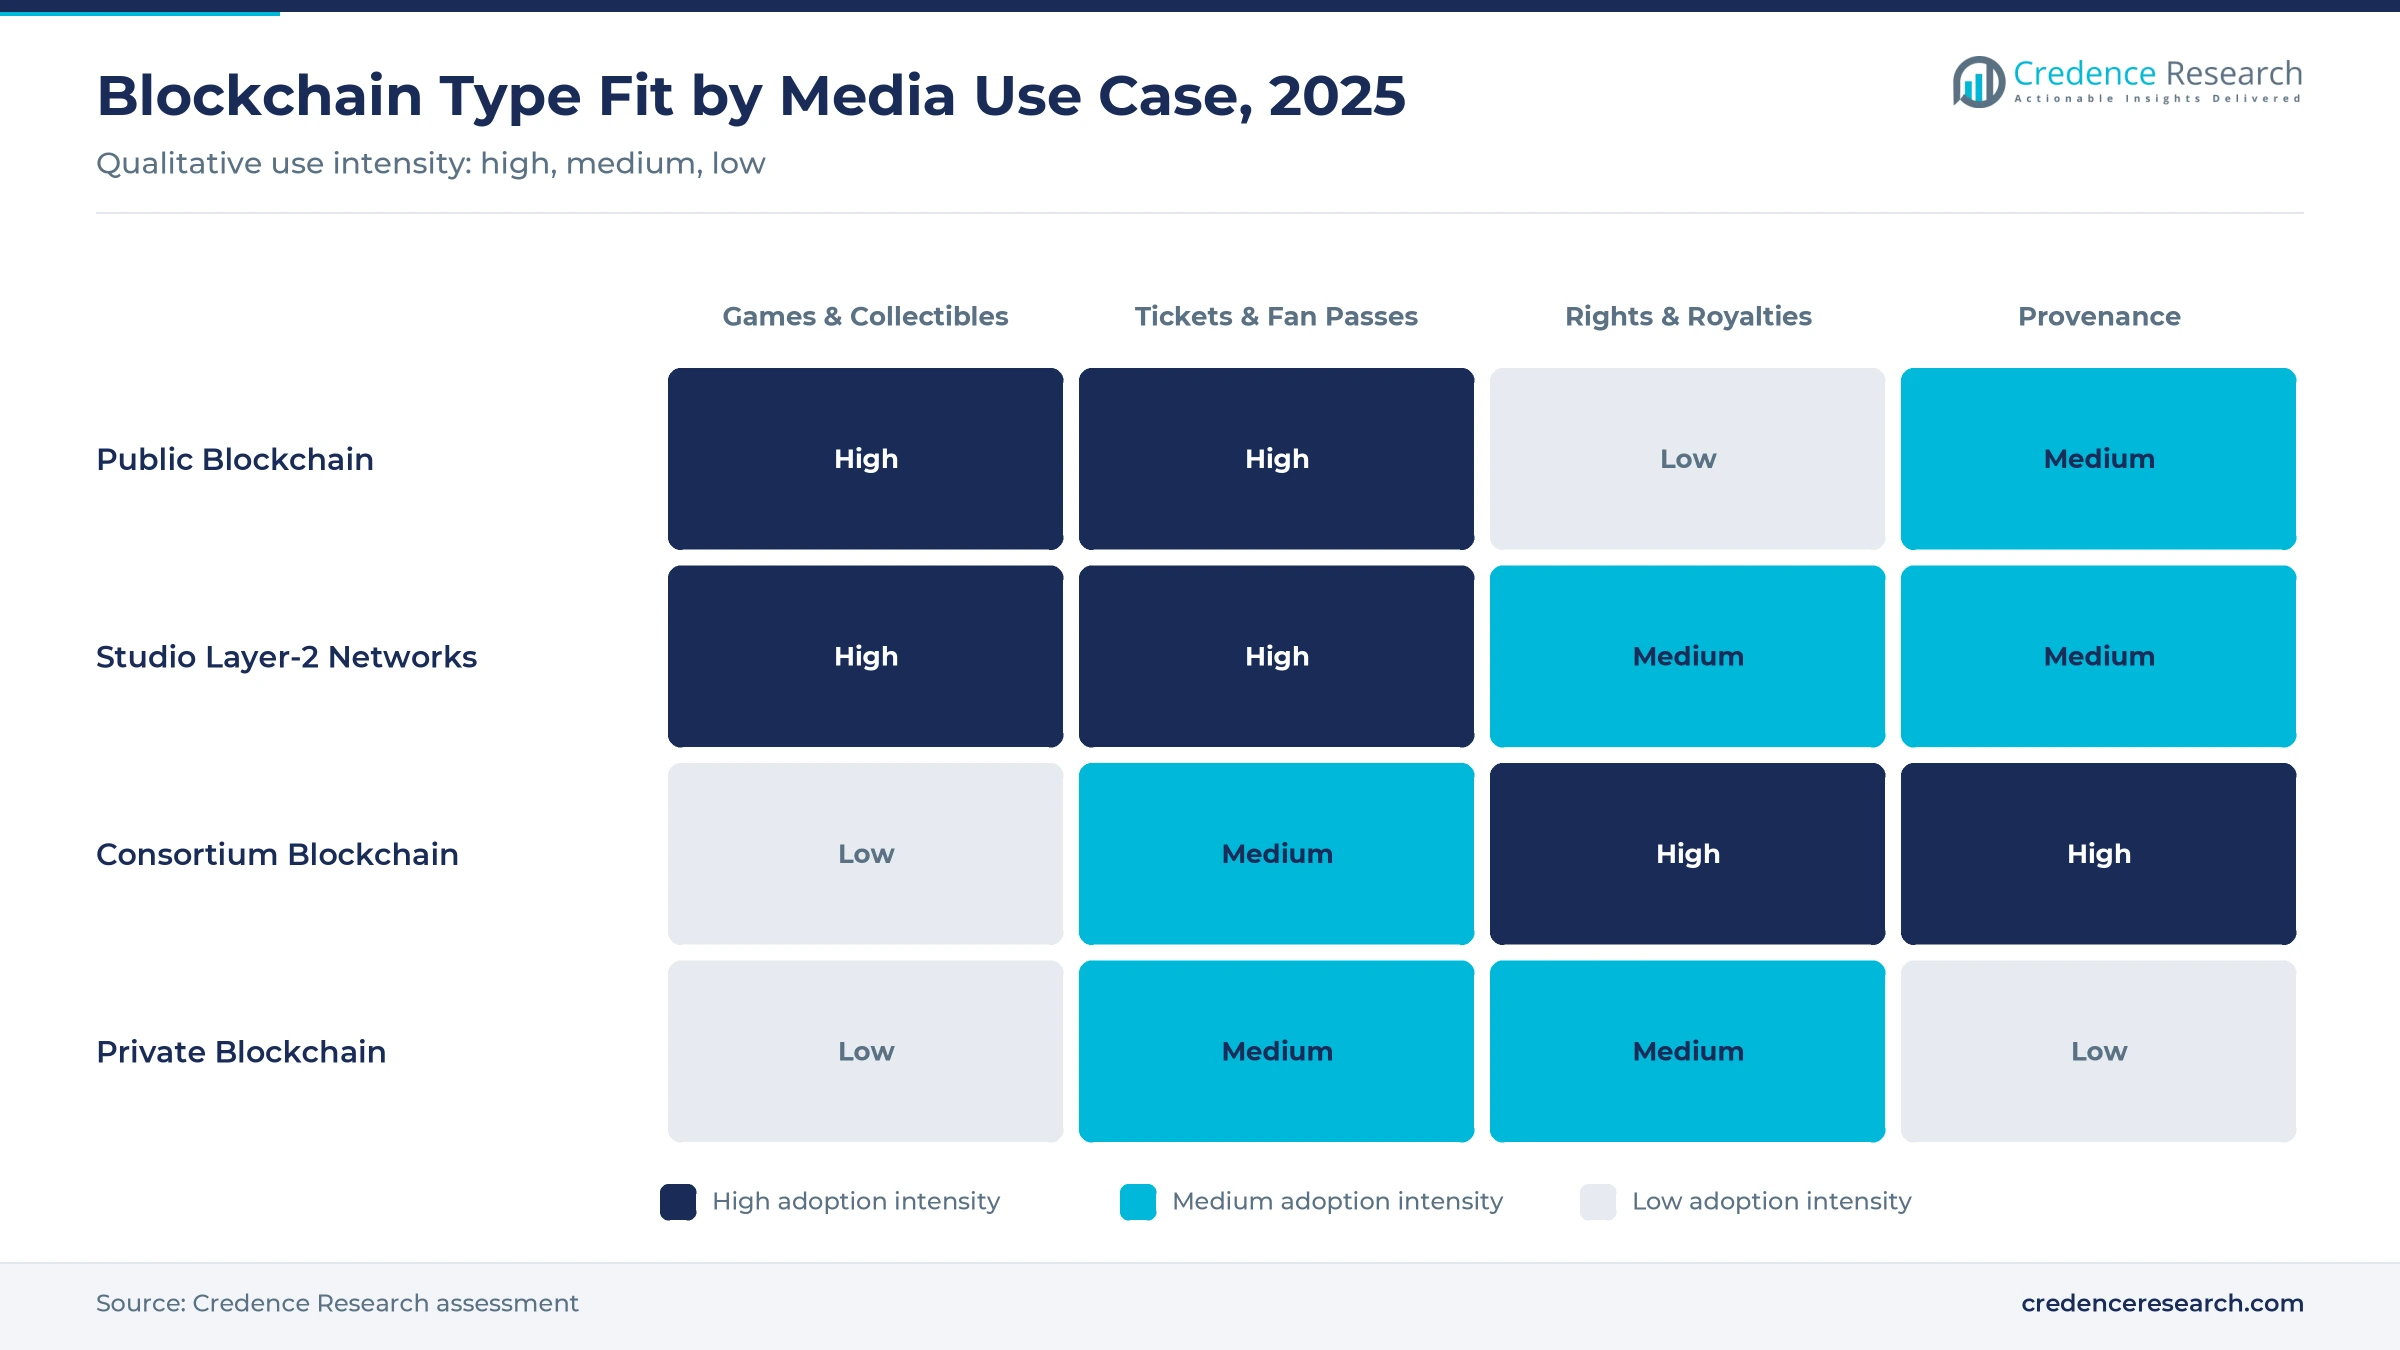
Based on type, the market is categorized into public blockchain, private blockchain and consortium blockchain. Public blockchain led with 53.8% of 2025 value, because game items, collectibles and fan passes must move between wallets and marketplaces, so most run on public networks and their layer-2s, such as Soneium, Immutable's chains and Polygon. Consortium blockchain grows fastest at 19.47% a year, as rights registries and provenance networks need shared governance among rival studios, labels and publishers.
Collectibles and game items lead by application while provenance grows fastest
Based on application, the market is categorized into digital collectibles and gaming assets, ticketing and fan engagement, content distribution and advertising, royalty payments and rights management, and content provenance and authentication. Digital collectibles and gaming assets led with 42.5% of 2025 value, since licensed sports collectibles and game items remain the largest live use after the crash. Content provenance and authentication grows fastest at 25.50% a year, as news and media owners anchor signed content and license terms on-chain.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Type | Public Blockchain | 53.8% | Consortium Blockchain | 19.47% |
| By Application | Digital Collectibles & Gaming Assets | 42.5% | Content Provenance & Authentication | 25.50% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
AI provenance and authorship rules drive media ledgers
Deepfakes and AI scraping push newsrooms to sign and license content on-chain
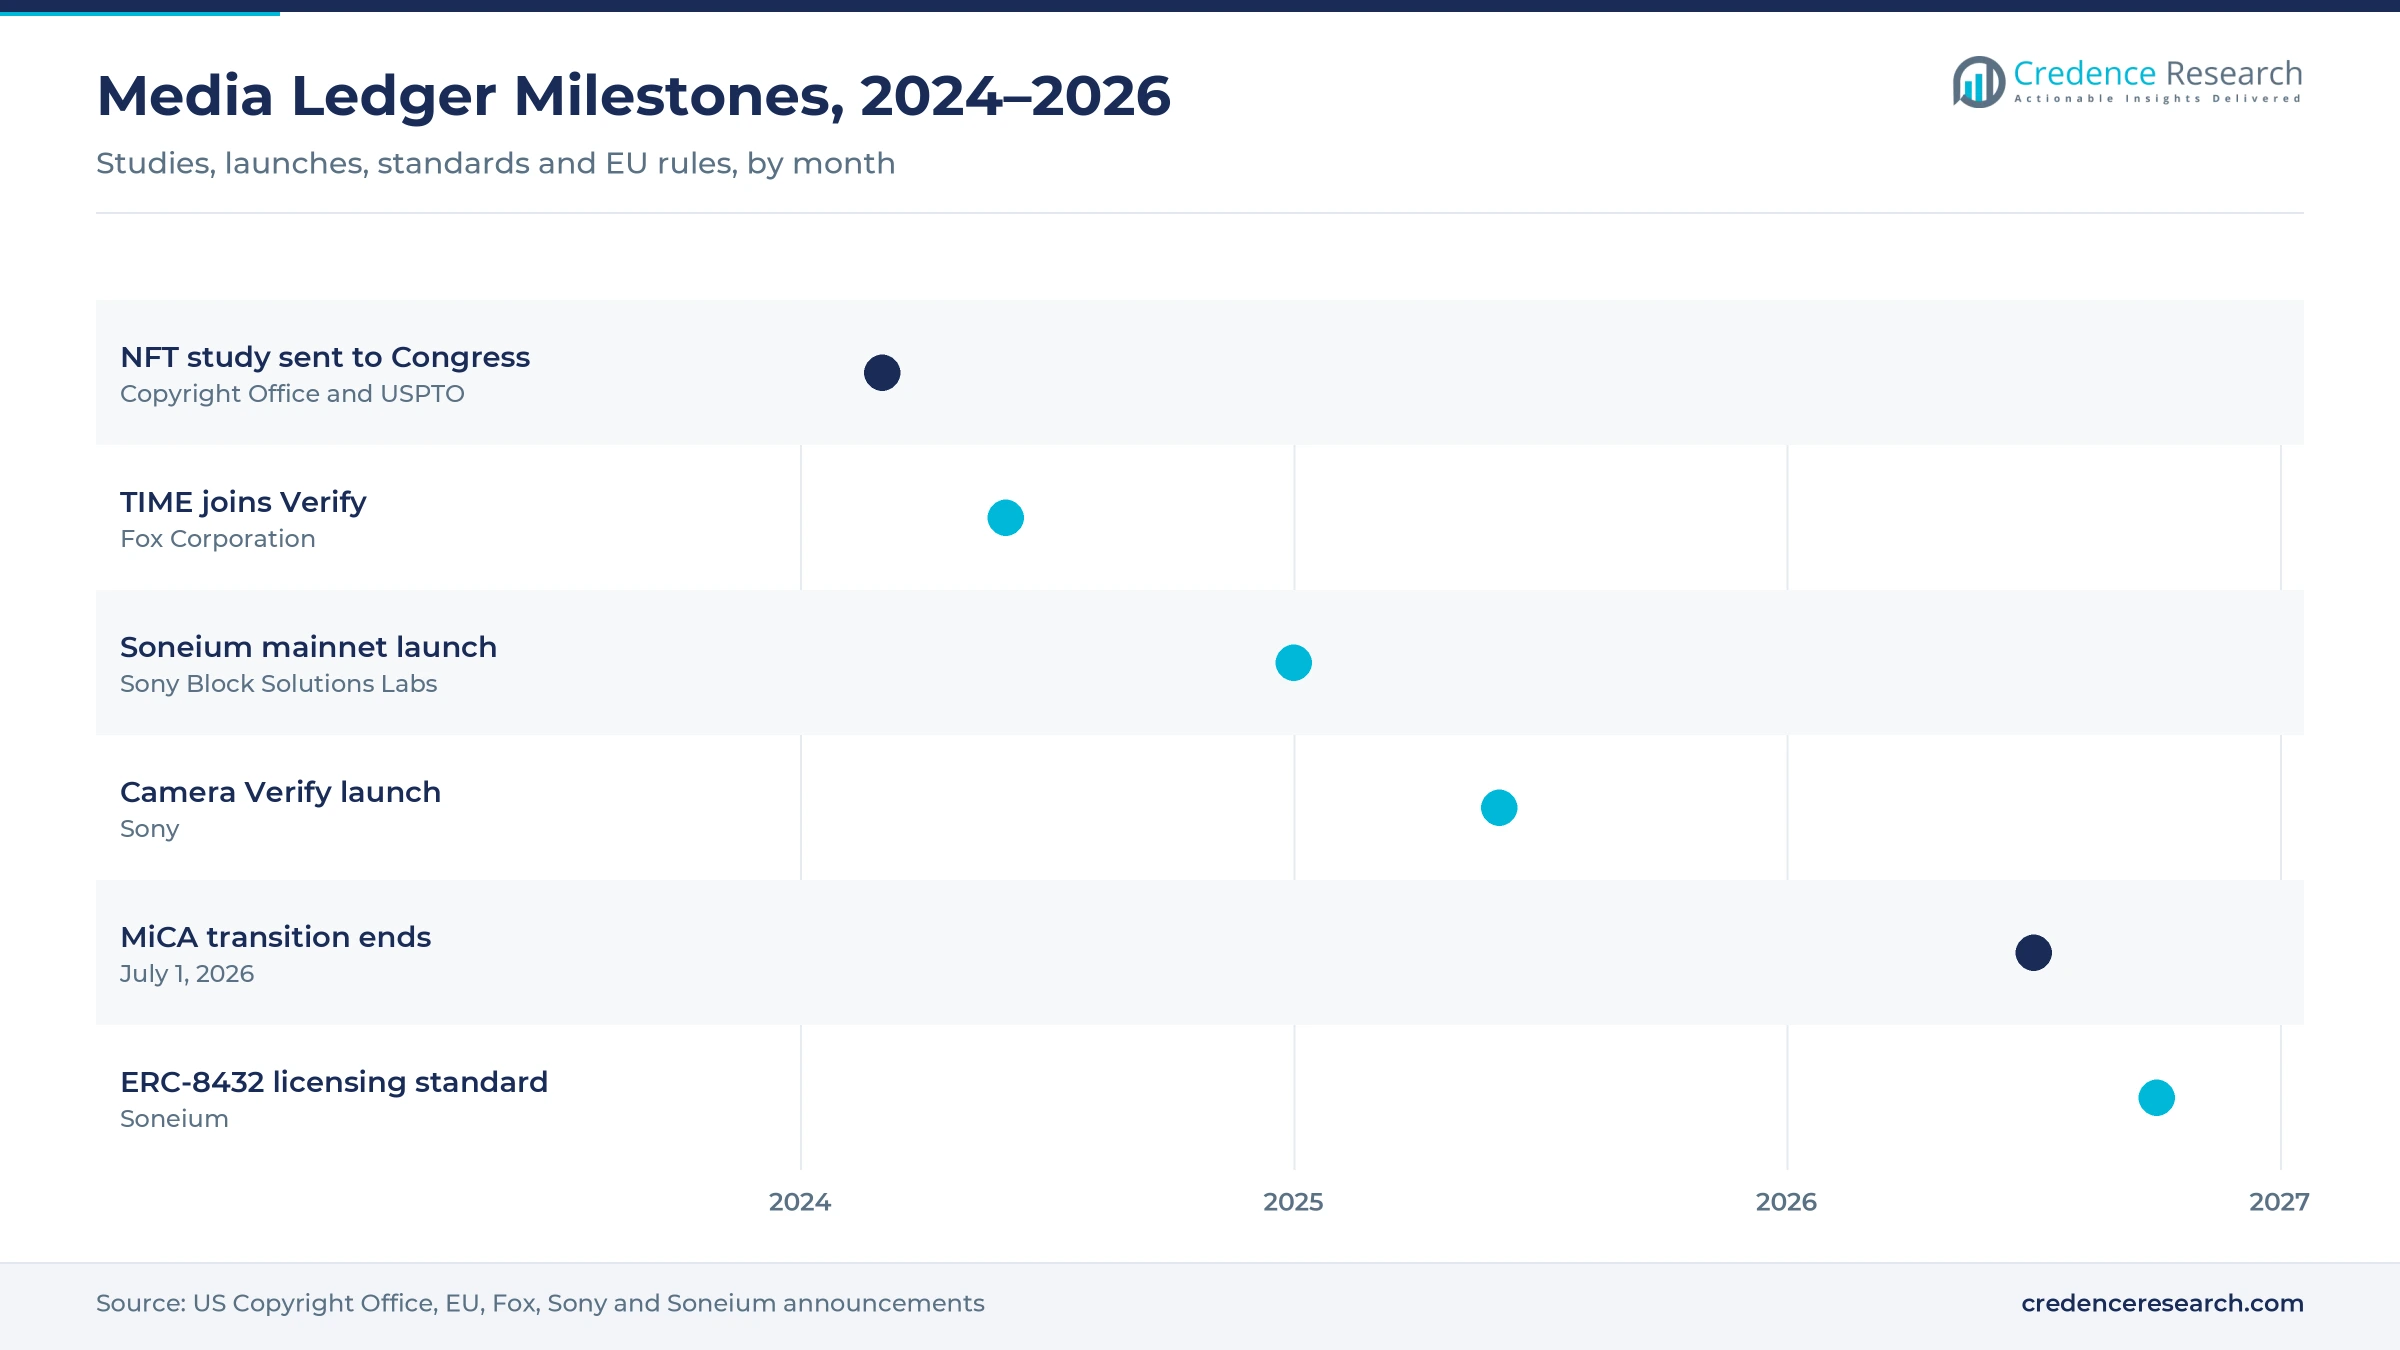
Generative AI makes it harder for publishers to prove what they released and to control who reuses it. In response, Fox Corporation released its Verify protocol on the public Polygon proof-of-stake network in January 2024, and in June 2024 it named TIME as the first outside publisher, according to Fox Corporation's investor announcement, with smart contracts setting the terms on which AI platforms access articles. News groups in the U.S. and Europe are the first buyers, which makes provenance the fastest-growing application through 2035.
Human-authorship rules make studios and labels record who made what
The U.S. Copyright Office released Part 2 of its AI copyright report on Jan. 29, 2025, concluding that AI outputs are protected only where a human contributes enough expressive material, so studios and labels must now document contributors and dates. The joint Copyright Office and USPTO NFT study, sent to Congress on March 12, 2024, had already found that NFT buyers often do not know which rights they acquire. Registries binding a token to a license, contributors and a payment split close that gap in digital rights management.
Sony's Soneium shows media groups paying for owned fan channels
Owning the fan relationship is worth more to a studio than selling a collectible once. Sony Block Solutions Labs took Soneium, an Ethereum layer-2 network, to mainnet in January 2025, and Sony Group's fan marketing platform launched on it that month. The network processed 455 million transactions, counted 5.3 million active wallets and hosted more than 250 live apps in 2025, according to Soneium's 2025 review. Ticketing and fan programs in Japan, Korea and the U.S. benefit first, with demand building over the next 3 to five years.
MiCA exempts unique tokens, giving European issuers a clear path
Regulation (EU) 2023/1114, the Markets in Crypto-Assets Regulation, entered into force on June 29, 2023, and its recital 10 excludes crypto-assets that are unique and not fungible, such as digital art and collectibles. Media firms can therefore issue one-off tickets, passes and artworks without a crypto-asset white paper. Recital 11 sets the limit, as fractional parts and large series can point to fungibility and bring a program inside the rules. The clarity favors utility tokens tied to a real service and supports Europe's growth of 15.20% a year.
Signing cameras and wallet-free games reshape ledger use
Cameras shift toward signing images at the moment of capture
Proof of origin increasingly starts inside the camera, and on June 26, 2025, Sony launched Camera Verify, according to Sony's European press center, embedding C2PA digital signatures in images and letting news organizations share verification links with third parties. Sony sits on the C2PA steering committee with Adobe, Amazon, the BBC, Google, Meta, Microsoft, OpenAI, TikTok and Truepic, and the Content Credentials specification has reached version 2.3. Content Credentials do not require a ledger, yet each signed asset adds demand for public registries where signatures and licenses can be checked.
Game publishers keep the wallet in the background
The second wave of blockchain games treats item ownership as a background feature rather than an investment. In April 2025, Immutable announced that Ubisoft had partnered with it on Might & Magic Fates, the 12th entry in the series, using Immutable's infrastructure for digital ownership and player rewards, and players do not need to buy tokens to start. Even after the crash, digital collectibles and gaming assets keep the largest application share, 42.5% in 2025.
AI developers need licenses that machines can read, creating an opportunity
AI developers need content, and publishers want an audit trail and payment. To bridge that gap, Fox's Verify uses smart contracts to set access terms for AI platforms, and on Oct. 6, 2026, Soneium backed ERC-8432, an IP licensing standard designed to be readable by both people and AI agents. Vendors that combine signing, license terms and settlement can therefore sell recurring services to news groups, image libraries and studios. Content provenance and authentication, the fastest-growing application, captures most of this spend, although the standards are still early.
Shared registries for music rights and K-pop IP open an opportunity
Collecting societies, publishers and labels are testing shared registries that several rights holders govern together. In April 2025, JASRAC and Kendrix worked with Soneium on a music-rights on-chain standard, and on Sept. 28, 2026, Soneium partnered with DayOneDream to bring K-pop IP on-chain as tokenized IP. That shared governance makes consortium blockchain the fastest-growing type at 19.47% a year. Royalty splits on music streaming are the natural first use, but adoption depends on rival labels agreeing on governance.
NFT distrust and unenforced royalties limit ledger budgets
The NFT crash left consumers wary and capital thinner
Secondary trading of collectibles fell to a fraction of its 2021 to 2022 peak, many celebrity and brand collections lost most of their value, and several projects closed. As a result, consumers now link the word NFT with loss, and investors are more selective, with Animoca Brands saying on Sept. 22, 2026, that it and Currenc Group had suspended merger discussions. Studios and brands respond by recasting tokens as passes, memberships and in-game items, and Credence Research models collectibles growth below the overall market rate.
Optional marketplace royalties undercut the promise to artists
Several NFT marketplaces made creator royalties optional on resales, which weakened the original promise that artists would earn from every trade. Musicians, illustrators and smaller labels lose expected income, and studios hesitate to build programs around resale royalties they cannot enforce. Royalty systems that work today sit inside licensed platforms and rights-society agreements, not open trading. Vendors reduce the risk by enforcing payment splits at the primary sale, inside closed marketplaces and through contracts with collecting societies.
Large series and fractional tokens can fall inside EU crypto rules
MiCA's exemption covers only unique tokens, so large series and fractional NFTs can be treated as fungible and fall inside the rules. At the same time, the transition period for existing crypto-asset service providers ended on July 1, 2026. Media firms that serve EU fans must design ticket, pass and collectible programs carefully, which raises legal costs and lengthens launches. Issuers mitigate the barrier by keeping editions unique, tying each token to a service such as event access, and working with authorized platforms wherever trading is involved.
Signed files and shared databases often do the job without a ledger
Content Credentials work without a blockchain, and a single label can keep royalty records in its own systems at lower cost. Buyers therefore question whether a ledger adds value, and many provenance and rights projects stop at the pilot stage. The pressure is strongest in content distribution and advertising, where decentralized video networks compete with mature cloud delivery. Suppliers respond by targeting cases where several parties that do not trust each other must share 1 record, such as rights splits across 2 or more labels.
U.S. studios lead as Gulf and Asian media hubs grow faster
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| North America | 35.2% | 14.20% |
| Asia Pacific | 33.8% | 18.00% |
| Europe | 21.8% | 15.20% |
| Latin America | 4.8% | 16.20% |
| Middle East & Africa | 4.4% | 18.70% |
North America's studios, leagues and newsrooms run the largest programs
North America held 35.2% of 2025 value and grows at 14.20% a year. The United States hosts the largest studios, sports leagues and news groups. Fox's Verify protocol, licensed collectible platforms such as NBA Top Shot and NFL ALL DAY on Dapper Labs' Flow chain, and U.S. Copyright Office guidance on AI authorship anchor demand. Growth trails the global rate because collectibles, the most mature use in the region, expand more slowly than provenance and rights services.
Asia Pacific moves Japanese and Korean entertainment IP on-chain
Asia Pacific held 33.8% of 2025 value and grows at 18.00% a year. Sony's Soneium network, Japanese music-rights work with JASRAC and Kendrix, and K-pop IP programs such as the DayOneDream partnership drive demand. LINE mini-apps were announced for Soneium in 2025, opening on-chain experiences to an audience of more than 200 million users. Game companies add volume, including Square Enix with its SYMBIOGENESIS title and Sky Mavis, which runs the Ronin network.
Europe's legal clarity on unique tokens supports issuers
Europe held 21.8% of 2025 value and grows at 15.20% a year. MiCA's exclusion for unique NFTs gives issuers of tickets, passes and art a clear legal path, while the end of the transition period on July 1, 2026, raises the bar for platforms that serve EU fans. The BBC sits on the C2PA steering committee, and French game publisher Ubisoft brings on-chain items to a long-running franchise through Might & Magic Fates.
Latin America and Middle East & Africa build on football fans and Gulf media hubs
Latin America held 4.8% of 2025 value and grows at 16.20% a year. Football clubs and music fan bases in Brazil and Argentina drive fan-token and pass programs. The Middle East & Africa held 4.4% of 2025 value and is the fastest-growing region at 18.70% a year. Gulf states are building media, gaming and sports hubs with web3 licensing regimes, from a small base.
K-pop tokens, licensing standards and an EU deadline
| Development | Status and market relevance |
|---|---|
| In October 2026, Soneium announced support for ERC-8432, an IP licensing standard designed to be readable by people and AI agents. | Announced. Moves license terms into a machine-readable on-chain format. |
| In September 2026, Soneium partnered with DayOneDream to bring K-pop IP on-chain as tokenized IP. | Partnership. Extends studio-run chains to Korean music IP. |
| In July 2026, the MiCA transition period for existing crypto-asset service providers in the EU ended on July 1. | In force. Ends grandfathering for platforms serving EU fans. |
| In June 2025, Sony launched Camera Verify, letting news organizations share C2PA signature checks with third parties. | Launched. Brings signed provenance to news photography. |
| In April 2025, Immutable announced that Ubisoft had partnered with it on Might & Magic Fates. | Partnership. Puts a major franchise on blockchain item infrastructure. |
Studio layer-2s and camera signing shape ledger technology
- Studio layer-2 networks such as Soneium, built as Ethereum layer-2 chains, give media groups control over fees, identity and fan data. Soneium hosted more than 250 live apps in 2025.
- Capture signing adds C2PA signatures in the camera, under a specification now at version 2.3, creating the records that ledger registries anchor and license.
- Machine-readable licensing standards such as ERC-8432 express IP license terms that both people and AI agents can read, enabling automated access deals.
- Zero-knowledge chains combine scale with privacy for publishers, and Fox plans to move Verify to its own zero-knowledge chain on Ethereum built with Polygon CDK.
- Invisible wallets from game publishers let players start without buying tokens, so ownership sits in the background of normal play.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Media owners, game platforms and fan-token firms compete
Suppliers fall into four groups, starting with media groups that run their own networks. Sony backs Soneium through Sony Block Solutions Labs and supplies C2PA signing in its professional cameras, while Fox Corporation operates Verify on Polygon. Gaming and collectible platforms, including Immutable, Dapper Labs, Sky Mavis and Animoca Brands, supply chains, wallets, marketplaces and investment to publishers such as Ubisoft and Square Enix. Infrastructure and fan-token firms, led by Polygon Labs and Chiliz, provide networks and the Socios platform used by football clubs. Ledger-based provenance tools build on the Content Credentials standard, which Adobe helps lead within the C2PA. Credence Research estimates the 10 largest suppliers hold just over half of 2025 value, with concentration lowest in provenance and rights, where standards are still forming. The likely winners make the ledger invisible to fans and readers.
Media ledger suppliers and their roles
| Company | Type | Role in the market |
|---|---|---|
| Sony | Media group | Backs the Soneium layer-2 network and supplies C2PA signing through Camera Verify |
| Fox Corporation | Media group | Runs the Verify content signing and licensing protocol, with TIME as first outside publisher |
| Immutable | Gaming infrastructure | Chains, wallets and marketplace for publishers including Ubisoft |
| Dapper Labs | Collectibles platform | NBA Top Shot and NFL ALL DAY on the Flow chain |
| Animoca Brands | Investor and game developer | Invests across web3 games and media firms and builds its own titles |
| Sky Mavis | Gaming network | Runs the Ronin network for games |
| Polygon Labs | Infrastructure provider | Network for Fox Verify and tooling for its planned chain |
| Chiliz | Fan-token platform | Socios fan-token platform used by football clubs |
| Square Enix | Game publisher | Blockchain title SYMBIOGENESIS |
| Ubisoft | Game publisher | Might & Magic Fates on Immutable infrastructure |
Media ledgers now sell proof and permission, not speculation
Credence Research's view is that media ledgers have become infrastructure for proof and permission, not a product sold to speculators. The NFT boom inflated earlier expectations; the spending that remains pays for signing, licensing, rights records and fan memberships, which is why provenance and authentication is the fastest-growing application. Suppliers that hide wallets, plug into C2PA signing and handle license settlement for AI developers are best placed. The main risk is that signed files and shared databases prove good enough, so buyers and investors should watch AI licensing deals, collecting-society pilots and MiCA enforcement.
Spend-based model excludes NFT trading and token prices
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from live programs run by studios, labels, broadcasters, game publishers and ticketing firms, priced by platform, infrastructure and services spend, and checked against the media-related revenue of supplier pools with trading income and token gains removed; type, application and regional splits are Credence Research estimates. Supporting evidence comes from company announcements, published network data, EU regulatory texts and U.S. Copyright Office publications.
Licensing and rights services outgrow collectibles by 2035
Through 2035, spending will shift from collectibles toward provenance, licensing and rights services, as AI developers pay for content with an audit trail and labels share registries. Studio-run networks will carry more fan programs, and game publishers will keep wallets out of sight. On Credence Research's regional growth rates, Asia Pacific overtakes North America in value around 2027, while the Middle East & Africa grows fastest from a small base. The pace will depend on licensing standards, collecting-society adoption and how strictly EU rules treat large token series.
Frequently Asked Questions
What was the size of the blockchain in media and entertainment market in 2025?
What is the forecast value and CAGR of the blockchain in media and entertainment market?
Why is this estimate lower than older figures for the market?
Which region leads the blockchain in media and entertainment market?
Which application leads, and which grows fastest?
Who are the major companies in blockchain for media and entertainment?
Does MiCA regulate NFTs used by media companies?
What challenges could slow the blockchain in media and entertainment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Public Blockchain
- 1.2.2 Private Blockchain
- 1.2.3 Consortium Blockchain
- 1.3 By Application
- 1.3.1 Digital Collectibles & Gaming Assets
- 1.3.2 Ticketing & Fan Engagement
- 1.3.3 Content Distribution & Advertising
- 1.3.4 Royalty Payments & Rights Management
- 1.3.5 Content Provenance & Authentication
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 748.0 million → 2035: USD 3.33 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Blockchain in Media and Entertainment Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Blockchain in Media and Entertainment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Blockchain in Media and Entertainment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Blockchain in Media and Entertainment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Blockchain in Media and Entertainment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Blockchain in Media and Entertainment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Blockchain in Media and Entertainment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Blockchain in Media and Entertainment Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 748.0 million → 2035: USD 3.33 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Blockchain in Media and Entertainment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Public Blockchain
- 12.3.7.2 Private Blockchain
- 12.3.7.3 Consortium Blockchain
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Digital Collectibles & Gaming Assets
- 12.4.7.2 Ticketing & Fan Engagement
- 12.4.7.3 Content Distribution & Advertising
- 12.4.7.4 Royalty Payments & Rights Management
- 12.4.7.5 Content Provenance & Authentication
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Blockchain in Media and Entertainment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Blockchain in Media and Entertainment Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Blockchain in Media and Entertainment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Blockchain in Media and Entertainment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sony
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Fox Corporation
- 18.4 Immutable
- 18.5 Dapper Labs
- 18.6 Animoca Brands
- 18.7 Polygon Labs
- 18.8 Chiliz
- 18.9 Sky Mavis
- 18.10 Square Enix
- 18.11 Ubisoft
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

