
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Business Intelligence & Analytics Software Market Size 2023 | USD 33,365 Million |
| Business Intelligence & Analytics Software Market, CAGR | 12.96% |
| Business Intelligence & Analytics Software Market Size 2032 | USD 88,448.11 Million |
Market Overview
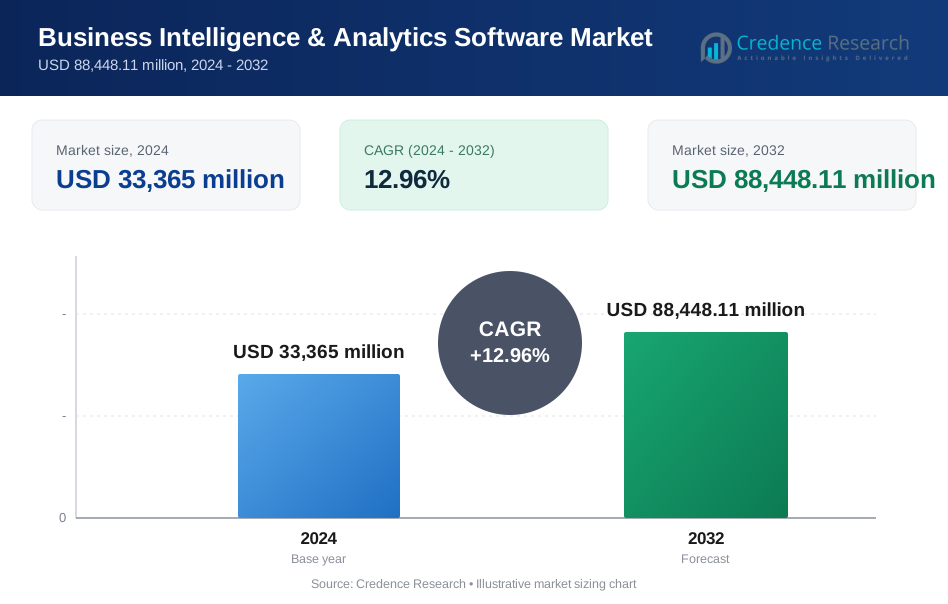
The global Business Intelligence and Analytics Software market is projected to grow from USD 33,365 million in 2024 to USD 88,448.11 million by 2032, exhibiting a compound annual growth rate (CAGR) of 12.96%.
The Business Intelligence and Analytics Software market is driven by the increasing demand for data-driven decision-making across industries, as organizations seek to enhance operational efficiency and competitiveness. The rapid growth of big data and the proliferation of cloud computing technologies further fuel market expansion, enabling companies to access and analyze vast amounts of information seamlessly. Additionally, the rise of advanced analytics tools, including artificial intelligence and machine learning, empowers businesses to derive actionable insights and improve forecasting capabilities. As companies prioritize data analytics to enhance customer experiences and optimize processes, the market is poised for significant growth.
The Business Intelligence & Analytics Software market is witnessing significant growth across various regions, with North America leading due to its advanced technological infrastructure and high adoption rates of BI tools. Key players such as Microsoft, IBM Corporation, and Oracle dominate this landscape, leveraging their robust product offerings and innovation capabilities. Europe follows closely, driven by increasing demand for data-driven decision-making among enterprises. Additionally, companies like SAP SE and Tableau Software are expanding their presence in this region, focusing on enhancing customer experiences through advanced analytics solutions. Emerging markets in Asia-Pacific are also gaining traction, presenting lucrative opportunities for growth.
Market Drivers
Data Explosion and Complexity
The Business Intelligence and Analytics Software market is significantly driven by the overwhelming volume, variety, and velocity of data generated from diverse sources such as IoT devices, social media, and e-commerce platforms. For instance, a report by IDC highlighted that the global data sphere is expected to reach 175 zettabytes by 2025, driven by the proliferation of IoT devices and digital platforms. This exponential growth complicates traditional data management techniques, necessitating sophisticated tools capable of extracting meaningful insights from structured, unstructured, and semi-structured data formats. Additionally, the rapid pace at which data is generated and updated demands robust real-time analytics capabilities, pushing organizations to adopt advanced BI solutions that can keep up with this dynamic environment.
Need for Data-Driven Decision Making
As organizations strive for enhanced decision-making, the demand for Business Intelligence and analytics tools is growing. For example, a survey by PwC found that highly data-driven organizations are three times more likely to report significant improvements in decision-making compared to those who rely less on data. These tools provide actionable insights that empower businesses to make informed decisions. By identifying trends, patterns, and anomalies, companies can optimize operations, reduce costs, and enhance productivity. Moreover, data-driven organizations gain a competitive advantage by swiftly identifying market opportunities and mitigating risks, allowing them to respond effectively to changing market dynamics and consumer behaviors.
Advancements in Technology
Technological advancements, particularly in cloud computing, artificial intelligence, and data visualization, play a pivotal role in the market's growth. Cloud-based BI solutions offer scalability, cost-effectiveness, and accessibility, attracting organizations of all sizes. Meanwhile, AI and machine learning algorithms facilitate automated data analysis, predictive modeling, and advanced analytics. Coupled with powerful visualization tools, these technologies make complex data more understandable, broadening accessibility to insights across various organizational levels.
Increasing Adoption of Mobile Devices
The increasing adoption of mobile devices further accelerates the demand for Business Intelligence solutions. Mobile-friendly BI applications allow users to access critical insights on-the-go, enabling timely decision-making. With real-time analytics capabilities, mobile BI empowers users to monitor key metrics and respond promptly to emerging trends. This flexibility enhances organizational agility, supporting data-driven strategies in an increasingly fast-paced business landscape.
Market Trends
Integration of Artificial Intelligence, Machine Learning, and Cloud-Based Solutions
The integration of Artificial Intelligence (AI) and Machine Learning (ML) into Business Intelligence (BI) tools marks a significant trend in the market, enhancing automated insights and predictive analytics. For instance, a report by IBM found that 45% of large enterprises have deployed AI in their BI processes, with plans for 80-90% adoption in the next two years. AI and ML algorithms automate data analysis processes, enabling organizations to generate actionable insights swiftly. Furthermore, these technologies facilitate predictive analytics, empowering businesses to forecast future trends and make proactive decisions. Natural Language Processing (NLP) capabilities in BI tools allow users to engage with data through natural language queries, making data interaction more intuitive and accessible. In tandem with these advancements, cloud-based BI solutions are gaining traction due to their scalability and flexibility. Organizations can quickly adapt cloud deployments to meet evolving business needs without the burden of significant upfront investments in hardware and infrastructure. The enhanced accessibility of cloud-based BI tools enables users to access critical insights from anywhere, promoting remote work and collaboration.
Emergence of Self-Service BI, Advanced Data Visualization, and Real-Time Analytics
Another pivotal trend is the emergence of self-service BI, which empowers end-users to access and analyze data independently, eliminating their reliance on IT professionals. This democratization of data fosters a data-driven culture within organizations, accelerating decision-making processes and enhancing overall agility. Modern self-service BI tools feature user-friendly interfaces and drag-and-drop functionality, simplifying data exploration for non-technical users. In parallel, advanced data visualization techniques, including interactive dashboards and data storytelling, are transforming how insights are communicated. Interactive dashboards enable users to drill down into data, uncovering insights that can be easily shared with stakeholders, while effective data storytelling techniques make complex data compelling and comprehensible. Additionally, geospatial analytics allows organizations to visualize data on maps, revealing geographic patterns and trends. The trend toward real-time analytics further amplifies the need for BI tools, as organizations seek time-sensitive insights that enable immediate responses to emerging trends. Advanced streaming analytics tools can process large volumes of data in real-time, integrating seamlessly with IoT devices to analyze sensor data and derive valuable insights. This combination of trends illustrates a shift toward more dynamic, user-centric BI solutions that empower organizations to harness data effectively for informed decision-making.
Market Challenges Analysis
Challenges in Data Quality, Integration, and Skill Gaps
Organizations face significant challenges in data quality and integration, primarily due to data silos that scatter information across various systems and departments. This fragmentation complicates the process of integrating and analyzing data, leading to data inconsistencies that can result in inaccurate insights. Furthermore, the labor-intensive process of data cleansing and preparation can hinder timely analysis, consuming valuable resources and delaying decision-making. Compounding these issues is a prevalent skill gap within many organizations; a lack of data literacy among employees often prevents effective utilization of Business Intelligence (BI) tools. Additionally, the shortage of skilled data analysts and scientists exacerbates this problem, leaving organizations without the necessary expertise to manage and analyze complex datasets effectively. This skill gap not only limits data-driven decision-making but also stifles innovation and growth.
Complexity, Cost, and Security Concerns
The complexity and cost associated with BI tools present further challenges for organizations. For example, IBM highlights that integrating new BI technologies with existing IT infrastructure can be complex and costly, requiring significant time and technical expertise. Many BI solutions have steep learning curves, necessitating significant training and expertise that can strain resources and slow down implementation. Moreover, high implementation costs, especially for large-scale deployments, can deter organizations from adopting advanced BI solutions, leaving them unable to leverage the full potential of their data. Security and privacy concerns also loom large, as the collection and storage of sensitive data heighten the risk of data breaches and cyberattacks. Organizations must navigate stringent regulatory compliance requirements, such as those outlined in GDPR and CCPA, which can be challenging and resource-intensive. Additionally, overwhelming data volumes contribute to information overload, making it difficult for users to extract meaningful insights and leading to analysis paralysis and decision fatigue. Finally, as business needs evolve and rapid technological advancements occur, organizations must ensure that their BI tools are adaptable and aligned with current requirements. Addressing these challenges requires organizations to invest in data quality, foster a data-driven culture, select user-friendly tools, prioritize security, leverage cloud-based solutions, and commit to continuous learning and development.
Market Segmentation Analysis:
By Segment and Services:
The Business Intelligence & Analytics Software market is primarily segmented into various categories based on its core functionalities. The segment comprising Business Intelligence (BI) Platforms leads the market due to its comprehensive capabilities that enable organizations to analyze and visualize data effectively. These platforms facilitate real-time reporting, interactive dashboards, and self-service analytics, allowing users to derive actionable insights swiftly. Corporate Performance Management (CPM) Suites also play a critical role, assisting organizations in strategic planning and performance monitoring. Advanced and Predictive Analytics is gaining traction, driven by the increasing need for data-driven forecasting and decision-making. Meanwhile, Content Analytics and Analytics Applications are essential for organizations looking to extract valuable insights from unstructured data and enhance their operational efficiency.
By Deployment modes:
In addition to software segments, the market encompasses various services that enhance the effectiveness of BI solutions. Professional Services are vital for implementation, customization, and training, ensuring organizations can leverage their BI tools to the fullest. Furthermore, Managed Services are becoming increasingly popular, offering organizations the advantage of outsourced management and maintenance of their BI environments. The deployment of these solutions is further categorized into On-premise and Cloud models. While on-premise solutions provide control and security, cloud-based deployment is gaining momentum due to its scalability, cost-effectiveness, and accessibility. This shift toward cloud adoption reflects a broader trend in the industry, emphasizing the need for flexibility and remote access to BI capabilities.
Segments:
Based on Segment and Services:
- Segment
- Business Intelligence (BI) Platforms
- Corporate Performance Management (CPM) Suite
- Advanced and Predictive Analytics
- Content Analytics
- Analytics Application
- Services
- Professional Services
- Managed Services
Based on Deployment modes:
- On-premise
- Cloud
Based on Organization size:
- Small Medium Business (SMB’s)
- Large enterprises
Based on Verticals:
- Banking, Financial Services, and Insurance (BFSI)
- Healthcare
- IT & Telecom
- Retail
- Manufacturing
- Education
- Government
- Energy and Power
- Media & Entertainment
- Others (transport & logistics, and hospitality)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region dominates the Business Intelligence & Analytics Software market, accounting for approximately 40% of the global market share in 2024. This leadership position is primarily driven by the presence of numerous technology giants and a robust ecosystem of innovative startups. Organizations across various industries in North America are increasingly investing in advanced BI solutions to enhance their decision-making processes and improve operational efficiency. The region benefits from high data maturity levels, enabling companies to leverage data analytics effectively. Additionally, the rapid adoption of cloud-based solutions and artificial intelligence technologies is further propelling market growth in this region, allowing organizations to derive actionable insights from their data.
Asia-Pacific
In contrast, the Asia-Pacific region is witnessing significant growth in the Business Intelligence & Analytics Software market, expected to capture around 30% of the global market share. This growth is fueled by the increasing digital transformation initiatives across emerging economies such as India and China, where businesses are prioritizing data-driven strategies to remain competitive. The rising adoption of mobile analytics, coupled with advancements in artificial intelligence and machine learning, is enabling organizations to harness the power of data more effectively. Furthermore, government initiatives aimed at promoting digitalization and smart city projects are driving demand for BI solutions. As organizations in the Asia-Pacific region continue to prioritize data analytics, the market is poised for substantial growth in the coming years.
Key Player Analysis
- Microsoft
- Oracle
- IBM Corporation
- Tableau Software, LLC (Salesforce, Inc.)
- SAP SE
- MicroStrategy Incorporated
- QlikTech International AB
- Sisense Ltd
- Yellowfin International Pty Ltd (Yellowfin)
- Rackspace US Inc
Competitive Analysis
The competitive landscape of the Business Intelligence & Analytics Software market is characterized by intense rivalry among leading players, including Microsoft, IBM Corporation, Oracle, SAP SE, Tableau Software, LLC (Salesforce, Inc.), QlikTech International AB, Sisense Ltd, MicroStrategy Incorporated, Rackspace US Inc , and Yellowfin International Pty Ltd. Microsoft and Tableau excel in user-friendly interfaces and cloud-based solutions, attracting small to medium-sized enterprises. Companies focus on developing scalable offerings that cater to small and medium-sized enterprises, as well as large organizations with complex needs. The integration of analytics within broader enterprise solutions is a key strategy, enhancing the value proposition for customers. Additionally, strong data visualization capabilities are increasingly important for users seeking interactive and insightful analytics. Overall, the competitive dynamics are shaped by the ability to address evolving customer requirements, strategic partnerships, and the ongoing demand for real-time data insights.
Recent Developments
- In June 2024, MicroStrategy released an update that allows enterprises to layer AI-driven data insights directly into any web and mobile application. This update enables organizations to leverage AI technology to enhance their data analysis and decision-making processes.
- In February 2024, MyDigitalOffice (MDO) rebranded as Otelier and announced the launch of IntelliSight, a Unified Business Intelligence Platform. IntelliSight allows hoteliers to collect cross-functional data for insights and analysis. This solution enables hoteliers to make data-driven decisions, increase efficiency, and optimize operations.
- In May 2023, Rackspace US Inc announced Object Storage which enables organizations securely store and utilize large pools of unstructured data, where Rackspace Object Storage saves substantial costs by eliminating data egress, retrieval, and transaction charges. In many cases, the Rackspace Object Storage solution can save more than 80% over hyper-scale cloud storage options. For multi-cloud customers operating modern S3-enabled applications, this is a new paradigm that facilitates better performance and lower costs, even as data-intensive applications continue to drive up the need for storage,
- In May 2023, GoodData announced the release of its new Last Mile ETL feature, which helps customers streamline their data management processes, enabling more effective use of time and resources and maximized data velocity. It fully supports changes made to the logical data model (LDM) within the GoodData interface without affecting the data and data structure in a user's database.
Market Concentration & Characteristics
The Business Intelligence & Analytics Software market exhibits a moderate level of concentration, with several key players dominating the landscape while numerous smaller companies provide niche solutions. The presence of established giants fosters a competitive environment where innovation and customer-centric approaches are essential for differentiation. Market characteristics include a growing demand for cloud-based solutions, as organizations seek scalable and flexible tools to manage their data needs. Additionally, the integration of advanced technologies such as artificial intelligence and machine learning is becoming prevalent, allowing businesses to gain deeper insights and enhance decision-making processes. Furthermore, the shift towards self-service analytics empowers non-technical users, facilitating a data-driven culture across organizations. As companies increasingly recognize the importance of data in driving business success, the market is likely to see continued growth, characterized by evolving technologies and an emphasis on user-friendly, accessible solutions.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Segment and Services, Deployment modes, Organization size, Verticals and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for Business Intelligence & Analytics Software is projected to expand significantly, driven by increasing data volumes and complexity.
- Adoption of cloud-based solutions will continue to rise, offering businesses flexibility and scalability to meet evolving data needs.
- Integration of artificial intelligence and machine learning will enhance predictive analytics capabilities, enabling organizations to make more informed decisions.
- Self-service analytics tools will empower non-technical users, fostering a data-driven culture across various departments.
- Advanced data visualization techniques will become more prevalent, helping users understand complex data through intuitive dashboards and reports.
- The demand for real-time analytics will grow, allowing organizations to respond quickly to emerging trends and changes in the market.
- Regulatory compliance and data governance will remain a priority, driving the need for robust security measures and data management practices.
- Mobile BI solutions will gain traction, providing users with access to insights and analytics on-the-go.
- Businesses will increasingly seek integrated platforms that combine various analytics functions, simplifying data management and analysis.
- Collaboration features within BI tools will improve, enabling teams to work together more effectively on data-driven projects.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Business Intelligence & Analytics Software market?
What factors are driving the growth of the Business Intelligence & Analytics Software market?
What are the key segments within the Business Intelligence & Analytics Software market?
What are some challenges faced by the Business Intelligence & Analytics Software market?
Who are the major players in the Business Intelligence & Analytics Software market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Business Intelligence & Analytics Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Business Intelligence & Analytics Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 33,365 million → 2032: USD 88,448.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Business Intelligence & Analytics Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Business Intelligence & Analytics Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Business Intelligence & Analytics Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Business Intelligence & Analytics Software Market Drivers
- 3.3 Business Intelligence & Analytics Software Market Restraints & Challenges
- 3.4 Business Intelligence & Analytics Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Business Intelligence & Analytics Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Business Intelligence & Analytics Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Business Intelligence & Analytics Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Business Intelligence & Analytics Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Business Intelligence & Analytics Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Business Intelligence & Analytics Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Business Intelligence & Analytics Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Business Intelligence & Analytics Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Business Intelligence & Analytics Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Business Intelligence & Analytics Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Business Intelligence & Analytics Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Business Intelligence & Analytics Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Business Intelligence & Analytics Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Business Intelligence & Analytics Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Business Intelligence & Analytics Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Business Intelligence & Analytics Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Business Intelligence & Analytics Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Business Intelligence & Analytics Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Business Intelligence & Analytics Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
