
Castrate Resistant Prostate Cancer Therapeutics Market Overview:
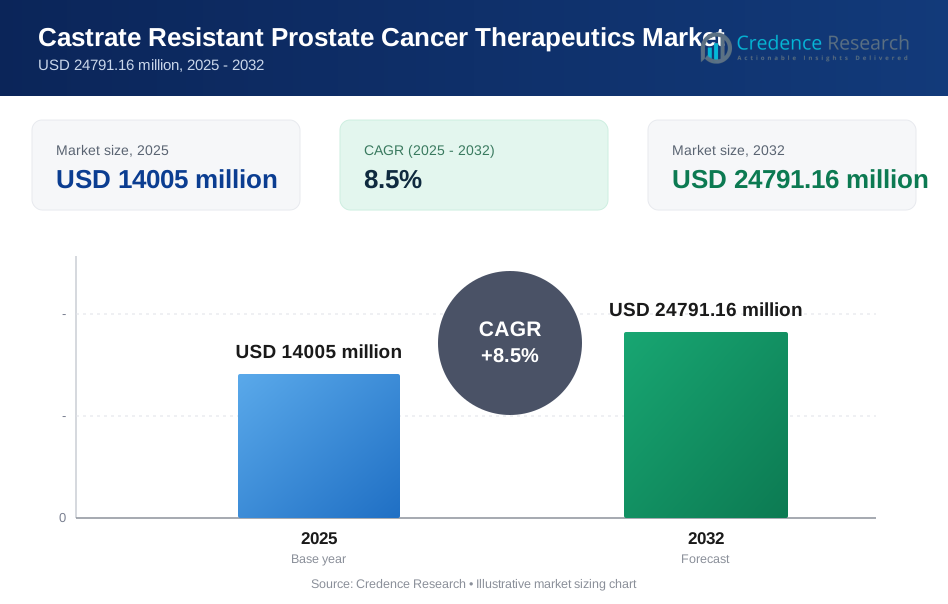
The global Castrate Resistant Prostate Cancer Therapeutics Market size was estimated at USD 14005 million in 2025 and is expected to reach USD 24791.16 million by 2032, growing at a CAGR of 8.5% from 2025 to 2032. Growth is primarily driven by rising use of next-generation androgen-axis therapies and biomarker-guided treatment sequencing that extend disease control and expand eligible patient pools across advanced stages. North America remains a major revenue center, and Asia Pacific continues to gain share as access to specialty oncology care improves across large-population countries.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Castrate Resistant Prostate Cancer Therapeutics Market Size 2025 | USD 14005 million |
| Castrate Resistant Prostate Cancer Therapeutics Market, CAGR | 8.5% |
| Castrate Resistant Prostate Cancer Therapeutics Market Size 2032 | USD 24791.16 million |
Key Market Trends & Insights
- The Castrate Resistant Prostate Cancer Therapeutics Market is projected to expand from USD 14005 million (2025) to USD 24791.16 million (2032) at a CAGR of 8.5% (2025–2032).
- Hormonal Therapy accounted for the largest share of 44.60% in 2025, supported by durable use of androgen-axis backbones across lines of therapy.
- AR Signalling Inhibitors held 33.10% share in 2025, reflecting continued clinical dependence on AR-pathway suppression in advanced prostate cancer care.
- Oral formulations represented 61.90% in 2025, indicating strong preference for outpatient-friendly regimens that reduce infusion burden.
- Asia Pacific reached 31.60% share in 2025, narrowing the gap with North America (34.20%) as treatment penetration rises.

Segment Analysis
Treatment choice in the Castrate Resistant Prostate Cancer Therapeutics Market is shaped by sequencing across hormonal agents, chemotherapy, immunotherapy, and radiotherapy based on disease biology, prior exposure, and patient fitness. Clinical practice increasingly emphasizes optimizing the androgen-axis backbone and layering additional modalities to delay progression and improve quality of life. Oral therapies strengthen adherence and support long-term management in outpatient settings, which influences prescribing and distribution patterns.
Innovation momentum is also driven by mechanism-led and biomarker-informed strategies, including DNA-damage response modulation and PSMA-targeted approaches. These approaches are expanding beyond niche use cases as diagnostic testing improves and evidence accumulates in broader patient subsets. Combination regimens are increasingly evaluated to deepen response and extend benefit in resistant disease pathways, supporting ongoing market expansion.
By Therapy Type Insights
Hormonal Therapy accounted for the largest share of 44.60% in 2025. Hormonal Therapy leadership is supported by entrenched guideline positioning of androgen-axis suppression as a core backbone across advanced disease states. Hormonal Therapy adoption is reinforced by strong clinician familiarity, broad eligibility, and compatibility with add-on mechanisms that extend benefit. Hormonal Therapy also benefits from outpatient convenience and sustained use across multiple lines, which supports consistent revenue contribution.
By Mechanism of Action Insights
AR Signalling Inhibitors accounted for the largest share of 33.10% in 2025. AR Signalling Inhibitors lead because AR-pathway dependence remains a key driver of disease progression even after castration resistance develops. AR Signalling Inhibitors retain high utilization through established clinical sequencing and wide availability across major markets. AR Signalling Inhibitors also align well with combination strategies and treatment intensification approaches that extend control in advanced disease settings.
By Distribution Channel Insights
Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, and Homecare Settings each play distinct roles in access for the Castrate Resistant Prostate Cancer Therapeutics Market. Hospital Pharmacies remain critical for complex regimens, initiation of advanced therapies, and coordination of supportive monitoring. Retail Pharmacies and specialty channels are increasingly important for oral therapies that support outpatient continuity. Homecare Settings and Online Pharmacies expand convenience in select systems where payer models and clinical monitoring pathways support safe delivery.
Castrate Resistant Prostate Cancer Therapeutics Market Drivers
Expanding Use of Androgen-Axis Backbones and Combination Sequencing
The Castrate Resistant Prostate Cancer Therapeutics Market benefits from sustained reliance on androgen-axis therapies as foundational treatment across advanced stages. Clinical sequencing increasingly pairs hormonal backbones with additional modalities to extend disease control and delay progression. Broader adoption is supported by clinician familiarity, established care pathways, and repeated use across multiple lines of therapy. Treatment optimization and earlier intervention approaches continue to expand addressable patient segments and support market growth.
Rising Biomarker Testing and Precision Treatment Pathways
The Castrate Resistant Prostate Cancer Therapeutics Market is being reshaped by broader biomarker testing that improves treatment selection and increases uptake of mechanism-led therapies. Testing for actionable alterations supports more targeted prescribing and improves confidence in benefit-risk decisions. Precision pathways also strengthen payer justification for advanced therapies in eligible subgroups. Expanding diagnostic infrastructure and improved clinical evidence are accelerating adoption across major oncology centers and strengthening long-term growth potential.
- For instance, Foundation Medicine’s FoundationOne® CDx assay identified homologous recombination repair (HRR) gene alterations in 23% of metastatic castration-resistant prostate cancer (mCRPC) patients in a 2023 real-world cohort, enabling PARP inhibitor eligibility for olaparib or rucaparib in biomarker-positive subsets per PROfound and TRITON3 trial criteria.
Shift Toward Outpatient-Friendly Oral Treatment Models
The Castrate Resistant Prostate Cancer Therapeutics Market is supported by strong preference for outpatient treatment models that reduce infusion burden and improve continuity. Oral regimens enable easier long-term administration, which supports adherence and reduces operational pressure on infusion sites. Outpatient suitability also broadens access through specialty retail and structured home delivery models in select geographies. These dynamics reinforce sustained utilization and support stable revenue contribution from chronic therapy management.
Pipeline Momentum in Targeted and Radiopharmaceutical Approaches
The Castrate Resistant Prostate Cancer Therapeutics Market continues to expand as targeted modalities and radiotherapy-based approaches progress through development and broader clinical use. PSMA-directed strategies and DNA-damage response modulation provide differentiated routes to treat resistant disease pathways. Evidence generation supports movement into earlier lines and combination regimens that expand eligible populations. Ongoing innovation increases competitive intensity and strengthens long-term market expansion through new options and improved outcomes.
- For instance, Novartis AG’s ¹⁷⁷Lu-PSMA-617 (Pluvicto®) demonstrated a median overall survival (OS) of 15.3 months versus 11.3 months with standard care alone in the phase 3 VISION trial, and received FDA approval in March 2022 for PSMA-positive mCRPC post-androgen-axis and taxane therapy.
Castrate Resistant Prostate Cancer Therapeutics Market Challenges
The Castrate Resistant Prostate Cancer Therapeutics Market faces access and affordability constraints driven by high therapy costs, variable reimbursement, and differences in national treatment guidelines. Payers often require strict eligibility criteria and prior authorization, which can delay initiation and limit uptake in certain care settings. Clinical pathway complexity also increases administrative burden as sequencing decisions require close monitoring and coordination across oncology teams. These factors can slow adoption, especially in cost-sensitive health systems.
- For instance, Novartis AG's Pluvicto (lutetium-177-PSMA-617) carries a wholesale acquisition cost of approximately $47,000 per dose in the United States, with a standard regimen requiring up to six doses, creating substantial budget impact for health systems.
The Castrate Resistant Prostate Cancer Therapeutics Market also faces challenges from treatment resistance, heterogeneous patient response, and adverse-event management that complicate long-duration therapy. Cross-resistance within hormone-pathway approaches can reduce effectiveness over time and require switches across therapy classes. Biomarker testing availability remains uneven across regions, limiting precision prescribing in routine practice. Operational constraints in specialty care capacity can further restrict timely access in under-resourced settings.
Castrate Resistant Prostate Cancer Therapeutics Market Trends and Opportunities
The Castrate Resistant Prostate Cancer Therapeutics Market is witnessing a trend toward mechanism-guided combinations that deepen response and extend duration of benefit. Combination regimens linking androgen-axis suppression with DNA-damage response strategies are gaining attention as diagnostic testing expands. Earlier identification of high-risk patients creates opportunity for intensified approaches that shift advanced therapies into earlier treatment stages. These changes support larger eligible populations and create pathways for differentiation through evidence-led positioning.
- For instance, in the Phase III TALAPRO-2 trial, Pfizer's Talzenna (talazoparib) combined with Astellas' Xtandi (enzalutamide) demonstrated a median radiographic progression-free survival (rPFS) of 33.1 months versus 19.5 months with enzalutamide alone (hazard ratio 0.67), and final overall survival data showed a median OS of 45.8 months versus 37.0 months, representing an 8.8-month survival advantage in first-line mCRPC.
The Castrate Resistant Prostate Cancer Therapeutics Market also shows growing opportunity in expanding access across emerging health systems through specialty distribution and structured monitoring models. Growth in Asia Pacific is supported by increasing oncology infrastructure, rising awareness, and broader availability of advanced therapies. Digital support tools and care pathway optimization improve adherence and follow-up, supporting sustained use in outpatient settings. These trends collectively strengthen long-term expansion opportunities for established and new entrants.
Regional Insights
North America
North America contributed 34.20% of 2025 revenue in the Castrate Resistant Prostate Cancer Therapeutics Market, supported by strong reimbursement depth, high use of advanced therapies, and established oncology care pathways. The region benefits from broad diagnostic access that supports precision treatment decisions and systematic sequencing. Specialty centers and integrated provider networks accelerate adoption of new standards of care. Ongoing innovation and real-world evidence generation continue to reinforce uptake across eligible patient groups.
Europe
Europe represented 22.80% of 2025 revenue in the Castrate Resistant Prostate Cancer Therapeutics Market, underpinned by guideline-led care and strong specialty infrastructure across major countries. Price controls and centralized reimbursement negotiations influence therapy mix and pace of adoption for premium modalities. Expanded biomarker testing and multi-disciplinary management strengthen precision prescribing in advanced disease. Market growth continues through progressive integration of mechanism-led therapies within structured treatment pathways.
Asia Pacific
Asia Pacific accounted for 31.60% of 2025 revenue in the Castrate Resistant Prostate Cancer Therapeutics Market, reflecting large patient populations and expanding access to specialty oncology care. Adoption is supported by increasing availability of advanced therapies, improved diagnostics, and growth in leading treatment hubs. Variation in healthcare funding and access creates uneven penetration across countries, but overall momentum remains strong. Continued investment in cancer care delivery supports rising utilization across outpatient and specialty settings.
Latin America
Latin America held 7.90% of 2025 revenue in the Castrate Resistant Prostate Cancer Therapeutics Market, driven by demand concentrated in major urban hubs and private-sector access pathways. Reimbursement constraints and limited specialty capacity restrict broad uptake of advanced treatments in several markets. Access expansion is supported by improving oncology infrastructure and growing specialty distribution reach. Treatment adoption often follows staged diffusion from leading centers to broader provider networks.
Middle East & Africa
Middle East & Africa captured 3.50% of 2025 revenue in the Castrate Resistant Prostate Cancer Therapeutics Market, with demand concentrated in better-funded systems and established specialty centers. Access remains uneven due to variations in healthcare budgets, diagnostic availability, and specialist density. GCC countries and select large markets act as regional anchors for advanced therapy adoption. Growth is supported by gradual expansion of oncology services and improved referral pathways.
Competitive Landscape
Competition in the Castrate Resistant Prostate Cancer Therapeutics Market centers on differentiating clinical outcomes through mechanism-led strategies, lifecycle management, and evidence generation for earlier-line use. Companies prioritize label expansion opportunities, combination regimens, and biomarker-aligned positioning to strengthen treatment sequencing relevance. Commercial success is increasingly tied to stakeholder education on testing pathways, patient selection, and real-world effectiveness across diverse clinical settings. Distribution strength and specialty engagement remain important to sustain adherence and continuity in outpatient management.
Johnson & Johnson maintains a strong presence in the Castrate Resistant Prostate Cancer Therapeutics Market through broad oncology reach and an emphasis on advancing precision combinations and androgen-axis aligned strategies. Johnson & Johnson benefits from scale across development, regulatory execution, and commercial access to sustain competitive positioning across advanced prostate cancer settings.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Johnson & Johnson
- Pfizer Inc.
- Bayer AG
- Sanofi
- Astellas Pharma
- Dendreon Pharmaceuticals
- Merck & Co.
- Clovis Oncology
- AstraZeneca
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2026, Monte Rosa Therapeutics announced a clinical supply agreement with Johnson & Johnson (Janssen) to support a Phase 2 trial evaluating MRT-2359 in combination with apalutamide (Erleada®) for metastatic CRPC. This partnership, finalized on March 16, 2026, will enable Monte Rosa to initiate a signal-confirming Phase 2 study in Q3 2026 targeting patients with androgen receptor (AR) mutations, building on compelling Phase 1/2 data showing activity in heavily pretreated patients.
- In February 2026, Astellas Pharma and Vir Biotechnology launched an up-to-$1.7 billion collaboration to co-develop and co-commercialize VIR-5500, an investigational T-cell engager for prostate cancer. Announced on February 24, 2026, this strategic partnership positions Astellas already a market leader in prostate cancer with Xtandi® and Pluvicto™ to oversee 60% of global development costs while Vir retains meaningful long-term economics and extends its cash runway into Q2 2028.
- In December 2025, the FDA granted regular approval to rucaparib (Rubraca) from pharmaand GmbH for adults with deleterious BRCA mutation-associated metastatic CRPC previously treated with an androgen receptor-directed therapy. This approval, dated December 17, 2025, converts the drug's prior accelerated approval (2020) into a full indication, reinforcing the precision medicine approach for BRCA-mutated CRPC patients.
- In October 2025, GSK acquired exclusive rights from Syndivia for a preclinical antibody-drug conjugate (ADC) targeting prostate cancer. Announced on October 26, 2025, this acquisition complements GSK's growing prostate cancer pipeline anchored by GSK'227 (a B7-H3-targeted ADC) and addresses the critical need for novel targeted treatments in metastatic castration-resistant settings
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 14005 million |
| Revenue forecast in 2032 | USD 24791.16 million |
| Growth rate (CAGR) | 8.5% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Therapy Type Outlook: Hormonal Therapy, Chemotherapy, Immunotherapy, Radiotherapy; By Mechanism of Action Outlook: AR Signalling Inhibitors, CYP17 Inhibitors, PSMA-Targeted Therapies, DNA-Damage Response Modulators, Immune Checkpoint Inhibitors; By Distribution Channel Outlook: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Homecare Settings |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Johnson & Johnson; Pfizer Inc.; Bayer AG; Sanofi; Astellas Pharma; Dendreon Pharmaceuticals; Merck & Co.; Clovis Oncology; AstraZeneca |
| No.of Pages | 328 |
Segmentation
By Therapy Type
- Hormonal Therapy
- Chemotherapy
- Immunotherapy
- Radiotherapy
By Mechanism of Action
- AR Signalling Inhibitors
- CYP17 Inhibitors
- PSMA-Targeted Therapies
- DNA-Damage Response Modulators
- Immune Checkpoint Inhibitors
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Homecare Settings
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Use of Androgen-Axis Backbones and Combination Sequencing
Sustained reliance on androgen-axis therapies as foundational treatment, combined with increasing use of combination regimens, extends disease control and broadens the eligible patient pool, supporting market growth across advanced stages.
Rising Biomarker Testing and Precision Treatment Pathways
Broader adoption of biomarker testing enables more targeted prescribing and increases uptake of mechanism-led therapies, improving patient selection and supporting the use of advanced therapeutics in biomarker-positive subgroups.
Shift Toward Outpatient-Friendly Oral Treatment Models
Strong preference for oral regimens that facilitate outpatient management improves adherence, reduces infusion burden, and supports long-term therapy, driving stable revenue and expanding access through retail and homecare channels.
Pipeline Momentum in Targeted and Radiopharmaceutical Approaches
Ongoing innovation in PSMA-targeted therapies, DNA-damage response modulators, and radiopharmaceuticals is expanding treatment options for resistant disease pathways, supporting earlier intervention and combination strategies that fuel market expansion.
Growth in Oncology Infrastructure and Access in Emerging Markets
Improved oncology infrastructure, rising awareness, and broader availability of advanced therapies in regions like Asia Pacific are increasing treatment penetration and driving significant market share gains in large-population countries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Castrate Resistant Prostate Cancer Therapeutics Market in 2025 and what is the forecast for 2032?
What is the growth rate for the Castrate Resistant Prostate Cancer Therapeutics Market during 2025–2032?
Which segment is the largest in the Castrate Resistant Prostate Cancer Therapeutics Market in 2025?
What factors are driving growth in the Castrate Resistant Prostate Cancer Therapeutics Market?
Who are the leading companies in the Castrate Resistant Prostate Cancer Therapeutics Market?
Which region leads the Castrate Resistant Prostate Cancer Therapeutics Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Therapy Type
- 1.2.1 Hormonal Therapy
- 1.2.2 Chemotherapy
- 1.2.3 Immunotherapy
- 1.2.4 Radiotherapy
- 1.3 By Mechanism of Action
- 1.3.1 AR Signalling Inhibitors
- 1.3.2 CYP17 Inhibitors
- 1.3.3 PSMA-Targeted Therapies
- 1.3.4 DNA-Damage Response Modulators
- 1.3.5 Immune Checkpoint Inhibitors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 14005 million → 2032: USD 24791.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Castrate Resistant Prostate Cancer Therapeutics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Castrate Resistant Prostate Cancer Therapeutics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Castrate Resistant Prostate Cancer Therapeutics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Castrate Resistant Prostate Cancer Therapeutics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Castrate Resistant Prostate Cancer Therapeutics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Castrate Resistant Prostate Cancer Therapeutics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Castrate Resistant Prostate Cancer Therapeutics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Castrate Resistant Prostate Cancer Therapeutics Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 14005 million → 2032: USD 24791.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Castrate Resistant Prostate Cancer Therapeutics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Therapy Type - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hormonal Therapy
- 12.3.7.2 Chemotherapy
- 12.3.7.3 Immunotherapy
- 12.3.7.4 Radiotherapy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Mechanism of Action - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 AR Signalling Inhibitors
- 12.4.7.2 CYP17 Inhibitors
- 12.4.7.3 PSMA-Targeted Therapies
- 12.4.7.4 DNA-Damage Response Modulators
- 12.4.7.5 Immune Checkpoint Inhibitors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Castrate Resistant Prostate Cancer Therapeutics Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Castrate Resistant Prostate Cancer Therapeutics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Castrate Resistant Prostate Cancer Therapeutics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Johnson & Johnson
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer Inc.
- 17.4 Bayer AG
- 17.5 Sanofi
- 17.6 Astellas Pharma
- 17.7 Dendreon Pharmaceuticals
- 17.8 Merck & Co.
- 17.9 Clovis Oncology
- 17.10 AstraZeneca
- 17.11 GSK
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

