
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cell Cryopreservation Market Size 2024 | USD 10,107 Million |
| Cell Cryopreservation Market, CAGR | 22.70% |
| Cell Cryopreservation Market Size 2032 | USD 51,925.27 Million |
Market Overview:
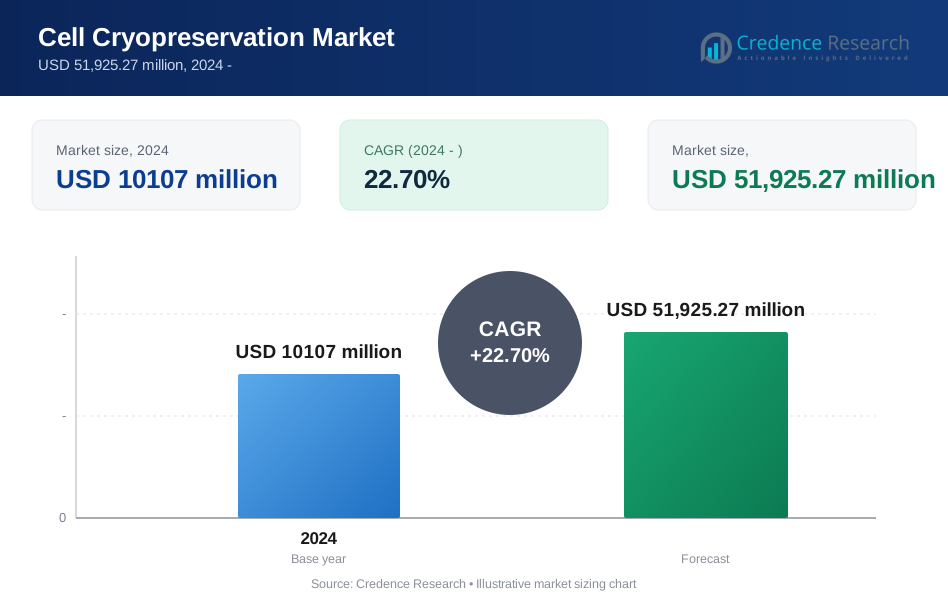
The Cell Cryopreservation Market is projected to grow from USD 10,107 million in 2024 to USD 51,925.27 million by 2032, achieving an impressive compound annual growth rate (CAGR) of 22.70% over the forecast period. Cell cryopreservation, a process that preserves cells, tissues, or any other biological constructs by cooling them to sub-zero temperatures, is essential for biobanking, regenerative medicine, and cell-based research. The market's rapid expansion is driven by the increasing adoption of cryopreservation in biotechnology and pharmaceuticals, where it is crucial for maintaining cell viability in research and therapeutic applications. As advancements in cell therapy and regenerative medicine continue to evolve, the demand for reliable cryopreservation solutions becomes more pressing, fueling market growth.
The cell cryopreservation market is primarily driven by the rising focus on regenerative medicine and cell therapy, which require advanced preservation methods to store various cell types, including stem cells, for extended periods. The increasing prevalence of chronic diseases, such as cancer and cardiovascular disorders, necessitates extensive research into cell-based therapies, thus enhancing demand for cryopreservation. Additionally, government funding and supportive initiatives for biobanking and research are propelling growth. For instance, the U.S. National Institutes of Health (NIH) allocates substantial funds towards regenerative medicine research, which further supports the expansion of cryopreservation technology. Furthermore, the growing number of clinical trials involving cryopreserved cells underscores the importance of reliable storage solutions, as cell-based treatments become more integral to advanced medical therapies.
Regionally, North America leads the cell cryopreservation market, accounting for a substantial share due to the region’s well-established biotechnology and pharmaceutical industries. The United States, in particular, is a key market due to significant investments in cell therapy and regenerative medicine research, supported by both government funding and private sector initiatives. Europe represents another important region, with countries like Germany and the U.K. advancing biobanking and regenerative medicine. The Asia-Pacific region is expected to witness the fastest growth, driven by rising healthcare expenditures, government initiatives, and increasing research activities in countries like China, Japan, and India. Expanding infrastructure and supportive regulatory frameworks in these regions further position Asia-Pacific as a critical growth area for the cell cryopreservation market.
Market Drivers:
Growing Demand for Regenerative Medicine and Cell-Based Therapies:
The increasing focus on regenerative medicine and cell-based therapies significantly drives the cell cryopreservation market. As chronic diseases such as diabetes, cancer, and neurodegenerative disorders rise globally, the need for innovative treatments like stem cell therapies has become critical. According to the World Health Organization (WHO), chronic diseases are the leading cause of death worldwide, which emphasizes the importance of research in cell-based treatments. Cell cryopreservation is essential in this field, as it allows for the long-term storage and availability of cells used in regenerative medicine, ensuring that viable cell lines are always on hand for clinical and research purposes.
Expansion of Biobanking for Research and Therapeutics:
Biobanking, which involves the preservation of biological samples for research and clinical applications, is expanding rapidly due to advancements in genomic research and personalized medicine. Government initiatives and funding support this growth, particularly in the United States and Europe, where biobanks play a vital role in disease research. For instance, the U.S. National Institutes of Health (NIH) funds extensive biobanking projects aimed at understanding and treating diseases at the genetic level. Biobanks rely on cryopreservation technology to maintain the quality of cells and tissues for long-term use, making cryopreservation a critical tool in medical research and precision medicine initiatives.
Rising Clinical Trials Involving Cell-Based Therapies:
As the pharmaceutical industry increasingly focuses on cell-based therapies, the number of clinical trials involving cryopreserved cells continues to grow. For example, the ClinicalTrials.gov database shows a significant rise in clinical trials involving stem cells, many of which require reliable cryopreservation solutions to maintain cell viability throughout the study duration. Companies like Lonza and Cryoport provide cryopreservation services that support these clinical trials, underscoring the importance of cryopreservation in advancing cell-based therapies. This trend reflects the growing role of cryopreservation as an enabling technology for innovative treatment options.
Technological Advancements in Cryopreservation Techniques:
Advances in cryopreservation technology are enhancing the efficiency and reliability of cell storage. Innovations such as controlled-rate freezing and vitrification allow for improved cell viability post-thaw, which is crucial for therapeutic applications. Companies like Thermo Fisher Scientific and BioLife Solutions are developing cryopreservation media that minimize cell damage during the freezing process, catering to the evolving needs of biopharma and research institutions. The U.S. Food and Drug Administration (FDA) supports these advancements by approving products that enhance the safety and efficacy of cryopreserved cells, driving further adoption of these cutting-edge technologies in medical and research fields.
Market Trends
Expansion of Cryopreservation in Gene and Cell Therapy:
As gene and cell therapy gain prominence in treating genetic disorders and cancer, cryopreservation is becoming an essential component of these therapies. Cryopreservation enables the preservation of genetically modified cells, such as CAR-T cells, which are engineered to target cancer cells specifically. For example, companies like Novartis use cryopreservation techniques to store CAR-T cells, ensuring they remain viable from manufacturing through to patient administration. The Alliance for Regenerative Medicine notes that the demand for cell cryopreservation in gene therapy is expected to grow as new therapies receive regulatory approval, reflecting its critical role in cell-based treatments.
Increasing Use of Automated Cryopreservation Systems:
Automation is a growing trend in cell cryopreservation, as laboratories and biopharmaceutical companies seek to enhance consistency and precision in cell storage processes. Automated cryopreservation systems, such as those offered by BioLife Solutions, enable controlled-rate freezing and storage with minimal manual intervention, reducing the risk of human error and contamination. According to a report by the U.S. Food and Drug Administration (FDA), automation in cryopreservation also supports scalability, making it easier for facilities to expand their storage capabilities as the demand for cryopreserved cells increases.
Development of Specialized Cryoprotective Agents:
Cryoprotective agents (CPAs) are integral to cell cryopreservation, as they prevent cell damage during freezing. Recent advancements focus on developing CPAs that reduce toxicity while maintaining cell viability. For instance, alternative CPAs like hydroxyethyl starch (HES) are being researched for their ability to protect cells without the drawbacks associated with traditional agents like dimethyl sulfoxide (DMSO). Companies such as Thermo Fisher Scientific are exploring formulations that enhance post-thaw viability, supporting more effective recovery of cells. This trend is reflected in ongoing studies supported by the National Institutes of Health (NIH), which emphasize safer and more effective cryoprotectants for clinical and research applications.
Growing Focus on Sustainable and Energy-Efficient Solutions:
As environmental concerns rise, the cryopreservation market is seeing a shift toward more sustainable and energy-efficient solutions. Advances in cryostorage equipment aim to reduce energy consumption and carbon emissions, supporting laboratories in achieving sustainability goals. Companies like Brooks Life Sciences have introduced energy-efficient freezers designed for ultra-low temperature storage with a reduced environmental footprint. Additionally, green cryopreservation initiatives are gaining traction, with research institutions exploring ways to minimize energy usage in cryostorage, a trend supported by global efforts to promote sustainable laboratory practices.
Market Challenges Analysis:
High Costs of Cryopreservation Infrastructure and Consumables:
The cell cryopreservation market faces significant cost-related challenges, particularly due to the high expenses associated with cryostorage infrastructure and specialized consumables. Establishing and maintaining ultra-low temperature freezers and liquid nitrogen tanks requires substantial capital investment, which can be prohibitive for smaller research institutions and startups. Moreover, the ongoing costs of cryoprotective agents and single-use storage containers add to operational expenses. According to the National Institutes of Health (NIH), financial constraints often limit the adoption of advanced cryopreservation technologies, especially in low-resource settings, impacting the accessibility of cell preservation solutions.
Technical Complexity and Cell Viability Concerns:
Cryopreservation requires precise protocols to ensure cell viability post-thaw, and even minor deviations in temperature or timing can lead to cell damage. Techniques like controlled-rate freezing are essential to maintain cell integrity, yet these require specialized knowledge and equipment, making the process complex. Additionally, traditional cryoprotective agents, such as dimethyl sulfoxide (DMSO), can have cytotoxic effects, impacting cell viability and functionality after thawing. Regulatory bodies like the U.S. Food and Drug Administration (FDA) mandate stringent standards for cryopreserved cells used in therapeutic applications, further complicating compliance and operational challenges for biobanks and cell therapy providers.
Stringent Regulatory Requirements and Compliance Costs:
The regulatory landscape for cell cryopreservation is stringent, especially in therapeutic applications, where compliance with agencies like the FDA and the European Medicines Agency (EMA) is mandatory. These agencies enforce rigorous standards for the storage, transportation, and handling of cryopreserved cells to ensure safety and efficacy. Compliance with these regulations necessitates thorough documentation, validation of cryopreservation protocols, and adherence to Good Manufacturing Practices (GMP). Meeting these regulatory requirements can lead to increased operational costs and resource allocation, posing a challenge for companies and research organizations in maintaining compliance while ensuring cost efficiency.
Limited Awareness and Accessibility in Emerging Markets:
In emerging markets, the adoption of cell cryopreservation technology is often hampered by limited awareness and access to advanced cryopreservation solutions. Many healthcare facilities and research institutions in these regions lack the necessary infrastructure and technical expertise to implement cryopreservation protocols effectively. This disparity creates a barrier to the global expansion of cell cryopreservation applications, as low awareness and inadequate infrastructure restrict the development of biobanking and regenerative medicine in underserved areas.
Market Segmentation Analysis:
By Type The cell cryopreservation market is segmented by type into cryopreservation media and equipment. Cryopreservation media, which includes cryoprotective agents and storage solutions, is essential for preserving cell viability during freezing and storage. This segment is critical for both research and clinical applications, as it protects cells from ice damage during cryostorage. Equipment, such as ultra-low temperature freezers and liquid nitrogen tanks, facilitates the long-term storage of biological materials. The demand for advanced cryopreservation equipment continues to grow as biobanks, research institutions, and clinical facilities prioritize reliable storage solutions to support regenerative medicine and cellular therapies.
By Technology Cryopreservation technology is divided into controlled-rate freezing and vitrification. Controlled-rate freezing is the most widely used method, allowing cells to be cooled at a precise rate to prevent ice formation and minimize cell damage. This technology is commonly employed in the storage of stem cells, blood cells, and tissue samples. Vitrification, which involves ultra-rapid freezing to form a glass-like state, is gaining traction, especially for preserving cells highly sensitive to ice formation, such as embryos and oocytes. As advancements in cryopreservation technology continue, the choice of method is increasingly tailored to specific cell types and applications.
By End User End users of cell cryopreservation include biobanks, pharmaceutical & biotechnology companies, and research & academic institutions. Biobanks hold the largest share, as they store a wide variety of cell types for clinical and research purposes, including stem cells, immune cells, and cancer cells. Pharmaceutical and biotechnology companies use cryopreservation to maintain cell lines and support the development of cell-based therapies. Research and academic institutions rely on cryopreservation for fundamental research, particularly in fields like genetics and regenerative medicine, where cell integrity is crucial for experimental reliability and reproducibility. This segmentation highlights the essential role of cryopreservation across diverse sectors, supporting innovation in healthcare and biotechnology.
Segmentations:
- By Product Type
- Cryoprotectant Agents
- Glycerol
- Dimethyl Sulfoxide (DMSO)
- Others
- Equipment
- Incubators
- Liquid Nitrogen Supply Tanks
- Freezers
- Others
- Cryoprotectant Agents
- By Application
- Stem Cells
- Oocytes and Embryotic cells
- Sperm Cells
- Hepatocytes
- Others
- By End User
- Biopharmaceutical & Pharmaceutical Companies
- Research Institutes
- Biobanks
- IVF clinics
- Others
- By Region:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- North America
Regional Analysis:
North America North America leads the cell cryopreservation market, holding an estimated 40.2% share in 2024. The United States, in particular, is a major contributor, driven by a strong biopharmaceutical sector and advanced research infrastructure. Extensive investments in regenerative medicine and cell-based therapies fuel demand for reliable cryopreservation solutions, as these applications require high-quality storage to maintain cell viability. The U.S. also benefits from favorable regulatory frameworks and substantial government funding that support both academic and commercial research initiatives in cell preservation. Additionally, the region’s leading position is reinforced by the presence of major players, such as Thermo Fisher Scientific and BioLife Solutions, who continue to innovate within this field.
Europe Europe represents a significant portion of the cell cryopreservation market, with countries like Germany, the United Kingdom, and France leading in adoption. The European market is primarily driven by advancements in biobanking and regenerative medicine, supported by strong healthcare policies that encourage cell-based research and innovation. The European Medicines Agency (EMA) has established stringent guidelines for cell therapy applications, which contribute to the growth of cryopreservation technologies as they ensure cell integrity and compliance. Additionally, Europe’s commitment to stem cell research, backed by various government-funded initiatives, further boosts the demand for advanced cryopreservation equipment and consumables.
Asia-Pacific The Asia-Pacific region is projected to be the fastest-growing market, with an increasing focus on biopharmaceutical manufacturing and regenerative medicine. Countries such as China, Japan, and India are expanding their capabilities in life sciences, supported by government initiatives and rising healthcare investments. China’s “Made in China 2025” initiative, for instance, encourages advancements in biotechnology, including cell cryopreservation. Additionally, the region’s rapidly growing population and the corresponding rise in demand for personalized medicine propel investments in biobanking and cellular therapies. Local companies are also collaborating with international players to enhance technical expertise and cryopreservation infrastructure.
Latin America and the Middle East & Africa Latin America and the Middle East & Africa hold smaller shares of the market but are experiencing gradual growth. In Latin America, Brazil and Mexico are expanding their biopharmaceutical sectors, supported by government efforts to improve healthcare access. Cryopreservation is increasingly used in fertility clinics and research institutions as awareness of cell-based therapies grows. In the Middle East, countries like Saudi Arabia and the UAE are investing in healthcare modernization and adopting advanced cryopreservation techniques for stem cell banking and regenerative medicine. These regions are expected to see rising adoption as they develop infrastructure to support biobanking and cell-based applications.
Key Player Analysis:
- Thermo Fisher Scientific, Inc.
- Merck KGaA
- Sartorius AG
- BioLife Solutions, Inc.
- Lonza Group Ltd.
- Corning Incorporated
- Danaher Corporation
- Eppendorf SE
- PromoCell GmbH
- HiMedia Laboratories Pvt. Ltd.
Competitive Analysis:
The cell cryopreservation market is moderately competitive, led by key players such as Thermo Fisher Scientific, Merck KGaA, and BioLife Solutions, which hold substantial market shares due to their comprehensive product offerings and extensive distribution networks. These companies leverage advanced cryopreservation technologies, including specialized media and automated storage systems, to maintain a competitive edge. Additionally, they focus on research and development to improve cell viability and storage efficiency, catering to the growing demand in biobanking, regenerative medicine, and cell therapy sectors. Other players like Lonza and Sartorius emphasize partnerships and acquisitions to expand their portfolios and address the increasing needs of the pharmaceutical and biotechnology industries. Smaller companies, such as PromoCell and HiMedia Laboratories, compete by offering specialized and cost-effective cryopreservation solutions for research institutions. Overall, the market is driven by innovation, with companies striving to meet high standards for cell integrity and regulatory compliance across diverse applications.
Recent Developments:
- In August 2023, Thermo Fisher Scientific launched the TSV series of laboratory refrigerators and freezers, which includes ultra-low temperature freezers designed for cryopreservation. This product line, developed with the “Made in India” initiative, provides enhanced temperature uniformity and stability, which is crucial for maintaining cell viability in long-term storage. This expansion aligns with Thermo Fisher’s goal to support local manufacturing while catering to global cryopreservation needs.
- In June 2023, BioLife Solutions unveiled its IntelliRate i67C, a large-capacity controlled-rate freezer aimed at supporting high-volume cell therapy production. This product addition addresses growing customer demands for scalable cryopreservation solutions, particularly in commercial cell therapy applications. This freezer enhances the company’s ability to offer robust storage solutions that maintain cell viability throughout the production and storage process.
- Sartorius AG expanded its cell cryopreservation capabilities by acquiring Polyplus in July 2023. This acquisition allows Sartorius to broaden its focus on adjacent technologies such as plasmid design and manufacturing, which are integral to gene therapy and gene-modified cell therapies. This strategic move positions Sartorius to better serve the needs of advanced cell and gene therapy markets through comprehensive cryopreservation and bioprocessing solutions.
- In 2022, Lonza introduced optimized cryopreservation protocols and cryoprotective agents specifically tailored for cell therapy applications, including CAR-T cells. These innovations were developed to address the unique needs of cell therapies that require stringent preservation conditions to maintain cell integrity and functionality. This development reflects Lonza’s commitment to advancing cryopreservation technologies that support the growing demand in cell-based therapeutic applications.
Market Concentration & Characteristics:
The cell cryopreservation market is moderately concentrated, with leading players such as Thermo Fisher Scientific, Merck KGaA, and BioLife Solutions dominating due to their extensive portfolios, advanced cryopreservation technologies, and well-established global distribution networks. These companies focus on providing high-quality cryopreservation media, ultra-low temperature freezers, and automated storage solutions that cater to diverse applications in biobanking, regenerative medicine, and cell therapy. The market is characterized by significant R&D investments aimed at improving cell viability post-thaw, with innovations in cryoprotective agents and controlled-rate freezing technologies. Additionally, the sector is shaped by strict regulatory standards from agencies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), ensuring that cryopreservation products meet rigorous safety and efficacy requirements. The increasing demand for personalized medicine and cell-based therapies further intensifies competition, as companies strive to develop solutions that support both research and clinical applications in advanced cell storage.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for cell cryopreservation solutions will continue to rise as regenerative medicine and cell therapy applications expand.
- Technological advancements, such as the development of controlled-rate freezing and vitrification techniques, will enhance post-thaw cell viability and support broader therapeutic applications.
- The market will see increased adoption of automated cryopreservation systems, allowing for enhanced efficiency and consistency in biobanking and clinical settings.
- Cryopreservation for gene and cell therapy applications, including CAR-T and stem cell therapies, will grow, driven by the rising number of clinical trials and FDA approvals for cell-based treatments.
- Emerging markets in Asia-Pacific and Latin America will experience rapid growth, supported by government initiatives to boost biopharmaceutical infrastructure and research capabilities.
- Environmental sustainability will gain importance, encouraging companies to develop energy-efficient freezers and explore eco-friendly cryoprotective agents.
- Companies will likely invest in strategic partnerships and acquisitions to expand their cryopreservation technology portfolios and address specific market demands for regenerative medicine and personalized therapies.
- The biobanking segment will grow, as researchers increasingly recognize the value of preserved cells in studying disease mechanisms and developing new treatments.
- Regulatory agencies will continue to set high standards for cryopreservation protocols, particularly for clinical applications.
- Cryopreservation will play an essential role in advancing precision medicine, enabling the long-term storage of genetically modified cells.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the cell cryopreservation market?
What factors are driving the growth of the cell cryopreservation market?
What are some challenges faced by the cell cryopreservation market?
Who are the major players in the cell cryopreservation market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cell Cryopreservation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cell Cryopreservation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 10107 million → forecast year: USD 51,925.27 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cell Cryopreservation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cell Cryopreservation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cell Cryopreservation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cell Cryopreservation Market Drivers
- 3.3 Cell Cryopreservation Market Restraints & Challenges
- 3.4 Cell Cryopreservation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cell Cryopreservation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cell Cryopreservation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cell Cryopreservation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cell Cryopreservation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cell Cryopreservation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cell Cryopreservation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cell Cryopreservation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cell Cryopreservation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cell Cryopreservation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cell Cryopreservation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cell Cryopreservation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cell Cryopreservation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cell Cryopreservation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cell Cryopreservation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cell Cryopreservation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cell Cryopreservation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cell Cryopreservation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cell Cryopreservation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cell Cryopreservation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
