
Market Overview
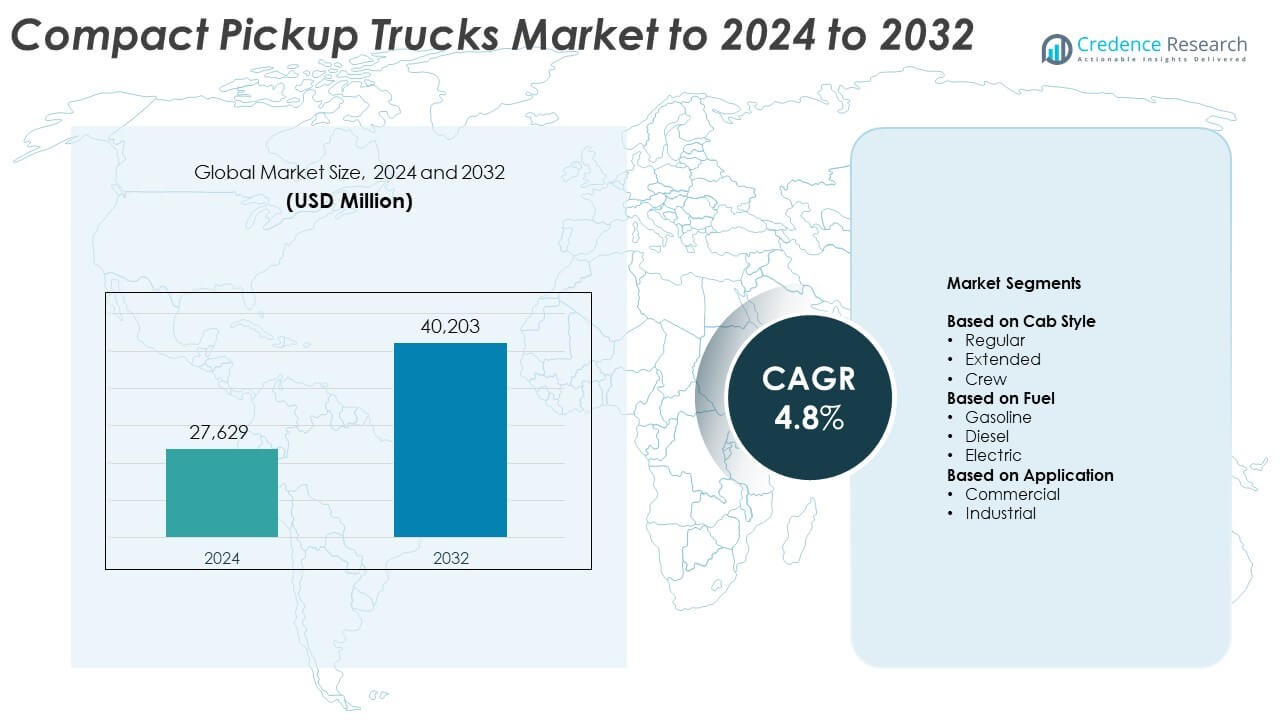
The Compact Pickup Trucks Market size was valued at USD 27,629 million in 2024 and is anticipated to reach USD 40,203 million by 2032, at a CAGR of 4.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Compact Pickup Trucks Market Size 2024 | USD 27,629 Million |
| Compact Pickup Trucks Market, CAGR | 4.8% |
| Compact Pickup Trucks Market Size 2032 | USD 40,203 Million |
The compact pickup trucks market is led by major players such as Ford Motor Company, Toyota Motor Corporation, General Motors Company, Hyundai Motor Corporation, and Tata Motors. These companies maintain a strong presence through extensive product portfolios, technological innovation, and global distribution networks. North America emerged as the leading region with a 55% market share in 2024, driven by high consumer demand and strong fleet adoption. Asia Pacific followed with a 22% share, supported by expanding urban infrastructure and growing small-business operations. Europe accounted for 18%, fueled by hybrid adoption and emission-compliant models.
Market Insights
- The compact pickup trucks market was valued at USD 27,629 million in 2024 and is projected to reach USD 40,203 million by 2032, growing at a CAGR of 4.8% during the forecast period.
- Rising demand for versatile, fuel-efficient vehicles for both personal and commercial use is a key driver of market growth.
- Electrification, advanced safety systems, and connectivity integration are emerging trends reshaping the design and performance of compact pickups.
- The market remains highly competitive, with global automakers focusing on hybrid and electric models to meet emission standards and consumer preferences.
- North America led with a 55% share in 2024, followed by Asia Pacific with 22% and Europe with 18%; among segments, the crew cab and gasoline categories dominated due to comfort, practicality, and wide infrastructure availability.
Market Segmentation Analysis:
By Cab Style
The crew cab segment dominated the compact pickup trucks market with a 47.2% share in 2024. Crew cabs are favored for their spacious interiors, four full-sized doors, and enhanced comfort for family and business use. The growing preference for lifestyle-oriented vehicles and multi-purpose usage in both personal and commercial settings supports this dominance. Automakers are expanding crew cab variants with advanced infotainment, driver-assistance systems, and ergonomic designs to attract younger buyers seeking performance and utility balance.
- For instance, the Hyundai Santa Cruz is available exclusively in a crew-cab configuration with four doors and a five-passenger seating capacity. The truck has an overall length of 195.7 inches and a curb-to-curb turning diameter of 39.6 feet.
By Fuel
The gasoline segment held the largest share of 61.5% in 2024, driven by the broad availability of fueling infrastructure and lower initial vehicle costs. Gasoline-powered compact pickups offer strong performance and are more suited for light-duty applications compared to diesel variants. Manufacturers are improving fuel efficiency with turbocharged engines and hybrid gasoline systems. However, the electric segment is gaining momentum as governments promote zero-emission vehicles and brands like Ford and Rivian launch compact EV pickups.
- For instance, the Chevrolet Montana's 1.2-turbo engine returns an INMETRO-rated 12.3 km/L in the city and 13.7 km/L on the highway when running on gasoline (with an automatic transmission), which highlights its competitive fuel efficiency.
By Application
The commercial segment led the compact pickup trucks market with a 58.4% share in 2024. Businesses prefer compact pickups for their affordability, fuel efficiency, and ease of maneuverability in urban areas. They are widely used for small-scale logistics, service fleets, and utility operations. Growth in e-commerce deliveries and last-mile transportation has increased demand for compact pickups. Companies are introducing customizable cargo solutions and telematics to enhance fleet performance and reduce operational costs.
Key Growth Drivers
Rising Urban Demand for Versatile Vehicles
Compact pickup trucks are gaining popularity among urban consumers seeking multipurpose vehicles for both personal and light commercial use. Their smaller dimensions and improved fuel efficiency make them ideal for navigating congested city environments. Automakers are introducing flexible seating and storage designs to appeal to users who need daily commuting convenience and cargo capability. The growing adoption among small businesses and individual contractors continues to strengthen the segment’s expansion globally.
- For instance, Ford Maverick’s length is 199.7 inches. Its turning circle is 40.0 feet. Compact size eases urban parking and deliveries.
Technological Advancements and Electrification
Manufacturers are increasingly focusing on integrating advanced technology and electrification into compact pickup models. Features like adaptive cruise control, lane-keeping systems, and connected infotainment platforms enhance safety and comfort. The transition toward hybrid and fully electric models aligns with global emission-reduction goals, boosting consumer interest. Government incentives and expanding charging networks further support adoption, creating a favorable environment for long-term growth.
- For instance, Toyota Tacoma i-FORCE MAX produces 326 horsepower. Peak torque reaches 465 lb-ft. The hybrid pairs a 2.4-liter turbo with a 48-hp motor.
Expanding Small Business and E-commerce Operations
The rise of e-commerce and small-scale delivery services drives strong demand for compact pickups due to their cost efficiency and maneuverability. Businesses prefer these vehicles for urban logistics, maintenance, and transportation of light goods. Their lower ownership costs and improved payload capacity make them attractive for fleet operators. As delivery networks expand in emerging economies, compact pickups continue to play a critical role in last-mile logistics growth.
Key Trends and Opportunities
Growing Adoption of Electric Compact Pickups
Electric compact pickup models are becoming a significant opportunity area as automakers diversify powertrain portfolios. The adoption is supported by stricter emission standards and advancements in battery technology, extending range and performance. Companies are developing lightweight platforms optimized for electric propulsion, enhancing energy efficiency. Expanding government incentives and consumer interest in sustainable mobility are expected to further accelerate the shift toward electric variants.
- For instance, the 2025 Rivian R1T Dual-Motor with the Max battery pack offers an EPA-rated range of up to 410 miles (with 21-inch wheels), reflecting updated specifications for the vehicle.
Increased Customization and Premiumization
Consumers are showing a growing interest in customized and premium compact pickup models equipped with advanced interiors and connectivity features. Automakers are offering luxury-oriented trims, smart infotainment, and off-road packages to attract lifestyle buyers. This trend supports higher profitability while catering to diverse consumer needs. As customers prioritize comfort and design alongside utility, premium compact pickups are emerging as a key growth segment in developed markets.
- For instance, the GMC Canyon AT4X AEV has a 1.5-inch additional lift compared to the standard AT4X (resulting in a total 4.5-inch factory lift over the base model). With its 35-inch tires, ground clearance reaches 12.2 inches. It uses Multimatic DSSV dampers and boron-steel skid plates.
Key Challenges
High Production and Maintenance Costs
The integration of advanced electronics, emission systems, and lightweight materials increases production costs for compact pickup trucks. Manufacturers face challenges in maintaining competitive pricing while ensuring high performance and safety standards. Maintenance expenses also rise with the addition of complex onboard systems, impacting overall ownership costs. These factors can limit adoption, especially in price-sensitive regions.
Competition from SUVs and Mid-size Trucks
Compact pickups face strong competition from compact SUVs and mid-size trucks offering similar features with added comfort or capacity. Consumers often view SUVs as more versatile family vehicles, reducing the appeal of compact trucks. Additionally, automakers are prioritizing mid-size models for higher margins and broader market presence. This competition pressures compact pickup manufacturers to differentiate through design innovation and efficiency improvements.
Regional Analysis
North America North America held approximately 55% share of the compact pickup trucks market in 2024. Demand stayed strong from retail buyers and small fleets. Urban delivery and lifestyle use supported steady orders. Localized manufacturing and wide dealer networks improved availability and service. Feature-rich crew cabs and gasoline powertrains remained popular choices. Hybrids gained traction in city fleets. Regulatory stability and healthy financing aided renewals and new purchases. Telematics adoption improved fleet uptime and cost control.
Europe
Europe accounted for about 18% share in 2024. Buyers favored efficient, multi-purpose models for mixed personal and business use. Emission rules encouraged lighter platforms and electrified variants. OEMs tailored trims, safety tech, and ride comfort to regional roads. Expansion of light commercial services in major cities lifted demand. Dealer incentives supported small-business purchases. Hybrid options entered municipal and utility fleets. Supply chain normalization improved delivery times across core markets.
Asia Pacific
Asia Pacific captured roughly 22% share in 2024. Rapid urbanization and growing SMEs boosted light-duty haulage needs. Thailand, Indonesia, and India showed solid retail and fleet uptake. Local production and component sourcing improved price competitiveness. Governments promoted cleaner powertrains, aiding hybrid introductions. E-commerce growth increased last-mile requirements. Road upgrades supported intercity operations for compact beds. New model launches targeted value buyers with connected features.
Latin America
Latin America represented about 3% share in 2024. Buyers valued low running costs and agility on mixed roads. Agriculture, utilities, and small traders drove steady orders. New entrants added competitive trims and safety bundles. Financing programs and improved parts logistics supported retention. Hybrid introductions started in a few metros. Regional assembly and imports balanced availability. Currency swings moderated pricing strategies and promotions.
Middle East & Africa
Middle East & Africa accounted for around 2% share in 2024. Demand came from construction, mining services, and municipal fleets. Compact models appealed as cost-effective alternatives to larger trucks. Growth concentrated in South Africa, UAE, and Saudi Arabia. Dealers expanded service packages for harsh environments. Emerging assembly projects improved supply resilience. Fleet buyers emphasized durability and payload within city limits. Electrified offerings began pilot deployments in select fleets.
Market Segmentations:
By Cab Style
- Regular
- Extended
- Crew
By Fuel
- Gasoline
- Diesel
- Electric
By Application
- Commercial
- Industrial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The compact pickup trucks market features strong competition among major automakers such as Ford Motor Company, Tata Motors, Hyundai Motor Corporation, Nissan Motor Co. Ltd., Ashok Leyland, Toyota Motor Corporation, General Motors Company, Dongfeng Motor Corporation, Honda Motor Co., Ltd., and China FAW Group Corp., Ltd. Market participants are focusing on introducing fuel-efficient and hybrid variants to meet tightening emission norms. Continuous investments in advanced safety systems, connectivity features, and lightweight chassis are reshaping product offerings. Manufacturers are expanding production capacity in emerging markets to reduce costs and address growing regional demand. Partnerships with battery suppliers and technology firms are strengthening the shift toward electric models. Companies are also diversifying product lines with premium trims, customizable interiors, and enhanced off-road performance. This competitive environment encourages consistent innovation, with firms leveraging digital marketing and fleet services to capture both commercial and lifestyle-driven consumer segments globally.
Key Player Analysis
- Ford Motor Company
- Tata Motors
- Hyundai Motor Corporation
- Nissan Motor Co. Ltd.
- Ashok Leyland
- Toyota Motor Corporation
- General Motors Company
- Dongfeng Motor Corporation
- Honda Motor Co., Ltd.
- China FAW Group Corp., Ltd.
Recent Developments
- In 2025, Ashok Leyland continued its strategic focus on the Light Commercial Vehicle (LCV) segment, which includes compact trucks like the Dost, Bada Dost, and the new Saathi.
- In August 2025, Ford announced plans to produce a new line of affordable electric vehicles on a "Universal EV Platform".
- In 2023, Toyota unveiled the EPU concept (Electric PickUp) at the Japan Mobility Show.
Report Coverage
The research report offers an in-depth analysis based on Cab Style, Fuel, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth driven by rising urban demand for multipurpose vehicles.
- Automakers will focus on expanding electric and hybrid compact pickup lineups.
- Integration of advanced driver-assistance and connectivity features will become standard.
- Lightweight materials and modular platforms will improve efficiency and performance.
- Fleet electrification and government emission goals will boost adoption across logistics sectors.
- Customization options and premium variants will attract lifestyle and adventure users.
- Emerging economies in Asia-Pacific will continue to lead global production and sales.
- Partnerships between automakers and tech firms will enhance telematics and smart fleet management.
- Aftermarket services and digital platforms will expand for maintenance and tracking.
- Increasing competition from compact SUVs will push manufacturers toward innovation and differentiation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Compact Pickup Trucks Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Compact Pickup Trucks Market projected to grow between 2025 and 2032?
Which Compact Pickup Trucks Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Compact Pickup Trucks Market?
Who are the leading companies in the Compact Pickup Trucks Market?
Which region commanded the largest share of the Compact Pickup Trucks Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 27,629 million → 2032: USD 40,203 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Compact Pickup Trucks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Compact Pickup Trucks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Compact Pickup Trucks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Compact Pickup Trucks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Compact Pickup Trucks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Compact Pickup Trucks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Compact Pickup Trucks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Compact Pickup Trucks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 27,629 million → 2032: USD 40,203 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Compact Pickup Trucks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Compact Pickup Trucks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Compact Pickup Trucks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Compact Pickup Trucks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

