
Market Overview
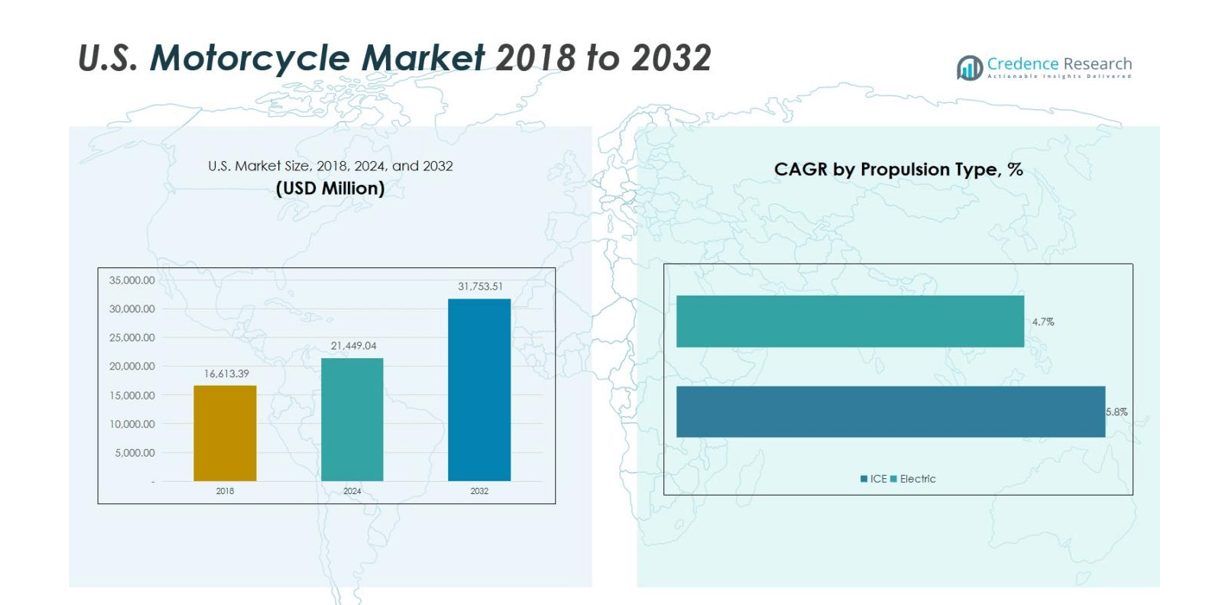
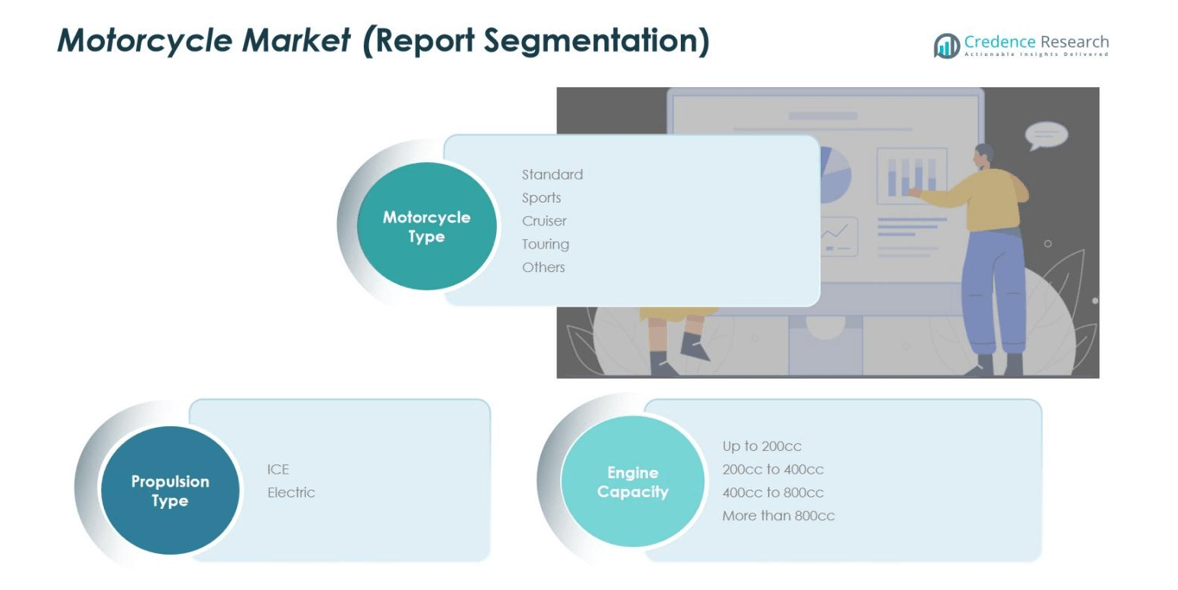
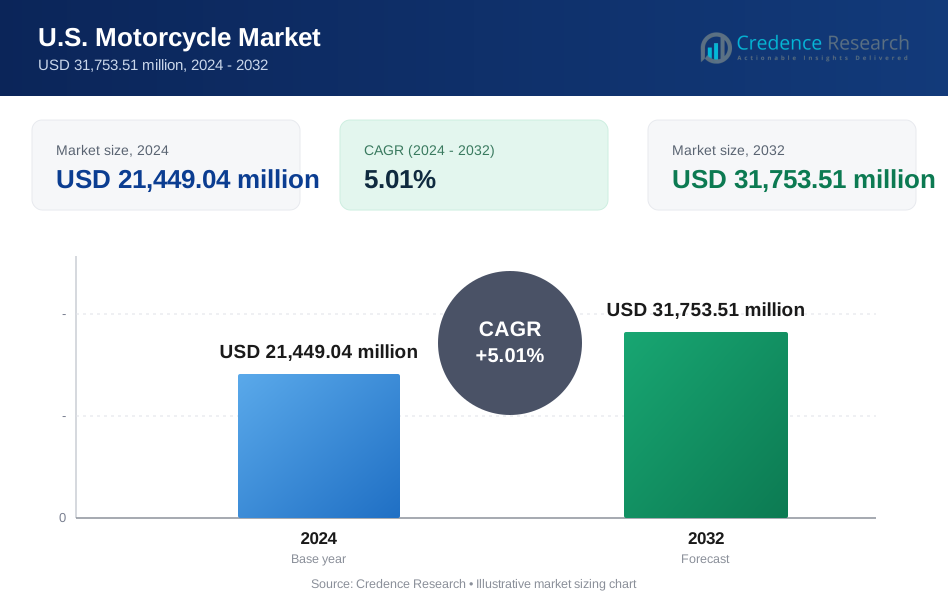
The U.S. Motorcycle Market size was valued at USD 16,613.39 million in 2018, growing to USD 21,449.04 million in 2024, and is anticipated to reach USD 31,753.51 million by 2032, at a CAGR of 5.01% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Motorcycle Market Size 2024 | USD 21,449.04 million |
| U.S. Motorcycle Market, CAGR | 5.01% |
| U.S. Motorcycle Market Size 2032 | USD 31,753.51 million |
The U.S. Motorcycle Market is dominated by key players such as Harley-Davidson, Polaris Inc., Yamaha Motor Co., Suzuki Motor Corporation, BMW AG, Honda Motor Co., Kawasaki Motors Corp., and Zero Motorcycles Inc. These companies lead through extensive product portfolios, innovation, and strong brand recognition across diverse segments. Harley-Davidson continues to hold a commanding position in the cruiser and touring categories, while Japanese manufacturers such as Yamaha, Honda, and Suzuki maintain dominance in sports and standard motorcycles. Zero Motorcycles is expanding rapidly within the electric segment through continuous advancements in battery efficiency. Regionally, the Western United States leads the market with a 36% share, driven by favorable weather conditions, scenic riding routes, and a strong culture of motorcycle tourism.
Market Insights
- The U.S. Motorcycle Market was valued at USD 21,449.04 million in 2024 and is expected to reach USD 31,753.51 million by 2032, growing at a CAGR of 5.01% during the forecast period.
- Market growth is primarily driven by rising consumer interest in recreational and touring activities, technological advancements, and the increasing availability of electric motorcycles supported by sustainability initiatives.
- A key trend shaping the market is the growing adoption of connected and smart motorcycles equipped with advanced safety and infotainment systems, appealing to younger and tech-oriented riders.
- The competitive landscape features leading players such as Harley-Davidson, Polaris Inc., Yamaha Motor Co., Suzuki Motor Corporation, and Zero Motorcycles Inc., focusing on product innovation and electrification.
- Regionally, the Western United States holds the largest share at 36%, while the standard motorcycle segment dominates the market with a 41.5% revenue share, supported by affordability and versatility.
Market Segmentation Analysis:
By Motorcycle Type
The U.S. motorcycle market is segmented into Standard, Sports, Cruiser, Touring, and Others, with the Standard segment dominating at nearly 41.5% market share in 2024. Standard motorcycles lead due to their versatility, affordability, and comfort for both daily commuting and recreational use. The Cruiser segment follows closely, supported by strong demand for long-distance and classic-styled bikes from brands like Harley-Davidson. Meanwhile, Sports motorcycles are witnessing rising popularity among younger riders drawn to performance, speed, and advanced technology integration. Touring and Adventure models are also gaining traction due to the growing trend of leisure and cross-country riding.
- For instance, Harley-Davidson reported that its new Street Glide and Road Glide touring motorcycles contributed to a nearly 5% growth in the U.S. Touring segment and helped the brand achieve a 74.5% market share in that segment for 2024.
By Propulsion Type
Based on propulsion, the Internal Combustion Engine (ICE) segment holds a dominant 89% market share, driven by widespread fuel infrastructure, cost efficiency, and mature technology. However, the Electric motorcycle segment is the fastest-growing, fueled by advancements in battery range, government incentives, and sustainability goals. U.S. manufacturers such as Zero Motorcycles are expanding their electric portfolios to attract eco-conscious consumers. The ongoing transition toward electrification highlights growing awareness of green mobility and the government’s support for emission-free transportation.
- For instance, the collaboration between Hero MotoCorp and Zero Motorcycles to co-develop premium electric motorcycles, targeting the midweight performance segment with launches planned by FY2026.
By Engine Capacity
The U.S. market is divided into Up to 200cc, 200cc–400cc, 400cc–800cc, and Above 800cc categories. The 400cc–800cc segment dominates, accounting for a significant 38–40% share, as it offers a balance of performance, comfort, and affordability. This range is preferred by mid-level riders for both urban and highway use. The Above 800cc category contributes notably to revenue through premium touring and cruiser motorcycles, while lower-capacity models (below 400cc) cater to beginners and commuters seeking fuel-efficient options. The demand across all capacity ranges is reinforced by rising motorcycle ownership and lifestyle-driven purchases in the U.S.
Key Growth Drivers
Rising Demand for Recreational and Lifestyle Motorcycles
The increasing popularity of motorcycling as a leisure activity is a major driver in the U.S. market. Consumers are investing in high-performance and touring motorcycles for weekend rides and long-distance travel. Established brands such as Harley-Davidson and BMW Motorrad benefit from this lifestyle shift, introducing feature-rich models tailored for comfort and adventure. Growing interest in road trips, motorcycle rallies, and club culture continues to expand demand, particularly among middle-aged and affluent consumers seeking both style and recreational value.
- For instance, BMW Motorrad's R 1300 RT model comes equipped with integral ABS Pro, dynamic electronic suspension adjustment, and adaptive cruise control for safer, more comfortable touring experiences.
Technological Advancements and Product Innovation
Continuous innovation in motorcycle design, safety, and performance is fueling market expansion. Manufacturers are integrating advanced rider-assist technologies, digital connectivity, ABS, and traction control systems to enhance safety and experience. Electric motorcycles are also gaining traction due to improved battery efficiency and lower maintenance costs. These innovations attract tech-savvy and sustainability-conscious riders, while premium features such as adaptive cruise control and infotainment systems elevate consumer expectations, boosting the overall market appeal across multiple motorcycle categories.
- For instance, Bosch has developed radar-based rider assistance systems that monitor a motorcycle’s surroundings, providing blind spot detection and adaptive cruise control to automatically maintain a safe distance from vehicles ahead.
Expansion of Electric Motorcycle Segment
The rapid evolution of electric mobility represents a pivotal growth driver in the U.S. motorcycle market. Companies like Zero Motorcycles and Harley-Davidson’s LiveWire are leading this transformation with advanced electric models offering extended range and fast-charging capabilities. Government incentives, emission regulations, and expanding charging infrastructure are further accelerating adoption. As consumers increasingly prioritize environmental responsibility and operating cost savings, the electric motorcycle segment is poised to register substantial growth over the forecast period, reshaping the nation’s two-wheeler landscape.
Key Trends & Opportunities
Integration of Smart Connectivity and IoT Features
The adoption of smart connectivity and IoT technologies is emerging as a key trend in the U.S. motorcycle market. Manufacturers are integrating features such as GPS navigation, vehicle diagnostics, and smartphone connectivity to enhance rider convenience and safety. Real-time monitoring systems and app-based interfaces provide riders with data-driven insights into performance and maintenance. This digital transformation creates opportunities for manufacturers to differentiate their products, attract tech-oriented customers, and establish new revenue streams through connected services and subscription models.
- For instance, Harley-Davidson launched its LiveWire electric motorcycle with smart features including real-time performance tracking, customizable ride modes, and remote diagnostics appealing to tech-savvy riders.
Growing Market for Premium and Customized Motorcycles
An expanding segment of U.S. consumers is showing strong interest in premium and customized motorcycles. Riders are seeking exclusivity, performance, and personalization-driving demand for luxury cruisers, sport bikes, and custom builds. Brands like Indian Motorcycle and Ducati are capitalizing on this trend by offering bespoke options, performance upgrades, and limited-edition models. The shift toward high-value motorcycles not only boosts profitability but also encourages aftermarket growth, creating opportunities for accessory manufacturers and service providers in the customization ecosystem.
- For instance, Indian Motorcycle offers the 2025 Roadmaster Elite, a touring model limited to just 350 units worldwide, featuring exclusive paint schemes and luxury finishes.
Key Challenges
High Ownership and Maintenance Costs
One of the major challenges in the U.S. motorcycle market is the high cost of ownership and maintenance, particularly for premium and large-displacement models. Expenses related to insurance, spare parts, and servicing often deter potential buyers, especially younger demographics. Additionally, rising component and labor costs have led to higher retail prices. These factors restrict market penetration in the mid- to low-income segments, compelling manufacturers to explore cost-effective production techniques and flexible financing options to sustain demand.
Safety Concerns and Regulatory Barriers
Safety risks associated with motorcycle riding remain a critical concern influencing market growth. Increasing accident rates and limited protective infrastructure discourage potential riders. Furthermore, stringent emission norms and noise regulations challenge manufacturers to continually adapt engine technologies, adding to development costs. The lack of widespread training programs and inconsistent licensing standards across states exacerbate safety challenges. Addressing these issues through enhanced safety awareness, rider education, and technological advancements will be essential for long-term market sustainability.
Regional Analysis
Western United States
The Western region holds the largest market share of 36% in the U.S. motorcycle market, driven by favorable weather conditions, scenic routes, and a strong leisure-riding culture. States such as California and Arizona contribute significantly due to their year-round riding climate and high concentration of motorcycle enthusiasts. The region also leads in electric motorcycle adoption, supported by progressive emission policies and robust charging infrastructure. Major manufacturers and dealerships are expanding their presence here, capitalizing on strong consumer demand for both premium touring and eco-friendly electric motorcycles.
Southern United States
The Southern region accounts for 29% of the U.S. motorcycle market, fueled by the popularity of cruisers and touring motorcycles suited for long highway rides. States like Texas, Florida, and Georgia are key contributors due to extensive road networks, strong motorcycling communities, and numerous biking events. Favorable registration costs and relatively mild winters support consistent year-round usage. The region also shows rising interest in mid-range motorcycles, supported by a growing youth population and increasing affordability. These factors collectively sustain the South’s robust position in the national motorcycle landscape.
Midwestern United States
The Midwest captures a market share of 21%, characterized by steady demand for heavy and cruiser motorcycles. States such as Illinois, Ohio, and Michigan have strong motorcycle ownership bases and a growing aftermarket ecosystem. While the riding season is shorter due to climatic conditions, the region benefits from a dense network of dealerships and manufacturer operations. Local consumers display loyalty to iconic brands like Harley-Davidson, which originated in this region. Expanding availability of mid-size and adventure bikes further supports gradual market growth across both urban and semi-rural communities.
Northeastern United States
The Northeastern region represents 14% of the U.S. motorcycle market, with concentrated demand in states such as New York, Pennsylvania, and Massachusetts. Despite limited riding months, the region maintains a steady market through strong urban commuter interest and premium motorcycle sales. Rising adoption of electric and low-emission models aligns with the region’s environmental policies. The high-income consumer base supports the growth of luxury and performance motorcycles, while increasing urban congestion continues to drive interest in two-wheel mobility solutions, including compact and electric models for daily transportation.
Market Segmentations:
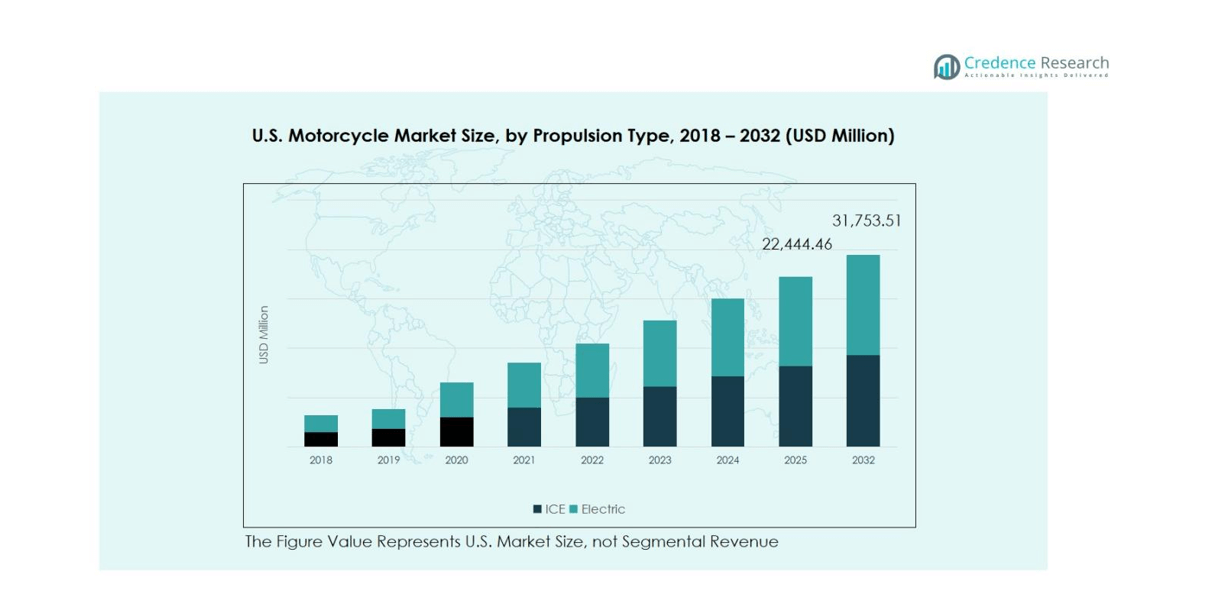
By Motorcycle Type
- Standard
- Sports
- Cruiser
- Touring
- Others
By Propulsion Type
- Internal Combustion Engine (ICE)
- Electric
By Engine Capacity
- Up to 200cc
- 200cc to 400cc
- 400cc to 800cc
- More than 800cc
By Region
- Western United States
- Southern United States
- Midwestern United State
- Northeastern United States
Competitive Landscape
The competitive landscape of the U.S. motorcycle market is defined by the presence of major players such as Harley-Davidson, Polaris Inc., Yamaha Motor Co., Suzuki Motor Corporation, BMW AG, Honda Motor Co., Kawasaki Motors Corp., and Zero Motorcycles Inc. These companies collectively shape market dynamics through product innovation, brand loyalty, and extensive dealership networks. Harley-Davidson continues to dominate the premium cruiser and touring segments, while Polaris, through its Indian Motorcycle brand, focuses on heritage and performance models. Japanese manufacturers such as Yamaha, Suzuki, and Kawasaki maintain strong positions in sports and standard categories, emphasizing affordability and reliability. Meanwhile, BMW and Honda drive technological advancement with luxury and adventure motorcycles. The growing electric segment is led by Zero Motorcycles and Harley-Davidson’s LiveWire division, both investing heavily in battery technology and range improvement. Competitive intensity remains high, with brands pursuing electrification, connectivity, and premiumization to strengthen market presence and customer engagement.
Key Player Analysis
- Polaris Inc.
- TVS Motor Company Ltd.
- Bajaj Auto Ltd.
- Yamaha Motor Co.
- Suzuki Motor Corporation
- Zero Motorcycles Inc.
- Bayerische Motoren Werke (BMW) AG
- Harley-Davidson, Inc.
- Piaggio Group
- Kawasaki Motors Corp.
- Other Key Players
Recent Developments
- In August 2025, Harley-Davidson, Inc. achieved a major milestone by completing its strategic partnership with KKR and PIMCO, finalizing the sale of over USD 230 million in residual interests in securitized consumer loan receivables to strengthen its financial services operations.
- In October 2025, Polaris Inc. announced its plan to separate the Indian Motorcycle brand into an independent company by selling a majority stake to Carolwood LP, aiming to enhance profitability and focus on core business segments.
- In October 2025, Siemens Digital Industries Software extended its long-term partnership with Ducati Motor Holding S.p.A., focusing on advancing digital innovation, simulation technology, and sustainable manufacturing practices within the motorcycle industry.
- In October 2025, LiveWire Group Inc. showcased its upcoming S2 Alpinista Corsa and Patrol electric models production begins spring 2026 underscoring its expansion in the U.S. electric motorcycle segment.
Report Coverage
The research report offers an in-depth analysis based on Motorcycle Type, Propulsion Type, Engine Capacity and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. motorcycle market is expected to witness steady growth driven by rising recreational and touring activities.
- Electric motorcycles will gain strong traction due to stricter emission norms and government incentives.
- Premium and customized motorcycles will continue to attract affluent consumers seeking personalized experiences.
- Advancements in battery technology will enhance range and reduce charging time for electric models.
- Integration of smart connectivity and safety features will become standard across new motorcycle models.
- Manufacturers will expand mid-capacity motorcycle offerings to attract younger and urban riders.
- Expanding dealership networks and online sales channels will improve market accessibility.
- The growing popularity of motorcycle clubs and road tourism will support long-distance bike sales.
- Sustainability and eco-conscious consumer behavior will shape future product development strategies.
- Strategic collaborations and product diversification will remain key for companies to maintain competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the U.S. Motorcycle Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Motorcycle Market projected to grow between 2025 and 2032?
Which U.S. Motorcycle Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Motorcycle Market?
Who are the leading companies in the U.S. Motorcycle Market?
Which region commanded the largest share of the U.S. Motorcycle Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,449.04 million → 2032: USD 31,753.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Motorcycle Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Motorcycle Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Motorcycle Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Motorcycle Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Motorcycle Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Motorcycle Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Motorcycle Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Motorcycle Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,449.04 million → 2032: USD 31,753.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Motorcycle Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Motorcycle Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Motorcycle Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Motorcycle Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

