
Market Overview
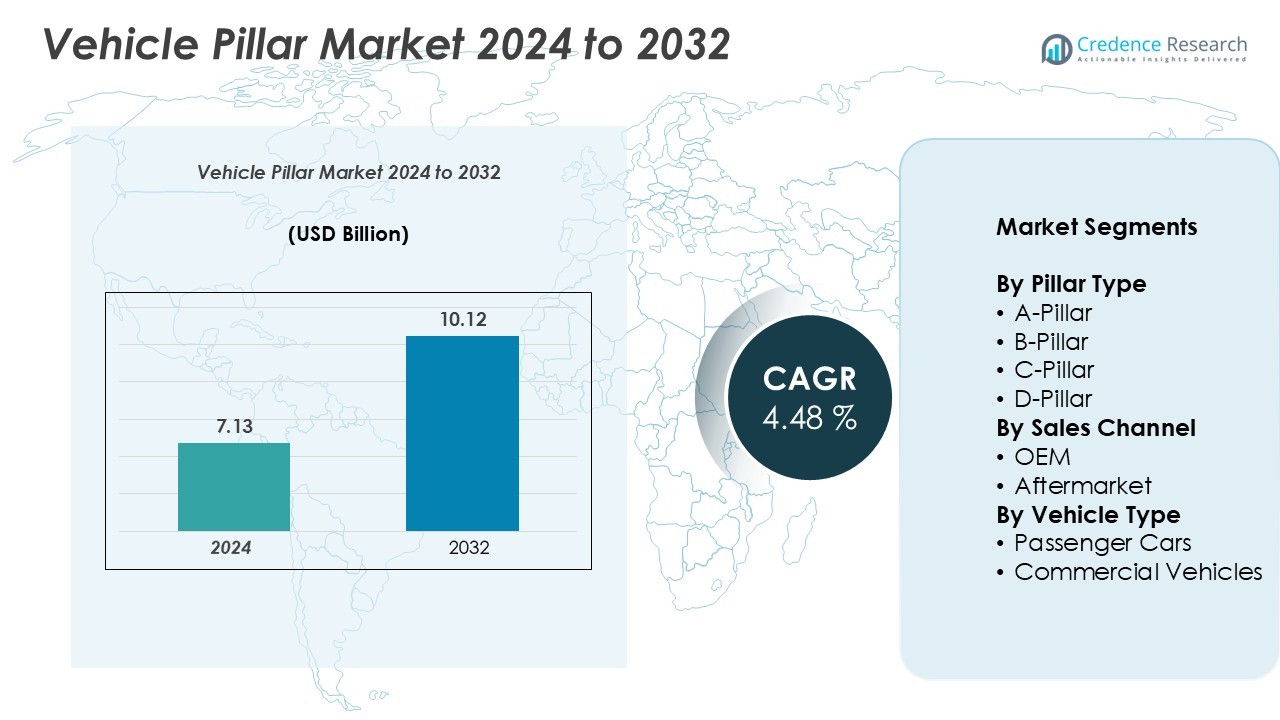
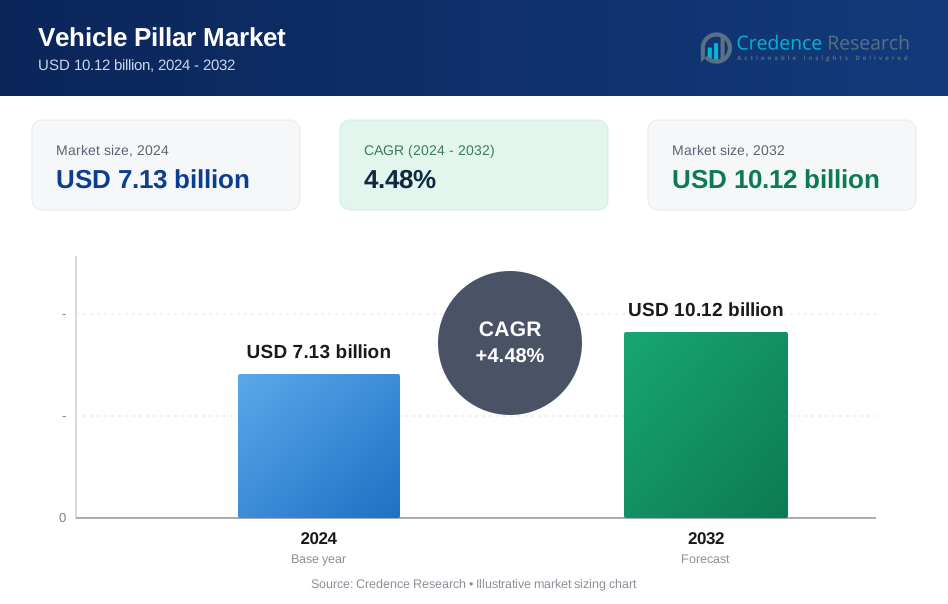
The Vehicle Pillar Market size was valued at USD 7.13 billion in 2024 and is anticipated to reach USD 10.12 billion by 2032, at a CAGR of 4.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vehicle Pillar Market Size 2024 | USD 7.13 Billion |
| Vehicle Pillar Market , CAGR | 4.48% |
| Vehicle Pillar Market Size 2032 | USD 10.12 Billion |
The vehicle pillar market is led by major players including G-TEKT Corporation, Honda Motor Co., Ltd., AISIN Corporation, Volkswagen AG, AutoKiniton US Holdings, Inc., Toyota Motor Corporation, Ford Motor Company, Benteler International AG, and Hyundai Mobis Co., Ltd. These companies dominate through strong R&D investments, advanced lightweighting technologies, and strategic partnerships with OEMs. Asia Pacific is the leading region, holding 32% of the global market share, driven by large-scale vehicle production and rising EV adoption. North America follows with 28%, supported by strong regulatory frameworks and technology integration. Europe, with a 25% share, benefits from premium vehicle demand and stringent safety standards. This regional concentration aligns with robust manufacturing capabilities and innovation leadership.
Market Insights
- The vehicle pillar market size was valued at USD 7.13 billion in 2024 and is projected to reach USD 10.12 billion by 2032, growing at a CAGR of 4.48%.
- Rising safety regulations and growing EV production are driving demand for advanced pillar designs with improved crash protection and lightweight construction.
- Key trends include increased use of high-strength steel and aluminum, integration of ADAS sensors, and development of smart, transparent A-pillars to enhance visibility.
- The market is dominated by major players such as G-TEKT Corporation, Toyota Motor Corporation, Ford Motor Company, and Volkswagen AG, focusing on innovation and global expansion.
- Asia Pacific leads with 32% of the market share, followed by North America at 28% and Europe at 25%. The B-pillar segment holds the largest share due to its critical role in vehicle structure and passenger safety.
Market Segmentation Analysis:
By Pillar Type
The B-Pillar segment dominates the vehicle pillar market with the largest share. B-pillars provide crucial structural support, enhancing occupant protection during side-impact collisions. Their strength and placement improve vehicle rigidity, making them essential in both passenger and commercial vehicles. OEMs prioritize B-pillars in modern safety designs to meet crash test regulations and lightweighting goals. Increasing use of advanced materials like high-strength steel and aluminum further boosts adoption. As automotive manufacturers focus on structural safety and improved cabin stability, the B-pillar remains the most widely used pillar type in new vehicle platforms.
- For instance, ArcelorMittal developed its advanced high-strength steel grade, Usibor® 2000, with a very high tensile strength of up to 2,000 MPa. The steel was designed to improve safety and reduce vehicle weight through its use in structural components that need to withstand high forces during a collision.
By Sales Channel
The OEM segment holds the dominant share in the vehicle pillar market. Original equipment manufacturers integrate pillars into vehicle structures during production, ensuring high precision and strength. The growing demand for lightweight, safe, and aerodynamically efficient vehicles drives OEM adoption. Automakers use advanced forming techniques and automated welding to enhance pillar durability and reduce vehicle weight. OEM channels also benefit from strict safety standards and regulatory compliance. With rising global vehicle production and the shift toward electric platforms, OEM sales continue to lead over aftermarket channels.
- For instance, Honda Motor Co. uses hot-stamped boron steel pillars produced with advanced welding techniques, such as laser welding, to create stronger and lighter body structures. This process improves both rigidity and energy absorption to enhance crashworthiness.
By Vehicle Type
The Passenger Cars segment leads the vehicle pillar market with the highest share. Passenger vehicles require multiple pillars for enhanced structural integrity, crash safety, and aerodynamic performance. Rising demand for SUVs and sedans, especially in urban markets, drives this dominance. Automakers use advanced pillar designs to balance strength and visibility while improving fuel efficiency. Lightweight materials like aluminum and composites further support this trend. Increasing adoption of electric vehicles and focus on passenger safety features ensure strong growth for pillar integration in passenger car manufacturing.
Key Growth Drivers
Rising Focus on Passenger Safety and Crash Protection
Stringent automotive safety regulations and growing consumer awareness are driving strong demand for robust vehicle pillar structures. B- and A-pillars play a key role in maintaining cabin integrity during frontal and side impacts, directly influencing crash ratings. Automakers increasingly use advanced high-strength steel and aluminum alloys to enhance rigidity without adding weight. The rise in global road accidents further accelerates safety feature integration, making pillars essential in modern vehicle designs. OEMs are also adopting reinforced pillars to meet Euro NCAP and IIHS safety standards. This regulatory and safety-driven approach significantly boosts the vehicle pillar market.
- For instance, in its Scalable Product Architecture (SPA) platform, first used in the 2016 XC90, Volvo significantly increased its use of hot-formed boron steel, which is the strongest type of steel used in car bodies. This was done to build an ultra-strong safety cage, including reinforced B-pillars, to enhance crash performance and improve occupant survival rates in side-impact tests. The amount of hot-formed steel in SPA-based vehicles like the XC90 was increased from 7% in the previous model to up to 40%.
Increasing Demand for Lightweight Vehicles
The automotive sector is shifting toward lightweight construction to improve fuel efficiency and reduce emissions. Vehicle pillars made from aluminum, magnesium, and composite materials are gaining traction due to their strength-to-weight ratio. This shift aligns with global CO₂ emission targets and supports electric vehicle range optimization. Lightweight pillars enhance structural performance without compromising passenger safety. Automakers are integrating laser welding and hydroforming technologies to reduce weight and improve production efficiency. The growing demand for lightweight vehicles globally is a major driver, especially in passenger car and EV manufacturing.
Expansion of Electric and Autonomous Vehicle Production
The rapid expansion of electric and autonomous vehicles creates new opportunities for innovative pillar design. EV manufacturers prioritize lightweight and aerodynamic structures to maximize battery efficiency. Pillars are increasingly integrated with sensors, cameras, and ADAS systems to support autonomous driving. A-pillars with embedded vision systems enhance driver visibility and safety, enabling advanced navigation features. Global EV production growth, supported by government incentives and infrastructure investments, fuels pillar demand. As OEMs focus on intelligent and connected vehicle architectures, pillars become crucial components for both safety and technology integration.
Key Trends & Opportunities
Adoption of Advanced Materials and Manufacturing Technologies
Automakers are increasingly adopting advanced materials like carbon fiber-reinforced plastics, high-strength steel, and aluminum to improve pillar performance. These materials offer better rigidity, corrosion resistance, and reduced weight. Additive manufacturing and hydroforming enable complex pillar geometries that enhance crash performance and aerodynamic efficiency. Integrating lightweight materials also aligns with regulatory mandates for emission reduction. This shift creates opportunities for suppliers specializing in high-performance structural components. Companies investing in material innovation and advanced production processes are well positioned to capitalize on this trend.
- For instance, BMW uses a multi-material "Carbon Core" construction in the B-pillars of the 7 Series to enhance structural rigidity and safety. This technology, which incorporates CFRP, ultra-high-tensile steels, and aluminum, was first used in the 7 Series starting with the 2016 model year. While CFRP is used to strategically reduce weight and increase strength, the total vehicle weight reduction on the 7 Series is typically cited as being up to 130 kg.
Integration of Smart Features and ADAS Systems
Pillars are evolving from passive structural components to active technology enablers. OEMs are integrating sensors, radar, LiDAR, and cameras into A- and B-pillars to support ADAS and autonomous functions. Transparent pillar technologies improve driver visibility and reduce blind spots, enhancing road safety. Smart pillars also house antennas and communication modules to support connected vehicle functions. The increasing adoption of Level 2 and Level 3 autonomous driving features presents a strong growth opportunity for smart pillar development, pushing suppliers to innovate integrated structural-electronic solutions.
- For instance, Jaguar Land Rover revealed a research concept called the "360 Virtual Urban Windscreen" to address blind spots caused by the car's pillars. The technology used screens embedded in the interior pillars that would display a live video feed from cameras mounted on the exterior of the vehicle. The goal was to provide an uninterrupted 360-degree view around the car, making pedestrians, cyclists, and other vehicles more visible in urban environments.
Key Challenges
High Manufacturing Costs and Material Limitations
The use of advanced lightweight materials such as carbon fiber and aluminum significantly increases production costs. High-strength materials require specialized processing methods like hydroforming and laser welding, which involve expensive equipment and skilled labor. This cost burden affects smaller manufacturers and limits large-scale adoption. Additionally, maintaining structural strength while reducing weight poses design challenges. Balancing cost-effectiveness and safety standards remains a critical issue for OEMs. This challenge can slow market expansion, especially in price-sensitive segments like entry-level vehicles.
Design Complexity and Regulatory Compliance
Vehicle pillars must meet strict global safety regulations while supporting evolving design requirements. Integrating ADAS systems, wiring, and sensors into pillars adds complexity, increasing engineering and testing costs. Manufacturers must ensure crashworthiness, visibility, and lightweighting goals simultaneously. Regulatory variations across regions further complicate compliance, requiring tailored solutions for different markets. Any design failure can lead to production delays and high recall costs. Managing this complexity while maintaining cost and performance efficiency is a major challenge for industry players.
Regional Analysis
North America
North America holds 28% of the global vehicle pillar market share. The region benefits from strong automotive production, advanced safety regulations, and growing EV adoption. Automakers in the U.S. and Canada invest heavily in high-strength materials and lightweight structures to meet fuel efficiency and safety standards. B-pillars dominate regional demand due to their crucial role in crash protection. OEMs integrate smart pillar technologies with ADAS features to enhance driver visibility and passenger safety. Rising consumer preference for SUVs and electric vehicles further boosts pillar integration. Ongoing investments in advanced manufacturing strengthen North America’s market position.
Europe
Europe accounts for 25% of the vehicle pillar market share. The region is driven by stringent Euro NCAP safety standards and high demand for premium passenger cars. German and French automakers focus on lightweight pillar structures to meet emission targets and improve crash performance. The push for electric and autonomous vehicles accelerates the adoption of smart A- and B-pillars integrated with sensors and cameras. Strong R&D investment in advanced materials such as aluminum and composites supports innovation. Europe’s commitment to vehicle safety and sustainability ensures steady growth across OEM production networks.
Asia Pacific
Asia Pacific leads the vehicle pillar market with a 32% share. The region benefits from rapid urbanization, growing vehicle production, and rising consumer demand for passenger cars. China, Japan, and India drive pillar adoption through large-scale manufacturing and expanding EV infrastructure. OEMs prioritize cost-efficient yet strong pillar structures to meet safety standards. Lightweight material integration supports fuel efficiency and emission goals. B-pillar installations dominate due to their structural importance and high production volumes. The region’s competitive manufacturing base and supportive regulatory environment position it as the global growth hub.
Latin America
Latin America holds a 9% market share in the vehicle pillar industry. The region experiences steady demand growth supported by expanding automotive assembly facilities in Brazil and Mexico. OEMs are adopting stronger B-pillars to meet improving safety regulations and rising export demand. Increasing passenger car production and vehicle modernization programs also support market expansion. While lightweight materials adoption is still emerging, manufacturers are investing in cost-effective pillar solutions. Gradual EV adoption is expected to create future opportunities for advanced pillar integration, especially in urban centers with infrastructure development.
Middle East & Africa
The Middle East & Africa region represents 6% of the vehicle pillar market share. Growth is driven by rising vehicle imports, expanding assembly operations, and increasing demand for passenger vehicles. Safety regulations are tightening, pushing OEMs to adopt stronger pillar structures in new models. The market is shifting from basic structural pillars to lightweight and durable designs that enhance crash performance. Investments in regional manufacturing and EV mobility initiatives are also contributing to growth. Although the market is at an early stage, infrastructure development and localization of production support long-term potential.
Market Segmentations:
By Pillar Type
- A-Pillar
- B-Pillar
- C-Pillar
- D-Pillar
By Sales Channel
- OEM
- Aftermarket
By Vehicle Type
- Passenger Cars
- Commercial Vehicles
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The vehicle pillar market features a moderately consolidated competitive landscape, with leading OEMs and tier-one suppliers focusing on product innovation, lightweighting, and advanced manufacturing. Key players include G-TEKT Corporation, Honda Motor Co., Ltd., AISIN Corporation, Volkswagen AG, AutoKiniton US Holdings, Inc., Toyota Motor Corporation, Ford Motor Company, Benteler International AG, and Hyundai Mobis Co., Ltd. These companies invest in high-strength steel, aluminum, and composite technologies to enhance crash performance and reduce vehicle weight. Many are integrating sensor-based and ADAS-ready pillar solutions to support autonomous and electric vehicle platforms. Strategic collaborations, capacity expansions, and technology upgrades are common competitive strategies. For instance, major automakers and component suppliers are aligning pillar designs with global safety standards and lightweight targets. Continuous R&D efforts and global manufacturing footprints enable these players to maintain strong market positions while addressing evolving regulatory and consumer demands across regions.
Key Player Analysis
- G-TEKT Corporation
- Honda Motor Co., Ltd.
- AISIN Corporation
- Volkswagen AG
- AutoKiniton US Holdings, Inc.
- Toyota Motor Corporation
- Ford Motor Company
- Benteler International AG
- Hyundai Mobis Co., Ltd.
Recent Developments
- In November 2024, AUDI launched the E Concept Sportback car in China, featuring a curved pillar-to-pillar 4K touch display and a glass rooftop, marking a significant step in innovative EV interiors and showcasing advanced in-cabin technology.
- In October 2024, ZEEKR introduced the MIX EV with distinctive double B-pillar doors, priced below USD 40K, highlighting the company’s focus on affordable yet innovative electric vehicle design and accessibility.In November 2023, Fisker showcased the production-intent version of the Fisker Pear at The Grove, during the Los Angeles Auto Show. The Pear featured a new see-through A-pillar with a surround-view camera for improved driver visibility. This innovative tech aimed to address visibility issues, especially during left-hand turns.
- In July 2023, Mercedes-Benz unveiled a concept at the IAA Mobility auto show in Munich, offering a preview of its entry segment vision. The teaser showcased a sleek sedan with side-view mirrors attached to the A-pillar and distinctive white accents emphasizing its styling lines. Notably absent were visible door handles, suggesting a departure from conventional design.
Report Coverage
The research report offers an in-depth analysis based on Pillar Type, Sales Channel, Vehicle Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Vehicle pillar designs will focus more on lightweight materials to meet emission targets.
- Demand for smart pillars with integrated sensors and ADAS features will increase.
- OEMs will invest in advanced forming and welding technologies to improve pillar strength.
- Electric and autonomous vehicle growth will create new design requirements for pillar integration.
- Safety regulations will continue to drive innovation in structural reinforcement.
- Asia Pacific will remain the leading region due to strong vehicle production.
- North America and Europe will adopt more advanced pillar technologies for EV platforms.
- Transparent and camera-integrated A-pillars will enhance visibility and safety.
- Strategic partnerships between OEMs and suppliers will strengthen global supply chains.
- The aftermarket segment will grow with rising vehicle customization and replacement needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Vehicle Pillar Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vehicle Pillar Market projected to grow between 2025 and 2032?
Which Vehicle Pillar Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vehicle Pillar Market?
Who are the leading companies in the Vehicle Pillar Market?
Which region commanded the largest share of the Vehicle Pillar Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vehicle Pillar Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vehicle Pillar Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7.13 billion → 2032: USD 10.12 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vehicle Pillar Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vehicle Pillar Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vehicle Pillar Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vehicle Pillar Market Drivers
- 3.3 Vehicle Pillar Market Restraints & Challenges
- 3.4 Vehicle Pillar Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vehicle Pillar Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vehicle Pillar Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vehicle Pillar category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vehicle Pillar Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vehicle Pillar Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vehicle Pillar market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vehicle Pillar Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vehicle Pillar Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vehicle Pillar Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vehicle Pillar (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vehicle Pillar Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vehicle Pillar Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vehicle Pillar Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vehicle Pillar Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vehicle Pillar Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vehicle Pillar Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vehicle Pillar Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vehicle Pillar Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vehicle Pillar Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
