
Market Overview:
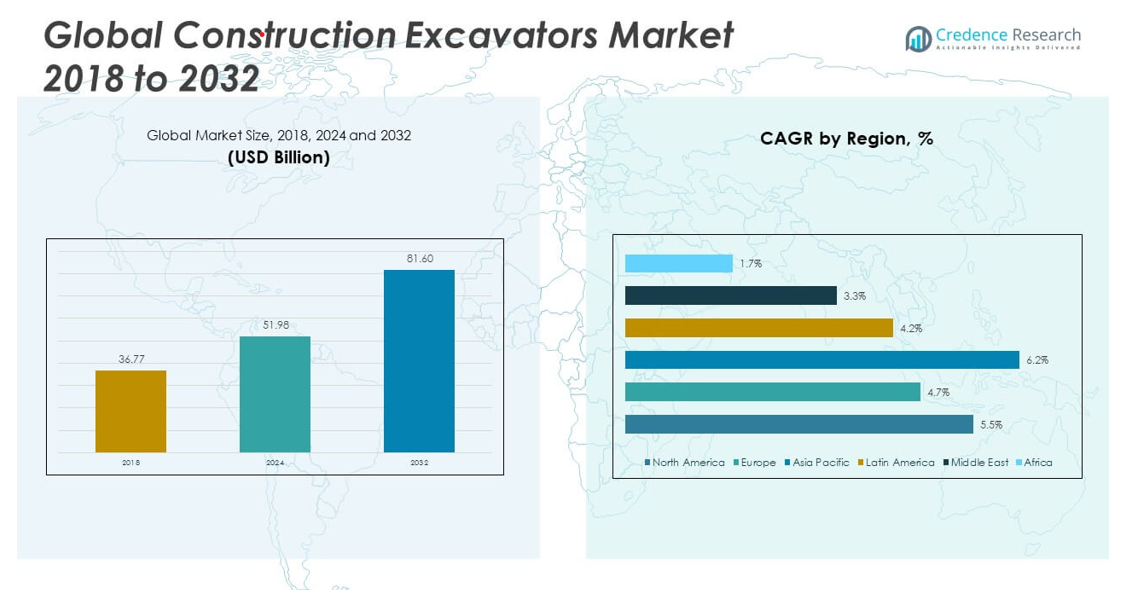
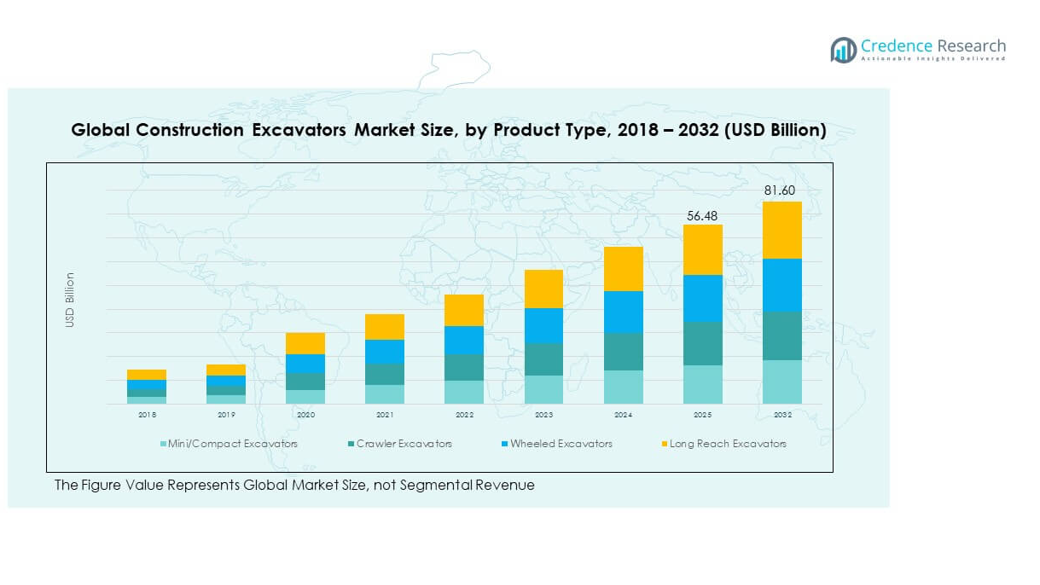
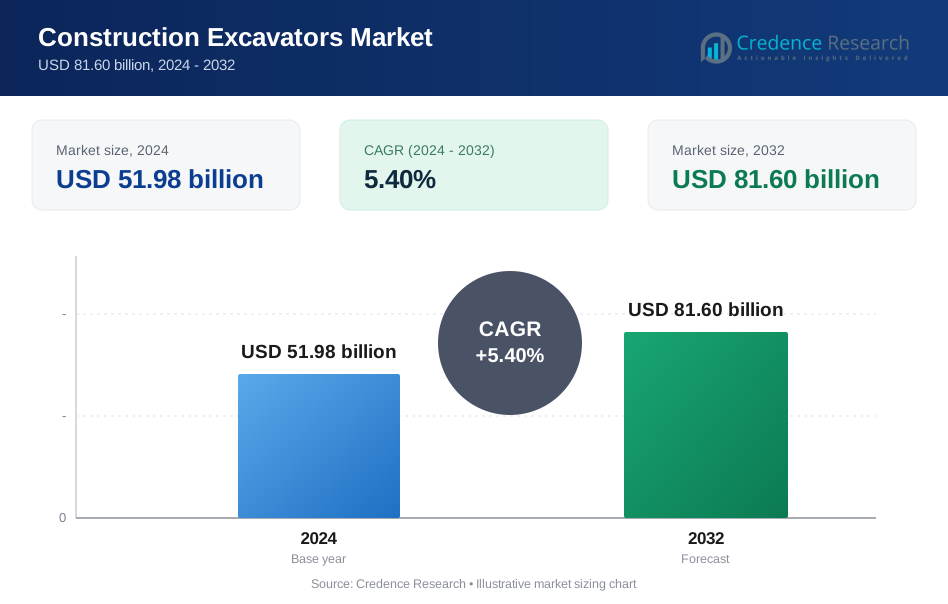
The Global Construction Excavators Market size was valued at USD 36.77 billion in 2018 to USD 51.98 billion in 2024 and is anticipated to reach USD 81.60 billion by 2032, at a CAGR of 5.40% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Construction Excavators Market Size 2024 | USD 51.98 billion |
| Construction Excavators Market, CAGR | 5.40% |
| Construction Excavators Market Size 2032 | USD 81.60 billion |
The Global Construction Excavators Market is driven by large-scale infrastructure projects, urban housing demand, and technological innovation. Governments are investing in transportation, energy, and smart city development, creating steady requirements for versatile excavators. Companies introduce hybrid and electric models to meet emission norms and improve fuel efficiency. Telematics, automation, and advanced hydraulics enhance machine performance and reduce operational downtime. Contractors prefer multi-purpose equipment with attachments for flexibility, while rental services expand availability. Together, these factors establish excavators as vital machinery across construction ecosystems.
In terms of geography, Asia Pacific dominates the Global Construction Excavators Market, supported by extensive public infrastructure and urban development initiatives in China, India, and Southeast Asia. North America and Europe maintain strong demand through technology-driven upgrades, emission compliance, and advanced compact machines for urban projects. Latin America and Africa emerge gradually, with growth linked to mining and infrastructure funding. The Middle East shows momentum through megaprojects and smart city programs in the GCC region. Each region reflects different priorities, shaping diverse growth trajectories.
Market Insights:
- The Global Construction Excavators Market size was valued at USD 36.77 billion in 2018, reached USD 51.98 billion in 2024, and is anticipated to achieve USD 81.60 billion by 2032, registering a CAGR of 5.40% during the forecast period.
- Asia Pacific led with 43% share in 2024, driven by large-scale infrastructure, urbanization, and mining projects, while Europe held 29% due to sustainability regulations and North America captured 17% supported by modernization and technology adoption.
- Asia Pacific is the fastest-growing region with 43% share, supported by government-backed infrastructure programs, strong housing demand, and industrial expansion across China, India, and Southeast Asia.
- Crawler excavators represented the dominant share of the market in 2024, accounting for 58% of total demand, due to their strength in infrastructure and mining projects.
- Mini/compact excavators accounted for 22% share, reflecting strong adoption in urban and residential projects where maneuverability and space efficiency are critical.
Market Drivers
Rising Demand From Expanding Infrastructure Development Projects Across Multiple Regions
Infrastructure development remains the strongest driver for the Global Construction Excavators Market, supported by large-scale public and private projects. Governments are committing to roads, railways, airports, and smart city programs requiring advanced machinery. Excavators provide speed and efficiency for foundation works, earthmoving, and site preparation. Urbanization across Asia and Africa fuels continuous demand for mid and large-size excavators. North America and Europe focus on upgrading old infrastructure, which also sustains growth. Contractors prefer machines with high productivity and versatile attachments. This preference ensures higher equipment penetration across projects. The driver keeps reinforcing long-term market potential.
Adoption Of Advanced Technologies Improving Productivity And Operational Efficiency
The integration of digital and hydraulic systems significantly drives the Global Construction Excavators Market. Telematics platforms allow real-time tracking and predictive maintenance, reducing downtime. Smart controls improve fuel economy and operator comfort. Hybrid and electric excavators support sustainability goals while cutting emissions. Contractors are prioritizing automation-ready models for efficiency. Equipment with integrated sensors provides actionable data for site managers. Connectivity between machines and project software enhances jobsite coordination. These technological improvements make excavators essential for modern construction activities.
- For instance, Komatsu’s PC210LCi-11 with Intelligent Machine Control 2.0 integrates a 12-inch touchscreen and 3D GNSS technology, enabling auto bucket angle control, over-digging prevention, and precise finish grading to improve efficiency and reduce operator skill gaps.
Strong Demand From Residential And Commercial Construction Investments Worldwide
The Global Construction Excavators Market gains momentum from rising residential and commercial construction investments. Housing demand in emerging economies increases equipment utilization. Commercial projects like malls, office complexes, and logistics hubs require excavators for large-scale groundwork. Real estate development is supported by rising disposable incomes and urban expansion. Compact excavators are favored in dense cities where space is limited. Builders also demand equipment with attachments for multipurpose use. This creates steady requirements across both large and small projects. Growth in construction financing also accelerates demand for excavation machinery.
- For instance, Volvo’s EC35D compact excavator offers a 3.71-meter digging depth and 1.65-meter operating width, providing strong digging force and stability for urban residential and commercial projects in space-constrained environments.
Sustainability Mandates And Emission Regulations Driving Equipment Replacement Cycles
Environmental regulations encourage the replacement of older diesel-based excavators with low-emission models. Governments promote the adoption of hybrid and electric construction equipment. Manufacturers respond by developing fuel-efficient engines and electrified powertrains. The Global Construction Excavators Market experiences steady growth due to these regulations. Eco-friendly machines also support corporate sustainability goals for construction firms. Contractors recognize the long-term savings from efficient engines and reduced fuel costs. Policies around emission standards in Europe and North America accelerate adoption. Sustainability pressures therefore become a driver for equipment modernization globally.
Market Trends
Increasing Penetration Of Electric And Hybrid Excavators In Key Construction Markets
Electric and hybrid models are gaining wider acceptance across the Global Construction Excavators Market. Rising energy efficiency concerns shift attention from traditional diesel engines. Urban projects prefer low-noise equipment, making electric models popular. Manufacturers are expanding hybrid lineups to improve fuel savings. Charging infrastructure development supports long-term adoption in developed nations. Contractors experiment with rental fleets of electric excavators for pilot projects. Asian cities also embrace cleaner alternatives to reduce pollution. The shift indicates a permanent trend in construction machinery evolution.
Growing Popularity Of Rental And Leasing Solutions Among Construction Firms
The Global Construction Excavators Market is experiencing a rising preference for rental and leasing models. Small and medium contractors avoid heavy capital expenditure by renting. Rental firms upgrade fleets frequently to offer advanced machinery. This practice ensures access to newer technologies without ownership costs. Flexible contracts support fluctuating project needs in construction cycles. The trend is stronger in Asia-Pacific, where small contractors dominate. North American companies also expand rental partnerships to handle seasonal demand. The trend provides consistent market activity regardless of ownership rates.
- For instance, in March 2023, United Rentals announced that it had surpassed 335,000 telematics-enabled fleet units, including earthmoving equipment such as excavators, enhancing rental offerings with real-time data insights for productivity and safety according to their company press report.
Development Of Compact Excavators For Urban And Space-Constrained Environments
Compact models are witnessing rapid adoption in the Global Construction Excavators Market. Dense cities prioritize smaller, maneuverable equipment for underground and utility work. Compact excavators are ideal for landscaping, demolition, and road repairs. Manufacturers design models with reduced tail swing for confined sites. Demand rises in Europe and Japan due to limited working spaces. Contractors value the ability to transport compact units on small trailers. Attachments extend versatility for specialized urban projects. Compact designs ensure efficiency without compromising power.
- For instance, Kubota introduced the U48-5 tight tail swing compact excavator in May 2021, offering operators a powerful 4.8 metric ton machine with a redesigned tail swing for enhanced maneuverability in urban and space-constrained job sites, as officially documented by Kubota’s launch announcement.
Integration Of Smart Connectivity And IoT Features Into Construction Excavators
Digitalization remains a defining trend for the Global Construction Excavators Market. Telematics, IoT, and GPS-based tracking are standard in new models. Contractors gain access to data on fuel use, idle times, and engine health. Predictive maintenance features lower costs and extend machine life. Cloud platforms allow fleet managers to monitor multiple machines simultaneously. Jobsite efficiency improves with remote diagnostics and operator performance data. Manufacturers partner with software providers to expand connected services. This trend strengthens customer loyalty and equipment value.
Market Challenges Analysis
High Equipment Costs And Rising Operational Expenses Limiting Broader Market Adoption
The Global Construction Excavators Market faces challenges linked to high purchase and operational costs. Excavators require significant investment, which smaller contractors may not afford. Rising prices of raw materials further inflate equipment costs. Fuel and maintenance expenses add to the financial burden of ownership. Rental models partly address this issue but do not cover all needs. Advanced features like automation increase machine prices, creating affordability gaps. Price-sensitive markets in Asia and Africa experience slower adoption due to this. Cost pressures remain a persistent challenge for manufacturers and buyers.
Supply Chain Disruptions And Regulatory Pressures Affecting Market Stability Globally
The Global Construction Excavators Market is also challenged by supply chain volatility and regulations. Shortages of semiconductors and hydraulic components delay production timelines. Global shipping constraints extend delivery lead times for new machines. Environmental regulations force rapid technological changes, straining smaller manufacturers. Compliance requires higher R&D spending and redesign of existing models. Trade barriers and tariffs in some regions increase import costs. Contractors also face regulatory pressure for sustainability certifications. The industry must balance compliance with cost efficiency to maintain competitiveness.
Market Opportunities
Expanding Infrastructure Projects In Emerging Economies Offering Growth Avenues For Manufacturers
The Global Construction Excavators Market benefits from large-scale projects in developing economies. Governments in Asia, Latin America, and Africa allocate funds for transport and housing. Urbanization creates long-term demand for versatile excavators. International contractors entering these markets drive equipment imports. Compact and mid-size excavators hold strong potential in urban construction. Companies expanding dealer networks in these regions can capture higher shares. Partnerships with local firms improve service reach and aftersales support. These opportunities strengthen growth beyond developed markets.
Technological Advancements Creating A Path For Product Diversification And Market Expansion
Innovation provides consistent opportunities for the Global Construction Excavators Market. Electric and hybrid technologies allow manufacturers to meet sustainability goals. Smart connectivity offers differentiation and new revenue streams through digital services. Autonomous excavator prototypes demonstrate potential for future demand. Specialized attachments open opportunities in demolition, mining, and landscaping. Manufacturers investing in R&D gain competitive edge in global markets. Service models built on predictive analytics strengthen customer relationships. Opportunities grow where technology aligns with regulatory and operational needs.
Market Segmentation Analysis:
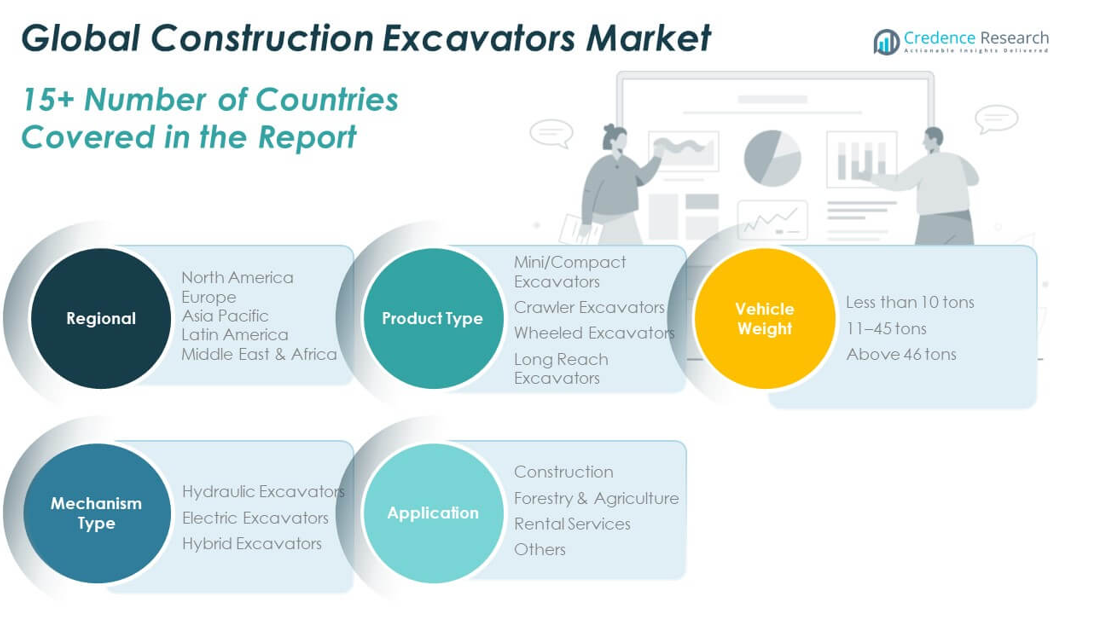
By product type, the Global Construction Excavators Market is led by crawler excavators due to their ability to handle large-scale infrastructure, mining, and heavy-duty construction projects. Mini and compact excavators show strong growth in urban development’s where space efficiency is critical, while wheeled models are preferred for mobility in roadwork and municipal projects. Long reach excavators serve niche applications such as river dredging and demolition, adding diversity to product demand.
- For instance, Komatsu’s PC950-11 crawler excavator, introduced in 2024, has an operating weight range of 94,600 to 97,700 kg and supports bucket capacities between 4.0 and 6.5 cubic meters, making it effective for heavy infrastructure and mining operations.
By vehicle weight, the Global Construction Excavators Market reflects dominance in the 11–45 tons category, which balances power and flexibility for infrastructure and residential projects. Excavators below 10 tons gain traction in city-based construction, landscaping, and utility work. Above 46 tons remains significant for mining and industrial-scale projects where maximum digging force is required.
- For instance, Caterpillar’s 330 hydraulic excavator, updated for 2024, delivers a 30,500 kg operating weight and a 1.76 cubic meter bucket, matching versatility and power needs for major construction projects worldwide.
By mechanism type, hydraulic excavators hold the largest share due to their reliability and widespread application across industries. Electric models are steadily gaining acceptance in developed regions, driven by emission norms and sustainability goals. Hybrid variants provide a transition pathway, delivering fuel savings and performance advantages for contractors seeking efficiency.
By application, the Global Construction Excavators Market is primarily driven by the construction segment, supported by urban expansion and government-backed infrastructure projects. Forestry and agriculture create stable opportunities for specialized excavators. Rental services are expanding quickly as smaller contractors prefer flexible access to equipment without heavy capital investment. Other applications include utilities and industrial operations, extending the role of excavators across multiple sectors.
Segmentation:
By Product Type
- Mini/Compact
- Crawler
- Wheeled
- Long Reach
By Vehicle Weight
- Less than 10 tons
- 11–45 tons
- Above 46 tons
By Mechanism Type
- Hydraulic Excavators
- Electric Excavators
- Hybrid Excavators
By Application
- Construction
- Forestry & Agriculture
- Rental Services
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Construction Excavators Market size was valued at USD 6.45 billion in 2018 to USD 8.88 billion in 2024 and is anticipated to reach USD 14.04 billion by 2032, at a CAGR of 5.5% during the forecast period. North America holds a 17% market share. The Global Construction Excavators Market in this region benefits from strong infrastructure modernization programs across the U.S. and Canada. Demand is supported by road upgrades, residential projects, and energy sector developments. Contractors favor advanced hydraulic and hybrid excavators for efficiency and compliance with emission standards. Rental services see strong adoption due to high machine costs. The U.S. dominates regional demand due to large-scale public investment. Canada contributes through mining and construction growth. Mexico strengthens adoption with rising industrial construction. The region remains a technology-driven market for premium excavator models.
Europe
The Europe Global Construction Excavators Market size was valued at USD 11.12 billion in 2018 to USD 15.18 billion in 2024 and is anticipated to reach USD 22.53 billion by 2032, at a CAGR of 4.7% during the forecast period. Europe holds a 29% market share. The Global Construction Excavators Market here is shaped by infrastructure renovation, housing projects, and sustainability policies. Governments enforce strict emission standards, which drive hybrid and electric excavator adoption. Compact machines see high demand due to urban density in Germany, UK, and France. Eastern Europe contributes growth through industrial and transport infrastructure expansion. Rental services remain strong across the region to manage high equipment costs. The market reflects maturity in Western Europe but continues expanding eastward. European manufacturers also focus on export-driven growth supported by advanced product portfolios.
Asia Pacific
The Asia Pacific Global Construction Excavators Market size was valued at USD 15.31 billion in 2018 to USD 22.48 billion in 2024 and is anticipated to reach USD 37.54 billion by 2032, at a CAGR of 6.2% during the forecast period. Asia Pacific holds a 43% market share. The Global Construction Excavators Market is dominated by large-scale projects in China, India, and Southeast Asia. Rising urbanization, smart city programs, and industrial parks drive demand. Contractors adopt mid and large-sized crawler excavators for road, rail, and port developments. Japan and South Korea lead in compact excavator demand due to urban density. Australia supports growth with mining-related equipment needs. Local manufacturers in China and Japan drive competitive pricing and innovation. Asia Pacific remains the fastest-growing regional market due to continuous construction and infrastructure investments.
Latin America
The Latin America Global Construction Excavators Market size was valued at USD 2.33 billion in 2018 to USD 3.27 billion in 2024 and is anticipated to reach USD 4.69 billion by 2032, at a CAGR of 4.2% during the forecast period. Latin America holds a 6% market share. The Global Construction Excavators Market gains momentum from urban expansion and public infrastructure programs in Brazil and Mexico. Government investment in housing and transportation projects supports steady demand. Contractors adopt compact and medium excavators for urban development. The mining sector in Chile and Peru creates opportunities for heavy-duty equipment. Rental services expand across smaller contractors seeking affordable access. Economic fluctuations limit rapid expansion but long-term demand remains resilient. Regional growth depends on consistent policy support and foreign investment inflows.
Middle East
The Middle East Global Construction Excavators Market size was valued at USD 1.10 billion in 2018 to USD 1.43 billion in 2024 and is anticipated to reach USD 1.93 billion by 2032, at a CAGR of 3.3% during the forecast period. The Middle East holds a 3% market share. The Global Construction Excavators Market in this region is driven by ongoing megaprojects in GCC countries. Saudi Arabia’s Vision 2030 and UAE’s smart city projects create sustained demand. Large crawler excavators dominate in oil, gas, and infrastructure projects. Compact excavators gain traction in urban housing projects. Rental services expand to cater to contractors in large-scale developments. Israel and Turkey contribute with transport and urban infrastructure upgrades. Demand for advanced models rises due to hot climate operational needs. Regional adoption is steady but relies heavily on government-funded projects.
Africa
The Africa Global Construction Excavators Market size was valued at USD 0.46 billion in 2018 to USD 0.74 billion in 2024 and is anticipated to reach USD 0.87 billion by 2032, at a CAGR of 1.7% during the forecast period. Africa holds a 2% market share. The Global Construction Excavators Market in this region is influenced by infrastructure gaps and growing urbanization. South Africa and Egypt lead demand through housing and road projects. Mining activities in Sub-Saharan Africa sustain crawler excavator adoption. Limited financing and high costs restrict rapid adoption of advanced models. Compact excavators gain traction in smaller urban projects. Rental and leasing options emerge as practical solutions for small contractors. Foreign investment in infrastructure enhances opportunities in East and West Africa. The region maintains slow growth but carries long-term potential with government partnerships.
Key Player Analysis:
- Caterpillar Inc.
- Komatsu Ltd.
- XCMG Group
- SANY Heavy Industry Co., Ltd.
- Volvo Construction Equipment
- Liebherr Group
- Hitachi Construction Machinery Co., Ltd.
Competitive Analysis:
The Global Construction Excavators Market is highly competitive, shaped by established international manufacturers and regional players. Caterpillar Inc. and Komatsu Ltd. lead through extensive product portfolios and global distribution networks. XCMG Group and SANY Heavy Industry Co., Ltd. strengthen their presence with cost-effective solutions and rapid innovation. Volvo Construction Equipment and Liebherr Group focus on advanced technology, fuel efficiency, and sustainable machinery. Hitachi Construction Machinery Co., Ltd. emphasizes hydraulic efficiency and compact models for urban projects. Competition is driven by continuous product development, strategic partnerships, and geographic expansion. It reflects a balance between premium brands catering to developed economies and competitive Asian players supplying emerging markets. Companies invest in digital integration, hybrid technologies, and aftersales services to secure long-term customer loyalty.
Recent Developments:
- In September 2025, Komatsu announced a landmark multi-year strategic partnership with Applied Intuition to build the next generation of intelligent vehicles for the mining industry. This partnership marks the largest technology investment in Komatsu’s history and will deploy advanced onboard software and autonomy technology including Vehicle OS, AI-powered haulage, and collision avoidance features for Komatsu's mining equipment.
- In June 2025, XCMG Group entered a global framework agreement with BHP, marking one of the most significant mining equipment partnerships between a Western and Chinese manufacturer. Worth an estimated $1.2 billion over five years, this deal focuses on co-developing next-generation heavy hauling, excavating, and AI-based drilling solutions.
- In March 2025, Caterpillar Inc. signed a strategic development agreement by investing £5 million ($5.4 million) in Equipmake Holdings PLC to accelerate the creation of electric drivetrain products and solutions tailored for Caterpillar’s diverse industrial and construction applications. The loan, set to mature in March 2029, will help develop advanced electrification options in Caterpillar's equipment line, marking a major step forward in sustainability and innovation for the brand.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Vehicle Weight, Mechanism Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Construction Excavators Market will witness steady demand driven by urbanization and infrastructure investments.
- Growing adoption of hybrid and electric excavators will transform equipment portfolios across developed regions.
- Rental services will expand as contractors prioritize cost management and flexible machine access.
- Compact excavators will gain stronger traction in dense urban areas with limited working space.
- Digital integration and IoT-enabled features will enhance fleet management and operational efficiency.
- Sustainable machinery will play a critical role due to tightening global emission regulations.
- Asia Pacific will remain the dominant region supported by large-scale construction and mining projects.
- Europe and North America will focus on technology-driven growth with advanced hydraulic and smart systems.
- Strategic alliances, mergers, and new product launches will intensify competition among key players.
- Long-term opportunities will arise in emerging regions through government-backed infrastructure programs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Construction Excavators Market?
At what Compound Annual Growth Rate is the Global Construction Excavators Market projected to grow between 2024 and 2032?
What factors are driving the growth of the Global Construction Excavators Market?
What are some challenges faced by the Global Construction Excavators Market?
Who are the major players in the Global Construction Excavators Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Construction Excavators Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Construction Excavators Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 51.98 billion → 2032: USD 81.60 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Construction Excavators Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Construction Excavators Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Construction Excavators Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Construction Excavators Market Drivers
- 3.3 Construction Excavators Market Restraints & Challenges
- 3.4 Construction Excavators Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Construction Excavators Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Construction Excavators Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Construction Excavators category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Construction Excavators Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Construction Excavators Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Construction Excavators market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Construction Excavators Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Construction Excavators Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Construction Excavators Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Construction Excavators (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Construction Excavators Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Construction Excavators Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Construction Excavators Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Construction Excavators Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Construction Excavators Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Construction Excavators Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Construction Excavators Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Construction Excavators Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Construction Excavators Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
