
Market Overview
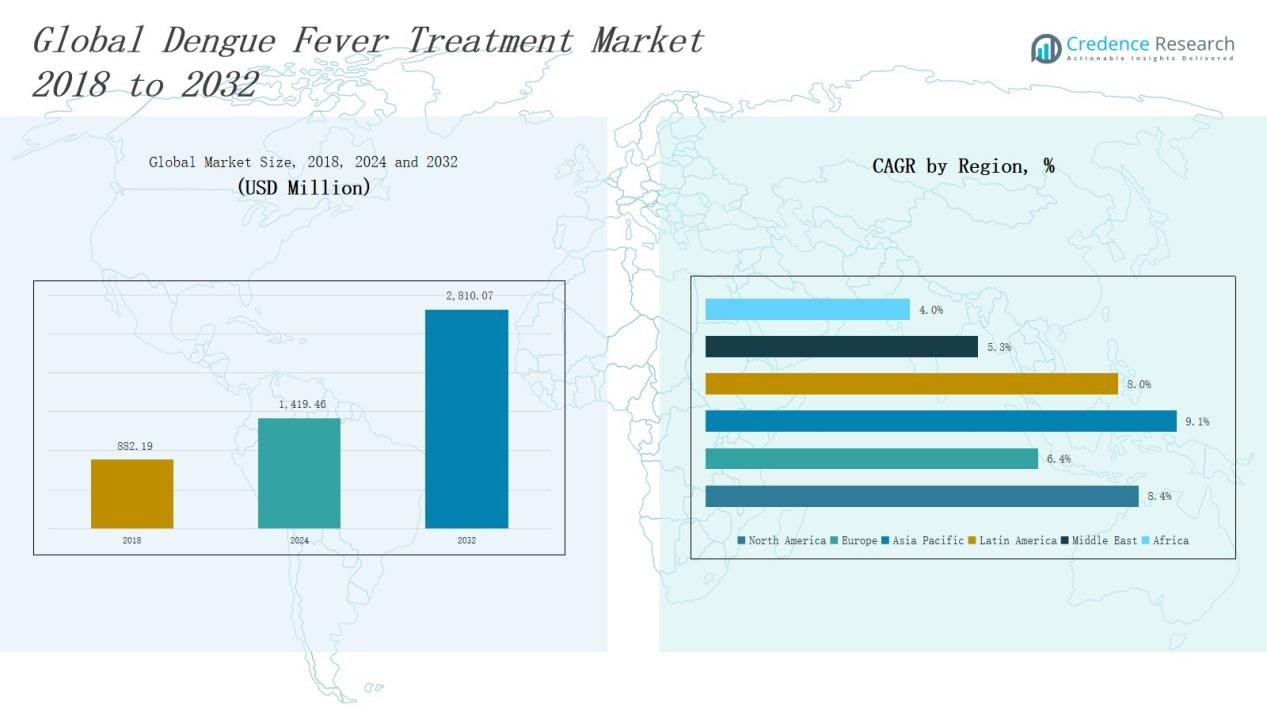
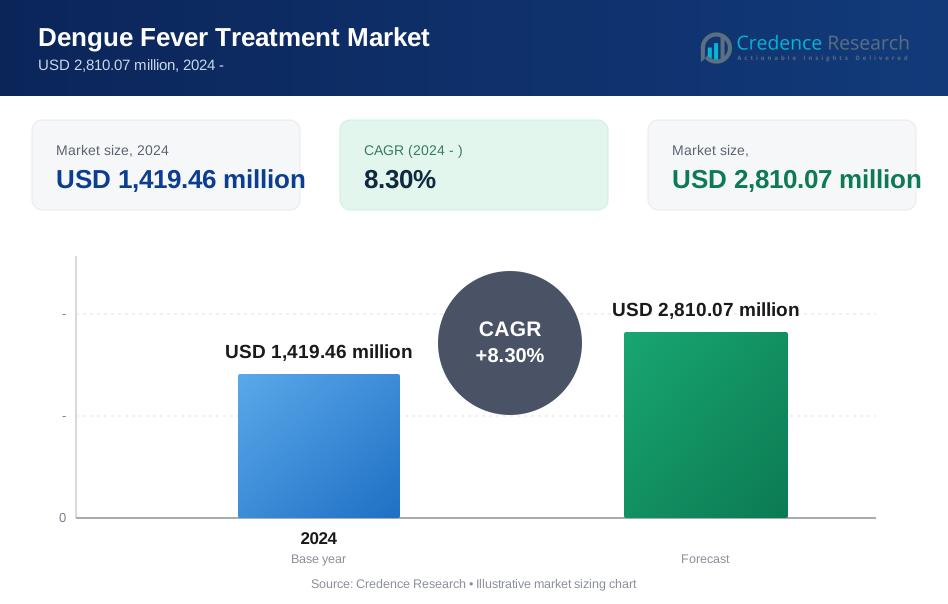
Dengue Fever Treatment Market size was valued at USD 882.19 million in 2018 to USD 1,419.46 million in 2024 and is anticipated to reach USD 2,810.07 million by 2032, at a CAGR of 8.30% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dengue Fever Treatment Market Size 2024 | USD 1,419.46 Million |
| Dengue Fever Treatment Market, CAGR | 8.30% |
| Dengue Fever Treatment Market Size 2032 | USD 2,810.07 Million |
The Dengue Fever Treatment Market is shaped by leading players such as Takeda Pharmaceutical, Sanofi, Pfizer, GlaxoSmithKline, Johnson & Johnson, Abbott Laboratories, Teva Pharmaceuticals, Sun Pharmaceutical Industries, Dr. Reddy’s Laboratories, Cipla, Serum Institute of India, Bharat Biotech, Panacea Biotec, and Instituto Butantan. These companies strengthen their positions through vaccine innovations, development of monoclonal antibodies, and affordable symptomatic drug portfolios. Strategic collaborations with global health agencies and government partnerships enhance their market penetration, particularly in endemic regions. Asia Pacific emerged as the leading region with a 46% share in 2024, driven by high dengue prevalence, large-scale immunization initiatives, and significant investments in advanced therapies and preventive solutions.
Market Insights
- The Dengue Fever Treatment Market grew from USD 882.19 million in 2018 to USD 1,419.46 million in 2024 and is expected to reach USD 2,810.07 million by 2032.
- Asia Pacific led with 46% share in 2024, driven by high endemicity, large-scale vaccination programs, and rapid healthcare expansion across India, Indonesia, and the Philippines.
- By treatment type, vaccines dominated with 38% share in 2024, followed by symptomatic drugs at 32%, highlighting their critical role in preventive and supportive care.
- By route of administration, parenteral treatments held 61% share in 2024, reflecting the hospital-based delivery of vaccines, antivirals, and monoclonal antibodies.
- Hospitals accounted for the highest end-user share at 54% in 2024, due to the need for inpatient care, intravenous therapy, and monitoring in severe dengue cases.
Market Segment Insights
By Treatment Type
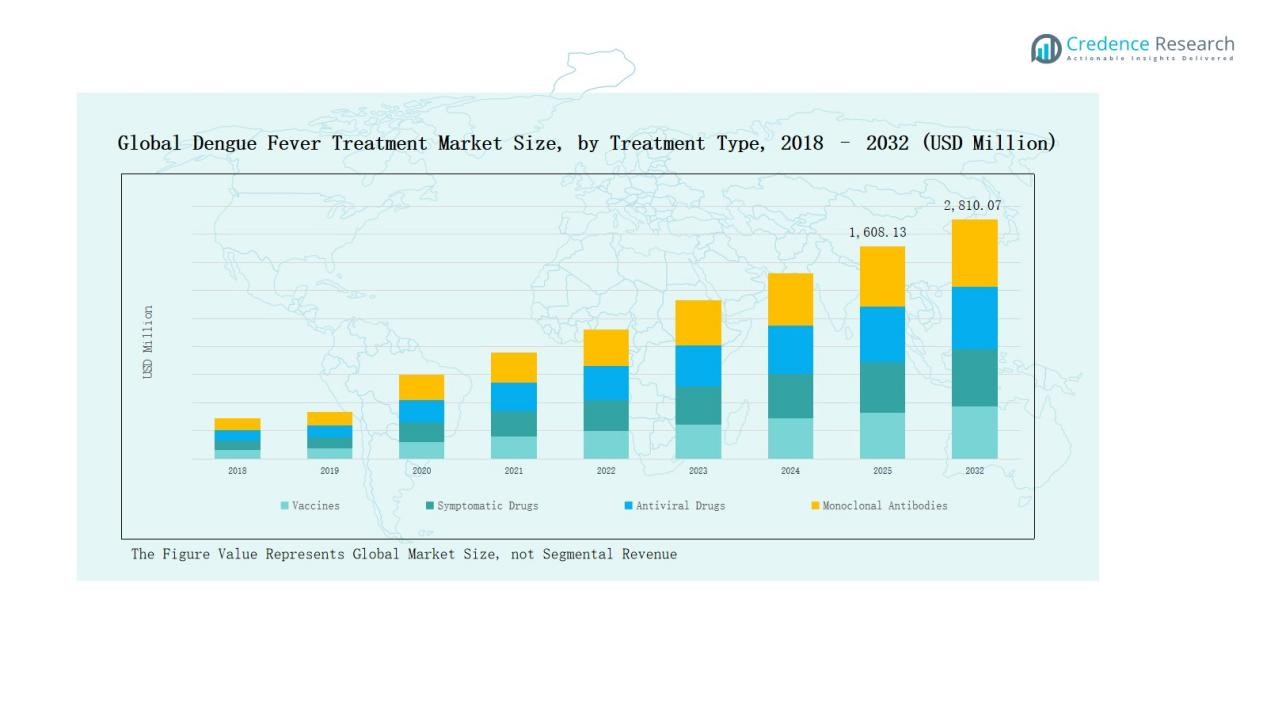
Vaccines accounted for the largest share of the dengue fever treatment market with 38% in 2024. Their dominance is driven by growing adoption in endemic regions and government immunization initiatives. Symptomatic drugs held 32% share, supported by high patient reliance on pain relievers and antipyretics for immediate relief. Antiviral drugs represented 20% share, boosted by increasing R&D efforts to develop targeted therapies. Monoclonal antibodies captured 10% share, benefiting from recent clinical approvals that provide longer-term protection.
- For instance, Dengvaxia was approved and integrated into national vaccination campaigns in countries like Brazil and the Philippines, the program was suspended and eventually banned in the Philippines due to safety risks in non-infected people.
By Route of Administration
Parenteral (injectable) treatments dominated the segment with 61% share in 2024. Their leadership stems from the necessity of hospital-based administration of vaccines, antivirals, and monoclonal antibodies. Oral treatments followed with 39% share, primarily driven by symptomatic drugs such as analgesics and fluid replacement therapies. The oral route continues to expand due to convenience, lower cost, and wider availability in outpatient and home healthcare settings.
- For instance, by May 2024, Qdenga was approved in approximately 40 countries, not just "over 20". Countries include Indonesia, Brazil, Thailand, Argentina, and members of the European Union.
By End User
Hospitals held the dominant position with 54% share in 2024, attributed to the need for inpatient care, intravenous drug administration, and critical monitoring in severe dengue cases. Specialty clinics accounted for 28% share, as they provide tailored treatments and follow-up services for dengue management. Home healthcare represented 18% share, supported by rising patient preference for oral symptomatic drugs and cost-effective care outside hospitals. Growing awareness and telehealth integration are expected to enhance adoption of home-based care in the coming years.
Key Growth Drivers
Rising Global Burden of Dengue
The increasing incidence of dengue cases worldwide serves as the strongest growth driver. According to WHO, nearly 390 million infections occur annually, intensifying the need for effective treatments. Governments in high-burden countries are expanding vector-control programs and allocating funds to strengthen treatment facilities. Hospitals and clinics report rising patient admissions during seasonal outbreaks, increasing reliance on both symptomatic and advanced therapies. This growing disease prevalence is pushing pharmaceutical companies to accelerate development of vaccines, antivirals, and supportive care solutions.
- For instance, Takeda Pharmaceutical’s dengue vaccine, Qdenga, demonstrated 80.2% efficacy in Phase III trials across 8 countries, leading to its regulatory approval in Europe in December 2022
Advancements in Vaccine Development
Innovations in dengue vaccines are transforming the treatment landscape. Takeda’s Dengvaxia and Qdenga have gained approval across several regions, expanding patient access. The vaccines reduce hospitalization risk and severe dengue cases, driving higher demand in endemic regions. Public health agencies in Asia-Pacific and Latin America actively promote vaccination programs. Clinical pipelines for next-generation vaccines show promising outcomes, ensuring wider adoption over the next decade. The ability of vaccines to offer long-term prevention strengthens their role as a cornerstone in market expansion.
Government Support and Funding Initiatives
Robust government initiatives play a critical role in advancing dengue treatment availability. National immunization programs in countries like Brazil, Philippines, and India include dengue vaccines as part of public health policies. Funding support also extends to vector control measures, clinical trials, and procurement of medical supplies during outbreaks. Organizations such as UNICEF and WHO partner with governments to ensure affordable treatment access. These combined efforts not only boost awareness but also improve healthcare infrastructure, which directly accelerates treatment adoption across hospitals and community centers.
- For instance, Brazil’s Ministry of Health launched a nationwide dengue control campaign in 2023 that distributed over 600,000 Wolbachia-infected mosquitoes to reduce dengue transmission.
Key Trends & Opportunities
Monoclonal Antibody Therapies
The rise of monoclonal antibodies offers new opportunities in dengue management. These therapies provide targeted immune protection, reducing viral load and disease severity. Recent clinical trials highlight efficacy against multiple dengue strains, making them a promising segment for long-term treatment strategies. Growing pharmaceutical partnerships and accelerated regulatory approvals are pushing these therapies into mainstream adoption. High acceptance among patients with severe infections and supportive reimbursement policies are expected to position monoclonal antibodies as a major future growth driver in the market.
- For instance, Janssen Pharmaceuticals (Johnson & Johnson) partnered with the National Institute of Allergy and Infectious Diseases (NIAID) to evaluate its mAb combination therapy, including antibodies JNJ-1802 and JNJ-1954, which showed a greater than 90% reduction in viral RNA in non-human primate models within 48 hours of administration.
Expansion of Home Healthcare and Telemedicine
Home healthcare adoption is growing as patients prefer cost-effective treatment outside hospitals. Oral symptomatic drugs, fluid replacement, and remote monitoring technologies are supporting this transition. Telemedicine platforms enable patients to consult physicians for early symptom management, reducing hospitalization pressure. This trend is especially evident in Asia-Pacific, where digital health adoption is rapidly increasing. Pharmaceutical companies and digital health providers are collaborating to integrate telehealth tools with dengue care solutions. The expansion of this model represents a strong opportunity for widening access to treatment.
- For instance, Takeda's tetravalent dengue vaccine candidate, TAK-003, is based on a live, attenuated dengue serotype 2 virus that provides cross-neutralizing activity against all four dengue serotypes. Phase 3 data from a 4.5-year study showed a cumulative vaccine efficacy of 84.1% against hospitalized dengue.
Key Challenges
Limited Antiviral Options
The absence of widely approved, effective antiviral drugs remains a major hurdle. While research is ongoing, most treatments remain symptomatic, leaving patients reliant on supportive care. This limitation increases hospitalization duration and recovery times. Uncertainty in clinical trial outcomes also discourages large-scale investments from pharmaceutical companies. Without breakthrough therapies, reliance on vaccines and symptomatic drugs continues, slowing innovation. Developing effective antivirals that cover all dengue serotypes is a critical need for strengthening the treatment market’s long-term growth potential.
Vaccine Safety Concerns and Acceptance
Safety concerns around dengue vaccines have created barriers to adoption. Previous controversies, such as limited efficacy in seronegative patients, have raised public skepticism. Despite advancements, some regions remain hesitant to include vaccines in mass immunization programs. Negative public perception affects uptake rates and slows revenue growth for manufacturers. Addressing safety profiles through transparent clinical data and public education campaigns is essential to restore trust. Without higher acceptance, the full preventive potential of vaccines may not be realized, limiting overall market progress.
High Treatment Costs in Developing Regions
Affordability continues to challenge access in low- and middle-income countries, where dengue is most prevalent. Vaccines, monoclonal antibodies, and advanced therapies often remain priced beyond the reach of average households. Weak reimbursement systems and uneven healthcare funding further worsen disparities in treatment availability. Many patients rely on low-cost symptomatic drugs, which provide only temporary relief. Unless manufacturers and governments collaborate on cost-reduction measures, equitable access will remain limited. This cost challenge directly affects both patient outcomes and market penetration in developing regions.
Regional Analysis
North America
North America accounted for 22% of the global dengue fever treatment market in 2024, with revenue of USD 229.68 million. The region is projected to reach USD 458.07 million by 2032, growing at a CAGR of 8.4%. Strong healthcare infrastructure, high awareness levels, and adoption of advanced therapies such as monoclonal antibodies drive market growth. The U.S. leads regional demand with expanded vaccine approvals and government-led awareness campaigns. Increasing cross-border travel also amplifies the need for preventive and therapeutic solutions, strengthening North America’s role in the global landscape.
Europe
Europe represented 17% of the market share in 2024, valued at USD 177.44 million, and is projected to reach USD 306.32 million by 2032 at a CAGR of 6.4%. The region benefits from structured healthcare systems and rising incidence of travel-related dengue cases. Countries like France, Spain, and Italy report higher adoption of vaccines and supportive care. Government efforts to monitor vector-borne diseases and collaborations with pharmaceutical companies are expanding access to advanced treatments. However, slower adoption compared to Asia-Pacific reflects reliance on preventive measures and relatively lower prevalence rates.
Asia Pacific
Asia Pacific dominated the market with the largest 46% share in 2024, generating USD 615.47 million and expected to reach USD 1,296.09 million by 2032 at a CAGR of 9.1%. The region’s dominance stems from high endemicity in countries such as India, Indonesia, and the Philippines, which account for a majority of global dengue cases. Large-scale vaccination programs, government investments, and a surge in R&D for antivirals strengthen market growth. Rapid healthcare expansion and growing awareness further drive treatment adoption. Asia Pacific remains the most critical region for future market expansion due to its significant disease burden.
Latin America
Latin America held 26% of the global market share in 2024, valued at USD 350.42 million, and is projected to reach USD 678.66 million by 2032 at a CAGR of 8.0%. Brazil and Argentina lead regional demand, supported by widespread dengue prevalence and government immunization initiatives. The high adoption of vaccines and symptomatic drugs highlights the region’s urgent need for effective solutions. Seasonal outbreaks and large-scale awareness campaigns boost demand across hospitals and clinics. Latin America’s strong disease burden ensures it remains a vital market for pharmaceutical companies expanding treatment portfolios.
Middle East
The Middle East accounted for 2% share in 2024, valued at USD 28.45 million, with projections reaching USD 45.08 million by 2032 at a CAGR of 5.3%. Although the disease burden is lower compared to Asia and Latin America, rising travel-related cases and imported infections drive demand. Countries in the GCC are investing in vaccines and advanced therapies as precautionary measures. Growing public health initiatives and collaborations with international pharmaceutical firms support gradual market expansion. However, limited endemic presence keeps market size relatively modest.
Africa
Africa captured 1% of the market share in 2024, valued at USD 18.00 million, and is projected to reach USD 25.85 million by 2032 at a CAGR of 4.0%. Dengue remains underreported in many African nations due to weak surveillance systems and limited diagnostic infrastructure. However, rising outbreaks in regions like East Africa are creating awareness and increasing demand for symptomatic care. Access challenges, affordability issues, and fragmented healthcare systems constrain growth. International collaborations and government-backed vaccination efforts are expected to improve treatment adoption gradually across the region.
Market Segmentations:
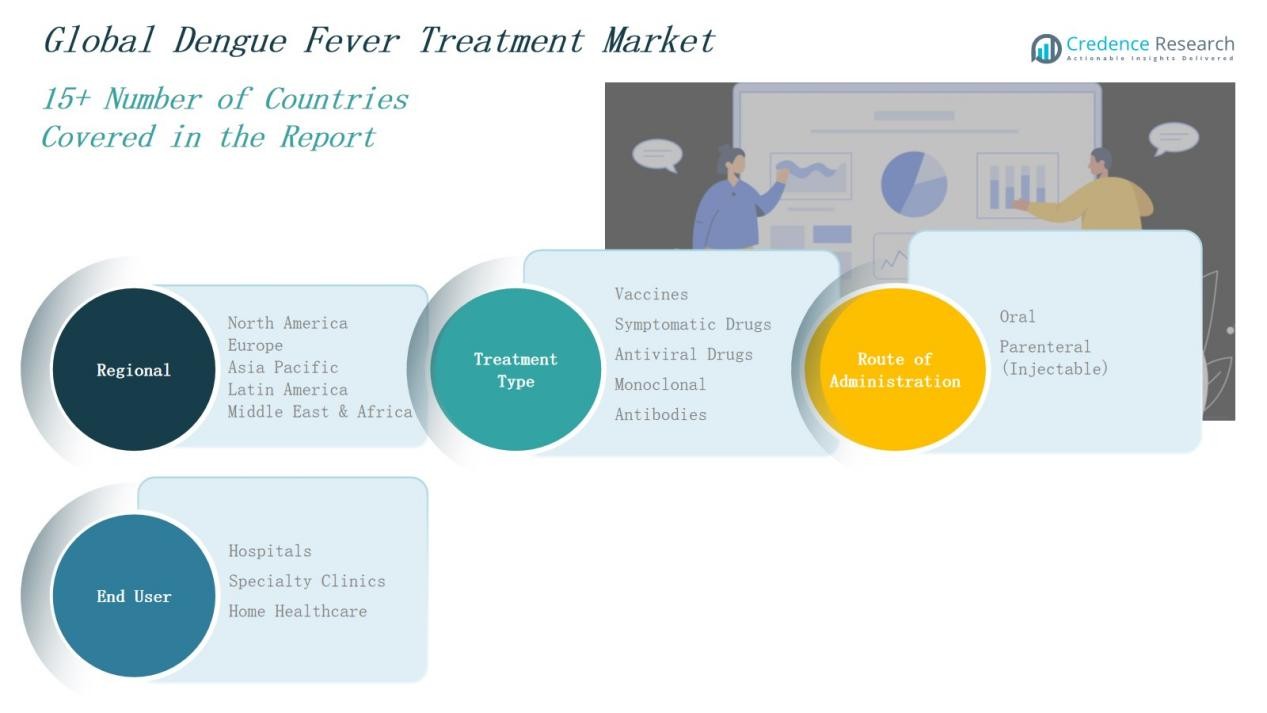
By Treatment Type
- Vaccines
- Symptomatic Drugs
- Antiviral Drugs
- Monoclonal Antibodies
By Route of Administration
- Oral
- Parenteral (Injectable)
By End User
- Hospitals
- Specialty Clinics
- Home Healthcare
By Region
- North America:S., Canada, Mexico
- Europe:UK, France, Germany, Italy, Spain, Russia, Rest of Europe
- Asia Pacific:China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific
- Latin America:Brazil, Argentina, Rest of Latin America
- Middle East:GCC Countries, Israel, Turkey, Rest of Middle East
- Africa:South Africa, Egypt, Rest of Africa
Competitive Landscape
The dengue fever treatment market is moderately consolidated, with global and regional players competing through product innovation, vaccine approvals, and strategic collaborations. Leading companies such as Takeda Pharmaceutical, Sanofi, Pfizer, and GlaxoSmithKline dominate with strong vaccine portfolios and global distribution networks. Their market strength is reinforced by continuous R&D investment, clinical trials for advanced antivirals, and regulatory approvals across endemic regions. Generic drug manufacturers including Sun Pharmaceutical, Teva, and Dr. Reddy’s Laboratories play a vital role by supplying affordable symptomatic drugs widely used in hospitals and home healthcare. Emerging biopharma firms are focusing on monoclonal antibodies and next-generation antivirals, supported by funding from governments and international health agencies. Strategic partnerships, such as collaborations with the WHO and UNICEF for vaccine distribution, strengthen market penetration in Asia-Pacific and Latin America. Competition is also intensifying through pricing strategies, expansion into developing regions, and technology-driven innovations in diagnostics and treatment delivery.
Key Players
- Takeda Pharmaceutical Company
- Sanofi (Sanofi Pasteur)
- Pfizer
- GlaxoSmithKline (GSK)
- Johnson & Johnson (Janssen)
- Abbott Laboratories
- Teva Pharmaceuticals
- Viatris (Mylan)
- Sun Pharmaceutical Industries
- Perrigo Company
- Fresenius Kabi
- Baxter International
- Braun Melsungen AG
- Reddy’s Laboratories
- Cipla
- Aurobindo Pharma
- Lupin
- Zydus Lifesciences
- Serum Institute of India
- Bharat Biotech
- Panacea Biotec
- Biological E.
- Instituto Butantan
Recent Developments
- In June 2025, the Serum Institute of India partnered with DNDi to advance a monoclonal antibody treatment targeting all four dengue virus serotypes, moving into Phase III clinical trials across India, Brazil, and other endemic regions.
- In August 2024, Panacea Biotec, in collaboration with ICMR, initiated a Phase III trial for its dengue vaccine candidate DengiAll in India.
- In February 2024, Takeda Pharmaceutical announced a manufacturing partnership with Biological E. Ltd., scaling production capacity for QDENGA (TAK-003) to 50 million doses annually, with a target of 100 million by 2030.
Report Coverage
The research report offers an in-depth analysis based on Tretament Type, Route of Administration, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for dengue vaccines will continue to expand in endemic regions.
- Pharmaceutical companies will accelerate development of effective antiviral therapies.
- Monoclonal antibodies will gain wider acceptance for severe case management.
- Governments will strengthen immunization programs to reduce hospitalization rates.
- Digital health and telemedicine will improve access to early diagnosis and treatment.
- Home healthcare solutions will see rising adoption for mild and moderate cases.
- Public–private partnerships will drive faster distribution of vaccines and therapies.
- Research collaborations will focus on next-generation multivalent vaccines.
- Awareness campaigns will enhance preventive care and early intervention practices.
- Market players will expand presence in Asia-Pacific and Latin America to meet rising demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Burden of Dengue
The increasing incidence of dengue cases worldwide, with nearly 390 million infections annually, is intensifying the need for effective treatments and driving demand for vaccines, antivirals, and supportive care solutions.
Advancements in Vaccine Development
Innovations and regulatory approvals for new dengue vaccines, such as Qdenga and Dengvaxia, are expanding access and reducing hospitalization rates, especially in endemic regions, fueling market growth.
Government Support and Funding Initiatives
National immunization programs, increased funding for vector control, and partnerships with organizations like WHO and UNICEF are improving treatment access and infrastructure, accelerating market adoption.
Expansion of Monoclonal Antibody Therapies
Recent clinical approvals and promising trial results for monoclonal antibodies are providing new targeted treatment options, particularly for severe cases, and are expected to become a major growth driver.
Growth of Home Healthcare and Telemedicine
The shift toward home-based care, supported by oral symptomatic drugs and telemedicine platforms, is increasing treatment accessibility and reducing the burden on hospitals, especially in Asia Pacific.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dengue Fever Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dengue Fever Treatment Market projected to grow between 2025 and 2032?
Which Dengue Fever Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dengue Fever Treatment Market?
Who are the leading companies in the Dengue Fever Treatment Market?
Which region commanded the largest share of the Dengue Fever Treatment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Specialty Clinics
- 1.2.3 Home Healthcare
- 1.3 By Treatment Type
- 1.3.1 Vaccines
- 1.3.2 Symptomatic Drugs
- 1.3.3 Antiviral Drugs
- 1.3.4 Monoclonal Antibodies
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Parenteral (Injectable)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,419.46 million → 2032: USD 2,810.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dengue Fever Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dengue Fever Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dengue Fever Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dengue Fever Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dengue Fever Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dengue Fever Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dengue Fever Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dengue Fever Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,419.46 million → 2032: USD 2,810.07 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dengue Fever Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Specialty Clinics
- 12.3.7.3 Home Healthcare
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Vaccines
- 12.4.7.2 Symptomatic Drugs
- 12.4.7.3 Antiviral Drugs
- 12.4.7.4 Monoclonal Antibodies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Parenteral (Injectable)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dengue Fever Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dengue Fever Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dengue Fever Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dengue Fever Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Takeda Pharmaceutical Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sanofi
- 18.4 Pfizer
- 18.5 GlaxoSmithKline (GSK)
- 18.6 Johnson & Johnson (Janssen)
- 18.7 Abbott Laboratories
- 18.8 Teva Pharmaceuticals
- 18.9 Sun Pharmaceutical Industries
- 18.10 Serum Institute of India
- 18.11 Bharat Biotech
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

