
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Point and Shoot Camera Market Size 2024 | USD 7,550 million |
| Digital Point and Shoot Camera Market, CAGR | 4% |
| Digital Point and Shoot Camera Market Size 2032 | USD 10,333 million |
Market Overview:
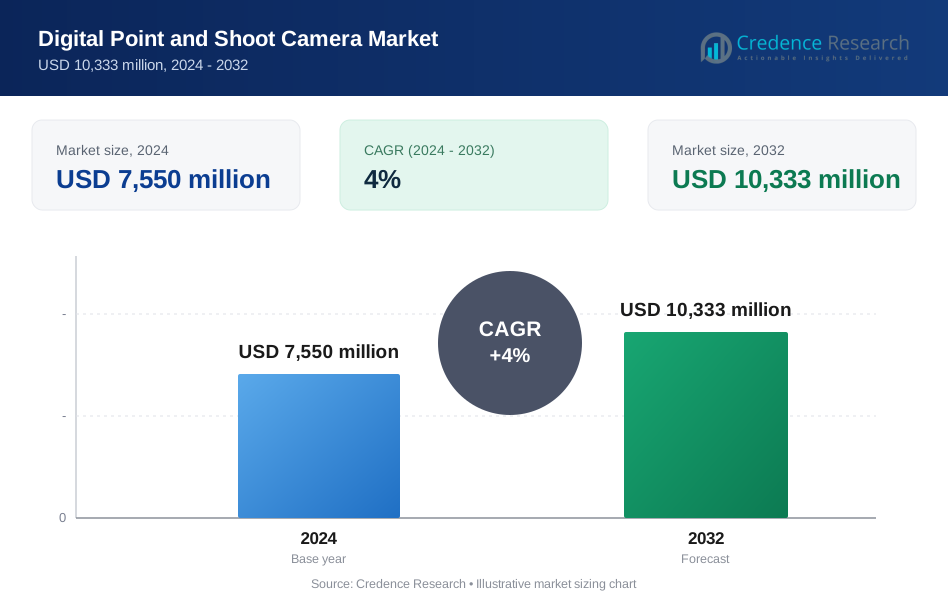
Digital Point and Shoot Camera Market size was valued at USD 7,550 million in 2024 and is anticipated to reach USD 10,333 million by 2032, at a CAGR of 4% during the forecast period (2024-2032).
Market growth is primarily driven by product enhancements such as improved image sensors, faster autofocus systems, extended zoom capabilities, and advanced connectivity options like Wi-Fi and Bluetooth. The growing trend of content creation, especially vlogging and travel photography, supports demand for lightweight yet capable imaging tools. Furthermore, features such as 4K video recording, touchscreen interfaces, and rugged waterproof designs attract users who prefer specialized cameras over multi-functional smartphones. Manufacturers are increasingly targeting segments like youth, outdoor enthusiasts, and budget-conscious consumers by offering value-packed models with user-friendly interfaces. Increased marketing efforts and brand collaborations with influencers are helping revive interest in compact digital cameras. The integration of AI-driven scene recognition and automated settings has further improved the user experience and output quality.
Regionally, Asia Pacific dominates the Digital Point and Shoot Camera Market with the largest market share, supported by rising disposable income, growth in tourism, and a strong consumer electronics manufacturing base in countries like Japan, China, and South Korea. North America holds a significant share due to the presence of leading camera brands, a strong community of digital creators, and increasing interest in travel and lifestyle photography. Europe maintains steady growth, driven by consumer interest in leisure photography and established distribution networks. Emerging markets in Latin America and the Middle East & Africa also present opportunities, particularly as manufacturers explore cost-effective product lines and expand their retail footprint across developing regions. Government support for local electronics production and growing e-commerce penetration are further accelerating camera adoption in these regions. Regional players are also entering strategic partnerships to distribute products efficiently and strengthen brand visibility.
Market Insights:
- The Digital Point and Shoot Camera Market was valued at USD 7,550 million in 2024 and is expected to reach USD 10,333 million by 2032, growing at a CAGR of 4% during the forecast period.
- Demand is rising among content creators, vloggers, and travellers who seek portable, high-quality cameras with minimal setup.
- Advanced features like 4K video recording, AI scene recognition, and fast autofocus systems enhance camera performance and attract tech-savvy users.
- Youth, outdoor enthusiasts, and budget-conscious consumers drive adoption through interest in durable, user-friendly models.
- Smartphone cameras create strong competition, urging manufacturers to innovate and highlight specialized capabilities unique to compact cameras.
- Asia Pacific leads the market with 38% share, driven by strong manufacturing hubs in Japan, China, and South Korea and rising consumer demand.
- North America and Europe maintain steady growth, fueled by active content creation communities, strong retail networks, and high brand loyalty.
Market Drivers:
Rising Demand from Content Creators and Social Media Influencers:
The growing community of content creators and social media influencers drives the demand for compact, high-quality imaging devices. Many prefer point and shoot cameras for their portability, ease of use, and ability to deliver sharp images and videos. The Digital Point And Shoot Camera Market benefits from increased video blogging, travel documentation, and lifestyle content production. It meets the needs of users seeking specialized tools that offer better quality than smartphone cameras. Lightweight designs and user-friendly controls appeal to influencers who require on-the-go performance. Built-in features such as image stabilization and face detection enhance content output and broaden the appeal across user segments.
Technological Advancements in Camera Hardware and Features:
Rapid improvements in image sensor technology, autofocus systems, and optical zoom functionality fuel market growth. The inclusion of 4K video recording, larger sensors, and improved low-light performance makes point and shoot cameras more versatile. It supports a shift toward advanced compact models that cater to both amateur and enthusiast users. Touchscreen interfaces, electronic viewfinders, and manual control options give users greater creative flexibility. These innovations bridge the gap between basic compact cameras and professional-grade devices. The market continues to evolve with AI-powered features that optimize image quality and shooting conditions automatically.
- For instance, Sony’s RX100 VII compact camera incorporates advanced autofocus technology derived from its Alpha series mirrorless cameras, while Canon’s PowerShot G7 X Mark III uses a 1-inch stacked CMOS sensor and 4K video capabilities to appeal to vloggers and content creators.
Increased Appeal Among Hobbyists and Casual Users:
The simplicity and reliability of point and shoot cameras continue to attract casual users and hobbyist photographers. The Digital Point and Shoot Camera Market grows through its accessibility and reduced learning curve compared to DSLR or mirrorless systems. It serves individuals seeking high-quality imagery without complex settings or interchangeable lenses. Travel enthusiasts, parents, and students represent key consumer segments for entry-level and mid-range models. Waterproof and shockproof variants add value for outdoor use and active lifestyles. Compact cameras remain a preferred choice for users who want a separate device dedicated solely to photography.
- For instance, the Olympus Tough TG-6 is widely used by outdoor adventurers for its crushproof, waterproof, and freeze-proof design, and Fujifilm’s X100V has gained a cult following among street photographers for its retro styling and hybrid optical-electronic viewfinder.
Brand Differentiation and Competitive Product Strategies:
Leading manufacturers actively develop distinct models with targeted features to differentiate in a saturated market. It enables brands to capture consumer interest through limited editions, aesthetic designs, and bundled accessories. Competitive pricing and value-added features enhance the appeal among cost-sensitive buyers. Companies also invest in influencer marketing, in-store promotions, and online campaigns to boost visibility. Customer loyalty programs and post-sale support further strengthen brand-consumer relationships. Strategic differentiation helps sustain momentum in the Digital Point And Shoot Camera Market despite rising smartphone penetration.
Market Trends:
Integration of Advanced Features for Enhanced User Experience:
Manufacturers are equipping point and shoot cameras with advanced features to stay relevant in a competitive imaging landscape. The inclusion of 4K video recording, face and eye detection autofocus, and AI-powered scene recognition has improved image quality and usability. The Digital Point and Shoot Camera Market reflects a shift toward intelligent automation that simplifies the photography process for non-professionals. Built-in editing tools, touch interfaces, and wireless connectivity further enhance convenience and real-time sharing. Compact models now offer larger sensors and higher ISO performance, enabling better results in diverse lighting conditions. These advancements attract hobbyists and vloggers who demand quality and functionality in a portable form.
- For instance, Sony’s ZV-1 II is specifically designed for content creators, offering features such as a fully articulating LCD screen, advanced autofocus, 4K video capabilities, and built-in ND filters, making it a top choice for vloggers and video enthusiasts.
Focus on Aesthetic Appeal and Customization:
Design aesthetics and personalization options are gaining importance among younger demographics. Consumers increasingly value the look and feel of their devices, prompting manufacturers to launch stylish, retro-inspired, and limited-edition models. It reflects a broader lifestyle trend where visual appeal plays a key role in purchase decisions. The market sees growing interest in compact cameras that double as fashion accessories while offering practical photography capabilities. Customizable grips, color options, and interchangeable skins help brands cater to niche user preferences. These trends support brand engagement and repeat purchases in the Digital Point and Shoot Camera Market.
- For instance, Fujifilm’s Instax series has gained popularity among younger generations for its unique design elements and vibrant color options, blending nostalgia with modern functionality.
Market Challenges Analysis:
Intense Competition from Smartphone Cameras:
Smartphone advancements pose a significant challenge to the Digital Point and Shoot Camera Market. Consumers often choose high-end smartphones with multi-lens camera systems over standalone compact cameras. It reduces the perceived value of owning a separate device for casual photography. Smartphone integration with social media platforms also enhances real-time sharing and editing capabilities, making them more appealing to everyday users. This shift limits the market’s growth potential among mainstream consumers. Manufacturers must innovate continually to justify the relevance of point and shoot models in a smartphone-dominated environment.
- For instance, a Corning Gorilla Glass survey commissioned to TRUE Global Intelligence found that the camera is now a key factor in smartphone purchase decisions, with Indian consumers specifically highlighting the importance of features such as the number of camera lenses, image clarity, and light capture when evaluating smartphones.
Limited Differentiation and Price Sensitivity:
Many digital point and shoot models offer similar features, which creates challenges in product differentiation. Price-sensitive consumers often compare compact cameras to budget smartphones or entry-level mirrorless options, putting pressure on pricing strategies. It affects profitability and slows premium product adoption in emerging markets. Brands struggle to maintain strong value propositions without unique selling points or targeted feature sets. This challenge forces manufacturers to balance affordability with performance, often requiring cost trade-offs. Sustaining brand loyalty under such conditions becomes increasingly difficult.
Market Opportunities:
Expansion into Niche Consumer Segments and Specialized Use Cases:
The Digital Point and Shoot Camera Market holds strong potential in niche segments such as outdoor enthusiasts, underwater photographers, and children’s photography. It can serve users who require rugged, waterproof, and user-friendly devices for specific environments. Brands that design compact cameras with unique features for sports, wildlife, or travel experiences can capture new demand. Educational kits for young users and cameras for senior citizens with simplified interfaces offer further growth avenues. Manufacturers that address these distinct user groups with tailored solutions gain a competitive advantage. These specialized markets remain underserved by smartphones and create room for product differentiation.
Growth Through Technological Innovation and Smart Integration:
Opportunities emerge from integrating smart technology and cloud-based ecosystems into digital compact cameras. The Digital Point and Shoot Camera Market can grow by aligning with consumer preferences for wireless sharing, remote operation, and AI-enhanced image processing. Cameras that sync seamlessly with mobile apps and editing platforms enhance workflow efficiency for casual and semi-professional users. Voice control, GPS tagging, and real-time cloud storage add functional value beyond traditional photography. Companies that invest in R&D and software capabilities can transform compact cameras into connected lifestyle tools. These innovations position point and shoot models as complementary rather than competing devices to smartphones.
Market Segmentation Analysis:
By Product Type
The Digital Point and Shoot Camera Market includes built-in lens cameras and zoom lens cameras. Built-in lens cameras lead the segment due to their compact size, lightweight design, and affordability. These models appeal to casual users who prioritize convenience over complex functionality. Zoom lens cameras attract photography enthusiasts and travellers who require greater focal range and optical clarity. Brands continue to improve both variants with features such as image stabilization, high-resolution sensors, and video recording capabilities. The availability of water-resistant and rugged designs adds further value to the zoom lens category.
By Application
The market is segmented into personal and commercial applications. Personal use dominates, supported by the growing number of content creators, travel enthusiasts, and everyday users capturing moments on dedicated devices. Compact cameras remain popular for their ease of operation and superior image quality compared to smartphones in specific conditions. The commercial segment includes usage by educational institutions, field researchers, and businesses creating marketing content. It benefits from organizations seeking reliable, cost-effective photography solutions for non-professional settings. The rise in promotional media and visual documentation enhances demand in this category.
By Distribution Channel
Distribution channels include offline and online retail platforms. Offline channels such as electronics stores and brand-exclusive outlets maintain strong consumer preference due to hands-on experience and in-store assistance. It supports purchases through real-time demonstrations and after-sales service. Online channels gain momentum through digital convenience, wider product variety, and better deals. E-commerce platforms enable manufacturers to reach broader geographies, especially where retail infrastructure is limited. Promotions, user reviews, and comparison tools influence purchasing decisions in the online segment.
Segmentations:
By Product Type
- Built-in Lens Cameras
- Zoom Lens Cameras
By Application
- Personal Use
- Commercial Use
By Distribution Channel
- Offline Retail
- Online Retail
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia Pacific Leads with Manufacturing Strength and Rising Consumer Demand
Asia Pacific held 38% of the global Digital Point and Shoot Camera Market in 2024, the highest among all regions. Japan, China, and South Korea contribute significantly to this share through their advanced manufacturing infrastructure and strong consumer base. Countries in this region drive production efficiency and technological innovation in compact cameras. It benefits from rising disposable income and a growing middle class in urban areas. Increased interest in travel, photography, and digital content creation further supports camera adoption. E-commerce expansion and regional brand accessibility make products available across diverse markets. Frequent product updates and competitive pricing strategies sustain regional momentum.
North America Benefits from a Strong Creator Economy and Brand Presence
North America accounted for 28% of the global Digital Point and Shoot Camera Market in 2024, making it the second-largest region. This market benefits from a high concentration of content creators and strong demand for digital imaging tools. It grows through consistent adoption among vloggers, travellers, and photography enthusiasts. Brands such as Canon, Sony, and Nikon maintain a strong regional presence supported by loyal customer bases. Retail and online platforms ensure widespread product availability and frequent promotional activity. Integration with social media platforms influences purchase behavior across younger demographics. Consumer expectations for high performance and ease of use shape product development strategies.
Europe Shows Steady Growth Driven by Leisure Photography and Design Preferences
Europe held 21% of the global Digital Point and Shoot Camera Market in 2024, supported by stable demand and design-conscious consumers. The region values quality, aesthetics, and functional design, driving interest in compact models for travel and leisure photography. Countries such as Germany, France, and the United Kingdom serve as key markets due to their established distribution and retail systems. It benefits from a steady tourism sector and rising youth participation in digital storytelling. Brands respond to European preferences with retro-style models and limited editions. Demand remains consistent for compact, durable devices suited for casual and lifestyle photography.
Key Player Analysis:
- Canon Inc.
- Ricoh Company, Ltd.
- Leica Camera AG
- Nikon Corporation
- Sony Corporation
- Panasonic Corporation
- Polaroid Corporation
- Pentax Corporation
- Fujifilm Holdings Corporation
Competitive Analysis:
The Digital Point and Shoot Camera Market features strong competition among established players such as Canon Inc., Nikon Corporation, Sony Corporation, Panasonic Corporation, and Fujifilm Holdings Corporation. These companies invest consistently in product innovation, compact design, and advanced imaging features to maintain market relevance. It benefits from brand loyalty and global distribution networks that enhance market reach. New entrants face high barriers due to strong brand presence and technological expertise of existing players. Companies differentiate by offering models tailored to specific user segments like vloggers, travellers, and beginners. Marketing strategies focus on online visibility, influencer collaborations, and bundled accessories to attract modern consumers. Continuous improvements in autofocus, low-light performance, and wireless connectivity remain key focus areas for sustaining competitive advantage.
Recent Developments:
- In June 2023, Canon launched the EOS R100, another APS-C mirrorless camera designed for entry-level users.
- In May 2024, Canon announced the ongoing development of the EOS R1, a full-frame mirrorless camera with a new image processor (DIGIC Accelerator) and advanced deep learning autofocus, targeting a 2024 release.
- In April 2025, Nikon launched the Z5II, a full-frame mirrorless camera with advanced autofocus, powerful low-light performance, and a 5-axis in-body stabilization system, catering to both professionals and enthusiasts.
Market Concentration & Characteristics:
The Digital Point and Shoot Camera Market displays moderate to high market concentration, with a few global players controlling a significant share. It is characterized by strong brand dominance, steady technological upgrades, and a focus on user-friendly, compact designs. Market leaders differentiate through innovation in image quality, video capabilities, and wireless integration. Product life cycles remain short due to rapid feature updates and evolving consumer preferences. The market caters to both entry-level and mid-range users, emphasizing portability and ease of use. Price sensitivity influences purchasing behavior, prompting brands to balance cost-efficiency with performance. Retail and e-commerce channels play a critical role in shaping consumer access and brand exposure. Strategic partnerships with content creators and targeted digital marketing campaigns enhance customer engagement and drive brand loyalty. Sustainability and eco-friendly materials are gaining importance as consumer awareness grows across key markets.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Manufacturers will integrate AI-driven features such as scene recognition and real-time image optimization to enhance user experience.
- Compact cameras will offer 4K and 8K video recording capabilities, catering to content creators and vloggers.
- The market will see a rise in rugged and waterproof models designed for outdoor enthusiasts and adventure photography.
- Retro-inspired designs and customizable aesthetics will attract younger consumers seeking unique and stylish devices.
- Improved wireless connectivity, including seamless integration with smartphones and cloud services, will become standard.
- Manufacturers will focus on sustainability by using eco-friendly materials and promoting recyclable components.
- Emerging markets in Asia, Latin America, and Africa will present growth opportunities due to increasing disposable incomes and interest in photography.
- The demand for instant printing features will grow, combining digital photography with tangible photo outputs.
- Enhanced low-light performance and optical zoom capabilities will be key differentiators among competing models.
- Collaborations with social media platforms will enable direct sharing features, appealing to the always-connected generation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Digital Point and Shoot Camera Market?
What is driving the growth of this market?
Which features are attracting buyers to point and shoot cameras?
Which region leads the market and why?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Digital Point and Shoot Camera Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Digital Point and Shoot Camera Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,550 million → 2032: USD 10,333 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Digital Point and Shoot Camera Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Digital Point and Shoot Camera Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Digital Point and Shoot Camera Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Digital Point and Shoot Camera Market Drivers
- 3.3 Digital Point and Shoot Camera Market Restraints & Challenges
- 3.4 Digital Point and Shoot Camera Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Digital Point and Shoot Camera Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Digital Point and Shoot Camera Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Digital Point and Shoot Camera category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Digital Point and Shoot Camera Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Digital Point and Shoot Camera Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Digital Point and Shoot Camera. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Digital Point and Shoot Camera Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Digital Point and Shoot Camera Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Digital Point and Shoot Camera Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Digital Point and Shoot Camera (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Digital Point and Shoot Camera
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Digital Point and Shoot Camera Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Digital Point and Shoot Camera Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Digital Point and Shoot Camera Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Digital Point and Shoot Camera Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Digital Point and Shoot Camera Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Digital Point and Shoot Camera Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Digital Point and Shoot Camera Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Digital Point and Shoot Camera Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
