
Market Overview:
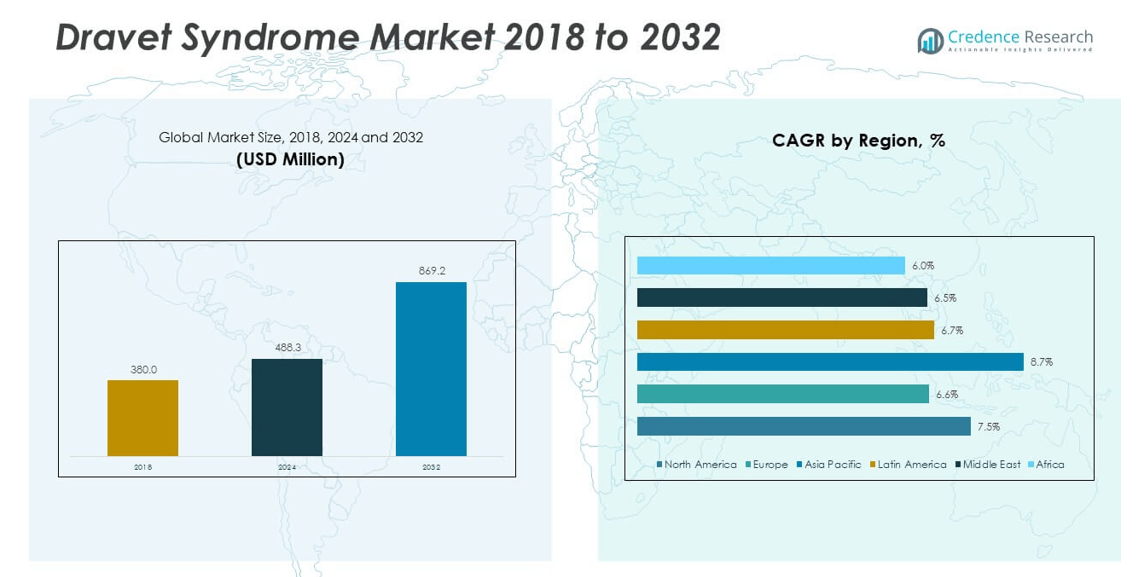
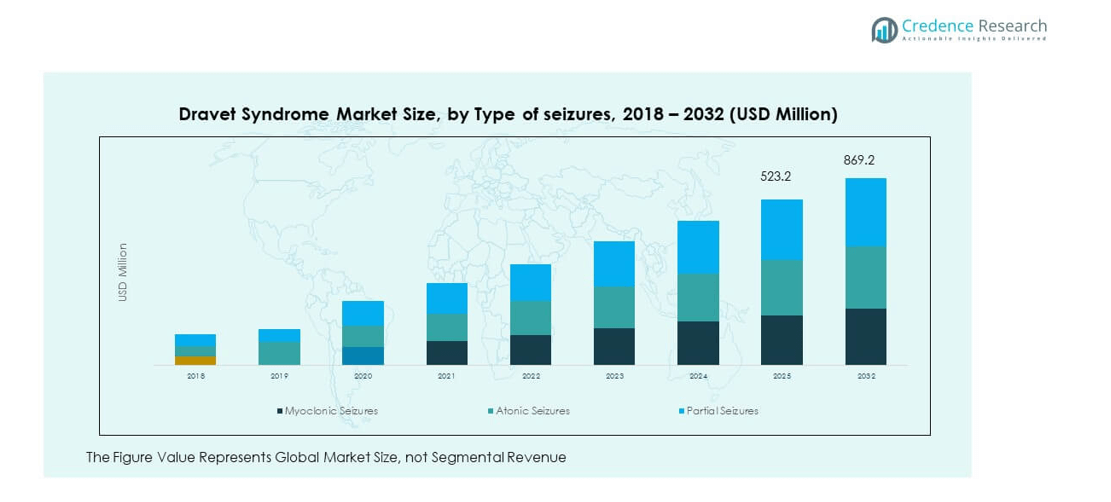
The Global Dravet Syndrome Market size was valued at USD 380.0 million in 2018 to USD 488.3 million in 2024 and is anticipated to reach USD 869.2 million by 2032, at a CAGR of 7.50% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dravet Syndrome Market Size 2024 | USD 488.3 million |
| Dravet Syndrome Market, CAGR | 7.50% |
| Dravet Syndrome Market Size 2032 | USD 869.2 million |
Growth in the Global Dravet Syndrome Market is driven by rising awareness of rare epileptic disorders, increasing diagnosis rates, and expanding access to advanced therapies. The market benefits from ongoing research initiatives and clinical trials focused on improving treatment efficacy and safety. Demand is further supported by government and non-profit programs that emphasize patient support, rare disease management, and drug development incentives. The introduction of novel therapies and expansion of orphan drug designations strengthen the market, while improvements in healthcare infrastructure enable earlier intervention and better patient outcomes.
Regionally, North America leads the market due to strong healthcare infrastructure, high diagnosis rates, and favorable regulatory frameworks that encourage innovation. Europe follows closely, supported by government-backed rare disease initiatives and well-established healthcare reimbursement systems. The Asia-Pacific region is emerging as a high-growth market, driven by rising healthcare investments, improving awareness, and the increasing availability of advanced therapies. Latin America and the Middle East & Africa show gradual progress, supported by expanding medical access and partnerships with global healthcare organizations.
Market Insights:
- The Global Dravet Syndrome Market size was valued at USD 380.0 million in 2018, grew to USD 488.3 million in 2024, and is projected to reach USD 869.2 million by 2032, expanding at a CAGR of 7.50%.
- Strong growth is driven by rising awareness of rare epileptic disorders and improved diagnosis through genetic testing and advanced imaging.
- Regulatory support and orphan drug designations encourage pharmaceutical companies to invest in innovative therapies with favorable incentives.
- High treatment costs and limited accessibility in low- and middle-income countries remain key restraints, impacting affordability and adoption.
- North America leads the market with strong healthcare infrastructure and favorable reimbursement policies supporting advanced therapies.
- Europe maintains a significant share due to government-backed rare disease programs and established treatment frameworks.
- Asia-Pacific emerges as a high-growth region with rising healthcare investments, improved awareness, and expanding clinical trial participation.
Market Drivers:
Increasing Focus on Rare Disease Awareness and Early Diagnosis:
The Global Dravet Syndrome Market expands steadily with rising awareness of rare epileptic disorders and the importance of timely diagnosis. Patient advocacy groups and healthcare organizations conduct initiatives that highlight the severity of the condition and encourage early medical consultation. Early diagnosis helps physicians initiate treatments that reduce long-term complications and improve patient outcomes. Government programs supporting rare disease awareness contribute to this momentum. Pharmaceutical companies align their strategies with awareness campaigns to improve access to novel therapies. Medical professionals emphasize better training to recognize symptoms and improve detection rates. Advances in diagnostic imaging and genetic testing provide clinicians with reliable tools to confirm cases. This growing awareness creates a broader patient pool eligible for specialized treatment options.
- For instance, The Dravet Syndrome Foundation reported that their awareness campaigns resulted in over 45,000 individuals reached through educational initiatives in 2023, improving referral rates for early diagnosis across the US and Europe.
Expanding Orphan Drug Designation and Strong Regulatory Support:
The Global Dravet Syndrome Market benefits significantly from orphan drug designations granted by regulatory authorities in major markets. These incentives include tax credits, research grants, and market exclusivity, which encourage pharmaceutical companies to develop novel therapies. It creates favorable conditions for investments in advanced drug pipelines. Regulatory agencies collaborate with medical research bodies to accelerate the approval process for life-saving drugs. Such measures reduce the time-to-market for treatments and provide patients with timely access to new therapies. The availability of regulatory support drives competitive activity and fosters innovation. Strong compliance frameworks ensure that approved drugs meet safety and efficacy standards. Global harmonization of regulations further improves cross-border availability. This framework continues to be a key driver of market growth.
- For instance, Zogenix (now part of UCB) received orphan drug designation for Fintepla (fenfluramine) in both the US and EU, enabling expedited development and exclusivity. As of 2024, Fintepla is approved and administered to over 7,000 patients worldwide with Dravet Syndrome.
Growing Clinical Research Activities and Advancements in Treatment Modalities:
The Global Dravet Syndrome Market gains strength from ongoing clinical research programs and advancements in drug development. Pharmaceutical companies and academic institutions focus on exploring new therapeutic mechanisms to improve seizure control. Increased collaboration across industry stakeholders fosters the exchange of knowledge and expertise. Innovative treatment modalities such as gene therapy and targeted molecular approaches expand possibilities for patients. Improved formulations reduce side effects and enhance long-term management of the condition. The industry experiences steady funding inflows from both private investors and public agencies. Clinical trials bring valuable data that helps refine treatment protocols. Expanded global participation in trials ensures better representation of diverse patient populations. This momentum directly supports stronger adoption of novel therapeutic solutions.
Rising Patient Support Initiatives and Improved Healthcare Infrastructure:
The Global Dravet Syndrome Market grows with patient support initiatives that address unmet medical needs. Non-profit organizations and advocacy groups play a vital role in connecting patients with treatment resources. Expansion of healthcare infrastructure in developed and emerging regions allows improved access to advanced therapies. Hospitals and specialty clinics establish dedicated neurology units that enhance treatment availability. Insurance coverage and reimbursement programs reduce the financial burden for patients and families. Governments prioritize rare disease management as part of broader healthcare reforms. Telemedicine solutions improve accessibility for patients in remote areas. Healthcare professionals adopt multidisciplinary approaches to provide comprehensive care. It strengthens the overall framework for effective management of Dravet Syndrome.
Market Trends:
Increasing Role of Precision Medicine and Personalized Therapies:
The Global Dravet Syndrome Market shows a rising trend toward precision medicine and personalized therapy options. Genetic testing provides critical insights into individual patient profiles, enabling tailored treatment plans. Precision-based approaches reduce trial-and-error in treatment selection. Pharmaceutical companies invest in advanced research that focuses on identifying patient-specific responses to drugs. Physicians use data-driven platforms to adjust treatment strategies based on real-time feedback. Personalized therapy improves adherence and outcomes by addressing unique patient needs. Research highlights gene-targeted therapies that offer potential breakthroughs. The market continues to move toward integrating molecular biology insights into treatment design. It creates a more effective and patient-centric healthcare model.
Integration of Digital Health Solutions and Remote Monitoring Systems:
The Global Dravet Syndrome Market embraces digital health innovations and remote monitoring technologies. Wearable devices and connected applications provide continuous seizure tracking and patient health data. Remote consultations enable timely intervention, reducing risks associated with severe episodes. Healthcare providers use digital platforms to monitor patient progress and adjust therapy plans. Integration of artificial intelligence supports predictive analysis of seizure patterns. Families gain tools for proactive management through mobile apps and digital support communities. Telemedicine adoption improves patient access in rural and underserved regions. Digital health platforms also foster clinical data collection for research. This trend strengthens the link between technology and patient care.
- For instance, Seer Medical reported hours of seizure data collected via wearable EEG technology across rare epilepsy populations since 2022, supporting AI-driven predictive analysis.
Expansion of Collaborative Research and Global Partnerships in Rare Diseases:
The Global Dravet Syndrome Market advances with expanded collaborative research and global partnerships. Universities, biotech firms, and large pharmaceutical companies pool resources to accelerate innovation. International collaborations ensure knowledge sharing across regions with varying expertise. Joint ventures provide financial stability to long-term research programs. Rare disease research gains visibility through cross-border initiatives. Partnerships with patient advocacy organizations improve trial participation rates. Clinical research networks facilitate multicenter studies for stronger clinical evidence. Such collaborations reduce duplication of efforts and optimize resource utilization. This trend builds momentum for breakthrough therapies with global impact.
- For instance, Teladoc Health’s telemedicine platforms facilitated neurologist consultations for epilepsy and rare seizure disorders in 2023, expanding access particularly in rural areas.
Rising Focus on Adjunctive Therapies and Holistic Care Approaches:
The Global Dravet Syndrome Market evolves with a growing emphasis on adjunctive therapies and holistic care. Alongside drug therapies, dietary interventions like ketogenic diets support seizure management. Physicians recommend physiotherapy and psychological support to improve quality of life. Holistic care frameworks address not only medical symptoms but also mental and emotional health. Caregivers receive guidance on lifestyle management strategies for patients. Multidisciplinary teams coordinate care involving neurologists, psychologists, and dietitians. The approach reduces treatment gaps and strengthens patient well-being. Adjunctive therapies complement primary treatments, creating comprehensive management solutions. This shift reflects a broader acceptance of patient-centric healthcare.
Market Challenges Analysis:
High Cost of Treatment and Limited Accessibility to Advanced Therapies:
The Global Dravet Syndrome Market faces challenges due to the high cost of treatment and limited accessibility to advanced therapies. Many therapies come with premium pricing linked to research intensity and orphan drug status. This creates affordability issues for patients, especially in regions with weak reimbursement structures. In lower-income countries, access to advanced drugs remains restricted. Healthcare inequalities limit the availability of specialists trained to manage Dravet Syndrome effectively. Patients in remote areas face additional difficulties in reaching tertiary care facilities. Even when therapies are available, ongoing treatment costs strain family budgets. Insurance programs vary widely across countries, affecting patient support. The gap between availability and affordability continues to limit widespread adoption.
Complex Clinical Nature and Limited Awareness Among Healthcare Professionals:
The Global Dravet Syndrome Market encounters obstacles due to the complex clinical nature of the disorder and limited awareness among healthcare professionals. Diagnosis remains difficult as symptoms often overlap with other epileptic conditions. Many physicians in general practice lack the expertise to identify early signs. Delayed diagnosis prevents timely initiation of effective therapies. Limited awareness also leads to underreporting of cases, restricting accurate prevalence data. Without reliable statistics, healthcare planning becomes less effective. Complex management protocols demand specialized knowledge and resources. Multidisciplinary collaboration often falls short due to fragmented healthcare systems. These challenges slow the pace of consistent patient care improvements.
Market Opportunities:
Advancements in Gene Therapy and Next-Generation Treatment Options:
The Global Dravet Syndrome Market presents strong opportunities with advancements in gene therapy and next-generation treatments. Innovative therapeutic platforms target underlying genetic mutations, offering the potential for long-term disease control. Investment in biotechnology fosters rapid progress in these cutting-edge solutions. Clinical trials for gene therapies attract global attention and funding. These therapies hold the promise of reducing seizure frequency and improving cognitive development. Patient communities actively support research and accelerate trial participation. Governments extend financial backing for research into breakthrough treatments. It creates a favorable environment for the commercialization of advanced solutions.
Expansion into Emerging Markets and Improved Global Patient Support Networks:
The Global Dravet Syndrome Market finds new opportunities in emerging economies with expanding healthcare infrastructure. Rising investments in rare disease treatment facilities broaden patient access. Governments in Asia-Pacific and Latin America increase funding for rare disease management. Global advocacy networks strengthen collaborations with local organizations. Improved awareness campaigns help identify more patients for clinical trials and therapies. Pharmaceutical companies establish market entry strategies targeting high-growth regions. Digital health solutions enhance reach into underserved populations. This expansion aligns with the growing global focus on equitable healthcare. It fosters broader adoption of innovative treatment solutions worldwide.
Market Segmentation Analysis:
By Type of Seizures
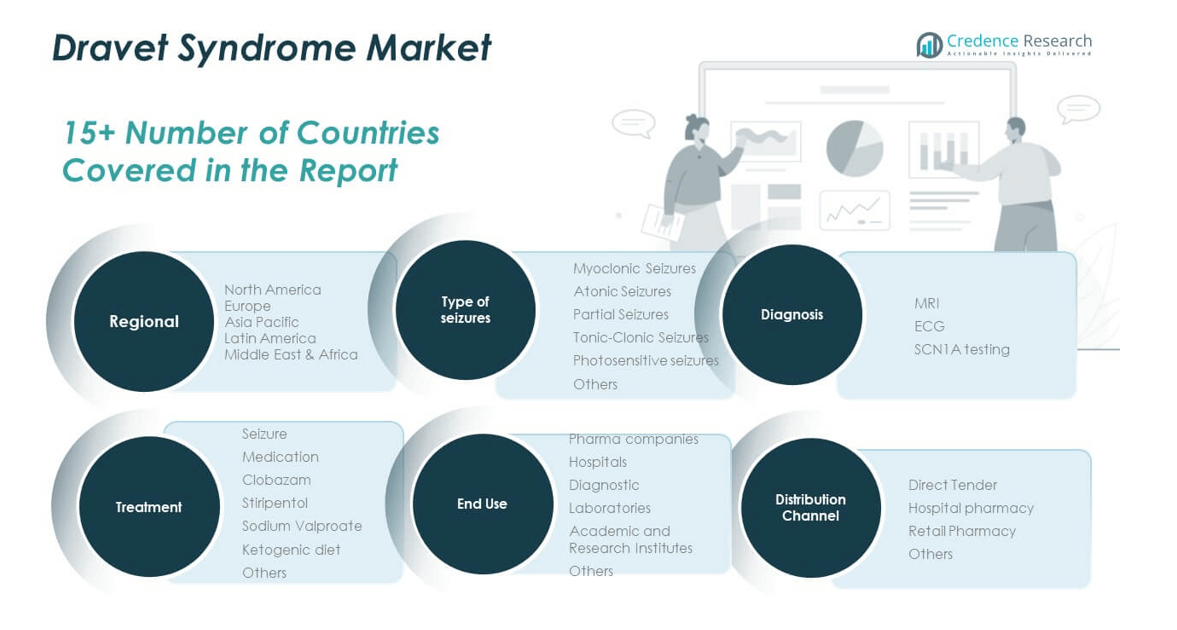
The Global Dravet Syndrome Market is segmented by seizure types including myoclonic, atonic, partial, tonic-clonic, photosensitive, and others. Tonic-clonic seizures and myoclonic seizures dominate due to their high prevalence and significant clinical impact. Partial and photosensitive seizures represent smaller shares but remain crucial in determining treatment needs. Each category requires targeted therapeutic approaches, driving demand for specialized medications and care frameworks. It highlights the importance of seizure-specific management strategies in shaping overall market demand.
- For instance, Zogenix Fintepla (fenfluramine) has demonstrated efficacy specifically in reducing tonic-clonic seizures by an average of 74 seizures per 28 days in clinical trials involving over 340 Dravet patients, showcasing a targeted approach in seizure type management.
By Diagnosis
Diagnosis is led by SCN1A testing, which provides the most accurate method for confirming the genetic basis of Dravet Syndrome. MRI and ECG serve as complementary diagnostic tools that help in identifying neurological and cardiac complications associated with the condition. The adoption of advanced genetic testing increases early detection rates and ensures precise treatment planning. It demonstrates a shift toward precision-based diagnostics, improving patient outcomes and supporting market growth.
- For instance, Invitae’s SCN1A genetic test processed epilepsy-related diagnostic panels in 2024, enabling early and confirmed diagnosis in suspected Dravet cases. Additionally, advanced MRI protocols developed at UCSF led to the identification of subtle neurological changes in genetically confirmed Dravet patients across a cohort of 150 individuals, refining diagnostic accuracy.
By Treatment
Medication forms the largest share of the treatment segment, with clobazam, stiripentol, and sodium valproate serving as primary therapeutic options. Seizure management frameworks and ketogenic diets act as effective complementary solutions. Other treatment approaches continue to evolve, focusing on reducing side effects and improving quality of life. Hospitals and physicians emphasize tailored therapeutic combinations to address diverse seizure patterns. It underscores the critical role of pharmacological and non-pharmacological solutions in long-term disease control.
By End-Use and Distribution Channel
Pharmaceutical companies and hospitals lead the end-use segment, supported by diagnostic centers and academic institutes that contribute to research and patient evaluation. Laboratories enhance testing capabilities to improve early detection. In distribution, hospital pharmacies dominate with structured delivery systems, while direct tenders support bulk procurement. Retail pharmacies remain essential for patient-level accessibility, especially in developed regions. It reflects a balanced ecosystem where healthcare providers, institutions, and supply channels collectively drive market growth.
Segmentation:
By Type of Seizures
- Myoclonic Seizures
- Atonic Seizures
- Partial Seizures
- Tonic-Clonic Seizures
- Photosensitive Seizures
- Others
By Diagnosis
- MRI
- ECG
- SCN1A Testing
By Treatment (Screen Size Segment in outline)
- Seizure Management
- Medication
- Clobazam
- Stiripentol
- Sodium Valproate
- Ketogenic Diet
- Others
By End-Use
- Pharma Companies
- Hospitals
- Diagnostic Centers
- Laboratories
- Academic and Research Institutes
- Others
By Distribution Channel
- Direct Tender
- Hospital Pharmacy
- Retail Pharmacy
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Dravet Syndrome Market size was valued at USD 140.5 million in 2018 to USD 178.4 million in 2024 and is anticipated to reach USD 317.1 million by 2032, at a CAGR of 7.5% during the forecast period. North America accounts for 36.5% of the global market in 2024, holding the largest share due to its advanced healthcare infrastructure and strong presence of leading pharmaceutical companies. The region benefits from favorable reimbursement policies that support access to high-cost therapies. Patient advocacy groups play a pivotal role in raising awareness and driving participation in clinical trials. Regulatory agencies such as the FDA accelerate the approval of orphan drugs, enhancing treatment availability. Growing adoption of precision medicine and digital health solutions strengthens patient management. It continues to lead research initiatives, with universities and biotech firms investing heavily in innovative therapies. The region remains the most mature and influential market, setting benchmarks for treatment standards globally.
Europe
The Europe Global Dravet Syndrome Market size was valued at USD 80.9 million in 2018 to USD 99.0 million in 2024 and is anticipated to reach USD 164.1 million by 2032, at a CAGR of 6.6% during the forecast period. Europe represents 20.3% of the global market in 2024, supported by strong government-backed rare disease programs and coordinated healthcare policies across member states. The European Medicines Agency provides structured regulatory pathways that promote drug development and approval. Patient registries and cross-country collaborations improve case tracking and clinical research. The region emphasizes comprehensive care through public healthcare systems, ensuring wider treatment access. Countries like Germany, France, and the UK lead in advanced drug adoption, while Eastern Europe shows gradual improvement in infrastructure. Awareness initiatives by patient advocacy organizations strengthen diagnosis rates. It maintains a balanced growth trajectory supported by stable healthcare funding and regional collaborations.
Asia Pacific
The Asia Pacific Global Dravet Syndrome Market size was valued at USD 100.7 million in 2018 to USD 134.7 million in 2024 and is anticipated to reach USD 262.0 million by 2032, at a CAGR of 8.7% during the forecast period. Asia Pacific holds 27.6% of the global market in 2024, making it the fastest-growing regional segment. Rising healthcare investments and expanding infrastructure improve access to advanced treatments across major economies such as China, Japan, and India. Governments in the region increase funding for rare diseases and encourage clinical research participation. Growing awareness campaigns support earlier diagnosis and stronger adoption of therapies. The expansion of biotechnology firms and partnerships with multinational companies boost drug availability. Telemedicine and digital health platforms play a significant role in improving patient access in rural areas. It is expected to continue outpacing other regions in growth, driven by high demand and rising healthcare spending.
Latin America
The Latin America Global Dravet Syndrome Market size was valued at USD 27.7 million in 2018 to USD 35.3 million in 2024 and is anticipated to reach USD 59.0 million by 2032, at a CAGR of 6.7% during the forecast period. Latin America represents 7.2% of the global market in 2024, reflecting steady but limited growth compared to developed regions. Brazil and Mexico remain key contributors due to their relatively advanced healthcare systems. Regional governments are gradually expanding rare disease coverage in public health programs. Access to innovative therapies is still restricted by high treatment costs and uneven reimbursement frameworks. International partnerships with non-profits and advocacy groups support awareness initiatives. Clinical trial participation is rising, particularly in larger economies with stronger research networks. It continues to grow, but affordability and infrastructure gaps remain key barriers.
Middle East
The Middle East Global Dravet Syndrome Market size was valued at USD 19.4 million in 2018 to USD 23.7 million in 2024 and is anticipated to reach USD 39.2 million by 2032, at a CAGR of 6.5% during the forecast period. The Middle East accounts for 4.9% of the global market in 2024, with growth supported by investments in healthcare modernization. Wealthier nations such as Saudi Arabia and the UAE lead the region in adopting advanced therapies. Government initiatives to improve rare disease management strengthen access in urban centers. However, disparities in healthcare infrastructure limit broader adoption across lower-income countries. The region has shown interest in fostering international partnerships to accelerate drug availability. Awareness levels remain lower compared to North America and Europe, slowing early diagnosis. It is expected to record steady growth with ongoing healthcare reforms and rising private sector participation.
Africa
The Africa Global Dravet Syndrome Market size was valued at USD 10.7 million in 2018 to USD 17.1 million in 2024 and is anticipated to reach USD 27.8 million by 2032, at a CAGR of 6.0% during the forecast period. Africa accounts for 3.5% of the global market in 2024, making it the smallest contributor. Limited healthcare infrastructure and weak reimbursement frameworks constrain access to advanced therapies. Most patients rely on basic antiepileptic drugs due to affordability issues. Rare disease awareness remains low, leading to delayed diagnosis and underreporting of cases. International non-profits and NGOs play a key role in bridging treatment gaps. Partnerships with global healthcare organizations focus on improving training and early detection. Telemedicine adoption is gradually increasing in select countries to reach underserved populations. It holds long-term growth potential, but progress depends heavily on external collaborations and healthcare investments.
Key Player Analysis:
- Stoke Therapeutics (USA)
- Lundbeck A/S (Denmark)
- Sanofi (France)
- Biocodex S.A. (France)
- Jazz Pharmaceuticals plc (Ireland)
- Ovid Therapeutics Inc. (USA)
- AbbVie Inc. (USA)
- PTC Therapeutics Inc. (USA)
- Epygenix Therapeutics Inc. (USA)
- Marinus Pharmaceuticals Inc. (USA)
- Neurocrine Biosciences Inc. (USA)
- Aquestive Therapeutics Inc. (USA)
- Anavex Life Sciences Corp. (USA)
- Supernus Pharmaceuticals Inc. (USA)
- Xenon Pharmaceuticals Inc. (Canada)
- Zydus Lifesciences Ltd. (India)
- Sun Pharmaceutical Industries Ltd. (India)
- Lupin Ltd. (India)
Competitive Analysis:
The Global Dravet Syndrome Market is moderately fragmented, with pharmaceutical leaders, biotech innovators, and regional players competing to develop advanced therapies. Companies focus on orphan drug designations, gene therapy research, and combination drug regimens to strengthen their portfolios. Strategic collaborations between industry and academia accelerate clinical trial success and expand patient access. Established firms such as Sanofi, Jazz Pharmaceuticals, and Lundbeck maintain dominance through strong pipelines and regulatory support. Emerging companies like Stoke Therapeutics and Epygenix Therapeutics drive innovation in genetic and molecular therapies. It continues to witness high investment in R&D, with competition intensifying around targeted therapies, digital health integration, and precision medicine solutions.
Recent Developments:
- In February 2025, Stoke Therapeutics (USA) entered a global partnership with Biogen to co-develop zorevunersen, an investigational antisense oligonucleotide for Dravet syndrome. This agreement includes a $165million upfront payment to Stoke and the initiation of the global Phase 3 EMPEROR trial. Zorevunersen is set to become the first disease-modifying therapy for Dravet syndrome, aiming to boost SCN1A gene activity and help normalize nerve signaling. For instance, Biogen will lead commercialization outside North America, while Stoke retains North American rights, with over 80 patients already treated in earlier trials.
- On October 14, 2024, Lundbeck A/S (Denmark) announced its $2.6billion acquisition of Longboard Pharmaceuticals. This acquisition enhances Lundbeck’s neuroscience pipeline by adding bexicaserin, currently in a global Phase 3 trial for seizures associated with Dravet syndrome. For instance, the ongoing DEEp SEA Study targets children as young as two years, extending Lundbeck’s rare epilepsy leadership.
- On May 27, 2025, Sanofi (France) completed the acquisition of DR-0201 from Dren Bio for an upfront payment of $600million, bolstering Sanofi’s immunology pipeline. While this deal doesn't mention a Dravet-specific asset, Sanofi’s broader M&A moves in rare diseases, such as the $9.5billion acquisition of Blueprint Medicines (June 2025), seek to expand early-stage assets that could impact treatment innovation. For instance, Sanofi’s rare disease M&A spending exceeded $10billion in 2025.
- In November 2024, Biocodex S.A. (France) announced the development of a new oral-suspension formulation for DIACOMIT (stiripentol), the only FDA-approved Dravet-specific treatment indicated for patients six months and older. The new formula will serve children unable to swallow capsules, enhancing administration ease. For instance, DIACOMIT is now available in more than 55 countries worldwide.
Market Concentration & Characteristics:
The Global Dravet Syndrome Market demonstrates moderate concentration, with a mix of large pharmaceutical companies and specialized biotech firms shaping growth. It benefits from orphan drug incentives, which create strong opportunities for new entrants and niche developers. Market players compete on innovation, safety, and therapeutic efficacy, while partnerships with research organizations enhance trial participation. The presence of both established and emerging companies ensures competitive pricing, improved treatment options, and accelerated drug development timelines.
Report Coverage:
The research report offers an in-depth analysis based on segments such as type of seizures, diagnosis, treatment, end-use, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of gene therapy is expected to transform treatment paradigms.
- Increased clinical trial activity will broaden patient access to novel therapies.
- Growing awareness campaigns will improve diagnosis rates in emerging regions.
- Digital health platforms will expand remote monitoring and seizure management.
- Strong orphan drug incentives will attract more biotech investments.
- Collaborative research partnerships will accelerate therapy development.
- Non-pharmacological approaches such as ketogenic diets will gain structured adoption.
- Asia Pacific will emerge as a key high-growth market with expanding infrastructure.
- Pricing pressures will push companies to innovate cost-effective solutions.
- Advances in precision medicine will personalize treatment pathways for patients.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Awareness and Early Diagnosis of Rare Epileptic Disorders
Increased efforts by advocacy groups and healthcare organizations have led to greater awareness of Dravet Syndrome, resulting in earlier diagnosis and a larger patient pool eligible for advanced therapies. Early intervention improves outcomes and drives demand for specialized treatments.
Regulatory Support and Orphan Drug Incentives
Favorable regulatory frameworks and orphan drug designations provide tax credits, grants, and market exclusivity, encouraging pharmaceutical companies to invest in innovative therapies for Dravet Syndrome. These incentives accelerate drug development and expand treatment options.
Advancements in Genetic Testing and Precision Medicine
The adoption of SCN1A genetic testing and precision-based diagnostics enables accurate identification of Dravet Syndrome, supporting tailored treatment plans and improving patient outcomes. This shift toward personalized medicine increases the effectiveness and uptake of therapies.
Expansion of Patient Support Initiatives and Healthcare Infrastructure
Non-profit organizations, advocacy groups, and improved healthcare infrastructure in both developed and emerging regions enhance access to advanced therapies and comprehensive care. Insurance coverage and telemedicine further reduce barriers to treatment.
Growth in Clinical Research and Novel Therapeutic Modalities
Ongoing clinical trials and research collaborations are driving the development of new treatment modalities, including gene therapies and targeted drugs, which promise improved seizure control and long-term disease management for Dravet Syndrome patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Dravet Syndrome Market, and what is its projected size in 2032?
Which Global Dravet Syndrome Market segment held the largest share in 2024
What are the primary factors fueling the growth of the Global Dravet Syndrome Market?
Who are the leading companies in the Global Dravet Syndrome Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Pharma Companies
- 1.2.2 Hospitals
- 1.2.3 Diagnostic Centers
- 1.2.4 Laboratories
- 1.2.5 Academic and Research Institutes
- 1.2.6 Others
- 1.3 By Diagnosis
- 1.3.1 MRI
- 1.3.2 ECG
- 1.3.3 SCN1A Testing
- 1.4 By Treatment
- 1.4.1 Seizure Management
- 1.4.2 Medication
- 1.4.3 Clobazam
- 1.4.4 Stiripentol
- 1.4.5 Sodium Valproate
- 1.4.6 Ketogenic Diet
- 1.4.7 Others
- 1.5 By Type of Seizures
- 1.5.1 Myoclonic Seizures
- 1.5.2 Atonic Seizures
- 1.5.3 Partial Seizures
- 1.5.4 Tonic-Clonic Seizures
- 1.5.5 Photosensitive Seizures
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 380.0 million → 2032: USD 869.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dravet Syndrome Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dravet Syndrome Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dravet Syndrome Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dravet Syndrome Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dravet Syndrome Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dravet Syndrome Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dravet Syndrome Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dravet Syndrome Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 380.0 million → 2032: USD 869.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dravet Syndrome Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharma Companies
- 12.3.7.2 Hospitals
- 12.3.7.3 Diagnostic Centers
- 12.3.7.4 Laboratories
- 12.3.7.5 Academic and Research Institutes
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diagnosis - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 MRI
- 12.4.7.2 ECG
- 12.4.7.3 SCN1A Testing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Seizure Management
- 12.5.7.2 Medication
- 12.5.7.3 Clobazam
- 12.5.7.4 Stiripentol
- 12.5.7.5 Sodium Valproate
- 12.5.7.6 Ketogenic Diet
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Seizures - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Myoclonic Seizures
- 12.6.7.2 Atonic Seizures
- 12.6.7.3 Partial Seizures
- 12.6.7.4 Tonic-Clonic Seizures
- 12.6.7.5 Photosensitive Seizures
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dravet Syndrome End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dravet Syndrome Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dravet Syndrome Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dravet Syndrome Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stoke Therapeutics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lundbeck A/S
- 18.4 Sanofi
- 18.5 Biocodex S.A.
- 18.6 Jazz Pharmaceuticals plc
- 18.7 Ovid Therapeutics Inc.
- 18.8 AbbVie Inc.
- 18.9 PTC Therapeutics Inc.
- 18.10 Epygenix Therapeutics Inc.
- 18.11 Marinus Pharmaceuticals Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

