
Electric Vehicle Supply Equipment Market Overview:
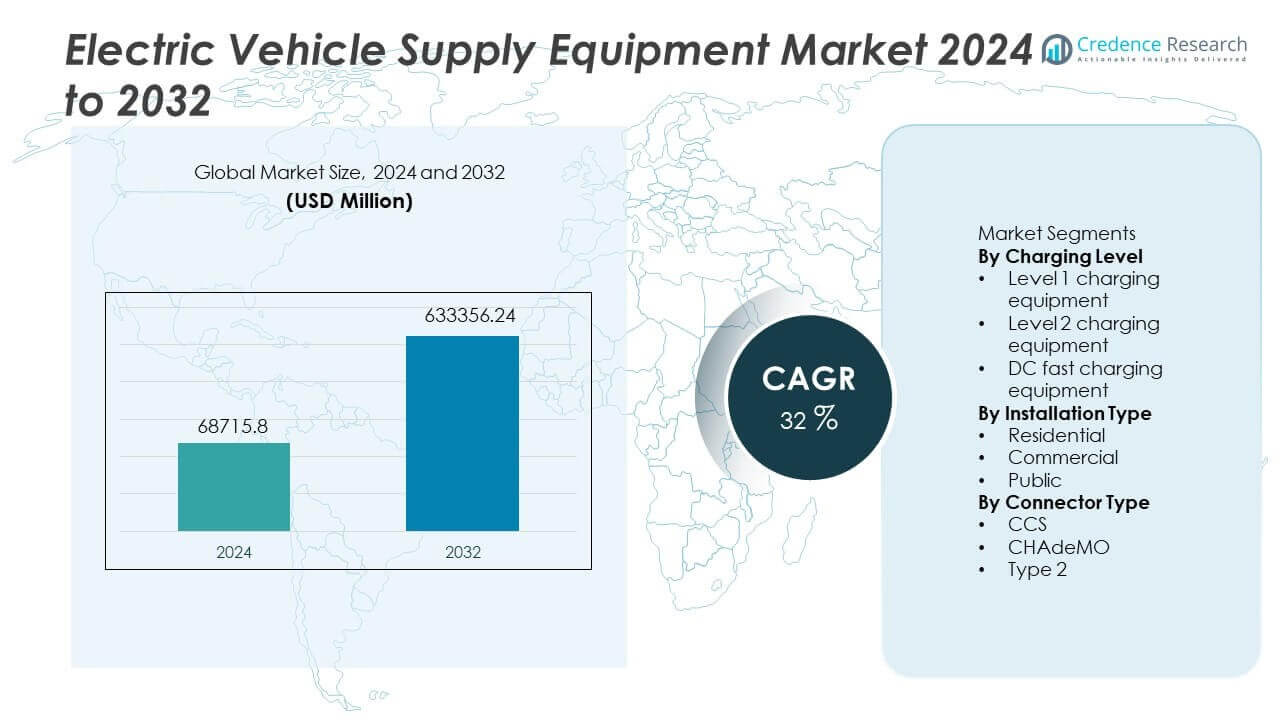
The Electric Vehicle Supply Equipment market was valued at USD 68,715.8 million in 2024 and is anticipated to reach USD 633,356.24 million by 2032, growing at a CAGR of 32% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Electric Vehicle Supply Equipment Market Size 2024 | USD 68,715.8 million |
| Electric Vehicle Supply Equipment Market, CAGR | 32% |
| Electric Vehicle Supply Equipment Market Size 2032 | USD 633,356.24 million |
Electric Vehicle Supply Equipment Market Insights
- Market growth is fueled by government funding, emission regulations, and rising EV penetration, with Level 2 charging equipment leading the charging level segment at a 52% share due to wide residential and commercial use.
- Market trends highlight strong expansion of DC fast charging and smart charging solutions, while public charging installations dominate the installation type segment with a 44% share due to high utilization rates.
- Competitive analysis shows intense focus on DC fast charging, software platforms, and interoperability, while high installation costs and grid upgrade requirements remain key market restraints.
- Regional analysis indicates Asia Pacific leads with a 35% share, followed by North America at 28% and Europe at 27%, reflecting EV adoption scale, infrastructure investment, and regulatory support.
Electric Vehicle Supply Equipment Market Segmentation Analysis:
By Charging Level
By charging level, Level 2 charging equipment dominates the electric vehicle supply equipment market with a 52% share. This dominance reflects widespread use across residential, workplace, and commercial locations. Level 2 chargers offer balanced charging speed and cost efficiency, making them suitable for daily charging needs. Governments and utilities support Level 2 deployment through incentives and building mandates. DC fast charging equipment holds a 38% share, driven by highway corridors, fleet depots, and urban fast-turnover locations. Level 1 charging equipment accounts for 10%, limited to basic residential use. Level 2 leadership reflects higher installation volumes and broad application coverage.
- For instance, ABB Ltd. supplies Terra AC Wallbox units rated at 22 kW, supporting three-phase charging for homes and offices.
By Installation Type
By installation type, public charging installations lead the market with a 44% share. Urbanization and lack of private parking increase reliance on public EVSE. Government-funded charging programs support large-scale rollout. Public chargers enable long-distance travel and shared mobility use. Commercial installations hold a 33% share, supported by workplaces, retail sites, and fleet depots seeking managed charging solutions. Residential installations account for 23%, driven by home charging convenience. Public charging dominance reflects higher utilization rates, strategic placement, and policy support for open-access charging infrastructure.
- For instance, ChargePoint Holdings operates over 300,000 activated ports globally, with many public units delivering 11 kW to 22 kW.
By Connector Type
By connector type, CCS connectors dominate the electric vehicle supply equipment market with a 41% share. Strong adoption across North America and Europe supports leadership. Compatibility with DC fast charging and broad OEM backing drive demand. Type 2 connectors hold a 36% share, led by extensive use in Europe and AC charging networks. CHAdeMO accounts for 23%, supported by legacy vehicles and select Asian markets. CCS dominance reflects global standardization efforts, fast-charging compatibility, and increasing deployment across public and commercial charging stations.
Key Growth Drivers
Rapid Expansion of Electric Vehicle Adoption
Electric vehicle adoption strongly drives the electric vehicle supply equipment market. Rising EV sales increase demand for accessible charging infrastructure. Governments promote EV uptake through incentives and emission regulations. Automakers expand electric model portfolios across segments. Higher EV penetration raises charging frequency and coverage needs. Urbanization increases reliance on shared charging networks. Residential and workplace charging deployment supports daily use. Public charging infrastructure expansion improves range confidence. Charging availability remains essential for sustained EV growth. This driver ensures long-term demand for EVSE deployment.
- For instance, Tesla, Inc. operates a vast network of Supercharger connectors across the globe, with many individual stalls capable of delivering high-speed power output to support rapid vehicle charging.
Strong Government Support and Infrastructure Funding
Government policies significantly accelerate EVSE market growth. National infrastructure programs fund charging station deployment. Subsidies reduce installation and equipment costs. Building codes mandate charger readiness in new developments. Public procurement supports open-access charging networks. Smart city initiatives integrate EV charging solutions. Highway corridor programs enable long-distance EV travel. Regulatory clarity attracts private investment. Policy alignment supports large-scale deployment. Government involvement remains a critical market driver.
- For instance, Siemens AG supplies public charging hubs using modular 150 kW DC units integrated with grid management systems.
Rising Electrification of Commercial and Fleet Vehicles
Fleet electrification drives high-capacity EVSE demand. Logistics, ride-hailing, and public transport fleets adopt electric vehicles. Centralized depots require reliable charging solutions. Managed charging improves operational efficiency. High vehicle utilization supports faster return on investment. Fleet operators prefer scalable EVSE systems. Commercial charging hubs expand rapidly. Charging-as-a-service models gain traction. Fleet demand adds stability to market growth. This driver strengthens commercial EVSE adoption.
Key Trends & Opportunities
Expansion of DC Fast Charging Networks
DC fast charging networks present major growth opportunities. Highway corridors and urban hubs demand rapid charging access. Fleet operations require reduced charging downtime. Technology improvements increase power output. High-speed charging supports long-distance EV travel. Public-private partnerships accelerate deployment. Fast chargers improve station utilization rates. Premium pricing supports revenue growth. This trend strengthens EVSE network density. Fast charging expansion enhances overall market scalability.
- For instance, EVBox supplies Troniq High Power DC chargers for high-traffic corridors, featuring a scalable architecture with power cabinets that allow operators to increase charging capacity as demand grows.
Integration of Smart Charging and Energy Management
Smart charging adoption continues to grow. Software platforms optimize load management. Energy management reduces grid stress. Integration with renewables improves sustainability. Data analytics enhance charger utilization. Demand response capabilities support utilities. User apps improve access and payment convenience. Smart features differentiate EVSE offerings. Digital solutions create recurring revenue streams. This trend supports value-added service opportunities.
- For instance, Schneider Electric integrates EVlink chargers with EcoStruxure software, managing sites with up to 100 connected charge points in real time.
Key Challenges
High Installation Costs and Grid Upgrade Requirements
EVSE deployment involves high upfront costs. Hardware and installation expenses increase investment needs. Grid upgrades add complexity and delay. Power availability limits site selection. Urban locations face space constraints. Smaller operators face financial challenges. Return on investment depends on utilization rates. Regulatory approvals slow project timelines. Cost management remains critical. Infrastructure economics challenge rapid scaling.
Interoperability and Standardization Issues
Interoperability challenges affect user experience. Multiple connector standards create compatibility issues. Fragmented networks limit seamless access. Payment systems vary across operators. Reliability concerns impact consumer trust. Maintenance complexity increases costs. Roaming limitations affect convenience. Software integration challenges persist. Standardization progress remains uneven. Addressing interoperability is essential for market maturity.
Regional Analysis
North America
North America holds a 28% share of the electric vehicle supply equipment market, driven by strong EV adoption and infrastructure funding. The United States leads regional deployment through federal and state charging programs. Public and commercial installations expand rapidly across highways and urban centers. Fleet electrification increases demand for high-capacity EVSE. Utilities invest in grid upgrades and smart charging solutions. Workplace charging grows steadily. Private investment supports network scale-up. Technology adoption remains high. The region benefits from mature EV ecosystems, strong policy backing, and growing consumer confidence.
Europe
Europe accounts for a 27% share of the electric vehicle supply equipment market, supported by strict emission targets and sustainability policies. Countries such as Germany, France, and the Netherlands lead EVSE deployment. Public charging expansion remains a priority in dense urban areas. Building regulations mandate charger-ready infrastructure. DC fast charging grows along transport corridors. Renewable energy integration strengthens charging networks. Cross-border standardization improves accessibility. Public-private partnerships accelerate rollout. Europe maintains steady growth due to regulatory consistency and high EV penetration.
Asia Pacific
Asia Pacific dominates the electric vehicle supply equipment market with a 35% share, driven by large-scale EV adoption. China leads regional deployment through government-backed charging programs. High population density supports public and shared charging models. Cost-efficient manufacturing enables rapid EVSE expansion. Urbanization increases charging demand. India and Southeast Asia show rising momentum in public and commercial installations. Smart city initiatives integrate EVSE infrastructure. Fleet and two-wheeler electrification boost volume demand. The region remains the fastest-growing EVSE market globally.
Rest of the World
The Rest of the World holds a 10% share of the electric vehicle supply equipment market, reflecting emerging adoption. Latin America expands EVSE deployment in major cities. The Middle East invests in charging aligned with clean energy goals. Australia supports highway and urban charging rollout. Infrastructure gaps limit rapid expansion in some regions. Policy frameworks continue to develop. Private investment remains selective. Pilot projects increase awareness. Long-term growth depends on EV adoption, incentives, and grid development.
Electric Vehicle Supply Equipment Market Segmentations:
By Charging Level
- Level 1 charging equipment
- Level 2 charging equipment
- DC fast charging equipment
By Installation Type
- Residential
- Commercial
- Public
By Connector Type
- CCS
- CHAdeMO
- Type 2
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis in the electric vehicle supply equipment market highlights ABB Ltd., Siemens AG, Schneider Electric, ChargePoint Holdings, and Tesla as leading participants. Competition centers on charging speed, network reliability, and smart charging capabilities. Companies invest heavily in DC fast charging, software platforms, and energy management integration. Public and commercial charging contracts drive volume growth and long-term revenue visibility. Strategic partnerships with utilities, fleet operators, and municipalities strengthen market positions. Product differentiation focuses on interoperability, uptime, and user experience. Expansion into emerging markets supports scale. Pricing pressure remains high due to increasing competition. Overall, the market rewards players with strong technology portfolios, service capabilities, and global deployment reach.
Key Player Analysis
- ABB Ltd.
- Siemens AG
- Schneider Electric
- ChargePoint Holdings
- Tesla
- EVBox
- Blink Charging
- Webasto Group
- Delta Electronics
- Leviton Manufacturing
Recent Developments
- In December 2025, ABB completed acquisition of Gamesa Electric’s power electronics business, which expands its EV charging-related power conversion offerings.
- In November 2025, ChargePoint and Dabaja Brothers Development Group announced expansion of ultra-fast EV chargers in Metro Detroit.
- In January 2025, Schneider Electric launched the Schneider Charge Pro EV charging solution in Europe to accelerate fleet and residential EV adoption.
Report Coverage
The research report offers an in-depth analysis based on Charging Level, Installation Type, Connector Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Electric vehicle adoption growth will continue driving EVSE demand globally.
- DC fast charging deployment will expand across highways and urban hubs.
- Public charging networks will remain the largest installation segment.
- Smart charging and energy management integration will increase.
- Fleet electrification will boost demand for high-capacity charging systems.
- Interoperability and standardization will improve user experience.
- Renewable energy integration with EVSE will gain importance.
- Charging-as-a-service models will expand among commercial users.
- Local manufacturing will strengthen supply chain resilience.
- Asia Pacific will remain the leading region for EVSE market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Electric Vehicle Supply Equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Vehicle Supply Equipment market projected to grow between 2024 and 2032?
Which Electric Vehicle Supply Equipment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Vehicle Supply Equipment market?
Who are the leading companies in the Electric Vehicle Supply Equipment market?
Which region commanded the largest share of the Electric Vehicle Supply Equipment market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electric Vehicle Supply Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electric Vehicle Supply Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 68,715.8 million → 2032: USD 633,356.24 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electric Vehicle Supply Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electric Vehicle Supply Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electric Vehicle Supply Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electric Vehicle Supply Equipment Market Drivers
- 3.3 Electric Vehicle Supply Equipment Market Restraints & Challenges
- 3.4 Electric Vehicle Supply Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electric Vehicle Supply Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electric Vehicle Supply Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electric Vehicle Supply Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electric Vehicle Supply Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Electric Vehicle Supply Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Electric Vehicle Supply Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electric Vehicle Supply Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electric Vehicle Supply Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Electric Vehicle Supply Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electric Vehicle Supply Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Electric Vehicle Supply Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electric Vehicle Supply Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Electric Vehicle Supply Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electric Vehicle Supply Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electric Vehicle Supply Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electric Vehicle Supply Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electric Vehicle Supply Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electric Vehicle Supply Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electric Vehicle Supply Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
