
Market Overview:
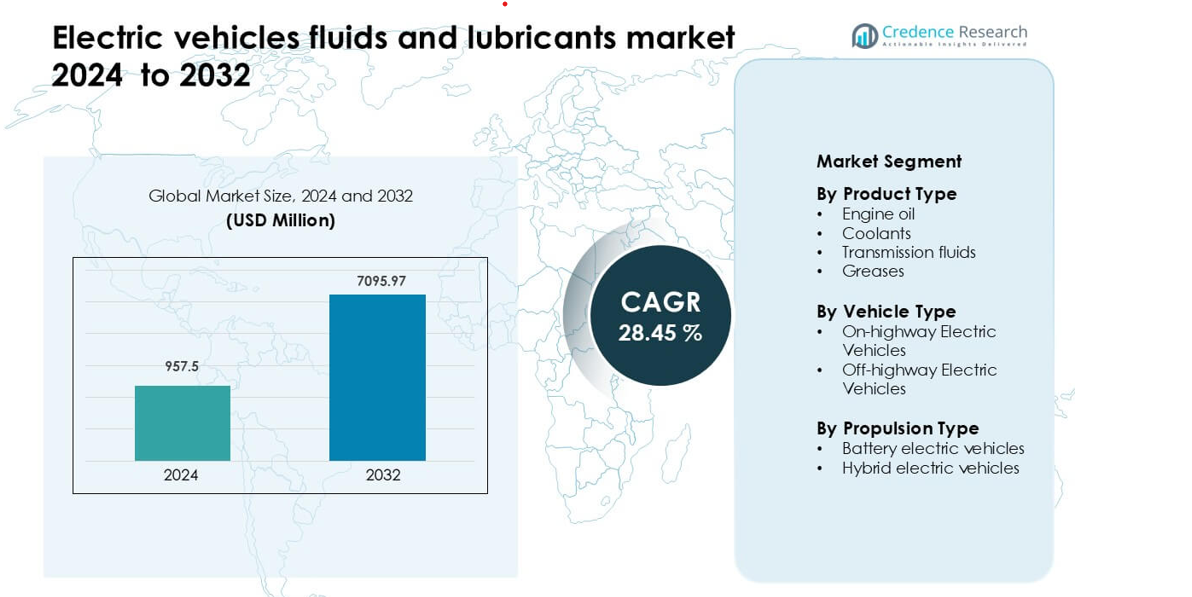
Electric vehicles fluids and lubricants market was valued at USD 957.5 million in 2024 and is anticipated to reach USD 7095.97 million by 2032, growing at a CAGR of 28.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Vehicles Fluids and Lubricants Market Size 2024 | USD 957.5 million |
| Electric Vehicles Fluids and Lubricants Market, CAGR | 28.45% |
| Electric Vehicles Fluids and Lubricants Market Size 2032 | USD 7095.97 million |
The Electric Vehicles (EV) fluids and lubricants market is shaped by the presence of major global players, including Exxon Mobil, Shell, BP, TotalEnergies, FUCHS, PETRONAS, Saudi Arabian Oil Co., Repsol, ENEOS, and Gulf Oil International. These companies compete through advanced EV-specific coolants, dielectric fluids, and long-life synthetic lubricants developed in collaboration with leading automakers. Asia Pacific leads the global market with an exact share of 38%, driven by high EV manufacturing activity, large-scale battery production, and strong policy support in China, Japan, South Korea, and India. This regional dominance continues to attract aggressive expansion and product innovation from key industry participants.
Market Insights
- Electric vehicles fluids and lubricants market was valued at USD 957.5 million in 2024 and is anticipated to reach USD 7095.97 million by 2032, growing at a CAGR of 28.45% during the forecast period.
- Rapid EV adoption driven by emissions regulations, government incentives, and OEM electrification strategies fuels demand for specialized thermal-management fluids and low-viscosity lubricants.
- A shift toward synthetic, long-life, and eco-friendly formulations is emerging as automakers and lubricant firms collaborate to optimize performance for next-generation electric drivetrains.
- Market competition remains intense, with major players like ExxonMobil, Shell, BP, TotalEnergies, FUCHS, PETRONAS, Repsol, ENEOS, and others racing to co-develop EV-specific products and expand geographically.
- High R&D costs, lack of global standardization of EV fluid specs, and a structural decline in lubricant volumes per vehicle especially in full BEVs pose key challenges, while Asia
Market Segmentation Analysis:
By Product Type
Within the EV fluids and lubricants market, engine oil remains the dominant product sub-segment, holding an estimated 55–56% share, primarily due to the extensive use of hybrid electric vehicles that still depend on internal combustion components. Specialized EV-compatible engine oils support reduced friction, enhanced thermal stability, and protection under high motor torque, making them essential for hybrid powertrains. Rising OEM specifications for EV-tailored lubricants and growing hybrid vehicle production continue to accelerate demand in this category, reinforcing its leading position.
- For instance, Shell’s Helix Hybrid 0W-20 uses its PurePlus Technology to produce a base oil that is 99.5% pure, offering very strong antioxidation stability and flow down to –40 °C, which helps performance in cold starts.
By Vehicle Type
Among vehicle categories, on-highway electric vehicles command the largest share at approximately 68–72%, driven by the rapid global expansion of electric passenger cars, commercial vans, and buses. These vehicles operate across extended duty cycles and high-mileage applications, creating strong demand for advanced thermal-management fluids, coolants, and transmission lubricants. Increasing fleet electrification, urban mobility programs, and the growth of long-range EV platforms further support the dominance of this sub-segment in the market.
- For instance, Shell has co-engineered its E-Fluid portfolio with commercial bus OEMs: its E-Thermal Fluid (for batteries and power electronics) exhibits 8× lower electrical conductivity compared to a conventional heavy-duty ATF, enabling safer operation in sealed high-voltage systems.
By Propulsion Type
In propulsion systems, hybrid electric vehicles (HEVs) lead the market with a share of around 74–75%, primarily because they incorporate both electric motors and internal combustion engines, requiring a wider range of fluids such as engine oils, coolants, and transmission fluids. Their dual-system architecture increases overall lubricant consumption compared to battery-electric vehicles. Continued hybrid adoption by major automakers, supported by fuel-efficiency regulations and cost-effective electrification strategies, sustains the strong demand for HEV-specific fluid formulations.
Key Growth Drivers
Rising Global Electrification and Expanding EV Fleet
The continuous rise in electric vehicle adoption remains one of the strongest drivers of demand for specialized EV fluids and lubricants. Governments worldwide are enforcing stricter emissions norms, offering incentives, and investing heavily in charging infrastructure, which collectively accelerate EV penetration. As the global fleet expands, the requirement for advanced fluids such as battery coolants, dielectric fluids, and e-motor greases grows proportionally. Unlike conventional vehicles, EVs rely heavily on superior thermal management to enhance battery efficiency and prevent overheating, pushing manufacturers to innovate high-performance formulations. Increasing production of passenger EVs, electric two-wheelers, and commercial electric fleets further contributes to the rising consumption of specialized lubricants. OEMs are integrating tailored fluid systems to improve longevity, reduce energy loss, and support fast-charging environments, reinforcing this driver.
- For instance, Repsol has developed a battery-thermal fluid that delivers a dielectric breakdown voltage of 77 kV and a kinematic viscosity of 27.4 cSt at 40 °C, supporting direct immersion cooling in high-voltage EV battery modules.
Advancements in Thermal Management and Lubrication Technologies
Rapid technological innovation in EV thermal management systems significantly boosts market growth. Modern EVs operate under higher voltages and generate intense localized heat, particularly within battery packs, power electronics, and electric motors. This has led to an increased need for high-performance fluids capable of delivering superior cooling efficiency and electrical insulation. Manufacturers are developing dielectric coolants, long-life transmission fluids, and low-viscosity lubricants that minimize friction and improve drivetrain efficiency. These innovations help extend component life, enhance vehicle range, and support next-generation battery chemistries such as solid-state systems. With OEMs focusing on improving energy density and fast-charging capabilities, demand grows for fluids that can stabilize temperatures under extreme loads. The ongoing shift toward integrated e-axle systems and compact powertrains further strengthens the need for specialized lubrication technologies.
- For instance, 3M’s Novec™ 649 dielectric coolant supports immersion cooling with a boiling point of 49 °C, thermal conductivity of 0.069 W/m·K, and dielectric strength of 40 kV, enabling direct-contact cooling for high-power battery modules used in prototype solid-state systems.
Increasing Hybrid Vehicle Production and Diverse Fluid Requirements
The surge in hybrid electric vehicle (HEV) production acts as an important growth driver, as hybrids require a broader range of fluids compared to purely battery-electric vehicles. HEVs combine electric motors with internal combustion engines, which means they still rely on engine oils, transmission fluids, and cooling solutions traditionally used in ICE platforms-along with EV-specific fluids. This dual-system architecture increases overall fluid consumption per vehicle, creating strong market potential. Automakers are expanding their hybrid portfolios to meet fuel-efficiency regulations in markets where full EV adoption is slower, further boosting demand for specialized lubricants. HEV engines also operate under unique thermal and mechanical loads due to frequent start-stop cycles and regenerative braking, increasing the need for advanced formulations that enhance durability and system reliability. This structural demand ensures steady market growth even as BEV adoption accelerates.
Key Trends & Opportunities
Growth of EV-Specific Synthetic and Long-Life Fluids
A major trend shaping the market is the shift toward fully synthetic, long-life, and low-viscosity fluids optimized for EV architectures. As automakers aim to reduce maintenance intervals and enhance vehicle efficiency, synthetic formulations offer extended durability, improved oxidation stability, and superior heat dissipation. Opportunity emerges as OEMs increasingly collaborate with lubricant manufacturers to co-develop customized fluids for new-generation motors, integrated e-axles, and high-performance drivetrains. Fluids that support high-speed motor rotation, minimize electrical losses, and operate safely in wide temperature ranges are gaining prominence. Additionally, the market is witnessing increased focus on eco-friendly and biodegradable fluids aligned with sustainability goals. Suppliers that invest in research and partner with OEMs stand to capture substantial opportunities in premium-value product categories.
- For instance, Cargill’s Priolube™ EF 3446, a fully synthetic dielectric ester base oil, has a kinematic viscosity of 6.1 cSt at 40 °C and 2.0 cSt at 100 °C, which helps reduce churning losses in e-axles while maintaining load-carrying capability.
Rapid Expansion of EV Thermal Management Innovations
Thermal management remains one of the most dynamic areas of opportunity, as EV batteries, inverters, and motors demand precise temperature control for optimal performance. The trend is shifting toward immersion cooling, liquid-to-air systems, and advanced dielectric fluids capable of direct battery contact. These technologies offer major opportunities for fluid manufacturers to develop formulations that enhance safety, support fast charging, and improve battery lifespan. As automakers reduce battery spacing and push for compact pack designs, high-performance coolants become essential. Moreover, high-voltage charging systems used in commercial EVs create demand for fluids that manage extreme heat loads. The intersection of battery innovation and fluid development presents a substantial long-term opportunity for suppliers focusing on next-generation energy storage systems.
- For instance, BASF’s GLYSANTIN® G22® ELECTRIFIED® coolant maintains an electrical conductivity of ≤ 50 µS/cm at 20 °C, which ensures low and stable currents under a 4 V source, minimizing hydrogen generation and fluid decomposition.
Growth Potential in Commercial EV and Fleet Electrification
Fleet electrification particularly in logistics, ride-hailing, and public transportation-presents a growing market opportunity for EV fluids and lubricants. Commercial EVs operate longer daily distances, experience higher load cycles, and rely on fast charging, making effective thermal and lubrication systems critical. These conditions drive stronger demand for high-performance coolants, gear oils, and greases tailored for heavy-duty electric powertrains. Governments are increasingly mandating zero-emission public transport fleets, which further boosts product requirements. As fleet operators prioritize efficiency, uptime, and total cost of ownership, suppliers have opportunities to offer advanced, long-life, and maintenance-reducing fluid formulations. This segment is expected to attract significant investments in the coming years.
Key Challenges
Limited Standardization and High R&D Costs
One of the key challenges in the EV fluids market is the lack of industry-wide standardization for fluid requirements across different vehicle platforms. Each OEM develops its own EV architecture, battery chemistry, and thermal management system, requiring custom-formulated fluids. This raises development costs for lubricant manufacturers and complicates mass-scale production. High R&D investment is required to create formulations that meet stringent electrical insulation, material compatibility, and performance specifications. Manufacturers face long testing cycles and rigorous validation procedures before approval. Smaller companies struggle to compete due to the capital-intensive nature of EV fluid innovation. The absence of harmonized standards also limits cross-compatibility, slowing market scalability.
Reduced Fluid Consumption in Fully Electric Vehicles
Another major challenge is the declining consumption of traditional lubricants as the market shifts toward battery-electric vehicles (BEVs). Unlike hybrids or ICE vehicles, BEVs eliminate the need for engine oils and require significantly fewer mechanical lubricants. While specialized EV fluids such as coolants and dielectric lubricants are growing, their total volume per vehicle is comparatively lower. This structural reduction in fluid usage tightens market potential and intensifies competition among suppliers. Companies must continuously innovate higher-value products to offset declining volumes. As BEV technology improves with solid-state batteries and simplified powertrain designs, fluid requirements may decrease further, posing a long-term challenge for traditional lubricant manufacturers
Regional Analysis
North America
In North America, the EV fluids and lubricants market holds approximately 25–28% of global revenue, driven by strong EV adoption in the U.S. and Canada. The region benefits from tight emissions regulations, government incentives, and a mature automotive industry that rapidly integrates advanced thermal management and lubricant systems into EV powertrains. Major OEMs and lubricant suppliers collaborate closely to develop high-performance synthetic coolants and greases tailored for harsh driving conditions and cold climates, which supports both innovation and steady market growth.
Europe
Europe accounts for about 25–30% of the global EV fluids and lubricants market, reflecting its aggressive push toward decarbonization. The region’s regulatory environment-anchored in the European Green Deal-presses automakers to accelerate EV deployment, creating strong demand for specialized coolants, dielectric fluids, and EV-grade lubricants. High EV penetration in major markets like Germany, France, and the Nordic countries stimulates investments in next-generation thermal management solutions. Furthermore, Europe’s established automotive R&D ecosystem strengthens partnerships between OEMs and fluid-technology providers.
Asia Pacific
Asia Pacific dominates the EV fluids and lubricants space with a share of 35–40%, underpinned by massive EV production in China, Japan, South Korea, and India. Supportive government policies, large-scale investment in charging infrastructure, and local OEM manufacturing capacity drive demand for specialized fluids tailored to high-volume EV platforms. The intensity of thermal management needs in densely populated and hotter regions amplifies the consumption of coolants and dielectric fluids. Additionally, regional players are innovating aggressively in greases and long-life lubricants suited for fast-charging and high-power EV systems.
Latin America
Latin America contributes roughly 4–6% to the global market for EV fluids and lubricants, reflecting its emerging but growing EV ecosystem. Market growth hinges on rising EV adoption in countries such as Brazil, Mexico, and Chile, spurred by improving charging infrastructure and government incentives. While demand is still relatively modest compared to more mature markets, there is growing interest in thermal-management fluids and low-viscosity lubricants. Infrastructure investments and OEM expansion in the region present meaningful opportunities for fluid suppliers willing to localize and scale operations.
Middle East & Africa
The Middle East & Africa (MEA) region holds around 3–5% of the global EV fluids and lubricants market. EV adoption here is nascent but accelerating, especially in the UAE, Saudi Arabia, and South Africa, where sustainability and clean-energy mandates are gaining traction. High ambient temperatures create unique thermal management challenges, which elevate demand for robust coolants and advanced dielectric fluids. Meanwhile, limited local manufacturing encourages partnerships with global fluid suppliers to establish supply chains that can cater to the distinctive performance needs of EVs in this region.
Market Segmentations:
By Product Type
- Engine oil
- Coolants
- Transmission fluids
- Greases
By Vehicle Type
- On-highway Electric Vehicles
- Off-highway Electric Vehicles
By Propulsion Type
- Battery electric vehicles
- Hybrid electric vehicles
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the electric vehicle fluids and lubricants market is characterized by strong participation from global energy giants, specialized lubricant manufacturers, and automotive fluid technology innovators. Leading companies such as Exxon Mobil, Shell, BP, TotalEnergies, FUCHS, PETRONAS, and ENEOS focus on expanding their EV-specific portfolios, including dielectric coolants, long-life transmission fluids, and high-performance greases tailored for electric powertrains. These players invest heavily in research collaborations with OEMs to co-develop advanced thermal management solutions that meet evolving EV architecture requirements. Competitive strategies emphasize product innovation, sustainability, and geographic expansion, supported by partnerships and acquisitions to strengthen supply chains. Companies increasingly prioritize synthetic, eco-friendly, and high-efficiency formulations to differentiate themselves in a market where technical performance and compatibility with next-generation batteries remain critical competitive factors.
Key Player Analysis
- Repsol
- BP Plc.
- Gulf Oil International Ltd.
- Saudi Arabian Oil Co.
- FUCHS
- TotalEnergies
- Exxon Mobil Corporation
- Shell Plc.
- ENEOS Corp.
- Petroliam Nasional Berhad (PETRONAS)
Recent Developments
- In September 2024, BP plc (Castrol) brand introduced Castrol ON EV Transmission Fluids W2 and W5 for EVs with wet e-motors, expanding its Castrol ON EV thermal, transmission, and grease portfolio; by 2023, three of the world’s four largest motor manufacturers were already using Castrol electric-vehicle fluids as factory fill.
- In June 2023, Gulf Oil International Ltd. launched Gulf eLEC Brake Fluid and related EV coolant solutions, formulated to handle high brake-system demands in EVs and to keep traction batteries within optimal temperature ranges, building on its earlier Gulf eLEC driveline and coolant EV-fluid range.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Vehicle Type, Propulsion Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand rapidly as global EV adoption accelerates and OEMs increase production of high-performance electric powertrains.
- Demand for advanced thermal-management fluids will rise with the growth of fast-charging infrastructure and high-voltage battery systems.
- Dielectric coolants will gain stronger penetration as immersion cooling technologies become more widely integrated into EV battery packs.
- Synthetic and long-life lubricants will see higher uptake as automakers target extended service intervals and reduced maintenance requirements.
- Hybrid vehicles will continue generating significant fluid demand due to their dual powertrain architecture.
- Collaboration between lubricant manufacturers and EV OEMs will intensify to co-develop customized formulations for next-generation platforms.
- Sustainability will influence product innovation, driving interest in biodegradable and energy-efficient EV fluids.
- Regional leaders in EV manufacturing, particularly Asia Pacific, will strengthen their dominance in production and consumption.
- Increased regulatory focus on battery safety will accelerate development of thermally stable and fire-resistant fluids.
- Competitive differentiation will rely on R&D capabilities, rapid product testing, and strong partnerships across automotive supply chains.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Electrification and Expanding EV Fleet
Stricter emissions regulations, government incentives, and investments in charging infrastructure are accelerating electric vehicle adoption worldwide, directly increasing demand for specialized fluids and lubricants required for EV thermal management and drivetrain efficiency.
Advancements in Thermal Management and Lubrication Technologies
Modern EVs generate significant heat in batteries and power electronics, driving the need for advanced coolants and dielectric fluids. Continuous innovation in fluid formulations enhances battery safety, supports fast charging, and extends component life, fueling market growth.
Increasing Hybrid Vehicle Production and Diverse Fluid Requirements
Hybrid electric vehicles require both traditional and EV-specific fluids due to their dual powertrain architecture, resulting in higher fluid consumption per vehicle and sustaining strong demand for specialized lubricants as automakers expand hybrid offerings.
Growth of EV-Specific Synthetic and Long-Life Fluids
Automakers and lubricant manufacturers are shifting toward synthetic, long-life, and eco-friendly fluids to reduce maintenance intervals and improve vehicle efficiency, creating new opportunities for premium, high-performance product categories tailored to next-generation EVs.
Fleet Electrification and Commercial EV Growth
The electrification of commercial fleets in logistics, public transport, and ride-hailing sectors increases demand for robust, high-performance fluids that can withstand intensive duty cycles, high mileage, and fast-charging environments, further expanding the market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Electric Vehicles Fluids and Lubricants market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Vehicles Fluids and Lubricants market projected to grow between 2025 and 2032?
Which is the leading region of the market for Electric Vehicles Fluids and Lubricants?
What are the key drivers for the growth of the Electric Vehicles Fluids and Lubricants market?
Which is the major segment in the Electric Vehicles Fluids and Lubricants market By Vehicle Type?
Who are the leading companies in the Electric Vehicles Fluids and Lubricants market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Engine oil
- 1.2.2 Coolants
- 1.2.3 Transmission fluids
- 1.2.4 Greases
- 1.3 By Vehicle Type
- 1.3.1 On-highway Electric Vehicles
- 1.3.2 Off-highway Electric Vehicles
- 1.4 By Propulsion Type
- 1.4.1 Battery electric vehicles
- 1.4.2 Hybrid electric vehicles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 957.5 million → 2032: USD 7,095.97 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Vehicles Fluids and Lubricants Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Vehicles Fluids and Lubricants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Vehicles Fluids and Lubricants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Vehicles Fluids and Lubricants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Vehicles Fluids and Lubricants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Vehicles Fluids and Lubricants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Vehicles Fluids and Lubricants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Vehicles Fluids and Lubricants Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 957.5 million → 2032: USD 7,095.97 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Vehicles Fluids and Lubricants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Engine oil
- 12.3.7.2 Coolants
- 12.3.7.3 Transmission fluids
- 12.3.7.4 Greases
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-highway Electric Vehicles
- 12.4.7.2 Off-highway Electric Vehicles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Propulsion Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Battery electric vehicles
- 12.5.7.2 Hybrid electric vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Vehicles Fluids and Lubricants Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electric Vehicles Fluids and Lubricants Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electric Vehicles Fluids and Lubricants Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Exxon Mobil Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Shell Plc.
- 17.4 BP Plc.
- 17.5 TotalEnergies
- 17.6 FUCHS
- 17.7 PETRONAS
- 17.8 Repsol
- 17.9 ENEOS Corp.
- 17.10 Gulf Oil International Ltd.
- 17.11 Saudi Arabian Oil Co.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

