
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Engine Blocks Market Size 2024 | USD 119,065.00 Million |
| Engine Blocks Market, CAGR | 6.13% |
| Engine Blocks Market Size 2032 | USD 191,641.4 Million |
Market Overview
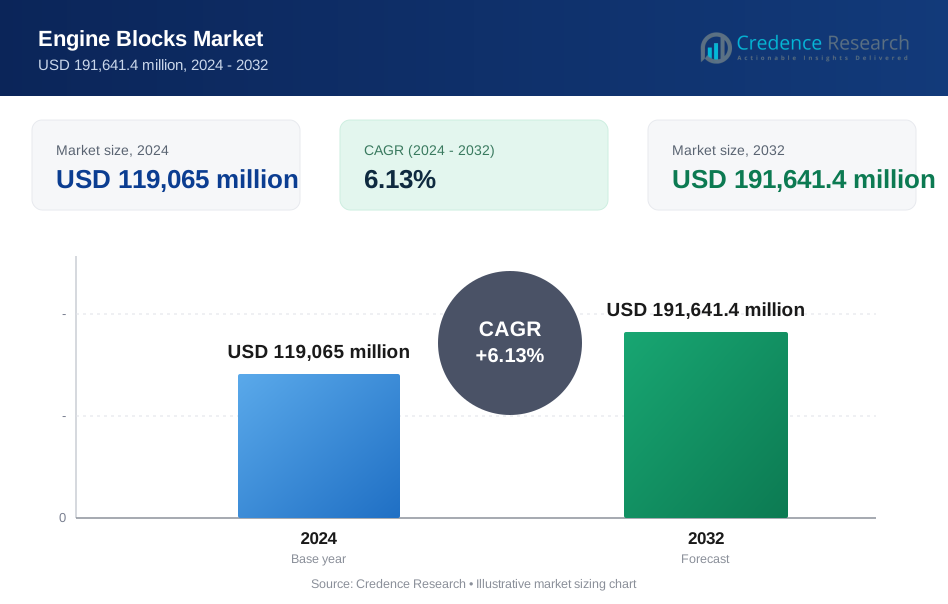
The Engine Blocks Market is projected to grow from USD 119,065.00 million in 2024 to USD 191,641.4 million by 2032, registering a CAGR of 6.13% during the forecast period.
The Engine Blocks Market is witnessing steady growth due to increasing global vehicle production, rising demand for fuel-efficient and lightweight engines, and advancements in manufacturing technologies such as high-pressure die casting and 3D printing. The market benefits from the growing adoption of aluminum and composite materials, which reduce engine weight and enhance thermal performance, improving overall vehicle efficiency. Rising environmental regulations and emission norms are prompting automakers to invest in innovative engine block designs that support cleaner combustion and higher fuel economy. In parallel, the expansion of the electric and hybrid vehicle segment is influencing the development of hybrid-compatible engine blocks with integrated cooling systems. Additionally, emerging economies, particularly in Asia-Pacific, are contributing significantly to market expansion due to infrastructure development and increasing disposable income driving automobile sales. OEMs and suppliers are also focusing on enhancing durability and precision engineering, responding to demand for high-performance engines in both commercial and passenger vehicles across diverse regions.
The Engine Blocks Market demonstrates strong geographical diversity, with Asia-Pacific holding the largest share due to high automotive production in China, India, Japan, and South Korea. North America follows, driven by demand for light trucks and advanced engine technologies in the United States and Canada. Europe remains a key region with strict emission norms and strong OEM presence in Germany, France, and the United Kingdom. Leading players in the market include Toyota Motor Corporation, Ford Motor Company, General Motors Company, Volkswagen AG, Hyundai Motor Company, Honda Motor Co., Ltd., Nissan Motor Co., Ltd., Fiat Chrysler Automobiles N.V., BMW AG, Daimler AG, Renault Group, and Tata Motors Limited. These companies focus on material innovation, precision casting, and hybrid powertrain integration to maintain competitiveness across global markets. Their strategic investments and regional expansions continue to influence the global engine block supply chain and technology landscape.
Market Insights
- The Engine Blocks Market is projected to grow from USD 119,065 million in 2024 to USD 191,641.4 million by 2032, registering a CAGR of 6.13% during the forecast period.
- Increasing global vehicle production and demand for fuel-efficient engines are driving consistent growth across both passenger and commercial vehicle segments.
- Technological advancements such as high-pressure die casting, CNC machining, and 3D printing enable production of lightweight, durable engine blocks.
- Strict emission norms and fuel economy standards are pushing OEMs to adopt innovative materials and integrate advanced cooling systems into engine block designs.
- Emerging markets in Asia-Pacific, Latin America, and Africa are expanding rapidly due to infrastructure development, rising incomes, and growing vehicle ownership.
- Challenges such as high production costs, complex supply chains, and the shift toward electric vehicles are pressuring traditional engine block manufacturers to innovate and diversify.
- Asia-Pacific holds 44% of the market, followed by North America with 26% and Europe with 20%, driven by regional manufacturing strengths and regulatory landscapes.
Market Drivers
Rising Global Vehicle Production and Automotive Industry Growth
The Engine Blocks Market is directly supported by the consistent rise in global vehicle production across passenger and commercial segments. Automotive OEMs are expanding manufacturing capacities to meet the growing demand from emerging economies. The expansion of ride-hailing services and increased vehicle ownership also contribute to rising engine block requirements. It benefits from growth in the commercial vehicle sector, especially in logistics and construction. Urbanization and infrastructure projects further drive demand for engine-powered machinery. It continues to expand in parallel with the automotive industry.
For instance, Maruti Suzuki, India’s largest carmaker, dispatched over 1.76 million passenger vehicles in FY2025, which required robust engine block production to support this volume.
Technological Advancements in Manufacturing and Materials
Technological progress in casting techniques and material innovation is transforming the Engine Blocks Market. High-pressure die casting, CNC machining, and 3D printing have enabled the production of complex, lightweight, and highly durable engine blocks. Manufacturers are replacing traditional cast iron with aluminum and magnesium alloys for better heat dissipation and reduced weight. These advancements enhance fuel efficiency and vehicle performance. It fosters competitive differentiation through engineering precision. Automation and robotics are also reducing lead times and improving production consistency.
For instance, Porsche’s latest air-cooled engine blocks for certain industrial and specialty applications feature redesigned cooling fins and CNC-machined channels, made from advanced aluminum alloys.
Environmental Regulations and Demand for Fuel Efficiency
Stringent emission regulations across regions such as North America, Europe, and parts of Asia are shaping the Engine Blocks Market. Automakers are under pressure to design engines with lower emissions and better fuel economy. This has increased the demand for downsized turbocharged engines and lighter engine blocks that maintain power without compromising environmental performance. It helps OEMs meet compliance goals while improving vehicle mileage. Market players are integrating cooling technologies and design optimizations to support cleaner combustion. Regulatory push is driving sustainable innovation across the value chain.
Emerging Markets and Growth in Aftermarket Sales
Emerging economies in Asia-Pacific, Latin America, and Africa are fueling expansion in the Engine Blocks Market. Rising disposable incomes, urban development, and government investments in road infrastructure boost automobile sales in these regions. In parallel, aftermarket sales of engine blocks for repairs and performance upgrades are gaining momentum. It creates new revenue opportunities for suppliers and distributors. Local manufacturing and favorable trade policies are supporting regional growth. Small-scale manufacturers are increasingly entering the market, strengthening competition and innovation.
Market Trends
Shift Toward Lightweight and High-Performance Materials
The Engine Blocks Market is undergoing a shift toward lightweight and high-performance materials to meet fuel efficiency and emission standards. Aluminum alloys, magnesium, and composite materials are replacing traditional cast iron in modern engine block manufacturing. These materials offer better heat dissipation, reduced engine weight, and enhanced durability under high-pressure conditions. It supports improved vehicle performance while aligning with evolving regulatory frameworks. Automakers are investing in research to optimize material combinations that maintain strength without adding bulk.
For instance, Ford’s F-150 pickup truck features an aluminum-intensive engine block and body, reducing vehicle weight by over 700 pounds and directly improving fuel efficiency while maintaining structural integrity.
Integration of Advanced Cooling and Thermal Management Features
Thermal management has become a critical design focus in the Engine Blocks Market. Manufacturers are incorporating integrated cooling passages and advanced thermal coatings to maintain optimal operating temperatures and prevent overheating. This trend enhances the performance and longevity of internal combustion engines in both high-performance and commercial vehicles. It enables better efficiency and reliability in varying driving conditions. Engine blocks with embedded sensors and smart cooling systems are also gaining popularity among leading OEMs.
For instance, Mercedes-Benz now utilizes advanced thermal coatings and integrated cooling channels in its M256 engine block, which helps maintain consistent temperatures under high load, supporting up to 435 horsepower output while improving fuel efficiency.
Rising Adoption of Hybrid and Electric Powertrain-Compatible Blocks
The transition toward hybrid and electric vehicles is reshaping product development in the Engine Blocks Market. Engine blocks are being redesigned to support hybrid systems that combine internal combustion engines with electric motors. It includes structural adaptations for compact integration, improved thermal properties, and compatibility with regenerative braking. Hybrid-ready blocks must also support frequent start-stop operations. Market players are adjusting manufacturing lines and materials to support this trend. This ensures relevance as electrification accelerates across mobility sectors.
Growth in Customized and High-Precision Engine Block Manufacturing
Customization and precision engineering are becoming central to the competitive landscape of the Engine Blocks Market. Automotive OEMs demand tailor-made engine blocks for specific models and performance requirements, including racing, heavy-duty, and off-road applications. It has prompted investments in CNC machining, CAD-based design, and 3D-printed prototyping. This trend supports shorter development cycles and enhanced part performance. Suppliers offering engineering flexibility and small-batch production capabilities are gaining favor across premium and niche vehicle categories.
Market Challenges Analysis
High Manufacturing Costs and Complex Supply Chain Dynamics
The Engine Blocks Market faces cost-related challenges driven by high raw material prices and advanced manufacturing requirements. Producing lightweight engine blocks with precision demands investments in specialized equipment, tooling, and quality control systems. It increases the overall cost of production, particularly for small and mid-sized suppliers. Disruptions in global supply chains and fluctuating metal prices also strain operational efficiency. Import dependencies for critical components further impact lead times and margins. Companies must balance cost-efficiency with innovation and compliance.
For instance, Ferrari employs bespoke castings and precision machining for its V8 and V12 engine blocks, using specialized alloys and advanced CNC equipment, which results in much higher per-unit costs compared to mass-market manufacturers.
Pressure from Vehicle Electrification and Regulatory Shifts
The accelerating shift toward electric vehicles presents a structural challenge to the Engine Blocks Market. Pure electric vehicles do not use internal combustion engines, reducing long-term demand for engine blocks. It forces traditional engine block manufacturers to diversify or adapt their offerings. Regulatory bodies are also tightening fuel emission norms, compelling OEMs to explore alternative propulsion systems. This transition limits growth potential in some mature markets. Companies must evaluate future-proof strategies to remain relevant in evolving mobility ecosystems.
Market Opportunities
Expansion in Emerging Automotive Markets and Infrastructure Development
Emerging economies present strong growth opportunities for the Engine Blocks Market due to increasing automobile demand and infrastructure expansion. Rising urbanization, higher disposable incomes, and government incentives are driving vehicle sales across Asia-Pacific, Latin America, and Africa. It benefits from local manufacturing initiatives and rising investments in transportation infrastructure. Rapid industrialization also boosts demand for commercial vehicles and off-road equipment. Companies can establish regional production hubs to reduce costs and improve distribution. Strategic entry into underserved markets enhances long-term growth potential.
Innovation in Lightweight Design and Hybrid Compatibility
Technological advancements open new avenues in the Engine Blocks Market through innovations in lightweight and hybrid-compatible designs. Growing demand for fuel-efficient and eco-friendly vehicles encourages OEMs to collaborate with suppliers on next-generation engine platforms. It allows manufacturers to offer high-performance blocks that integrate with hybrid systems without compromising structural integrity. Research in composite materials and smart thermal solutions also supports product innovation. Suppliers focusing on custom-engineered and future-ready solutions can capture premium segments. Early adoption of emerging technologies helps strengthen market position.
Market Segmentation Analysis:
By Material Type
The Engine Blocks Market features a diverse range of materials, with aluminum emerging as the fastest-growing segment due to its lightweight nature and thermal efficiency. Cast iron continues to dominate in heavy-duty applications because of its strength and cost-effectiveness. Compacted graphite iron is gaining traction for offering a balance between durability and weight, especially in high-performance engines. It reflects a shift toward material innovation aligned with fuel economy standards. The "Others" category includes emerging composites and alloys under evaluation for future use.
For instance, Ford uses aluminum engine blocks in its EcoBoost line, such as the 2.7L V6, which is significantly lighter than traditional cast iron blocks-helping improve vehicle fuel efficiency and performance.
By Vehicle Type
The Engine Blocks Market serves a broad vehicle range, with passenger cars accounting for the largest share due to high production volumes. Light commercial vehicles show increasing demand due to last-mile delivery expansion and logistics growth. Heavy commercial vehicles continue to rely on robust engine blocks built for durability and high-load operations. It supports market stability across sectors. The "Others" segment includes specialty vehicles used in agriculture, mining, and construction with specific block performance needs.
For instance, Volkswagen Group’s MQB platform engines, such as the 1.5-liter TSI Evo, utilize advanced aluminum engine blocks that combine lightweight design with high strength, supporting improved fuel efficiency and performance in models like the Golf and Tiguan.
By Manufacturing Process
By manufacturing process, sand casting remains the most widely used method in the Engine Blocks Market for its flexibility and suitability in large-scale production. Die casting is rapidly expanding in use for aluminum engine blocks, offering superior dimensional accuracy and faster cycle times. It enhances production efficiency, especially in automotive OEM environments focused on lightweighting. The "Others" category covers advanced techniques like 3D printing and lost foam casting, which are emerging for prototyping and niche applications.
Segments:
Based on Material Type
- Aluminum
- Cast Iron
- Compacted Graphite Iron
- Others
Based on Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Others
Based on Manufacturing Process
- Sand Casting
- Die Casting
- Others
Based on Fuel Type
- Gasoline
- Diesel
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific holds the largest share in the Engine Blocks Market, accounting for 44% of the global revenue. High vehicle production volumes in China, India, Japan, and South Korea drive demand for engine blocks across all vehicle categories. Strong growth in urban infrastructure and rising income levels contribute to increased automobile ownership. It benefits from cost-efficient manufacturing and a robust supplier ecosystem. Government initiatives supporting electric and hybrid vehicle adoption are influencing product innovation. Local and global OEMs continue to invest in expanding production capacities across the region.
North America
North America accounts for 26% of the Engine Blocks Market, supported by high demand for light trucks, SUVs, and performance vehicles. The United States dominates the region with a strong presence of automotive OEMs and aftermarket service providers. It experiences steady demand from commercial vehicle fleets and off-highway machinery sectors. Engine block manufacturers focus on lightweight materials and advanced casting methods to meet regulatory and consumer performance expectations. Strong R&D capabilities and access to advanced technology give North American suppliers a competitive edge. Investment in hybrid powertrain-compatible components is also rising.
Europe
Europe holds 20% of the Engine Blocks Market, driven by established automotive industries in Germany, France, and the United Kingdom. Strict emission norms and fuel efficiency regulations push manufacturers to adopt lightweight and high-efficiency engine block designs. It focuses on sustainability, prompting adoption of advanced materials and recycling processes. OEMs invest in hybrid-compatible engine blocks to support the region’s green mobility targets. Aftermarket demand also remains strong due to aging vehicle fleets and high vehicle retention rates. Regional innovation centers and collaborations between automakers and material specialists sustain market competitiveness.
Key Player Analysis
- Daimler AG
- Honda Motor Co., Ltd.
- Tata Motors Limited
- Renault Group
- BMW AG
- General Motors Company
- Fiat Chrysler Automobiles N.V.
- Toyota Motor Corporation
- Hyundai Motor Company
- Nissan Motor Co., Ltd.
- Ford Motor Company
- Volkswagen AG
Competitive Analysis
The Engine Blocks Market is highly competitive, with major players such as Toyota Motor Corporation, Ford Motor Company, General Motors Company, and Volkswagen AG leading the landscape. These companies invest heavily in R&D to develop lightweight, fuel-efficient engine blocks that comply with global emission standards. It sees continuous innovation in material science, casting technologies, and hybrid compatibility. Manufacturers focus on partnerships and localization strategies to reduce production costs and enhance supply chain resilience. Emerging players from Asia-Pacific are expanding their global footprint by offering cost-effective and technologically advanced solutions. The market also includes strong participation from engine specialists and foundries that serve both OEM and aftermarket segments. Strategic differentiation through proprietary technologies and customized solutions is becoming a key success factor. Companies aim to strengthen market presence through product diversification and expansion into electric and hybrid powertrain-compatible platforms, positioning themselves for long-term sustainability in a transitioning automotive industry.
Recent Developments
- In March 2024, Tata Motors Limited signed a memorandum of understanding with the Tamil Nadu government for new vehicle manufacturing investments, supporting continued advancements in engine and powertrain technologies, including potential developments in engine block design.
- On January 18, 2025, Cummins Group launched its next-generation HELM™ (Higher Efficiency, Lower Emissions, Multiple Fuels) engine platforms at the Bharat Mobility Global Expo 2025.
- On April 28, 2025, Daimler Truck North America announced that production of Freightliner Cascadia trucks featuring Cummins X15N natural gas engines will begin in summer 2025, marking the introduction of the industry’s first 15‑liter natural gas engine platform.
- In May 2025, Tata Motors Limited obtained licensing rights to develop and upgrade Fiat’s 2.0‑liter Multijet II diesel engine for its Harrier and Safari SUVs, enabling independent design enhancements.
- In June 2025, Renault Group confirmed plans for mass production of its next‑generation engine at the Cléon factory beginning in late 2027, advancing its commitment to sustainable powertrain innovation.
Market Concentration & Characteristics
The Engine Blocks Market is moderately concentrated, with a mix of global automotive OEMs and specialized engine component manufacturers dominating the landscape. Key players such as Toyota, Ford, General Motors, and Volkswagen hold significant market share due to large-scale production capabilities, established supply chains, and strong R&D infrastructure. It is characterized by high entry barriers due to the capital-intensive nature of engine block manufacturing and the need for precision engineering. Technological expertise, compliance with regulatory standards, and material innovation are critical competitive factors. The market exhibits a strong focus on quality control, lightweight materials, and hybrid compatibility, reflecting evolving customer and regulatory demands. Regional production hubs in Asia-Pacific and North America enable cost-effective operations and fast supply to major vehicle assembly plants. Companies compete on efficiency, product customization, and long-term OEM partnerships. It continues to evolve with increasing emphasis on electrification-ready platforms, environmentally sustainable manufacturing practices, and localized production strategies.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Vehicle Type, Manufacturing Process, Fuel type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for lightweight engine blocks will increase due to the push for fuel efficiency and emission reduction.
- Use of aluminum and composite materials will expand across all vehicle categories.
- Hybrid and plug-in hybrid vehicles will drive development of compatible engine block designs.
- 3D printing and precision casting technologies will gain broader adoption in manufacturing.
- Emerging economies will see strong growth in engine block production and vehicle sales.
- Engine block suppliers will invest more in R&D to meet regulatory and performance standards.
- Partnerships between OEMs and material innovators will shape product development.
- The aftermarket segment will grow due to longer vehicle life cycles and customization demand.
- Sustainability goals will lead manufacturers to explore recyclable and low-emission materials.
- Companies will expand regional production hubs to reduce lead times and improve supply chain resilience.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Vehicle Production
Increasing production of passenger and commercial vehicles, especially in emerging economies, directly boosts demand for engine blocks as core components in automotive manufacturing.
Technological Advancements in Manufacturing
Innovations such as high-pressure die casting, CNC machining, and 3D printing enable the production of lighter, more durable, and complex engine blocks, supporting OEMs' efforts to improve fuel efficiency and performance.
Stringent Emission and Fuel Efficiency Regulations
Tighter emission norms and fuel economy standards in major markets are pushing automakers to adopt lightweight materials and advanced engine block designs, driving market growth through regulatory compliance.
Expansion in Emerging Markets
Rapid urbanization, infrastructure development, and rising disposable incomes in Asia-Pacific, Latin America, and Africa are increasing vehicle ownership and, consequently, the need for new engine blocks.
Shift Toward Hybrid and Electric-Compatible Designs
The growing adoption of hybrid and plug-in hybrid vehicles is prompting manufacturers to develop engine blocks compatible with electrified powertrains, opening new avenues for market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Engine Blocks Market?
What factors are driving the growth of the Engine Blocks Market?
What are the key segments within the Engine Blocks Market?
What are some challenges faced by the Engine Blocks Market?
Who are the major players in the Engine Blocks Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel Type
- 1.2.1 Gasoline
- 1.2.2 Diesel
- 1.2.3 Others
- 1.3 By Vehicle Type
- 1.3.1 Passenger Cars
- 1.3.2 Light Commercial Vehicles
- 1.3.3 Heavy Commercial Vehicles
- 1.3.4 Others
- 1.4 By Material Type
- 1.4.1 Aluminum
- 1.4.2 Cast Iron
- 1.4.3 Compacted Graphite Iron
- 1.4.4 Others
- 1.5 By Manufacturing Process
- 1.5.1 Sand Casting
- 1.5.2 Die Casting
- 1.5.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 119,065 million → 2032: USD 191,641.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Engine Blocks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Engine Blocks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Engine Blocks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Engine Blocks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Engine Blocks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Engine Blocks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Engine Blocks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Engine Blocks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 119,065 million → 2032: USD 191,641.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Engine Blocks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gasoline
- 12.3.7.2 Diesel
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Cars
- 12.4.7.2 Light Commercial Vehicles
- 12.4.7.3 Heavy Commercial Vehicles
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aluminum
- 12.5.7.2 Cast Iron
- 12.5.7.3 Compacted Graphite Iron
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Manufacturing Process - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Sand Casting
- 12.6.7.2 Die Casting
- 12.6.7.3 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Engine Blocks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Engine Blocks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Engine Blocks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Toyota Motor Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Ford Motor Company
- 17.4 General Motors Company
- 17.5 Volkswagen AG
- 17.6 Hyundai Motor Company
- 17.7 Honda Motor Co., Ltd.
- 17.8 Nissan Motor Co., Ltd.
- 17.9 Fiat Chrysler Automobiles N.V.
- 17.10 BMW AG
- 17.11 Daimler AG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

