
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Environmental Monitoring System Market Size 2024 | USD 20,320 million |
| Environmental Monitoring System Market, CAGR | 5.29% |
| Environmental Monitoring System Market Size 2032 | USD 30,692 million |
Market Overview:
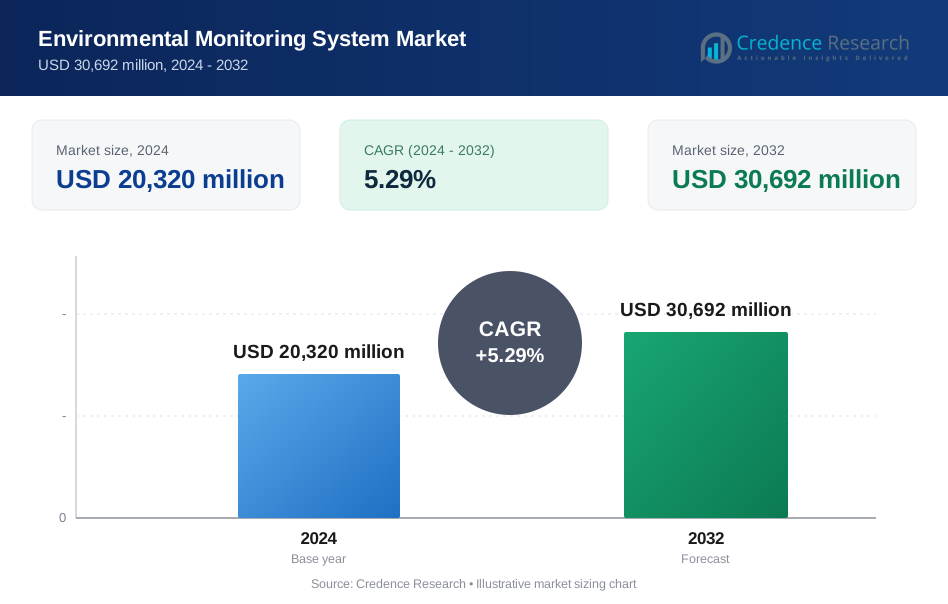
Environmental Monitoring System Market size was valued at USD 20,320 million in 2024 and is anticipated to reach USD 30,692 million by 2032, at a CAGR of 5.29% during the forecast period (2024-2032).
The market is driven by a combination of stringent environmental regulations, heightened global awareness of climate change, and the growing need for pollution monitoring in urban and industrial areas. Government mandates requiring regular environmental audits and emissions tracking are prompting industries to adopt automated monitoring systems. Industries such as manufacturing, energy, mining, and oil & gas are increasingly relying on these systems to maintain regulatory compliance and avoid penalties. The demand for smart city infrastructure and the rise in environmental disasters are also contributing to the broader deployment of monitoring solutions. Furthermore, advancements in sensor technology and data management are enhancing system accuracy, reliability, and scalability, encouraging further adoption. The growing consumer demand for environmental transparency is compelling businesses to disclose environmental performance more actively. In parallel, the use of portable and wireless devices is expanding the scope of real-time monitoring across remote and hard-to-access locations.
Regionally, North America holds a dominant share of the Environmental Monitoring System Market, supported by strict environmental policies, strong regulatory frameworks, and increased investment in clean technologies. Europe follows closely, driven by proactive sustainability initiatives and emission reduction goals. The Asia-Pacific region is expected to witness the fastest growth rate due to rising industrialization, urban expansion, and increasing government focus on environmental conservation. Countries like China, India, and South Korea are investing significantly in pollution monitoring infrastructure, creating lucrative opportunities for market players across the region. Rapid digital transformation across developing economies is supporting broader system adoption in environmental compliance programs. In Latin America and the Middle East, rising environmental health concerns are initiating government-funded monitoring initiatives, particularly in air and water quality.
Market Insights:
- The Environmental Monitoring System Market was valued at USD 20,320 million in 2024 and is projected to reach USD 30,692 million by 2032, growing at a CAGR of 5.29% from 2024 to 2032.
- Stringent environmental regulations and climate-related concerns are compelling industries to adopt automated monitoring systems for emissions, waste, and effluent tracking.
- Rapid industrialization and urban growth are increasing the demand for pollution monitoring, particularly in developing economies with expanding smart city initiatives.
- Technological advancements in IoT, cloud computing, and AI are enhancing system accuracy, real-time monitoring capabilities, and predictive analysis.
- High implementation costs and technical complexity remain key challenges, especially for small and medium enterprises and in cost-sensitive regions.
- North America leads the market with 38% share due to strict environmental enforcement, followed by Europe with 30% driven by sustainability targets, while Asia-Pacific shows the fastest growth at 24% market share.
- Growing interest in ESG compliance, sustainability-linked financing, and public demand for environmental transparency is accelerating the integration of monitoring systems across sectors.
Market Drivers:
Stringent Environmental Regulations Are Driving System Adoption:
Governments across the globe are tightening environmental regulations to mitigate pollution and safeguard public health. These policies mandate industries to monitor emissions, effluents, and waste continuously to meet compliance requirements. Regulatory frameworks such as the U.S. Clean Air Act, EU Industrial Emissions Directive, and India’s Environment Protection Act are compelling industries to adopt advanced monitoring systems. The Environmental Monitoring System Market is responding to this shift by offering automated, real-time solutions that ensure consistent regulatory adherence. Non-compliance penalties and reputational risks are motivating industries to implement robust monitoring infrastructure. Environmental audits and certifications increasingly depend on accurate, system-generated data, reinforcing demand across sectors.
Growing Industrialization and Urbanization Increase Pollution Surveillance Needs:
Rapid industrial growth and urban expansion in emerging economies are escalating pollution levels across air, water, and soil. Urban centers are facing pressure to control environmental degradation through continuous surveillance and corrective measures. The Environmental Monitoring System Market is expanding in response to this need for infrastructure capable of supporting large-scale monitoring operations. Smart cities, waste treatment plants, and transportation hubs require integrated solutions for real-time environmental data. Public demand for cleaner surroundings and safer living conditions is influencing municipal bodies to invest in modern monitoring technologies. It is also helping industries track their environmental performance and improve sustainability scores.
- For instance, the United States Environmental Protection Agency (EPA) conducts extensive air and water quality monitoring programs to address pollution in urban and industrial areas, and Siemens offers integrated environmental monitoring solutions used in smart city projects to track air quality and emissions in real time.
Technological Advancements Improve Accuracy and Data Efficiency:
Advances in IoT, wireless sensors, and cloud computing are transforming environmental monitoring capabilities. These technologies allow real-time data collection, transmission, and analysis from remote or harsh environments with minimal manual intervention. The Environmental Monitoring System Market is benefitting from these innovations, as users demand more accurate, scalable, and cost-effective tools. Artificial intelligence and machine learning models are now being integrated to predict pollution trends and automate alerts. It is also driving demand for mobile and portable monitoring devices in field operations and emergency response scenarios. Enhanced calibration features and user-friendly interfaces are encouraging wider adoption among non-specialist users.
- For instance, IBM's Green Horizons initiative uses AI and IoT to provide real-time air quality forecasting and pollution trend prediction, while Bosch offers wireless sensor networks and cloud-based platforms for scalable and accurate environmental data monitoring.
Corporate Sustainability Goals and ESG Mandates Drive System Integration:
Businesses are under pressure from investors, regulators, and consumers to align operations with environmental, social, and governance (ESG) criteria. Sustainability strategies now require measurable, traceable environmental data to demonstrate compliance and performance. The Environmental Monitoring System Market is addressing this need by delivering tools that support transparency and accountability in environmental reporting. Companies are embedding monitoring systems into their risk management and CSR frameworks to maintain investor confidence. It is also enabling firms to benchmark performance, reduce resource wastage, and improve brand reputation. Sustainability-linked loans and investor mandates are reinforcing the integration of monitoring systems across industries.
Market Trends:
Integration of Smart Technologies Is Reshaping Monitoring Capabilities:
The adoption of smart technologies is significantly enhancing the functionality and reach of environmental monitoring systems. IoT-enabled sensors, real-time data transmission, and cloud-based platforms are streamlining the process of capturing and analyzing environmental data. The Environmental Monitoring System Market is embracing these innovations to deliver faster, more reliable insights across air, water, and soil parameters. Smart systems now support predictive analytics and remote diagnostics, reducing manual intervention and operational delays. Integration with geospatial tools and satellite imagery is improving spatial analysis and broadening application scopes in agriculture, forestry, and urban planning. It is also enabling stakeholders to access centralized data dashboards for better decision-making and regulatory reporting.
- For instance, the U.S. Environmental Protection Agency (EPA) has implemented IoT-based air quality sensors in several pilot cities, enabling real-time data collection and analysis through cloud-based dashboards.
Shift Toward Decentralized and Portable Monitoring Solutions:
Demand is increasing for decentralized, compact systems that can operate efficiently in field conditions and remote locations. Traditional fixed stations are giving way to mobile units and handheld devices, allowing real-time monitoring in dynamic environments. The Environmental Monitoring System Market is evolving with this trend by offering rugged, battery-powered, and wireless-enabled devices suited for diverse use cases. These systems are proving essential in disaster-prone areas, mining zones, and temporary construction sites. It is also supporting NGOs, research institutes, and government agencies in community-level monitoring initiatives. The focus on flexibility, mobility, and ease of deployment is driving innovation in product design and field application.
- For instance, Thermo Fisher Scientific offers rugged, battery-powered environmental monitoring instruments that are widely used in field research and disaster response scenarios.
Market Challenges Analysis:
High Implementation Costs and Technical Complexity Limit Adoption:
The initial investment required for setting up comprehensive environmental monitoring systems remains a major barrier for small and medium enterprises. Costs associated with advanced sensors, data integration platforms, and maintenance can deter organizations from full-scale deployment. The Environmental Monitoring System Market faces resistance in cost-sensitive regions where budget constraints affect technology adoption. Technical complexity further compounds this challenge, especially when systems demand skilled personnel for calibration, data analysis, and compliance management. It creates gaps in implementation and reduces operational efficiency in underserved areas. Lack of standardized protocols also hampers interoperability across different monitoring platforms.
- For instance, the European Environment Agency (EEA) uses standardized environmental monitoring protocols to enhance data interoperability across member countries.
Data Management and Privacy Concerns Affect System Reliability:
The growing volume of environmental data raises challenges related to secure storage, processing accuracy, and real-time accessibility. Many industries lack robust data infrastructure to handle continuous monitoring outputs effectively. The Environmental Monitoring System Market is under pressure to address concerns around data security, especially when systems operate over cloud networks or transmit sensitive geolocation information. Errors in data interpretation or delayed reporting can lead to regulatory non-compliance or reputational damage. It also creates hesitation among end users who require high levels of system reliability and data integrity. The absence of unified regulatory standards for data handling adds to the complexity.
Market Opportunities:
Emerging Economies Present Untapped Growth Potential:
Rapid industrialization and urban development in emerging economies are creating substantial demand for environmental monitoring infrastructure. Countries in Asia-Pacific, Latin America, and Africa are investing in pollution control, water quality improvement, and sustainable urban planning. The Environmental Monitoring System Market has significant opportunities to expand in these regions, where regulatory bodies are introducing stricter environmental compliance frameworks. Governments are allocating funds for environmental projects, opening doors for technology providers and service integrators. It is enabling public-private partnerships to build scalable monitoring networks tailored to regional needs. Rising environmental awareness among communities is also driving demand for localized, low-cost monitoring solutions.
Digital Transformation Fuels Innovation and Service Expansion:
The acceleration of digital transformation across industries is unlocking new possibilities for monitoring applications. Cloud computing, artificial intelligence, and edge analytics are enhancing the speed and efficiency of environmental data processing. The Environmental Monitoring System Market is leveraging these advancements to offer real-time insights and predictive capabilities across complex ecosystems. Opportunities are expanding for subscription-based platforms, remote diagnostics, and mobile app integration that improve user engagement and operational control. It is also supporting the development of industry-specific solutions in sectors such as agriculture, healthcare, and logistics. The shift toward data-driven sustainability practices positions monitoring systems as critical tools for strategic decision-making.
Market Segmentation Analysis:
By Product Type
The Environmental Monitoring System Market includes particulate monitoring, gas monitoring, temperature monitoring, noise monitoring, and radiation detection systems. Gas monitoring holds the largest share due to regulatory focus on controlling industrial emissions and ambient air quality. Particulate monitoring is expanding rapidly in regions facing high levels of urban smog and construction-related dust pollution. Temperature and radiation detection systems are more prevalent in healthcare, laboratory, and nuclear facility applications. Noise monitoring is gaining relevance in urban planning and transportation infrastructure development. Each product type plays a role in delivering comprehensive environmental intelligence.
By Monitoring Parameters
The market is segmented into air, water, and soil monitoring based on environmental parameters. Air monitoring leads due to growing health concerns related to airborne pollutants and mandatory compliance in urban and industrial zones. Water monitoring systems are essential for detecting contaminants in municipal supply, wastewater treatment plants, and industrial discharge. Soil monitoring supports applications in agriculture, mining, and land restoration, where maintaining ecological balance is critical. The Environmental Monitoring System Market continues to prioritize air quality solutions, while demand for water and soil monitoring grows steadily across developing regions.
By Deployment Mode
Deployment modes include on-premise and cloud-based systems. On-premise systems dominate in sectors with strict data control needs, such as energy, defense, and heavy industries. Cloud-based solutions are expanding quickly due to cost efficiency, ease of remote access, and compatibility with smart devices. The Environmental Monitoring System Market is moving toward hybrid architectures that offer data security, scalability, and centralized reporting. It supports seamless integration with IoT platforms and enables stakeholders to monitor multiple locations from a single dashboard.
Segmentations:
By Product Type
- Particulate Monitoring Systems
- Gas Monitoring Systems
- Temperature Monitoring Systems
- Noise Monitoring Systems
- Radiation Detection Systems
By Monitoring Parameters
- Air Quality Monitoring
- Water Quality Monitoring
- Soil Monitoring
By Deployment Mode
- On-Premise
- Cloud-Based
By End-User
- Government and Public Authorities
- Industrial Facilities
- Commercial and Residential Buildings
- Healthcare Institutions
- Research and Academic Institutes
By Connectivity Technology
- Wired
- Wireless
- Hybrid
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Leads with Strong Regulatory Support and Technological Integration
North America accounts for 38% of the Environmental Monitoring System Market, driven by robust regulatory enforcement and widespread adoption of advanced technologies. The region maintains its lead through strong government mandates and well-funded environmental initiatives. The U.S. Environmental Protection Agency (EPA) requires continuous emissions monitoring, which pushes industries to implement high-performance monitoring systems. Investments in clean energy and smart infrastructure support system expansion in urban and industrial zones. The market benefits from an established network of technology developers and research institutions. It also incorporates AI-based analytics and cloud platforms to improve environmental data management. Strong public awareness and corporate accountability reinforce ongoing system integration.
Europe Strengthens Position Through Sustainability Goals and Emission Control
Europe holds 30% of the Environmental Monitoring System Market, supported by strict environmental policies and regional climate action plans. The European Union enforces aggressive emission reduction mandates through initiatives like the Green Deal and Industrial Emissions Directive. These efforts are accelerating system deployment in transportation, manufacturing, and energy sectors. It is advancing through the adoption of sensor-based air and water quality monitoring platforms. Key countries such as Germany, France, and the Netherlands are investing in urban pollution tracking and clean energy analytics. EU funding programs continue to back technological innovation and infrastructure expansion. Strong cross-border collaboration promotes standardization and drives demand for integrated systems.
Asia-Pacific Emerges as the Fastest Growing Region
Asia-Pacific represents 24% of the Environmental Monitoring System Market and is projected to register the fastest growth rate during the forecast period. Rapid industrial expansion, urban congestion, and rising environmental risks are pushing demand for real-time monitoring solutions. Governments in China, India, and South Korea are enforcing stricter compliance norms and investing in large-scale monitoring infrastructure. It is gaining momentum through public-private partnerships and smart city development. Domestic production of cost-efficient sensors and wireless systems supports affordability across sectors. Increasing environmental awareness and alignment with international sustainability goals further encourage adoption across industrial and municipal domains.
Key Player Analysis:
- SDL
- ABB
- Infore
- Shimadzu
- Endress+Hauser
- Focused Photonics
- Siemens
- Danaher
- Thermo Fisher
- Horiba
- Sick
- TSI Incrporated
- Xylem
- Environnement
- Sailhero
Competitive Analysis:
The Environmental Monitoring System Market is highly competitive, with key players focusing on innovation, strategic partnerships, and global expansion to strengthen their positions. Leading companies such as Thermo Fisher Scientific, Siemens AG, Honeywell International Inc., Agilent Technologies, and Teledyne Technologies dominate with comprehensive product portfolios and strong R&D capabilities. The market also includes specialized firms offering tailored solutions for air, water, and soil monitoring. It encourages competition through continuous advancements in IoT integration, real-time data analytics, and cloud-based platforms. Companies are enhancing product accuracy and user interface to meet evolving regulatory and industry demands. Regional players are gaining traction by delivering cost-effective systems and leveraging local distribution networks. The Environmental Monitoring System Market continues to evolve as manufacturers respond to stricter compliance requirements and rising environmental awareness. It favors firms that prioritize data security, system scalability, and technical support, especially in sectors with complex monitoring needs and high operational risk.
Recent Developments:
- In May 2024, Thermo Fisher announced the commencement of manufacturing Air Quality Monitoring System (AQMS) analyzers in India at its Nasik facility, supporting India’s localization and environmental stewardship efforts.
- In September 2024, TSI launched the TSI Link™ Smart Bridge, a SaaS product designed to enhance workflow and reporting for DustTrak™ monitors and other TSI devices, supporting remote and real-time environmental monitoring.
- In September 2024, FPI announced its independently innovated, fully automated AI water quality laboratory, capable of unmanned, around-the-clock monitoring and data analysis, improving efficiency for ecological environment monitoring.
Market Concentration & Characteristics:
The Environmental Monitoring System Market exhibits moderate to high market concentration, with a mix of global leaders and regional specialists competing across key segments. It features a strong presence of multinational corporations with diversified offerings, robust R&D pipelines, and established client bases across industrial and government sectors. Barriers to entry include high capital investment, technical expertise, and regulatory compliance requirements. The market is characterized by rapid technological advancements, integration of IoT and AI, and a growing preference for real-time, cloud-enabled systems. It also reflects increasing customer demand for scalable, modular, and portable monitoring solutions. Regulatory influence remains high, shaping product development and deployment strategies. The Environmental Monitoring System Market supports long-term contracts, recurring service models, and high customization to meet varied environmental and operational needs.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Monitoring Parameters, Deployment Mode, End-User, Connectivity Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Technological advancements will enhance real-time data collection and analysis, improving the accuracy and responsiveness of monitoring systems.
- Integration of artificial intelligence and machine learning will enable predictive analytics and support proactive environmental management.
- The demand for wireless and remote monitoring solutions will grow, supporting scalable deployments across industrial and remote settings.
- Emerging economies will increase investments in monitoring infrastructure to address rising pollution and meet international compliance standards.
- Regulatory frameworks will become stricter, prompting industries to adopt advanced monitoring technologies for environmental accountability.
- Public-private partnerships will help expand monitoring networks, especially in urban regions with high environmental risks.
- Healthcare organizations will integrate environmental monitoring to better understand pollutant exposure and its impact on population health.
- Development of low-cost, user-friendly devices will make monitoring accessible for small businesses and decentralized facilities.
- Climate change concerns will accelerate the implementation of comprehensive monitoring systems to support national and global climate strategies.
- Cross-border cooperation and international policy alignment will encourage standardization of monitoring protocols and data sharing initiatives.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Governments worldwide are enforcing stricter environmental regulations, requiring industries to continuously monitor emissions, effluents, and waste. This regulatory pressure is compelling organizations to adopt advanced, automated monitoring systems to ensure compliance and avoid penalties.
Rapid Industrialization and Urbanization
Emerging economies are experiencing fast-paced industrial growth and urban expansion, leading to increased pollution and environmental risks. This trend is driving demand for comprehensive monitoring systems to track and manage air, water, and soil quality in urban and industrial areas.
Technological Advancements in IoT and Data Analytics
Innovations in IoT, wireless sensors, and cloud computing are enabling real-time, accurate, and scalable environmental monitoring. These advancements are making systems more efficient and accessible, supporting broader adoption across sectors and geographies.
Corporate Sustainability and ESG Mandates
Businesses are under increasing pressure from investors, regulators, and consumers to demonstrate environmental responsibility and meet ESG criteria. This is accelerating the integration of monitoring systems for transparent reporting, risk management, and sustainability-linked financing.
Growing Demand for Smart City and Infrastructure Solutions
The development of smart cities and modern infrastructure projects requires integrated environmental monitoring to ensure public health and regulatory compliance. This is expanding the market for portable, wireless, and real-time monitoring solutions in both developed and developing regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected size of the Environmental Monitoring System Market?
What are the main factors driving the growth of this market?
Which regions are leading in market share and growth?
What technologies are shaping the future of this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Government and Public Authorities
- 1.2.2 Industrial Facilities
- 1.2.3 Commercial and Residential Buildings
- 1.2.4 Healthcare Institutions
- 1.2.5 Research and Academic Institutes
- 1.3 By Product Type
- 1.3.1 Particulate Monitoring Systems
- 1.3.2 Gas Monitoring Systems
- 1.3.3 Temperature Monitoring Systems
- 1.3.4 Noise Monitoring Systems
- 1.3.5 Radiation Detection Systems
- 1.4 By Deployment Mode
- 1.4.1 On-Premise
- 1.4.2 Cloud-Based
- 1.5 By Monitoring Parameters
- 1.5.1 Air Quality Monitoring
- 1.5.2 Water Quality Monitoring
- 1.5.3 Soil Monitoring
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,320 million → 2032: USD 30,692 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Environmental Monitoring System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Environmental Monitoring System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Environmental Monitoring System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Environmental Monitoring System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Environmental Monitoring System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Environmental Monitoring System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Environmental Monitoring System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Environmental Monitoring System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,320 million → 2032: USD 30,692 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Environmental Monitoring System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Government and Public Authorities
- 12.3.7.2 Industrial Facilities
- 12.3.7.3 Commercial and Residential Buildings
- 12.3.7.4 Healthcare Institutions
- 12.3.7.5 Research and Academic Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Particulate Monitoring Systems
- 12.4.7.2 Gas Monitoring Systems
- 12.4.7.3 Temperature Monitoring Systems
- 12.4.7.4 Noise Monitoring Systems
- 12.4.7.5 Radiation Detection Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premise
- 12.5.7.2 Cloud-Based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Monitoring Parameters - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Air Quality Monitoring
- 12.6.7.2 Water Quality Monitoring
- 12.6.7.3 Soil Monitoring
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Environmental Monitoring System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Environmental Monitoring System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Environmental Monitoring System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Environmental Monitoring System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens AG
- 18.4 Honeywell International Inc.
- 18.5 ABB
- 18.6 Shimadzu Corporation
- 18.7 Endress+Hauser
- 18.8 Danaher Corporation
- 18.9 Horiba
- 18.10 TSI Incorporated
- 18.11 Xylem
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

