
Market Overview:
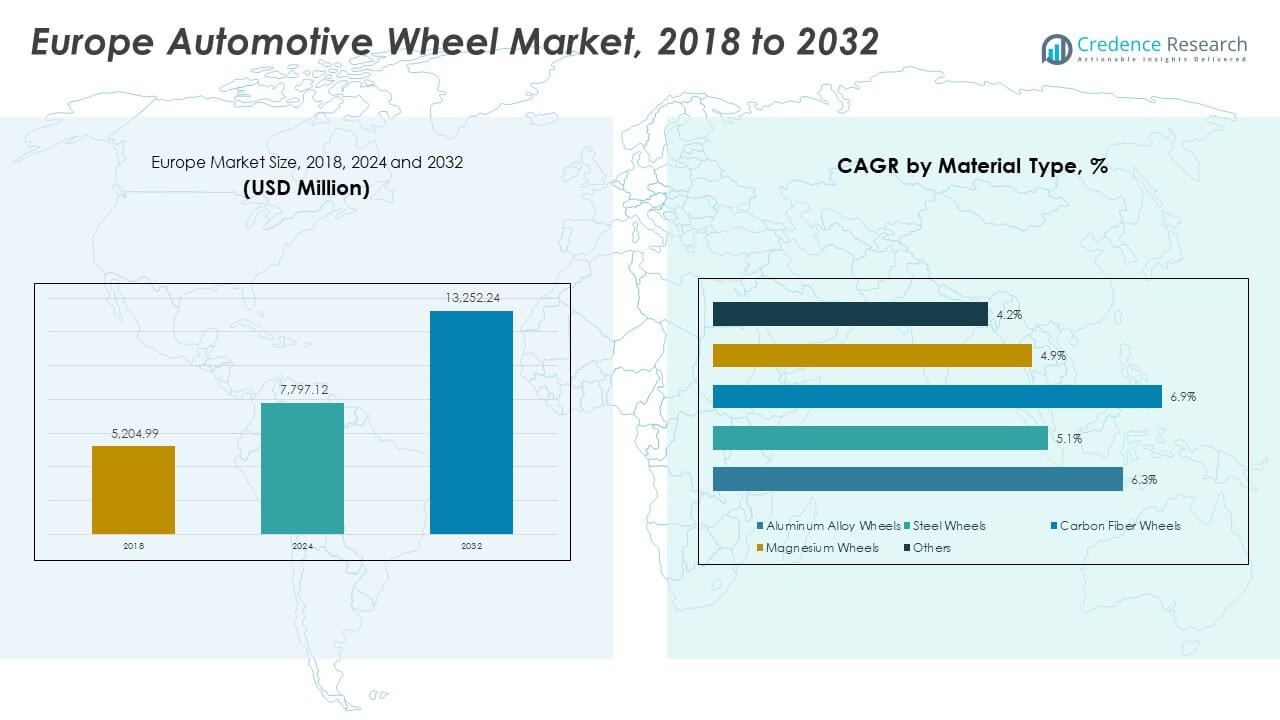
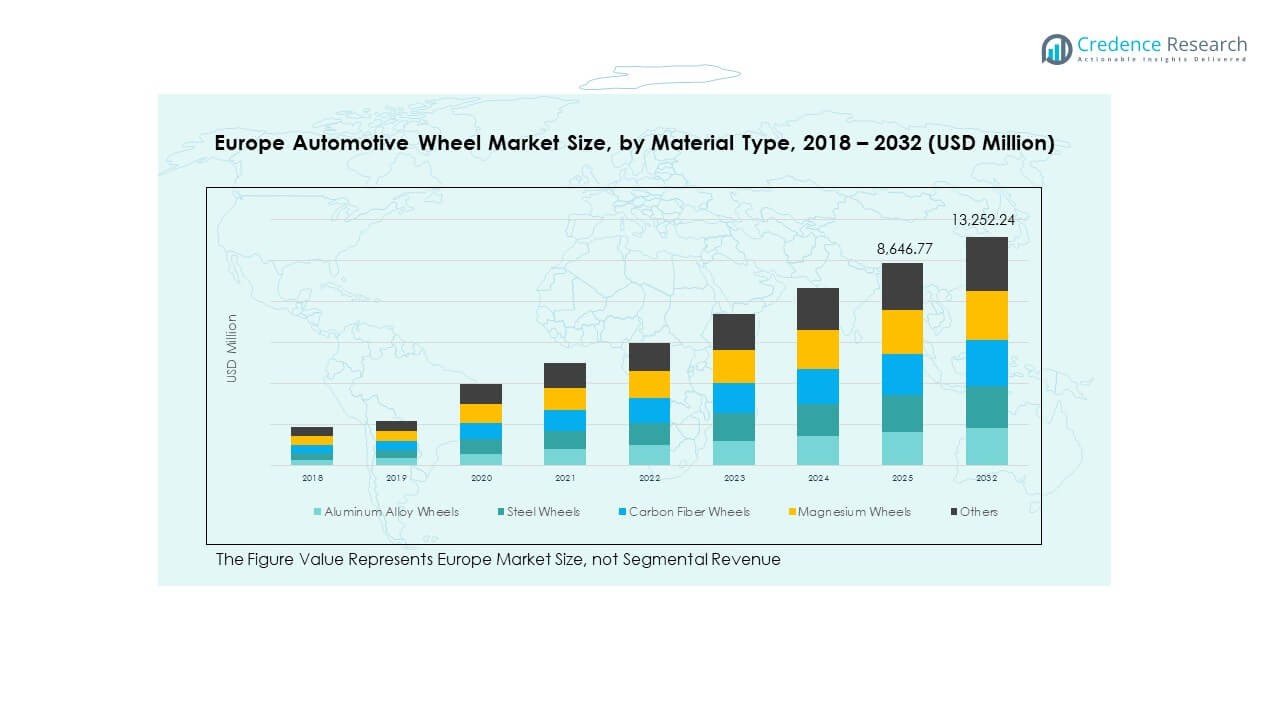
The Europe Automotive Wheel Market size was valued at USD 5,204.99 million in 2018 to USD 7,797.12 million in 2024 and is anticipated to reach USD 13,252.24 million by 2032, at a CAGR of 6.30% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Automotive Wheel Market Size 2024 | USD 7,797.12 Million |
| Europe Automotive Wheel Market, CAGR | 6.30% |
| Europe Automotive Wheel Market Size 2032 | USD 13,252.24 Million |
The market growth is driven by the rising adoption of lightweight materials and advanced wheel designs that enhance vehicle performance and fuel efficiency. Increasing electric vehicle production, demand for customized alloy wheels, and regulatory pressure to reduce carbon emissions are fueling innovation. Automakers are investing in aluminum and carbon fiber wheels to meet efficiency and aesthetic demands across premium and mass-market segments.
Germany leads the European market due to its strong automotive manufacturing base and R&D investment in lightweight materials. The U.K., France, and Italy are emerging markets driven by electric mobility expansion and rising consumer preference for performance-oriented vehicles. Eastern European countries are witnessing steady growth supported by growing auto component exports and local manufacturing investments.
Market Insights:
- The Europe Automotive Wheel Market was valued at USD 5,204.99 million in 2018, reached USD 7,797.12 million in 2024, and is projected to hit USD 13,252.24 million by 2032, registering a CAGR of 6.30%.
- Western Europe dominates with 56% share, driven by advanced manufacturing bases in Germany, France, and Italy supported by premium vehicle production and R&D strength.
- Eastern Europe holds 27% share due to low-cost manufacturing and growing OEM investments across Poland, Hungary, and the Czech Republic.
- Southern and Northern Europe together account for 17% share and represent the fastest-growing region, propelled by EV adoption, sustainability focus, and aftermarket expansion.
- Aluminum alloy wheels lead with about 46% share, followed by steel wheels at 28%, reflecting strong demand for lightweight, corrosion-resistant, and cost-effective designs.
Market Drivers:
Rising Demand for Lightweight and Fuel-Efficient Vehicles Across Europe
The Europe Automotive Wheel Market benefits from the growing need for lightweight and fuel-efficient vehicles. Automakers focus on weight reduction to improve mileage and cut CO₂ emissions under strict EU regulations. Aluminum and magnesium wheels replace traditional steel, improving performance and durability. The move toward electric vehicles also pushes demand for efficient and aerodynamic wheel designs. Consumers favor alloy wheels that enhance handling and aesthetics, supporting steady growth. Automotive suppliers invest in innovative wheel alloys that combine strength with reduced mass. It continues to evolve with OEM adoption of advanced lightweight materials and smart manufacturing processes.
- For instance, Alcoa Wheels reports weight savings of up to 51% when replacing traditional steel wheels with forged aluminium units, thereby improving efficiency and reducing emissions. Automakers focus on weight reduction to improve mileage and cut CO₂ emissions under strict EU regulations. Aluminium and magnesium wheels replace traditional steel, improving performance and durability.
Growth in Electric Mobility and Vehicle Electrification Programs
Expansion of electric vehicle production strengthens market growth across key European countries. Wheel manufacturers design aerodynamic, low-resistance wheels to extend EV range and improve efficiency. Governments support this transition through incentives for zero-emission vehicles, creating long-term demand. The push toward sustainable materials aligns with the rise of EVs in passenger and commercial fleets. Lightweight aluminum and forged alloys dominate due to their ability to reduce unsprung mass. It encourages automakers to adopt customized EV-compatible wheels optimized for battery performance. Research initiatives in EV integration and battery cooling further enhance the technical scope of wheel production.
- For instance, Ronal Group AG manufactures over 18 million wheels annually and uses forging and flow-forming technologies to support both OEM and aftermarket electric vehicle applications. Wheel manufacturers design aerodynamic, low-resistance wheels, such as the carbon-neutral R70-blue, to extend EV range and improve efficiency. Governments support this transition through incentives for zero-emission vehicles, creating long-term demand.
Strong Focus on Aesthetic Appeal and Vehicle Customization
Growing consumer interest in vehicle aesthetics drives the demand for customized and premium wheel finishes. Automakers and aftermarket players offer a wide variety of alloy designs, surface coatings, and color options. Customers prefer wheels that reflect personal style while maintaining structural strength. The Europe Automotive Wheel Market benefits from the rising trend of personalized luxury vehicles. Paint, chrome, and diamond-cut finishes increase in demand across both OEM and aftermarket channels. It supports a growing niche for high-end wheel design and branding. Evolving lifestyle preferences among younger buyers sustain this trend in urban and performance vehicle categories.
Technological Advancements and Adoption of Smart Manufacturing Systems
Advances in production technologies enhance precision and material utilization in wheel manufacturing. Use of robotics, additive manufacturing, and AI-based quality inspection improves output consistency. Integration of digital twins helps manufacturers monitor fatigue resistance and optimize performance during design. The Europe Automotive Wheel Market witnesses automation across casting, forging, and finishing operations. New surface treatment processes extend product lifespan and protect against corrosion. Automation reduces labor costs and waste while increasing throughput efficiency. It enables suppliers to maintain competitive pricing despite material cost fluctuations and global supply chain challenges.
 Market Trends:
Shift Toward Sustainable and Recyclable Wheel Materials
Manufacturers are increasingly using sustainable materials such as recycled aluminum and bio-based composites. This shift supports Europe’s climate neutrality goals under the Green Deal initiative. Companies invest in closed-loop production systems to reuse scrap material and minimize waste. It improves resource efficiency while reducing carbon footprint during production. Demand for green-certified materials drives partnerships between OEMs and raw material suppliers. Sustainable wheel manufacturing appeals to environmentally conscious consumers and enhances brand image. The trend sets a foundation for long-term competitiveness in a low-emission economy.
- For instance, Constellium SE’s C-TEC research centre has developed high-strength automotive aluminium alloys and holds over 600 patent families in lightweight structural components. This shift supports Europe’s climate neutrality goals under the Green Deal initiative. Companies invest in closed-loop production systems to reuse scrap material and minimise waste.
Integration of Smart and Sensor-Enabled Wheel Technologies
Integration of sensors into wheels enhances real-time data tracking for temperature, tire pressure, and load distribution. These smart systems improve safety, efficiency, and predictive maintenance in connected vehicles. The Europe Automotive Wheel Market benefits from the growth of intelligent mobility solutions. Manufacturers collaborate with electronics firms to embed IoT-based components into wheel assemblies. Such integration supports fleet management and advanced driver-assistance systems. It also helps detect early signs of wear and improve performance monitoring. Demand for smart wheels grows as vehicles transition toward higher automation levels.
- For instance, NIRA Dynamics AB’s Tire Pressure Indicator (TPI) system has been installed in over 110 million vehicles and supports indirect wheel-based monitoring without additional physical sensors. These smart systems improve safety, efficiency, and predictive maintenance in connected vehicles. The Europe Automotive Wheel Market benefits from the growth of intelligent mobility solutions.
Increasing Popularity of Premium and Performance Vehicle Segments
Luxury and sports car manufacturers increasingly rely on forged and precision-engineered alloy wheels. Premium vehicles emphasize aesthetics, performance, and brand exclusivity, encouraging innovation in wheel design. The market gains traction from rising disposable incomes and consumer interest in high-end mobility. Advanced wheel coatings enhance corrosion resistance and maintain a distinctive finish. It reinforces manufacturer focus on craftsmanship and precision detailing. The Europe Automotive Wheel Market continues to expand through the luxury aftermarket segment. Demand for performance upgrades sustains wheel innovation among boutique and mainstream brands alike.
Adoption of Hybrid Manufacturing and Advanced Design Technologies
The use of hybrid manufacturing methods combines casting, forging, and machining for enhanced performance. These techniques optimize material flow, density, and impact resistance in finished products. Adoption of computer-aided design (CAD) and simulation tools ensures structural integrity and lightweight balance. 3D printing supports prototyping and customization for low-volume production lines. It helps suppliers reduce development time while maintaining accuracy. The Europe Automotive Wheel Market evolves toward digital design environments that streamline innovation cycles. Continuous R&D efforts enhance flexibility, allowing faster adaptation to evolving consumer preferences.
Market Challenges Analysis:
Volatility in Raw Material Costs and Supply Chain Disruptions
Fluctuating prices of aluminum, magnesium, and other alloying metals create uncertainty in production planning. High energy costs in Europe increase operational expenses and pressure profit margins. Supply chain interruptions due to geopolitical tensions disrupt raw material sourcing. The Europe Automotive Wheel Market faces constraints from limited availability of specialized alloys. Logistics delays affect just-in-time delivery models critical for OEM operations. Manufacturers must balance cost control with maintaining product quality and performance standards. It pushes the need for diversified supplier networks and localized manufacturing strategies to reduce risk.
Stringent Environmental and Safety Regulations Affecting Design Flexibility
EU emission and recycling standards impose strict requirements on wheel materials and coatings. Compliance with REACH and Euro 7 standards limits the use of certain surface chemicals. Manufacturers must redesign processes to meet durability and sustainability benchmarks. Testing protocols for impact resistance and fatigue life add to time and development costs. The Europe Automotive Wheel Market encounters challenges adapting to evolving safety regulations. Restrictions on volatile organic compounds affect finishing and painting technologies. It compels the industry to invest heavily in R&D to balance safety, design freedom, and environmental compliance.
Market Opportunities:
Expansion of Electric and Autonomous Vehicle Segments in Europe
The growing electric and autonomous vehicle markets create new opportunities for wheel manufacturers. Lightweight aerodynamic wheels support higher energy efficiency and longer driving range. Automakers demand designs that integrate seamlessly with regenerative braking and low-noise requirements. The Europe Automotive Wheel Market benefits from collaborations between OEMs and technology providers. It allows development of advanced wheel systems tailored for next-generation EVs and automated fleets. Demand for quiet, durable, and energy-optimized wheels continues to accelerate with the mobility transition.
Emergence of Aftermarket Customization and Premium Wheel Upgrades
The expanding aftermarket for performance and aesthetic upgrades creates new revenue streams. Consumers seek stylish and personalized wheels that complement modern vehicle designs. Growth in online retailing and customization services supports this segment. The Europe Automotive Wheel Market gains from rising disposable incomes and enthusiasm for visual enhancement. It fosters innovation in modular design, finishes, and 3D-printed accessories. Increasing use of digital configurators simplifies selection and encourages premium purchases. Manufacturers offering flexible customization options strengthen brand loyalty and expand their market reach.
Market Segmentation Analysis:
By Material Type
The Europe Automotive Wheel Market is segmented by material type into aluminum alloy, steel, carbon fiber, magnesium, and others. Aluminum alloy wheels dominate due to their lightweight structure, corrosion resistance, and contribution to fuel efficiency. Steel wheels maintain steady demand in heavy-duty and commercial vehicles for their durability and affordability. Carbon fiber wheels gain traction in premium and sports segments because of their superior strength-to-weight ratio. Magnesium wheels appeal to performance-focused consumers for enhanced acceleration and reduced inertia. It continues evolving with innovations in hybrid composite materials designed for sustainability and recyclability.
- For instance, Carbon Revolution Ltd. developed 23-inch and 24-inch carbon-fibre wheels achieving approximately 45 % weight savings compared with aluminium equivalents. Magnesium wheels appeal to performance-focused consumers for enhanced acceleration and reduced inertia.
By Vehicle Type
The market is segmented by vehicle type into passenger vehicles, commercial vehicles, and off-highway vehicles. Passenger vehicles lead the segment, supported by higher production volumes and consumer preference for enhanced aesthetics and comfort. Commercial vehicles rely on robust steel and forged alloy wheels to meet the demands of logistics and transportation sectors. Off-highway vehicles, including agricultural and construction machinery, utilize reinforced wheels for performance under extreme conditions. It experiences growing diversification as automakers introduce vehicle-specific wheel designs optimized for energy efficiency and performance.
- For instance, OEM steel wheels for off-highway use are made in spun or pressed formats exceeding 54-inch diameters for heavy-duty farm machinery. It experiences growing diversification as automakers introduce vehicle-specific wheel designs optimised for energy efficiency and performance.
By End User
The market is classified by end user into OEM and aftermarket categories. OEMs dominate due to strong collaborations with automakers and the integration of advanced wheel technologies during vehicle assembly. The aftermarket segment grows rapidly with increasing demand for replacement and customization options. Consumers seek personalized finishes and lightweight upgrades that enhance vehicle performance. It benefits from online retail channels and the rising popularity of customization culture across Europe.
Segmentation:
By Material Type
- Aluminum Alloy Wheels
- Steel Wheels
- Carbon Fiber Wheels
- Magnesium Wheels
- Others
By Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
- Off-Highway Vehicles
By End User
- OEM (Original Equipment Manufacturer)
- Aftermarket
By Region
- Europe
- United Kingdom (UK)
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Regional Analysis:
Western Europe – Established Manufacturing Base and Premium Demand
Western Europe holds the dominant share of 56% in the Europe Automotive Wheel Market. Germany leads production with a strong automotive manufacturing network supported by BMW, Volkswagen, and Mercedes-Benz. The region emphasizes advanced wheel technologies and high-quality materials for performance and electric vehicles. France and Italy contribute significantly through luxury and sports car segments, where design precision drives wheel innovation. The aftermarket in the United Kingdom shows steady expansion due to consumer interest in customization and alloy upgrades. It maintains its leadership with continuous R&D investments, advanced forging technologies, and compliance with EU emission standards.
Eastern Europe – Expanding Industrial Footprint and Cost-Effective Manufacturing
Eastern Europe accounts for around 27% market share, supported by low production costs and skilled labor availability. Poland, the Czech Republic, and Hungary attract automotive wheel investments due to government incentives and supplier networks. Local plants serve both regional demand and export requirements for Western Europe. The market benefits from proximity to major European automakers, ensuring efficient logistics and supply chain operations. Rising demand for commercial and passenger vehicles increases OEM wheel production. It continues to emerge as a preferred hub for aluminum wheel casting and steel wheel manufacturing under expanding trade partnerships.
Southern and Northern Europe – Niche Growth Through Electrification and Aftermarket Expansion
Southern and Northern Europe together represent 17% of the total market share, focusing on specialty wheel production and electric vehicle integration. Spain and Italy support growing adoption of lightweight alloy wheels through expanding EV assembly plants. Scandinavian countries such as Sweden and Norway lead in sustainable automotive initiatives, encouraging demand for recyclable materials. The aftermarket in these regions benefits from premium vehicle sales and increased spending on performance wheels. Collaboration between regional suppliers and global brands enhances product diversification and availability. It demonstrates strong growth potential driven by electrification, design innovation, and circular economy strategies.
Key Player Analysis:
- Maxion Wheels
- Accuride Corporation
- Superior Industries International, Inc.
- American Eagle Wheels
- Alcoa Wheels
- MHT Luxury Wheels
- Wheel Pros
- Brixton Forged
- RTX Wheels
- Enkei
Competitive Analysis:
The Europe Automotive Wheel Market is highly competitive, with strong participation from both global and regional manufacturers. Companies focus on advanced materials, lightweight designs, and digital manufacturing processes to enhance efficiency and sustainability. Leading players such as Maxion Wheels, Accuride Corporation, and Superior Industries International compete through innovation, strategic partnerships, and expansion of OEM contracts. The industry shows consolidation trends as firms invest in automation and smart inspection systems to improve quality. It emphasizes customization, corrosion resistance, and advanced surface coatings to meet evolving design standards and consumer expectations.
Recent Developments:
- Enkei established a strategic distribution partnership in the Philippines in August 2025, with Wheel Gallery officially appointed as the Enkei wheel distributor by YHI Philippines, a subsidiary of YHI International Limited. The partnership encompasses Enkei's complete lineup, including Racing Series, Tuning Series, Performance Series, and Truck & SUV wheel models.
- American Eagle Wheels ventured into lifestyle collaborations beyond traditional automotive wheel manufacturing, debuting a limited-edition partnership with Tru Kolors by Travis Kelce in August 2025. This diversification strategy represents the company's expansion into broader consumer markets while maintaining its core wheel business operations.
- Superior Industries International, Inc. received shareholder approval in September 2025 for its acquisition by a group of term loan investors led by Oaktree Capital Management. The acquisition was initially announced on July 9, 2025, with all required regulatory approvals obtained by September 15, 2025, and the transaction anticipated to close on or before September 30, 2025. Superior Industries, with annual revenues of $1.16 billion, continues manufacturing aluminum wheels for the automotive industry while navigating significant capital structure challenges.
Report Coverage:
The research report offers an in-depth analysis based on material type, vehicle type, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of lightweight alloys will redefine production efficiency and performance standards.
- Integration of smart wheel sensors will enhance vehicle safety and diagnostics.
- Electric mobility expansion will create demand for aerodynamic and low-resistance wheels.
- Recyclable materials will gain prominence to align with EU sustainability goals.
- Aftermarket customization will grow with digital design and e-commerce platforms.
- Automation and AI-driven quality control will improve precision and reduce costs.
- Strategic collaborations between OEMs and suppliers will accelerate design innovation.
- Carbon fiber and hybrid composites will enter mainstream use in premium segments.
- Regional manufacturing hubs in Eastern Europe will strengthen supply chain resilience.
- Continuous R&D investment will sustain competitiveness in a transitioning mobility ecosystem.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Europe Automotive Wheel Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Automotive Wheel Market projected to grow between 2024 and 2032?
Which Europe Automotive Wheel Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Automotive Wheel Market?
Who are the leading companies in the Europe Automotive Wheel Market?
Which region commanded the largest share of the Europe Automotive Wheel Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,797.12 million → 2032: USD 13,252.24 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Automotive Wheel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Automotive Wheel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Automotive Wheel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Automotive Wheel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Automotive Wheel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Automotive Wheel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Automotive Wheel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Automotive Wheel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,797.12 million → 2032: USD 13,252.24 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Automotive Wheel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Automotive Wheel Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Automotive Wheel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Automotive Wheel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

