
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Enameled Cookware Market Size 2024 | USD 289.7 Million |
| Europe Enameled Cookware Market, CAGR | 6.21% |
| Europe Enameled Cookware Market Size 2032 | USD 469.25 Million |
Market Overview:
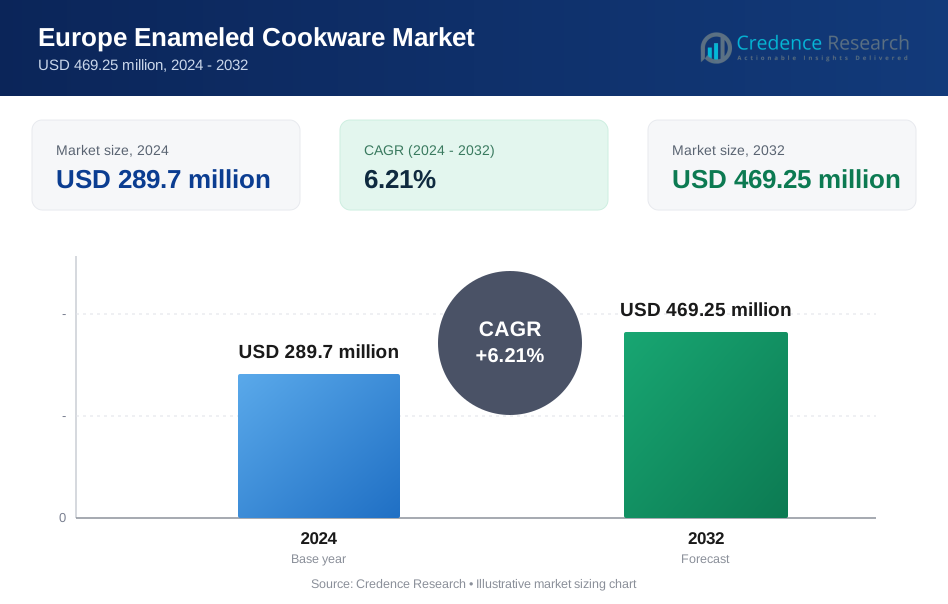
The Europe Enameled Cookware Market is projected to grow from USD 289.7 million in 2024 to an estimated USD 469.25 million by 2032, with a compound annual growth rate (CAGR) of 6.21% from 2024 to 2032.
Growing awareness about the advantages of enameled cookware, such as its ability to retain flavors, resistance to rust, and compatibility with various heat sources, is a key driver for Europe Enameled Cookware market expansion. The increasing trend of home cooking, driven by health consciousness and the rise of gourmet home chefs, is further propelling demand. Additionally, the surge in sustainable and eco-friendly cookware preferences is influencing manufacturers to innovate, enhancing product longevity and reducing environmental impact. The rising popularity of induction cooktops and the compatibility of enameled cookware with such modern appliances are further accelerating adoption. Moreover, the premium positioning of enameled cookware is attracting consumers willing to invest in high-quality, long-lasting kitchenware.
Regionally, Western Europe dominates the market due to strong consumer demand in countries such as Germany, France, and the UK, where premium kitchenware holds high appeal. Southern Europe, particularly Italy and Spain, is also experiencing growth driven by culinary traditions and rising disposable incomes. Eastern Europe is emerging as a potential growth hub, supported by increasing urbanization and expanding retail distribution networks. The presence of well-established brands and the introduction of innovative product designs are also shaping market dynamics across the region. Furthermore, the growing influence of social media and online culinary communities is playing a crucial role in driving awareness and influencing consumer purchasing decisions.
Market Insights:
- The Europe enameled cookware market is projected to grow from USD 289.7 million in 2024 to USD 469.25 million by 2032, registering a CAGR of 6.21% during the forecast period.
- Increasing consumer awareness of enameled cookware’s heat retention, durability, and non-reactive properties is driving market expansion, particularly among home cooks and professional chefs.
- Sustainability trends are influencing manufacturers to develop eco-friendly, long-lasting cookware, with growing demand for recyclable materials and non-toxic enamel coatings.
- The premium segment is expanding, as consumers prioritize high-quality cookware that offers both functional benefits and aesthetic appeal, driving innovation in design and color variety.
- E-commerce and online retail platforms are reshaping purchasing patterns, enabling direct-to-consumer sales, wider accessibility, and increased brand competition across Europe.
- Western Europe leads the market, with Germany, France, and the UK driving demand for premium cookware, while Eastern Europe emerges as a high-growth region due to rising urbanization and increasing disposable incomes.
- Challenges such as high product costs, susceptibility to chipping, and competition from alternative cookware materials may impact market growth, requiring manufacturers to focus on durability and cost-effective production strategies.
Market Drivers:
Increasing Consumer Preference for Premium and Durable Cookware
Consumers across Europe are increasingly prioritizing high-quality cookware that offers durability, functionality, and aesthetic appeal. Enameled cookware, known for its superior heat retention, resistance to rust, and ability to preserve flavors, has gained significant traction among both professional chefs and home cooks. For instance, Le Creuset, a leading brand in Europe, offers its Signature Round Dutch Oven, renowned for its durability, superior heat retention, and vibrant color options like Cerise and Marseille Blue. The growing preference for premium kitchenware is further driven by changing consumer lifestyles, where high-end and long-lasting cookware is seen as a valuable investment. Additionally, the availability of enameled cookware in a variety of colors and designs enhances its appeal, making it a preferred choice for modern and stylish kitchens.
Rising Health Consciousness and Shift Towards Home Cooking
Health-conscious consumers are actively seeking cookware that does not leach harmful chemicals into food, making enameled cookware an attractive option. Unlike non-stick alternatives that may contain synthetic coatings, enameled cookware provides a safe, non-reactive surface, contributing to its growing popularity. For instance, Staub’s Cocotte Round French Oven is a prime example, providing a non-reactive enamel surface that ensures safe cooking without chemical leaching. The increasing trend of home cooking, fueled by a desire for healthier eating habits and greater control over ingredients, has further accelerated demand. As consumers explore gourmet and traditional cooking styles at home, enameled cookware has emerged as a favored choice due to its versatility across different cooking methods and heat sources.
Growth of Sustainable and Eco-Friendly Kitchenware Trends
Sustainability has become a critical factor influencing purchasing decisions, with consumers actively seeking eco-friendly kitchenware. Enameled cookware, known for its durability and long lifespan, aligns with sustainability goals by reducing the frequency of replacements and minimizing waste. Additionally, manufacturers are focusing on sustainable production processes, using non-toxic coatings and recyclable materials to appeal to environmentally conscious buyers. For instance, Zwilling has introduced its Enameled Cast Iron Cookware line, which uses eco-friendly coatings and recyclable materials, aligning with Europe’s sustainability goals. The emphasis on reducing carbon footprints and promoting reusable products has further strengthened the demand for enameled cookware in the European market, positioning it as a viable alternative to disposable or chemically treated cookware options.
Expansion of Online Retail and Digital Influence on Consumer Choices
The rapid expansion of e-commerce platforms and the influence of digital marketing have played a pivotal role in boosting the enameled cookware market in Europe. Consumers now have access to a wide range of brands, product reviews, and detailed comparisons, enabling them to make informed purchasing decisions. For example, Misen, a DTC brand, has gained traction in Europe through its online platform, offering high-quality enameled cast iron Dutch ovens at competitive prices. The growing presence of social media influencers and culinary content creators has also contributed to increased awareness and demand for enameled cookware. As online retail channels continue to offer exclusive deals, direct-to-consumer models, and convenient home delivery options, the market for enameled cookware is expected to experience sustained growth across the region.
Market Trends:
Increasing Demand for Multi-Functional and Versatile Cookware
Consumers across Europe are seeking cookware that offers versatility across different cooking methods and heat sources. Enameled cookware, compatible with gas, electric, and induction stovetops, as well as ovens, has gained popularity due to its multi-functional properties. For instance, Staub’s Universal Pan is a versatile enameled cookware piece that can be used on gas, electric, and induction stovetops, as well as in ovens. The ability to transition seamlessly from stovetop to oven and even to the dining table enhances its appeal. Additionally, the rise of compact and modular kitchen designs has encouraged consumers to invest in cookware that serves multiple purposes, reducing the need for excessive kitchenware while maintaining efficiency.
Growing Influence of Aesthetic Appeal in Purchasing Decisions
Aesthetic appeal has become a significant factor influencing consumer choices in the enameled cookware market. The demand for cookware that complements modern kitchen interiors has led to an increased focus on color, design, and finishing. Manufacturers are introducing cookware in a wide range of vibrant hues, pastel shades, and classic enamel coatings to cater to evolving consumer preferences. For instance, Le Creuset’s Limited Edition Artisan Collection features handcrafted enameled cookware in unique, gradient color finishes like Sea Salt and Fig, blending functionality with artistic design. Limited-edition collections and collaborations with designers have further fueled the trend of cookware being perceived as both a functional tool and a statement piece. This shift has been particularly evident in premium markets, where consumers are willing to pay a premium for visually appealing and high-quality cookware.
Increasing Adoption of Direct-to-Consumer and E-Commerce Sales Channels
The rise of direct-to-consumer (DTC) brands and the rapid expansion of e-commerce platforms have transformed the enameled cookware market in Europe. Consumers are increasingly opting for online purchases due to the convenience of browsing extensive product selections, accessing detailed specifications, and comparing prices before making a purchase. Brands are leveraging digital platforms to engage with customers through interactive content, virtual demonstrations, and influencer partnerships. For instance, Mauviel, the esteemed French cookware brand, has expanded its digital presence by offering its products through online platforms. Additionally, subscription-based cookware services and exclusive online collections are gaining traction, further reshaping how consumers access and purchase enameled cookware.
Rising Popularity of High-Performance and Technologically Enhanced Cookware
Innovation in material science and manufacturing processes has led to the development of high-performance enameled cookware with enhanced durability and functionality. Advances in enamel coating technology have resulted in improved heat distribution, non-stick properties, and resistance to chipping or cracking. Some manufacturers are integrating smart cooking features, such as heat sensors and temperature indicators, to provide a more controlled cooking experience. For instance, The Hestan Cue system includes cookware with embedded sensors that monitor temperature and adjust heat levels in real-time, ensuring consistent and accurate cooking results. As consumers become more knowledgeable about cookware quality and performance, demand for technologically advanced enameled cookware is expected to rise, driving further market expansion across Europe.
Market Challenges Analysis:
High Cost of Premium Enameled Cookware
One of the primary challenges in the Europe enameled cookware market is the high cost associated with premium products. Enameled cookware, particularly from established brands, is often priced significantly higher than alternative cookware materials such as stainless steel, aluminum, or non-stick options. The cost factor can deter price-sensitive consumers, limiting market penetration, especially in regions where affordability plays a crucial role in purchasing decisions. While high durability and aesthetic appeal justify the pricing for some consumers, budget-conscious buyers may opt for more cost-effective alternatives, slowing overall market growth.
Susceptibility to Chipping and Wear Over Time
Despite its durability, enameled cookware is prone to chipping, cracking, or wear over prolonged use, which can impact its long-term usability. Unlike stainless steel or cast iron cookware, which can withstand heavy usage with minimal maintenance, enameled cookware requires careful handling to prevent surface damage. Consumers may hesitate to invest in cookware that demands extra care, particularly in households with frequent or high-intensity cooking routines. This concern also contributes to a slower replacement cycle, reducing repeat purchases and affecting overall market expansion.
Intense Market Competition from Alternative Cookware Materials
The enameled cookware market faces strong competition from other cookware materials, including stainless steel, ceramic, and advanced non-stick options. Many consumers are drawn to non-stick coatings for their easy maintenance and lightweight properties, while stainless steel remains a staple in professional and home kitchens due to its durability and cost-effectiveness. With ongoing advancements in cookware technology, alternative materials continue to gain traction, creating competitive pressure for enameled cookware manufacturers to differentiate their offerings through innovation and branding.
Supply Chain Disruptions and Rising Raw Material Costs
Fluctuations in raw material prices, particularly for cast iron and enamel coatings, pose challenges for manufacturers in maintaining cost efficiency and competitive pricing. Additionally, supply chain disruptions, driven by global logistics constraints and fluctuating energy costs, have impacted production timelines and product availability. These challenges have led to occasional shortages and increased costs for both manufacturers and consumers. To navigate these constraints, market players must focus on optimizing supply chains, securing sustainable sourcing practices, and implementing cost-effective production strategies to maintain profitability.
Market Opportunities:
The Europe enameled cookware market presents significant growth opportunities driven by increasing consumer demand for high-quality, durable, and aesthetically appealing kitchenware. As more consumers prioritize long-lasting and multi-functional cookware, manufacturers have the opportunity to expand their product lines with innovative designs and enhanced performance features. The growing interest in home cooking, fueled by health-conscious lifestyles and the popularity of gourmet culinary experiences, further boosts the demand for enameled cookware. Additionally, the rising influence of social media and digital marketing allows brands to directly engage with consumers, increasing awareness and driving product adoption.
Sustainability and eco-friendly consumer preferences also present a major opportunity for market expansion. As more buyers seek environmentally responsible kitchenware, manufacturers can leverage sustainable production processes, recyclable materials, and non-toxic enamel coatings to differentiate their products. The increasing shift towards online retail and direct-to-consumer sales channels offers another growth avenue, enabling brands to reach a broader audience while reducing distribution costs. Emerging markets within Eastern Europe, where urbanization and disposable incomes are rising, provide additional potential for market penetration. By focusing on technological advancements, premium aesthetics, and sustainable solutions, market players can capitalize on evolving consumer trends and strengthen their position in the competitive European enameled cookware market.
Market Segmentation Analysis:
The Europe enameled cookware market is segmented by type, material, end-user, and distribution channel, each playing a crucial role in market dynamics and growth trends.
By Type, Dutch ovens hold a significant share due to their versatility in slow cooking and heat retention, making them popular among both home cooks and professional chefs. Pans and pots are also widely adopted, driven by increasing demand for durable cookware that enhances cooking efficiency. Baking dishes are witnessing steady growth, supported by the rising popularity of home baking and the preference for aesthetically appealing oven-to-table cookware.
By Material, cast iron dominates the market due to its superior heat retention, durability, and non-reactive properties. Steel enameled cookware is also gaining traction, offering lightweight alternatives with enhanced resistance to rust and chipping. Other materials, including aluminum-based enameled cookware, cater to niche segments seeking affordability and easy maintenance.
By End-User, the residential sector leads market demand, driven by the growing trend of home cooking and premium kitchenware adoption. The commercial sector, including hotels and restaurants, is expanding as professional chefs prefer enameled cookware for its heat efficiency and durability.
By Distribution Channel, offline retail, including specialty cookware stores and department stores, remains the dominant sales channel, offering customers the ability to assess product quality before purchase. However, online channels are growing rapidly, supported by e-commerce platforms providing wider product accessibility, competitive pricing, and direct-to-consumer sales strategies.
Segmentation:
By Type
- Pots
- Pans
- Dutch Ovens
- Baking Dishes
- Others
By Material
- Cast Iron
- Steel
- Others
By End-User
- Residential
- Commercial
By Distribution Channel
- Online
- Offline
Regional Analysis:
Western Europe Leading with Strong Market Presence
Western Europe holds the largest market share in the Europe enameled cookware market, accounting for approximately 45% of total revenue. Countries such as Germany, France, and the United Kingdom drive demand, supported by high consumer spending on premium kitchenware and a strong preference for high-quality cookware. The presence of well-established brands and a growing inclination toward home cooking and gourmet dining experiences further boost market growth. Additionally, Western European consumers are highly brand-conscious and prioritize durability, aesthetics, and sustainability when purchasing cookware, prompting manufacturers to introduce innovative, eco-friendly product offerings.
Southern Europe Benefiting from Culinary Traditions and Tourism
Southern Europe, comprising Italy, Spain, and Portugal, represents around 20% of the market, with strong demand influenced by deep-rooted culinary traditions. The region's rich food culture and emphasis on slow cooking techniques contribute to the popularity of enameled cookware, particularly cast iron options for dishes that require extended heat retention. The booming tourism and hospitality industry in countries like Italy and Spain also drive demand, as hotels, restaurants, and professional chefs seek high-performance cookware. Additionally, increasing consumer preference for visually appealing cookware that aligns with Mediterranean-style kitchen aesthetics supports market expansion in this region.
Eastern Europe Emerging as a High-Growth Market
Eastern Europe accounts for roughly 15% of the enameled cookware market, with countries such as Poland, Hungary, and the Czech Republic experiencing rising demand. The region's growing urbanization, increasing disposable incomes, and expanding middle class contribute to the adoption of premium kitchenware. While affordability remains a key factor influencing consumer choices, rising awareness about the benefits of enameled cookware is driving gradual market penetration. Furthermore, the rapid expansion of e-commerce and direct-to-consumer sales channels is making high-quality cookware more accessible in Eastern European markets, supporting future growth.
Northern Europe Emphasizing Sustainability and Premium Cookware
Northern Europe, including countries such as Sweden, Denmark, Norway, and Finland, holds approximately 20% of the market, with demand primarily driven by a strong sustainability focus. Consumers in this region prioritize eco-friendly and long-lasting kitchenware, making enameled cookware a preferred choice due to its durability and non-toxic properties. The market also benefits from the widespread popularity of minimalist kitchen designs, where stylish and functional cookware plays a key role. Additionally, the high purchasing power of Northern European consumers allows for greater investment in premium, high-performance cookware, further strengthening market demand.
Key Player Analysis:
- Staub
- Chasseur
- Denby Pottery Company Ltd.
- Emile Henry
- Samuel Groves
- Riess Kelomat
- De Buyer Industries
- BK Cookware
- Oigen Foundry Co. Ltd.
Competitive Analysis:
The Europe enameled cookware market is highly competitive, with key players focusing on product innovation, premium quality, and sustainability to strengthen their market position. Established brands such as Le Creuset, Staub, and Lodge dominate the premium segment, leveraging strong brand recognition, superior craftsmanship, and aesthetic appeal to attract high-end consumers. These companies continue to invest in expanding their product lines with new colors, designs, and advanced enamel coatings to maintain their competitive edge. Mid-range brands example, Chasseur and Denby Pottery Company Ltd. are strengthening their market presence by offering high-quality alternatives at competitive prices. Private-label brands and regional manufacturers are also expanding their presence, particularly in price-sensitive markets. The growing influence of e-commerce has intensified competition, enabling direct-to-consumer sales and increasing brand accessibility. To remain competitive, companies are focusing on sustainability, enhancing distribution networks, and leveraging digital marketing strategies to engage consumers and expand their customer base across Europe.
Recent Developments:
- Le Creusethas launched a new cookware collection called the Gourmand Collection. This collection, announced in early March 2025, features single-serve versions of popular cast iron cookware pieces like cocottes, braisers, and skillets. The collection is designed for solo meal preparation and intimate dinner gatherings, offering a stylish and practical solution for modern cooking needs.
- In October 2024, Denby Pottery partnered with ESW to overcome post-Brexit challenges and launched direct-to-consumer ecommerce capabilities in 29 European markets. This partnership aimed to improve customer experience by displaying pricing, including duties and taxes, in local currencies, thus eliminating surprise charges at checkout or delivery.
- In January 2025, Groupe SEB acquired La Brigade de Buyer, which includes the de Buyer brand, known for its premium cookware. This acquisition strengthens Groupe SEB's position in the professional and premium segments, though it does not directly involve the German market.
Market Concentration & Characteristics:
The Europe enameled cookware market exhibits a moderate to high level of market concentration, with a few established brands holding a significant share. Premium players such as Le Creuset, Staub, and Lodge dominate the market, leveraging strong brand recognition, superior craftsmanship, and extensive distribution networks. These brands maintain a competitive advantage by offering high-quality, durable products with innovative designs and premium aesthetics, catering to consumers willing to invest in long-lasting cookware. The market is characterized by a growing preference for sustainable and high-performance cookware, with increasing demand for enameled cast iron and steel variants. Consumers seek cookware that combines functionality with visual appeal, driving manufacturers to expand their product portfolios with diverse colors and finishes. Additionally, digital transformation and the rise of e-commerce have reshaped market dynamics, making premium enameled cookware more accessible while intensifying competition among established and emerging brands.
Report Coverage:
The research report offers an in-depth analysis based on type, material, end-user, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Europe enameled cookware market is expected to witness steady growth, driven by increasing consumer preference for durable and aesthetically appealing cookware.
- Rising health consciousness and demand for non-toxic, non-reactive cookware will boost market expansion.
- Sustainability trends will encourage manufacturers to adopt eco-friendly materials and production processes to align with consumer preferences.
- The premium segment will continue to dominate, with high-end brands focusing on innovation, design variety, and enhanced performance features.
- Digital transformation and the growth of e-commerce will expand market accessibility, enabling direct-to-consumer sales and increased brand competition.
- Increasing urbanization and rising disposable incomes in Eastern Europe will present new opportunities for market penetration.
- Technological advancements in enamel coating and heat retention capabilities will enhance product longevity and performance.
- The rise of home cooking culture and social media influence will fuel consumer interest in high-quality, visually appealing cookware.
- Fluctuating raw material costs and supply chain disruptions may pose challenges, prompting manufacturers to optimize sourcing strategies.
- Expanding retail channels, including specialty kitchenware stores and online marketplaces, will drive market growth and competitive differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumer Preference for Premium and Durable Cookware
European consumers are prioritizing high-quality, long-lasting cookware that offers both functional and aesthetic benefits. Enameled cookware’s superior heat retention, resistance to rust, and vibrant design options make it a preferred choice for modern kitchens.
Rising Health Consciousness and Shift Towards Home Cooking
Health-aware consumers are seeking non-toxic, non-reactive cookware, driving demand for enameled products that do not leach chemicals. The trend toward home cooking and gourmet meal preparation further boosts adoption among both home cooks and professionals.
Growth of Sustainable and Eco-Friendly Kitchenware Trends
Sustainability is a key purchasing factor, with enameled cookware’s durability and recyclable materials aligning with eco-conscious values. Manufacturers are innovating with non-toxic coatings and sustainable production to meet this demand.
Expansion of Online Retail and Digital Influence
The rise of e-commerce and digital marketing has made enameled cookware more accessible, allowing consumers to compare products, read reviews, and purchase directly from brands. Social media and influencer marketing are also increasing product awareness and driving sales.
Technological Advancements and Product Innovation
Advances in enamel coating technology and the introduction of multi-functional, visually appealing cookware are attracting consumers seeking both performance and style. Features like improved heat distribution and enhanced durability are differentiating products in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Enameled Cookware Market?
What factors are driving the growth of the Europe Enameled Cookware Market?
What are the key segments within the Europe Enameled Cookware Market?
What are some challenges faced by the Europe Enameled Cookware Market?
Who are the major players in the Europe Enameled Cookware Market?
Which segment is leading the Europe Enameled Cookware Market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Pots
- 1.2.2 Pans
- 1.2.3 Dutch Ovens
- 1.2.4 Baking Dishes
- 1.2.5 Others
- 1.3 By End-User
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.4 By Material
- 1.4.1 Cast Iron
- 1.4.2 Steel
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 289.7 million → 2032: USD 469.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Enameled Cookware Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Enameled Cookware Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Enameled Cookware Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Enameled Cookware Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Enameled Cookware Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Enameled Cookware Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Enameled Cookware Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Enameled Cookware Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 289.7 million → 2032: USD 469.25 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Enameled Cookware Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pots
- 12.3.7.2 Pans
- 12.3.7.3 Dutch Ovens
- 12.3.7.4 Baking Dishes
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cast Iron
- 12.5.7.2 Steel
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Enameled Cookware End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Enameled Cookware Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Enameled Cookware Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Enameled Cookware Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Le Creuset
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Staub
- 18.4 Chasseur
- 18.5 Denby Pottery Company Ltd.
- 18.6 Emile Henry
- 18.7 Samuel Groves
- 18.8 Riess Kelomat
- 18.9 De Buyer Industries
- 18.10 BK Cookware
- 18.11 Oigen Foundry Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

