
Aging fleets keep replacement sales ahead of new fitment
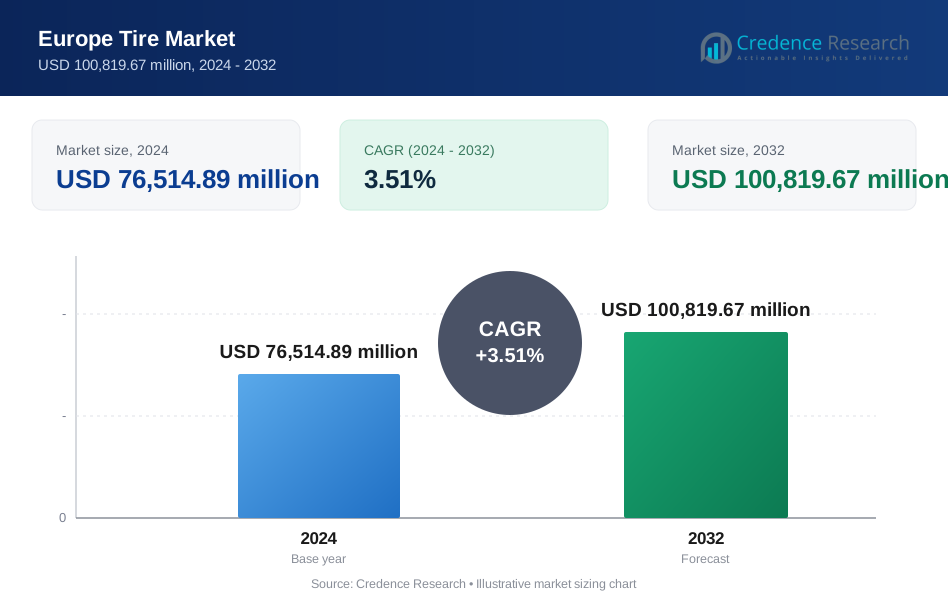
The Europe tire market was valued at USD 79.20 billion in 2025 and is projected to increase from USD 81.98 billion in 2026 to USD 111.83 billion by 2035, registering a CAGR of 3.51% during 2026–2035. Demand rests on a car fleet averaging 12.7 years of age, seasonal fitment rules in the Alpine and Nordic countries and electric models that need dedicated fitments. Germany held the largest single share, 22.0% in 2025, helped by a replacement trade the BRV trade association put at about 46.6 million units that year. Central and Eastern Europe is the fastest-growing area at 4.3% a year, as new plants in Romania and Hungary bring capacity closer to buyers. Definitive EU anti-dumping duties of 4.3% to 45.3% on Chinese car and light truck tires took effect in July 2026, changing how importers and dealers source their entry-level ranges across the region.
What does the Europe tire market cover and who buys?
The market counts new car, light truck, truck and bus, motorcycle and special vehicle tires sold in Europe, both as original equipment to vehicle makers and as replacements to motorists, fleets and farms. Most motorists buy through specialist dealers and workshops, while fleets usually buy on service contracts that bundle fitting, inspection and casing management.
The scope excludes retreading services, wheels and rims, tire recycling and raw materials such as natural and synthetic rubber. The value chain runs from compounders and tire plants through importers and wholesalers to dealers, online retailers and fitting partners, with vehicle makers buying directly from plants under multi-year fitment programs.
Europe Tire Market Insights
- The Europe tire market grows from USD 79.20 billion in 2025 to USD 111.83 billion by 2035, a 3.51% CAGR over 2026–2035, with replacement sales carrying most of the added value.
- Germany held 22.0% of 2025 value, the largest national share, while Central and Eastern Europe grows fastest at 4.3% a year on new regional plants.
- Replacement demand accounted for 78.0% of 2025 value, since the average EU car was 12.7 years old in 2024 according to ACEA data.
- Definitive EU duties of 4.3% to 45.3% took effect in July 2026 on Chinese car and light truck units, which held 28% of EU volume in 2024.
- Michelin, Goodyear and Apollo Tyres have closed or planned to close older sites since 2024, while Nokian Tyres, Hankook and Bridgestone invest in Romania, Hungary and Spain.
Replacement and truck demand shape the segment mix
Why do passenger car tires lead while truck and bus fitments grow fastest?
Based on vehicle type, the market is categorized into passenger car, light truck, truck and bus, motorcycle and special vehicle tires. Passenger Car Tires led with 62.0% of 2025 value because ACEA counted about 256 million cars on EU roads in 2024. Truck and Bus Tires grow fastest at 4.0% a year, as Continental expects 2026 replacement demand for medium and heavy vehicles to rise 1% to 3% and Hankook is adding 800,000 units of annual truck capacity in Hungary. Motorcycle demand is smaller, with ACEM counting 1,002,848 registrations in five key markets in 2025, while Yokohama bought a closed Romanian site in May 2025 for machinery fitments.
How far does replacement demand outweigh original equipment?
Based on demand, the market is categorized into OEM and replacement sales. Replacement led with 78.0% of 2025 value because Tyres Europe members alone sold 58.144 million consumer units in the first quarter of 2026, up from 57.499 million a year earlier. Replacement is also the faster side at 3.6% a year, as the average EU car reached 12.7 years in 2024 according to ACEA and each older car keeps returning to the trade for new sets. Original equipment stays weaker, since Continental forecast another decline in European light vehicle production for 2026, which limits new fitment volume for plants serving German, French and Spanish assembly lines.
Why is radial construction the default across European fleets?
Based on type of tires, the market is categorized into radial and bias construction. Radial led with 93.0% of 2025 value because European car, van and truck programs are built around it, including the 800,000-unit truck and bus radial line Hankook began building at Rácalmás in February 2025. Radial also grows fastest at 3.6% a year, as farm suppliers push it for larger machines, with Prometeon, Mitas and Maxam all showing VF casing ranges at Agritechnica in Hanover in November 2025, according to TyreNews. Bias remains in smaller farm, industrial and off-road sizes, which Credence Research treats as a slowly shrinking niche.
How do dealers and online retailers split European tire sales?
Based on distribution channel, the market is categorized into dealer and exclusive outlets, online and others. Dealer/Exclusive Outlets led with 74.0% of 2025 value because fitting remains a workshop job, and the BRV put specialist retailers and independent workshops at 71.3% of the German replacement trade in 2024. Online sales grow fastest at 4.4% a year from a small base, as Delticom now pairs 335 online shops with about 25,000 partner garages that mount orders. Others, chiefly carmaker dealerships and home improvement stores, keep a steady role, though the BRV found that dealerships held nearly 20% of German sales that year.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Vehicle Type | Passenger Car Tires | 62.0% | Truck and Bus Tires | 4.0% |
| By Demand | Replacement | 78.0% | Replacement | 3.6% |
| By Type of Tires | Radial | 93.0% | Radial | 3.6% |
| By Distribution Channel | Dealer/Exclusive Outlets | 74.0% | Online | 4.4% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fleet age and winter rules underpin European tire demand
An older car fleet keeps replacement volume steady
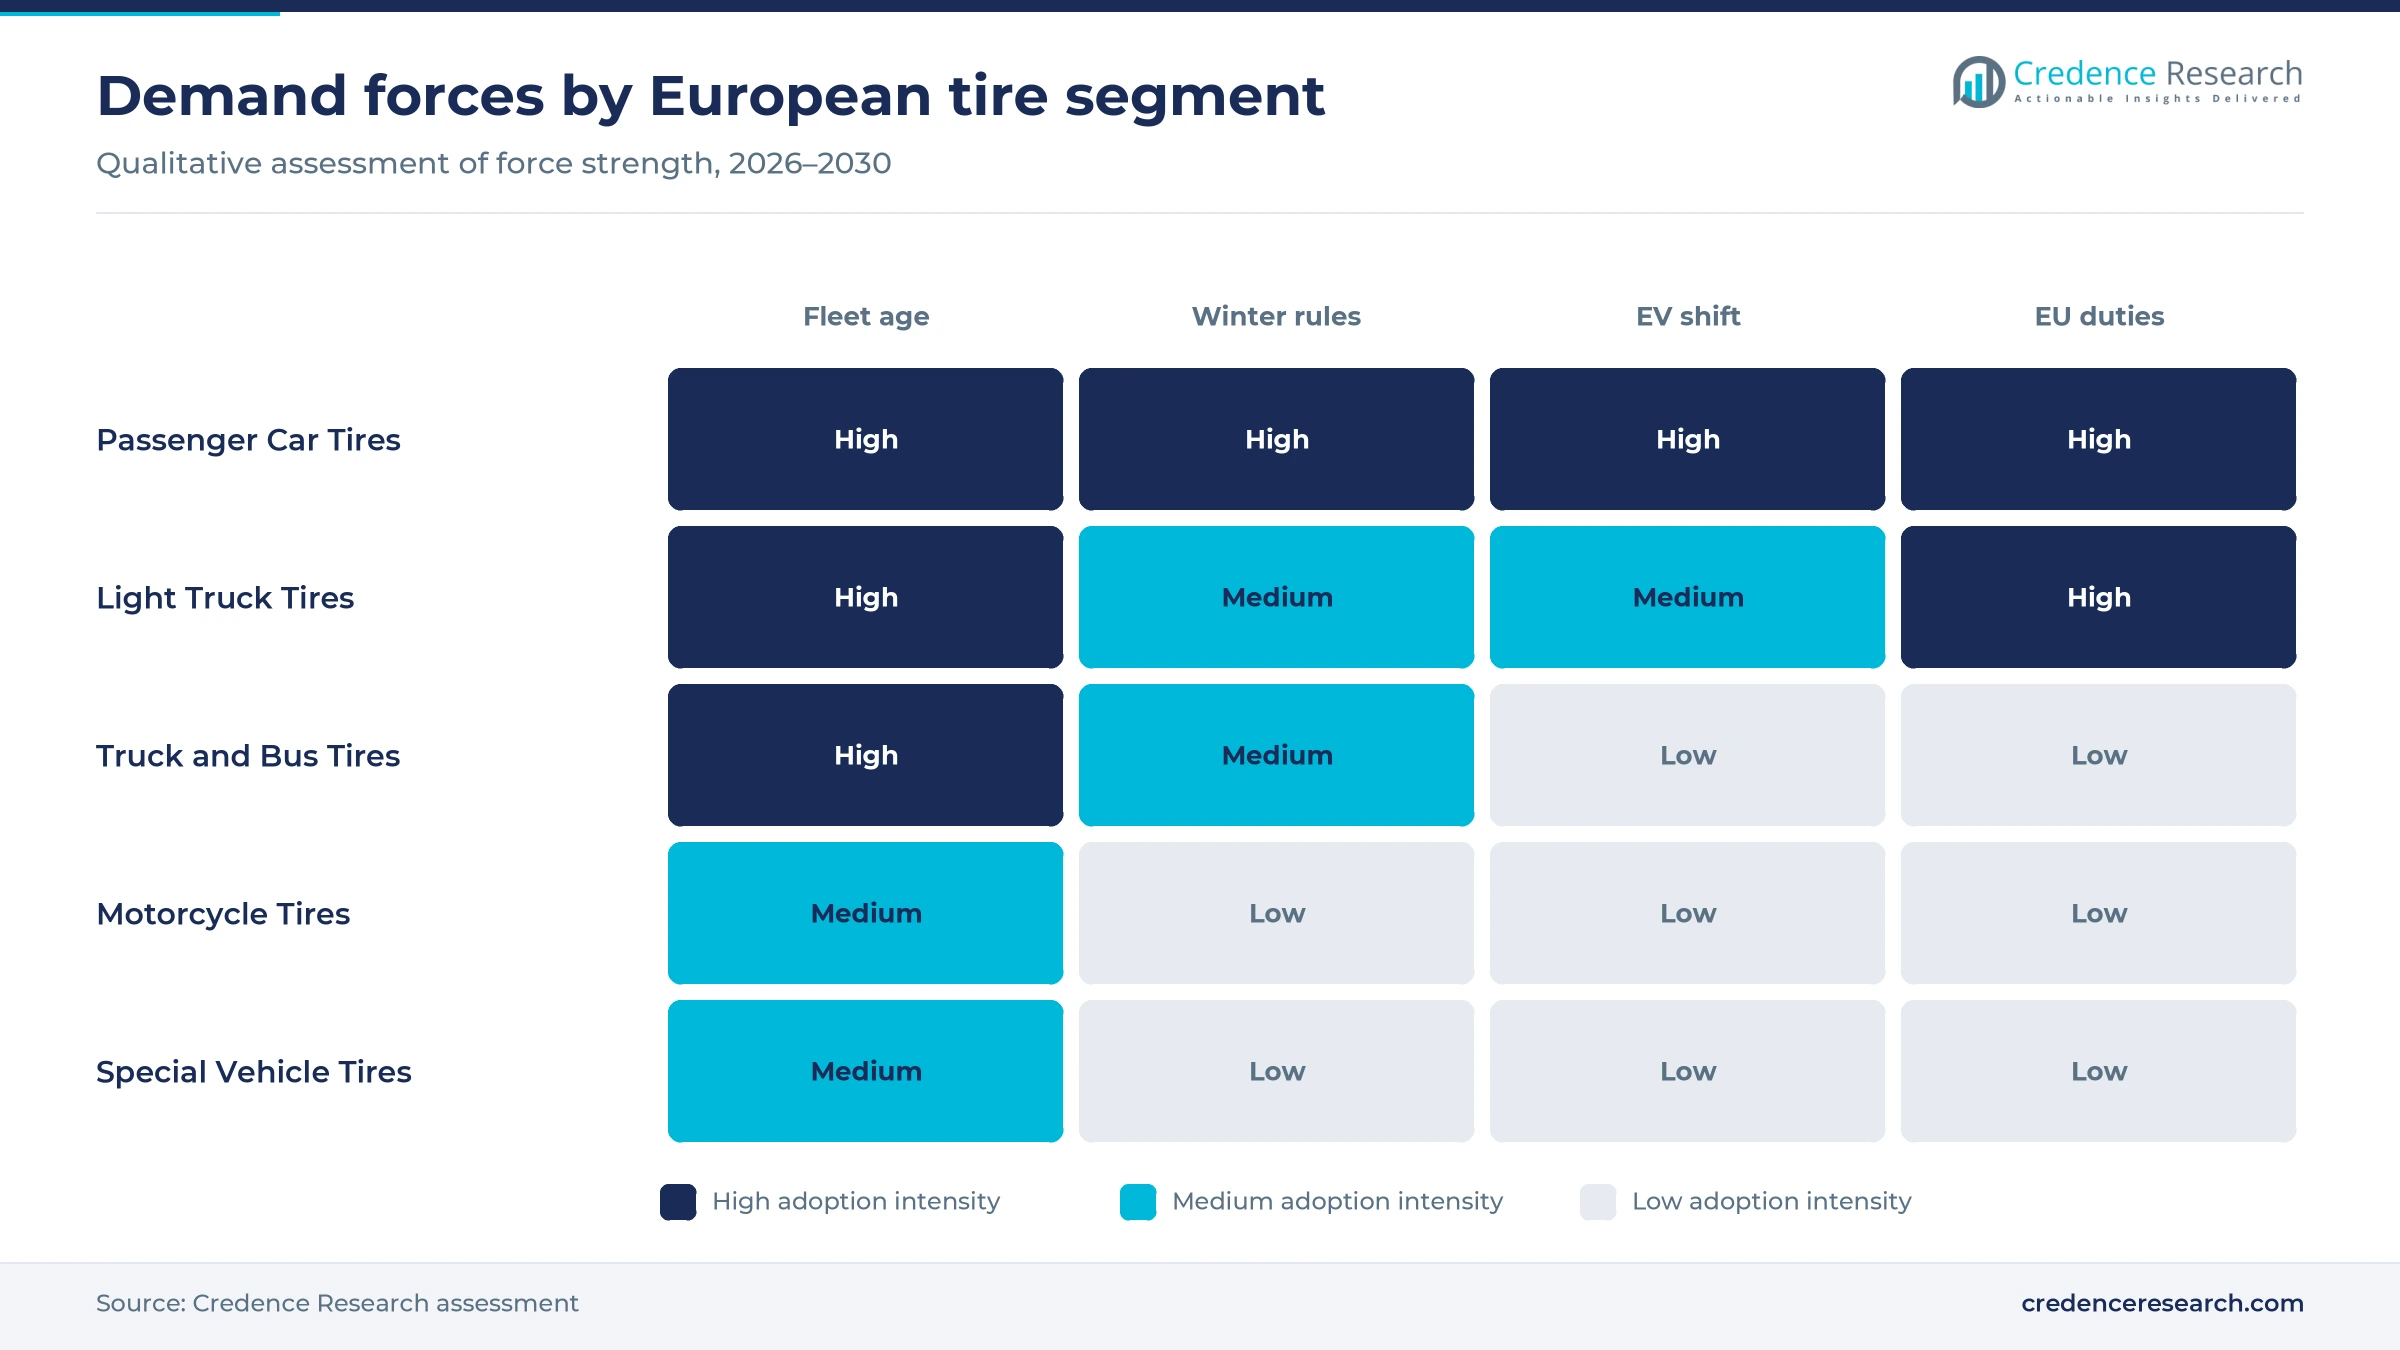
Older cars are the most dependable source of European demand because owners keep replacing worn sets long after the first fitment. ACEA reported in its January 2026 Vehicles on European Roads study that the EU had about 256 million cars in 2024, with an average age of 12.7 years. As a result, Tyres Europe members still sold 58.144 million consumer units in the first quarter of 2026, even after a soft 2025. The same pattern appears in Britain, where SMMT counted a record 36.68 million cars in use in 2025 with an average age of 9.7 years. This supports the 78.0% share of replacement sales, and it gives dealers a base that does not depend on new registrations.
Tighter winter rules push motorists toward certified fitments
National winter rules create a second buying cycle that summer-only markets do not have. Germany stopped accepting older M+S-only all-weather products in winter conditions from Oct. 1, 2024, according to the European Consumer Centre network, so owners of those sets must now buy units with the Alpine symbol. Finland has required the same 3PMSF symbol on studless winter products since Dec. 1, 2024, and a Danish law of July 2025 made snowflake-marked winter or all-season fitments compulsory in winter conditions. Austria also requires winter equipment from Nov. 1 to April 15 when roads call for it. These rules matter to buyers because a fine or an insurance dispute now attaches directly to the marking on the sidewall.
Electrified car sales raise specification and price per set
Electrified cars lift value per set because their weight, torque and range targets call for dedicated low-resistance products. According to ACEA, battery-electric cars took 17.4% of 2025 EU registrations, up from 13.6% in 2024, and hybrids took another 34.5%. The installed base is following, since SMMT counted 1.8 million battery-electric cars on British roads in 2025, up 34.7% in a year. Michelin markets this shift directly, claiming up to 60 kilometers of added range for its Pilot Sport EV and up to 32 kilometers for its e.Primacy All-Season, according to TyreNews in April 2025. Pirelli also said that about 65% of its 116 new homologations worldwide in the first quarter of 2026 were for electric models, and about 90% suited 19-inch or larger wheel assemblies, according to Modern Tire Dealer.
Commercial fleets keep truck and bus demand above car growth
Truck and bus operators replace on mileage rather than season, which makes this demand steadier and supports the 4.0% growth of the segment. ACEA counted about 6.16 million trucks on EU roads in 2024 with an average age of 14 years, and new bus registrations rose 7.5% to 38,238 in 2025. Germany shows the effect, because the BRV reported truck unit sales of about 2.52 million in 2025, up 2.4%, including retreaded casings at a 24.5% share. Suppliers are responding with capacity, as Continental plans to lift its Puchov site in Slovakia from about 2.6 million to more than 3 million units a year.
All-season growth and trade duties reset the supply map
Shift from summer sets to all-season fitments gathers pace
Motorists are moving away from two seasonal sets, and this is the clearest mix change in European car sales. Tyres Europe reported that summer car fitments fell 7% and winter fitments fell 4% in 2025, and overall consumer sales fell 2%, according to TyreNews in February 2026. Delticom reported in November 2025 that all-season sales rose about 5% across Europe in the first nine months of the year, and 6.6% in Germany. The BRV had already put the all-season share of the German trade at 36% in 2024, up from 33%. For suppliers, this reduces twice-yearly changeover revenue, and for that reason Giti gave its GT Radial ClimateActive all-season range 3PMSF approval.
Rise of EU trade defense reshapes entry-level sourcing
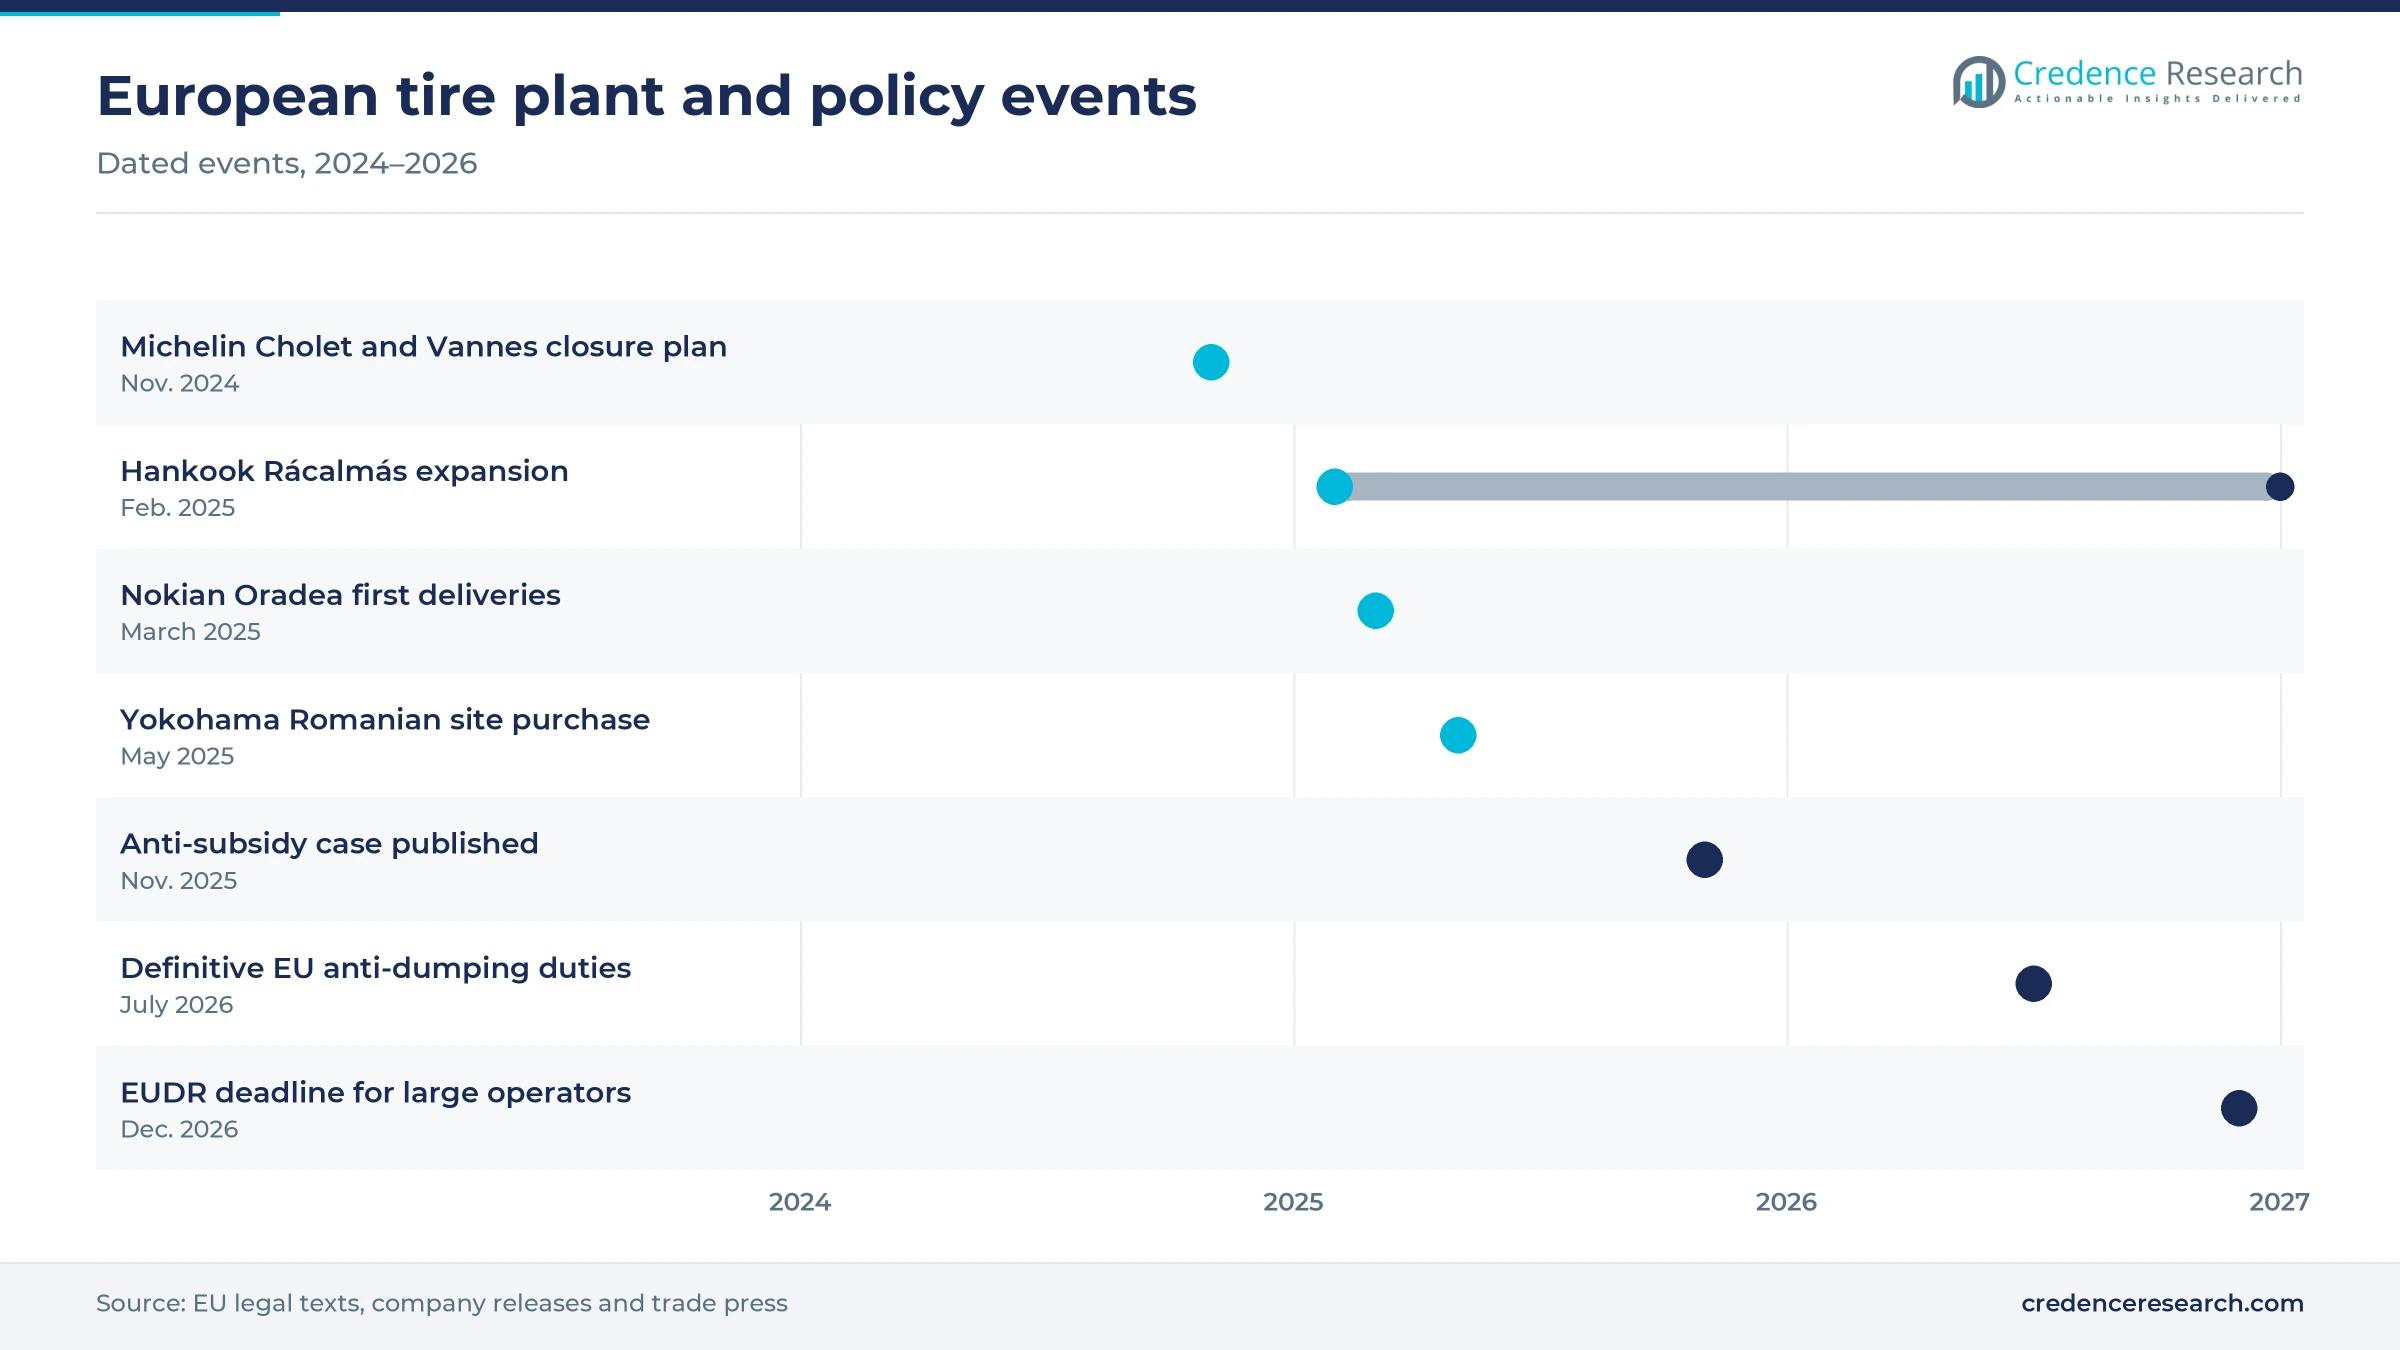
Trade policy is now redrawing the entry-level price tier, which had been supplied largely from China. Eunews reported in July 2026 that Chinese imports reached nearly 93 million units in 2024, about 28% of EU tire consumption of roughly 330 million units. In response, Commission Implementing Regulation (EU) 2026/1540 imposed definitive anti-dumping duties of 4.3% to 45.3%, effective July 8, 2026, for five years and without retroactive collection. A separate anti-subsidy case was published in the Official Journal on Nov. 6, 2025, and TyreNews noted that it can run up to 13 months. Importers are therefore comparing supplier-specific duty rates, and dealers can expect entry-level ranges and prices to change through 2027.
Opportunity in premium high-rim and regional capacity
Plants built for larger premium sizes offer the clearest opening, because premium fitments carry more margin than volume ranges now exposed to imports. Bridgestone is investing up to EUR 207 million in Burgos, Spain, through 2030 to lift capacity for 18-inch-and-above units by 75%, to more than 7 million a year, according to HGV Traders. Nokian Tyres spent EUR 650 million on its Oradea plant in Romania, which produced its one-millionth unit on Dec. 20, 2025, and plans a capacity of 6 million units by about 2027. Hankook is also spending EUR 540 million at Rácalmás, Hungary. As a result, suppliers of styrene-butadiene rubber, molds and logistics can follow new demand into Central and Eastern Europe.
Opportunity in low-abrasion and recycled-content products
Abrasion and circularity rules open room for products that can prove lower emissions, and this should reward early movers. Under Euro 7, type approval for passenger car fitments starts July 1, 2028, with sales of noncompliant stock allowed until June 30, 2032, and later dates apply to van and truck sizes. The pressure is real, because Pew and three partner groups wrote in November 2025 that tire wear releases an estimated 360,000 to 540,000 metric tons of microplastics a year. Continental showed one response in August 2026, a concept product with about 43% recycled material built within the EU ZEvRA project, according to Electrive. Fleet buyers can use such data in procurement, which gives low-wear ranges a commercial case before the limits apply.
Plant costs and weak vehicle output squeeze European makers
High energy and labor costs close older plants
Production costs are forcing closures at long-established European sites in several countries. Michelin said in November 2024 that it would close Cholet and Vannes in France by early 2026, affecting about 1,250 jobs, and it cited inflation and energy prices, according to RTE. Goodyear closed Fulda in Germany, and Brussels Signal counted 1,171 job losses across its German cuts in July 2025. Apollo Tyres also said in April 2025 that it planned to shut Enschede by summer 2026. Producers respond by moving volume east and automating remaining premium lines.
Falling commercial vehicle sales reduce original equipment orders
New vehicle demand no longer supports plant loading in the way it once did. ACEA recorded EU truck registrations down 6.2% to 307,460 in 2025, with Germany down 12.2%, while van registrations fell 8.8%. Continental also put 2025 European light vehicle production down 1% to 3%, and it expected a similar decline in 2026. This affects original equipment plants most, since fitment contracts follow assembly schedules. Suppliers answer by shifting lines to replacement ranges and larger sizes, though that shift takes several years.
Deforestation rules add traceability costs for natural rubber
Rubber sourcing rules add compliance work for every producer selling into the EU. Mongabay reported in May 2026 that large and medium operators must meet the deforestation regulation by Dec. 30, 2026, after two delays. Tire makers consume about 70% of natural rubber, and smallholders grow roughly 85% of it, so tracing supply back to plots is slow work. Michelin alone mapped about 2 million land plots for this purpose. Smaller operators get six more months, although they still depend on supplier declarations to comply.
Mild winters make seasonal demand harder to plan
Seasonal volatility makes stock planning difficult for dealers and wholesalers. Tyres Europe reported that winter fitments fell 14% in the fourth quarter of 2025, a drop far larger than the 4% decline for the full year. Delticom also said in November 2025 that snowfall at lower altitudes had been missing in many places early in that quarter. As a result, dealers risk carrying unsold stock into the new year, which encourages later orders and wider all-season ranges to reduce that exposure.
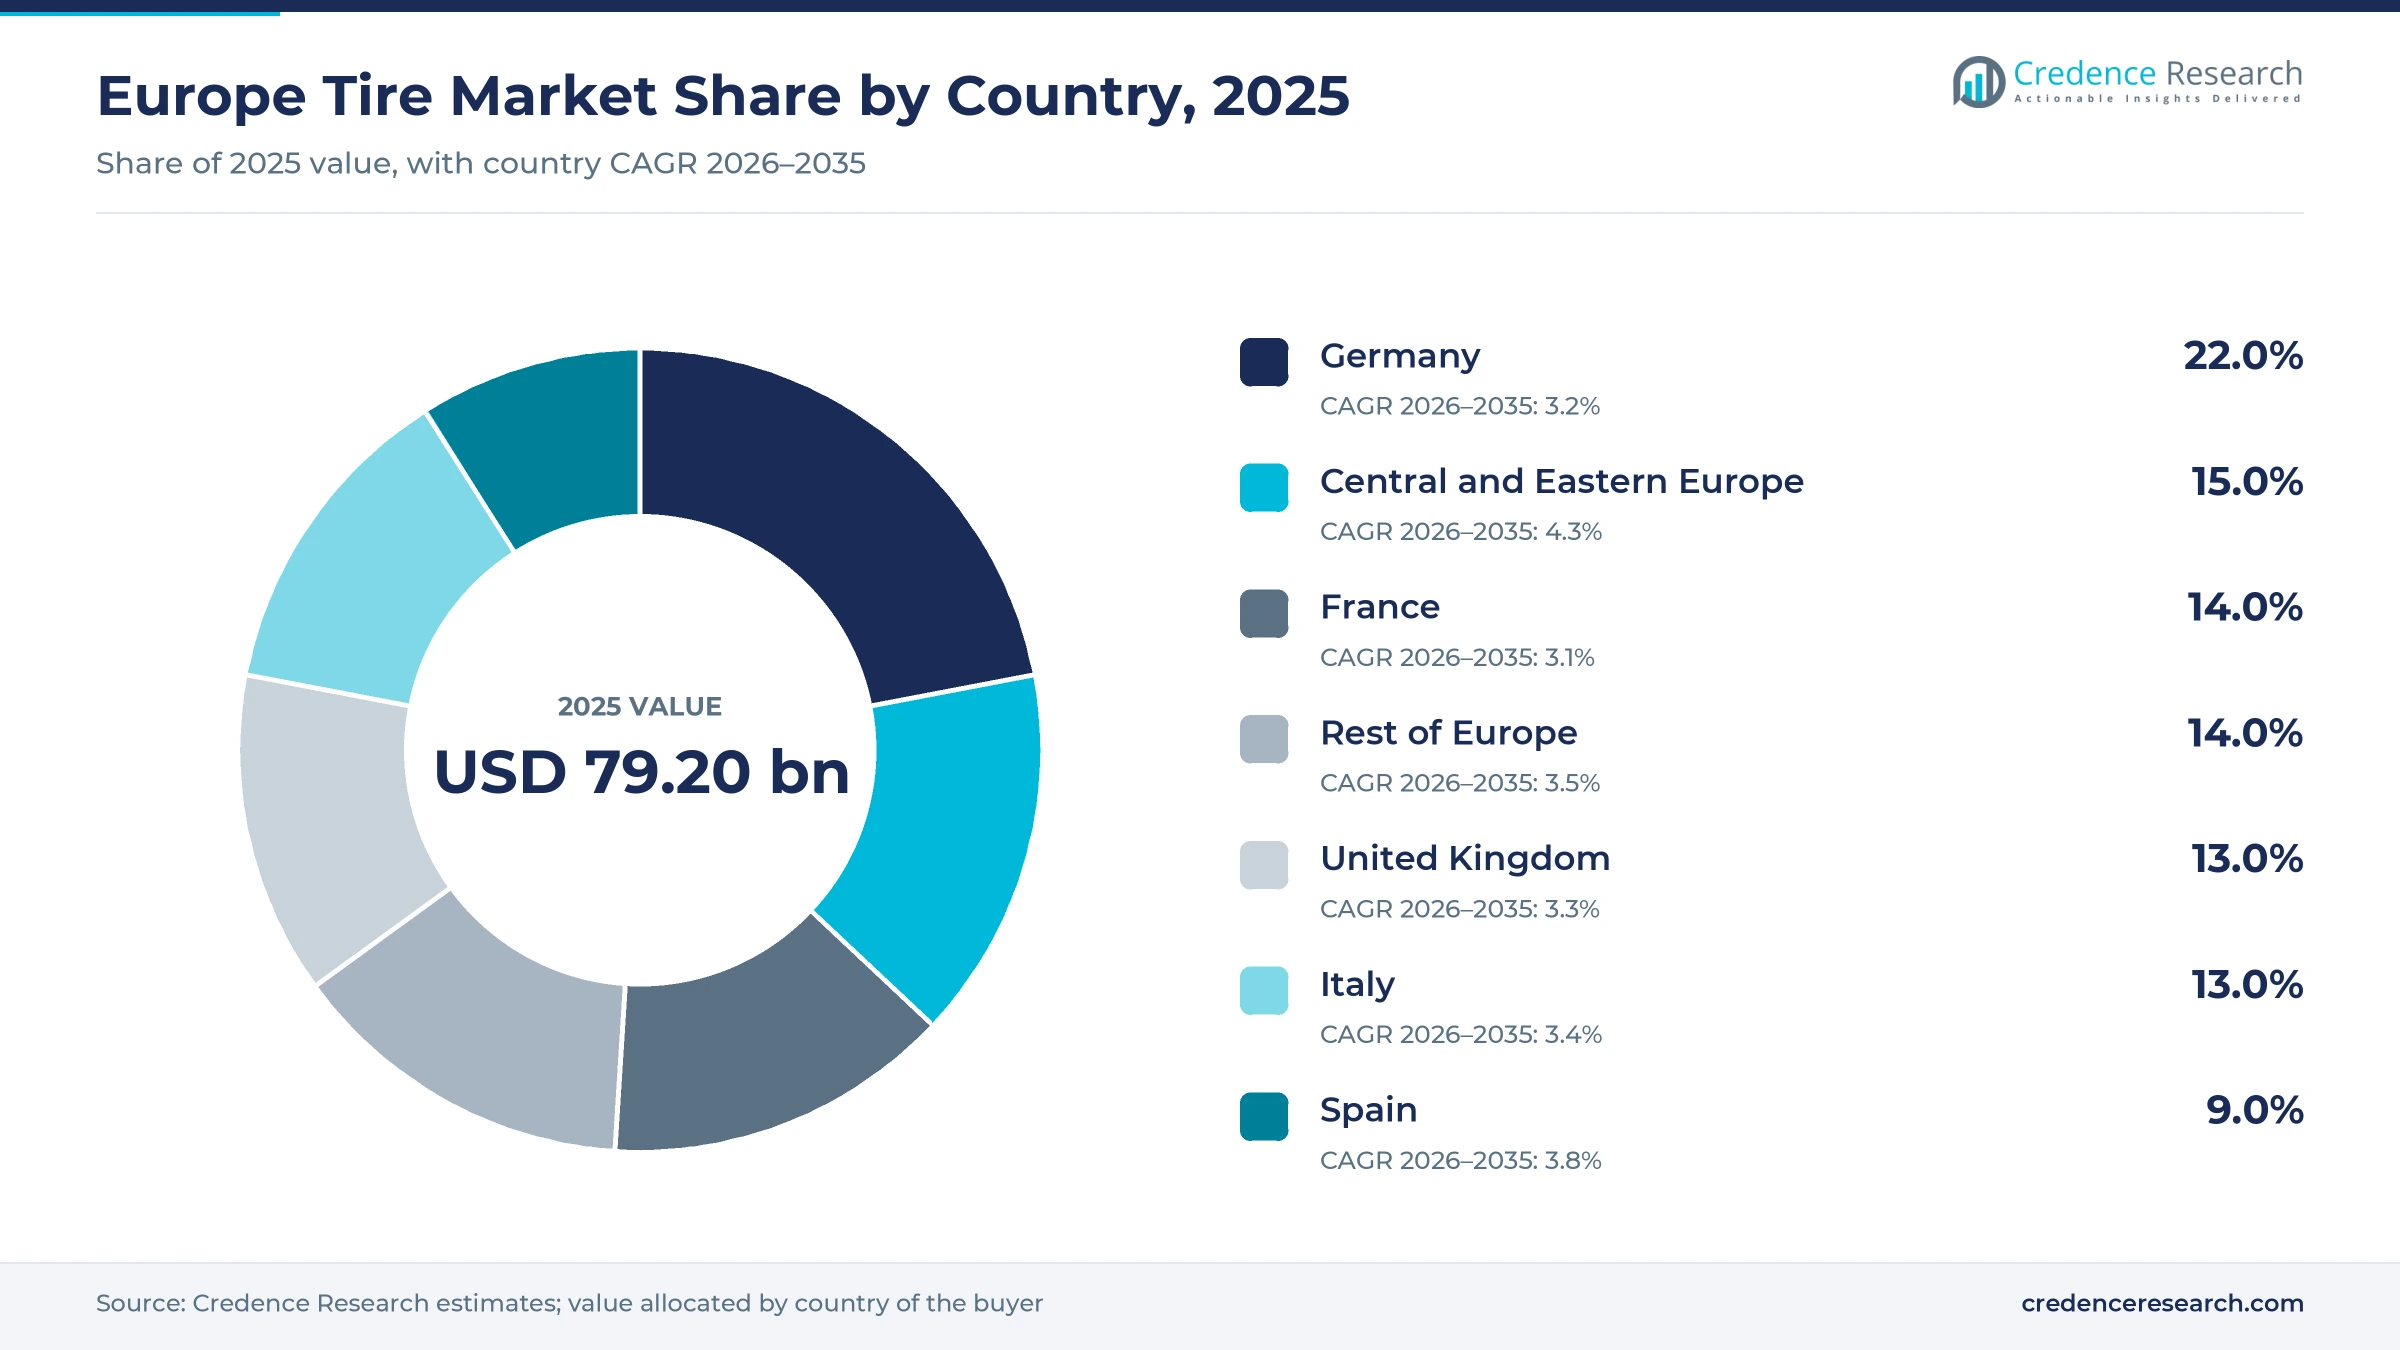
Germany leads while Central and Eastern Europe grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Germany | 17.42 | 22.0% | 3.2% |
| Central and Eastern Europe | 11.88 | 15.0% | 4.3% |
| France | 11.09 | 14.0% | 3.1% |
| Rest of Europe | 11.09 | 14.0% | 3.5% |
| United Kingdom | 10.30 | 13.0% | 3.3% |
| Italy | 10.30 | 13.0% | 3.4% |
| Spain | 7.13 | 9.0% | 3.8% |
Germany anchors premium and winter demand
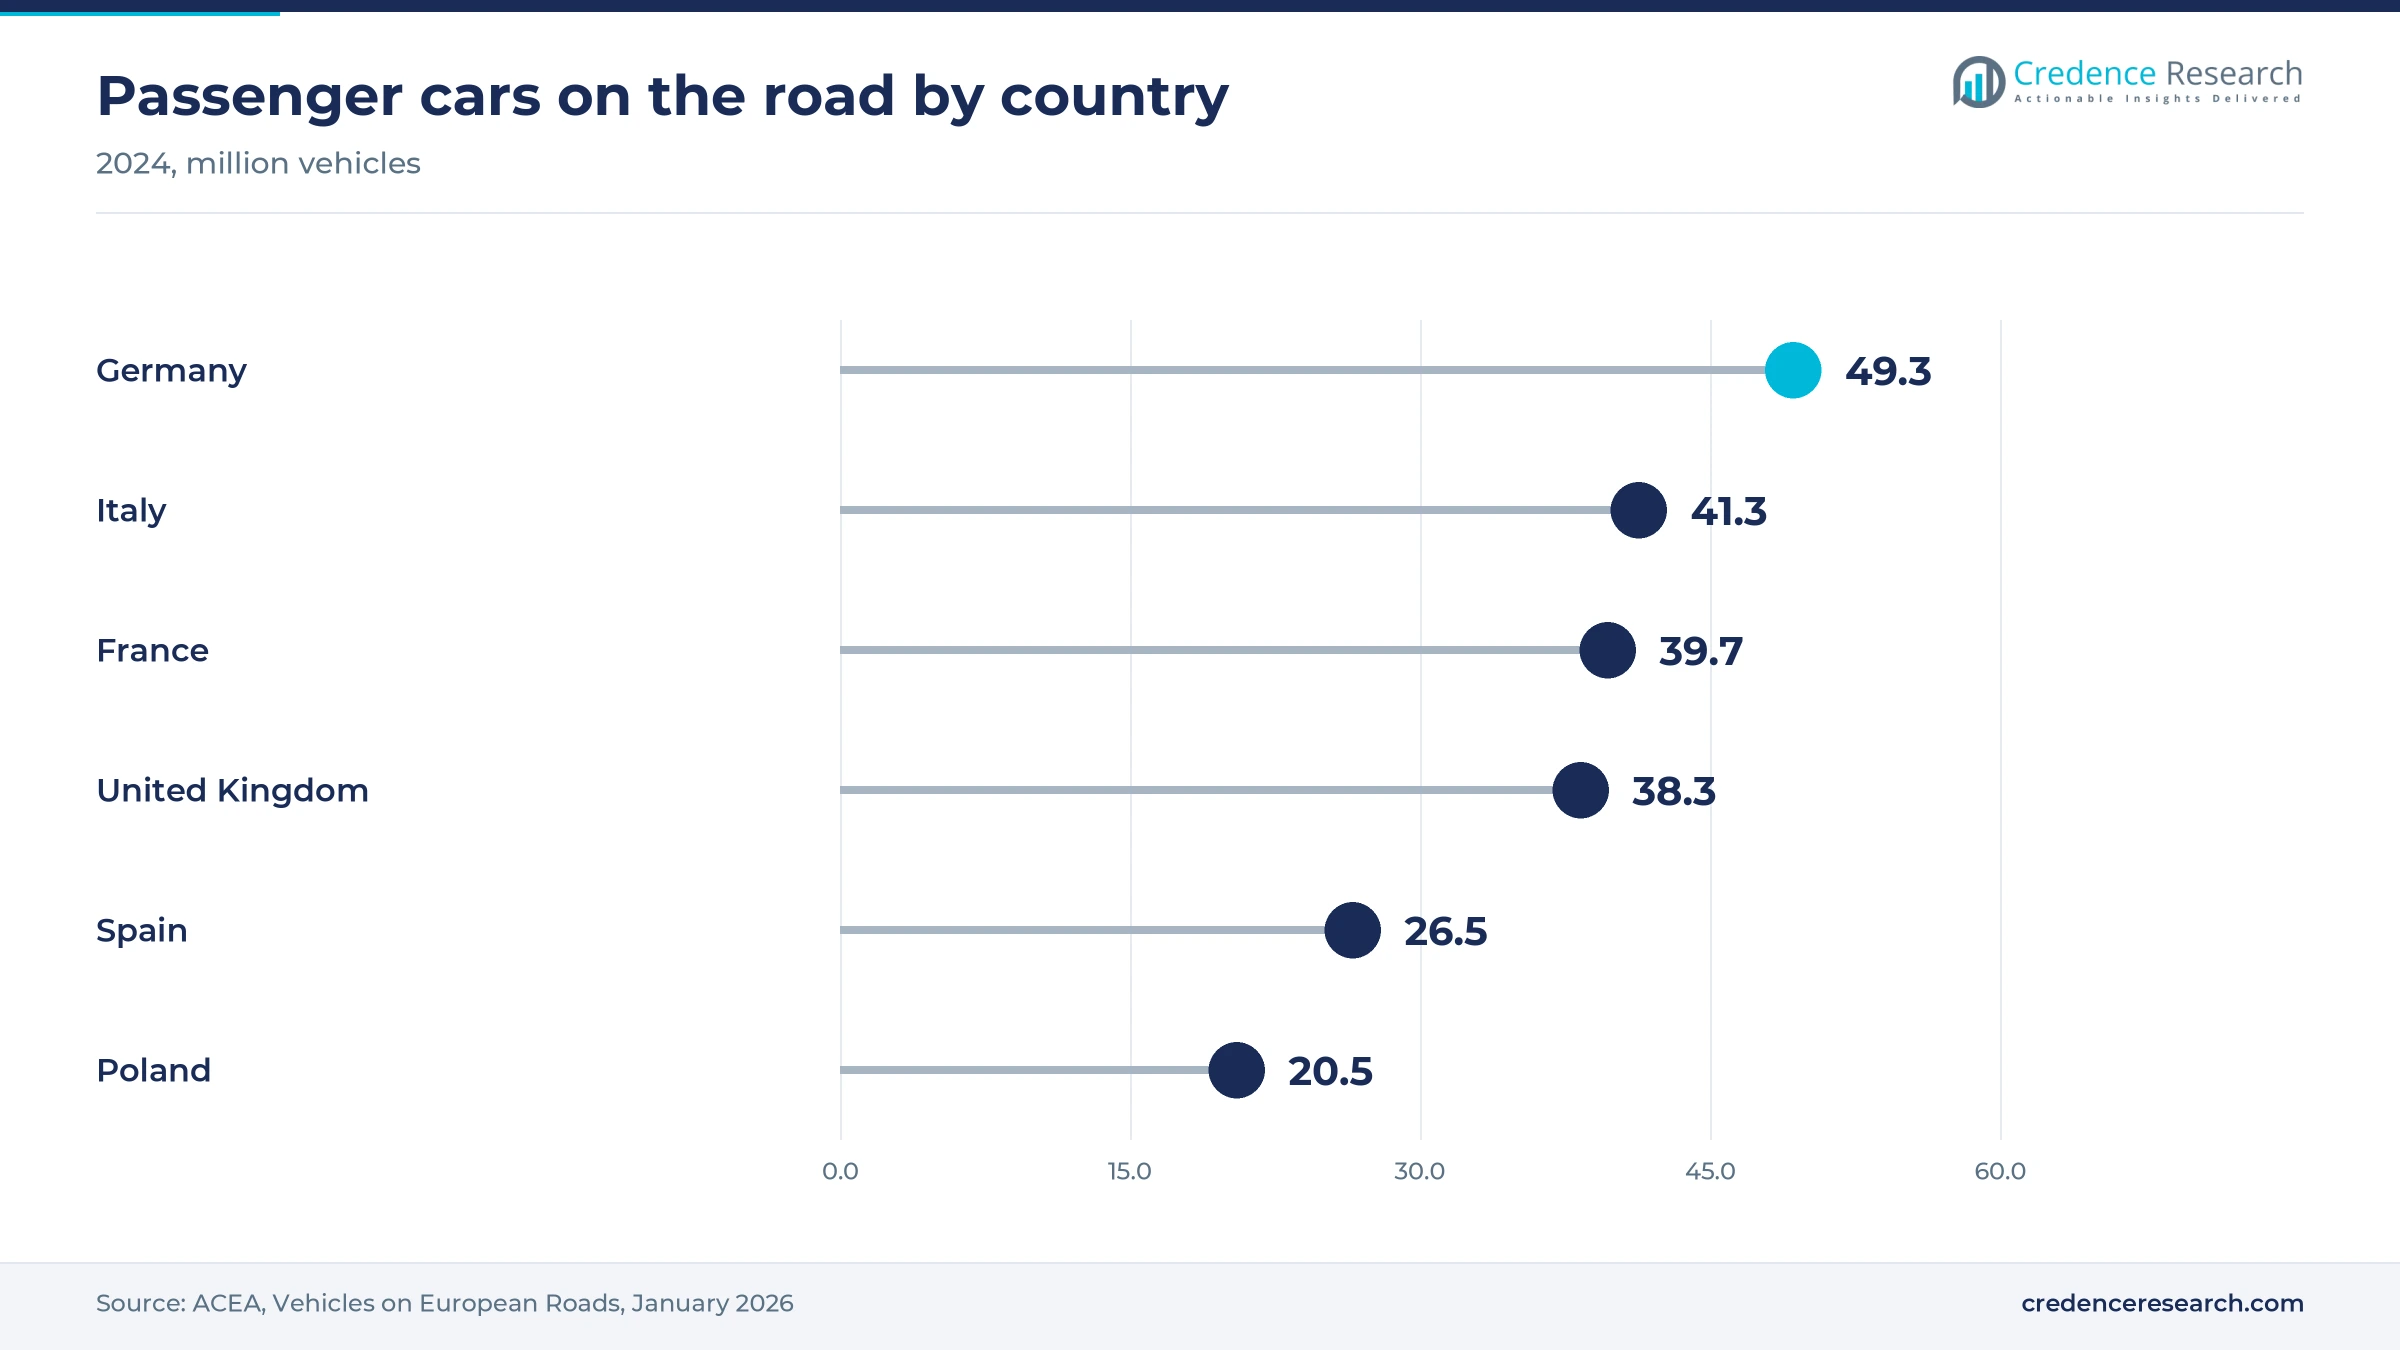
Germany held 22.0% of 2025 value and grows at 3.2% a year, the largest national share in the Europe tire market. ACEA counted 49.3 million cars there in 2024, the most in the EU, and the BRV put total unit sales at about 46.6 million in 2025, down 1.9%. Situational winter rules keep seasonal buying in place for many German motorists. However, the BRV expects consumer volume to fall 2.2% in 2026, with all-season growth only partly offsetting lower seasonal sales.
France balances mountain rules and plant closures
France held 14.0% of 2025 value and grows at 3.1% a year, the slowest pace among the large markets in this report. ACEA counted 39.7 million cars in 2024, while mountain rules apply from Nov. 1 to March 31 in signed zones, and only 3PMSF fitments have counted as equivalent to chains since Nov. 1, 2024. This supports all-season demand across the 34 departments covered by the rule. Even so, the Cholet and Vannes closures reduced local van tire output, so more of this demand is now served from other plants.
The United Kingdom relies on a large aging car parc
The United Kingdom held 13.0% of 2025 value and grows at 3.3% a year, and it sits outside the EU customs territory where the new duties apply. SMMT counted a record 42.5 million vehicles in use in 2025, which gives dealers a wide replacement base, and battery-electric cars made up almost 5% of the car parc. British importers also watch trade remedies closely, since TyreNews expects EU measures on Chinese supply to affect U.K. sourcing.
Italy pairs a dense car fleet with scooter demand
Italy held 13.0% of 2025 value and grows at 3.4% a year, supported by one of the largest car fleets in the region. ACEA counted 41.3 million cars in 2024, and ACEM recorded 331,634 motorcycle registrations in 2025, the highest of its five key markets, although down 6%. That base gives Italy a larger share of two-wheeler fitments than its neighbors. Winter equipment is compulsory only where signs require it, generally from Nov. 15 to April 15.
Spain gains from Burgos and van demand
Spain held 9.0% of 2025 value and grows at 3.8% a year, helped by both vehicle demand and local production. ACEA recorded van registrations up 11.7% in 2025, against an 8.8% EU decline, and ACEM counted 242,580 motorcycle registrations, up 8.3%. Bridgestone is also turning Burgos into one of its largest European van sites, which shortens supply for Iberian fleets. In addition, ACEA counted 26.5 million cars on Spanish roads in 2024, which gives replacement sales a growing base.
Central and Eastern Europe gains new capacity
Central and Eastern Europe held 15.0% of 2025 value and grows fastest at 4.3% a year. Poland has 20.5 million cars and 841,545 trucks according to ACEA, and its truck count rose from 741,097 in 2020, which reflects its role in European haulage. New capacity follows this demand, with Oradea, Rácalmás, Puchov and Yokohama at Drobeta-Turnu Severin all located here. Bus registrations in Poland also rose 16.6% in 2025, which adds fleet demand.
The Nordics, Belgium and Alpine countries set seasonal norms
The rest of Europe held 14.0% of 2025 value and grows at 3.5% a year, with demand shaped by climate rules. Sweden requires winter equipment from Dec. 1 to March 31, with a 3-millimeter tread minimum, while Austria sets a 4-millimeter minimum for radial units. Belgium has no winter mandate, though Denmark introduced one in July 2025, so neighboring markets now differ widely. Nokian Tyres keeps its winter and studded development in Finland, which serves this high-value seasonal demand.
EU duties and new Romanian plants mark 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In July 2026, the European Commission imposed definitive anti-dumping duties of 4.3% to 45.3% on Chinese car and light truck tires. | In force from July 8, 2026, for five years; a separate anti-subsidy case continues. |
| In August 2026, Continental unveiled a concept product with about 43% recycled materials under the EU ZEvRA project. | Concept stage; it targets the top EU label rating for rolling resistance. |
| In May 2025, Yokohama Rubber confirmed a USD 35 million purchase of a closed factory in Drobeta-Turnu Severin, Romania. | Adds off-the-road capacity for mining and construction machinery in Europe. |
| In February 2025, Hankook broke ground on a EUR 540 million expansion at Rácalmás, Hungary, including a truck and bus line. | Scheduled for completion in 2027, with capacity up to 800,000 units a year. |
| In March 2025, Nokian Tyres began deliveries from its new Oradea factory in Romania. | One million units were made by December 2025, with 6 million a year planned. |
Abrasion limits and recycled materials steer tire design
- Abrasion testing becomes a regulated property alongside rolling resistance, wet grip and noise, with passenger car methods due from the UN working group by July 2028.
- Recycled and renewable inputs are moving from pilots toward product design, as the Continental ZEvRA concept combines recycled steel, end-of-life rubber and recovered carbon black.
- Low rolling resistance compounds serve electric cars and long-haul trucks, and Michelin claims 0.62 liters per 100 kilometers of fuel savings for its X Line Energy 3.
- VF radial casings carry heavy farm loads at lower pressure, and several makers showed new ranges at Agritechnica in November 2025 to limit soil compaction.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Premium makers restructure as low-cost imports face duties
Competition in Europe splits between premium makers that defend original equipment approvals and brand strength, and value suppliers that compete on price through wholesalers and online channels. Michelin, Continental, Bridgestone and Goodyear are concentrating output on fewer sites and larger sizes, while closing older capacity in France and Germany. Hankook, Nokian Tyres and Yokohama Rubber are adding European capacity, which shortens delivery times and limits exposure to freight and to trade measures. Pirelli competes in premium and high-performance car tires from plants in Italy, Romania and Germany, while Sumitomo Rubber Industries sells Dunlop and Falken tires after buying the European Dunlop brand rights from Goodyear. Giti reached European buyers with its GT Radial ClimateActive all-season range, which covers 15- to 21-inch sizes across more than 40 product codes. Definitive duties on Chinese supply should help European plants at the entry level, though they will not remove low-cost competition from other Asian sources. In the farm and off-road niches, specialist brands compete on casing technology and dealer service rather than on list price.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Michelin | Global premium maker | Closed Cholet and Vannes in France; promotes EV and fleet ranges in the U.K. |
| Continental AG | German premium maker | Expanding truck and bus output at Puchov, Slovakia; leads the ZEvRA recycled concept |
| Bridgestone | Global premium maker | Investing up to EUR 207 million in Burgos, Spain, through 2030 |
| Goodyear | Global maker | Closed its Fulda plant in Germany during its 2024 restructuring |
| Pirelli | Italian premium maker | Premium and high-performance car tires from plants in Italy, Romania and Germany |
| Hankook Tire | Korean maker with EU plant | Expanding Rácalmás, Hungary, with a truck and bus line due in 2027 |
| Nokian Tyres | Nordic winter specialist | Ramping up Oradea, Romania, toward 6 million units a year |
| Sumitomo Rubber Industries | Japanese maker | Dunlop and Falken tires, after buying European Dunlop brand rights from Goodyear |
| Yokohama Rubber | Japanese maker | Bought a Romanian site in 2025 for off-the-road production |
| Apollo Vredestein | Apollo Tyres European brand | Planned the Enschede shutdown by summer 2026, keeping production in Hungary |
| Giti Tire | Asian value supplier | Sells the GT Radial ClimateActive all-season range through European distribution |
Replacement resilience matters more than new car volume
Credence Research's view is that replacement resilience matters more to this market than any recovery in new vehicle sales. Fleet age, winter rules and electric car specifications should hold value growth near 3.51% even when unit sales stay flat, as they did in 2025. The 2026 duties are the main swing factor, because they could return entry-level volume to European plants or simply move imports to other Asian countries. Buyers should test price lists against supplier-specific duty rates, while investors should favor capacity in high-rim, truck and low-abrasion products over standard ranges.
How Credence Research built the European tire estimates
The report uses 2025 as the base year and 2026 to 2035 as the forecast period, with market values taken from the Credence Research model. Country, vehicle, demand, construction and channel splits are Credence Research estimates informed by public data rather than reported statistics. Sources used were EU legal texts, ACEA, ACEM and SMMT vehicle data, Tyres Europe and BRV trade statistics, company reports and releases, and trade press reports. No interviews or surveys were conducted for this edition, and estimates carry uncertainty.
Duties, Euro 7 and fleet age set the path to 2035
By 2035, the Europe tire market is expected to reach USD 111.83 billion, with growth concentrated in replacement, truck and bus and Central and Eastern European demand. Euro 7 becomes the main technical test once passenger car type approval starts in 2028 and van and truck dates follow by 2032. Fleet renewal should gradually raise the electric share of the car base, which supports higher-value fitments. The main risks are prolonged weakness in vehicle output, further plant closures and a move of imports to countries outside the present duties. Producers that hold premium approvals in efficient plants should be best placed.
Frequently Asked Questions
How big is the Europe tire market?
What drives the Europe tire industry?
Which segment leads the Europe automotive tire market?
Which country has the largest share of European tire demand?
Are winter tires compulsory in Europe?
How are electric vehicles affecting tires in Europe?
What are the EU duties on Chinese tires?
What is happening in the European agricultural and mining tire market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle Type
- 1.2.1 Passenger Car Tires
- 1.2.2 Light Truck Tires
- 1.2.3 Truck and Bus Tires
- 1.2.4 Motorcycle Tires
- 1.2.5 Special Vehicle Tires
- 1.3 By Demand
- 1.3.1 Replacement
- 1.3.2 OEM
- 1.4 By Type of Tires
- 1.4.1 Radial
- 1.4.2 Bias
- 1.5 By Country
- 1.5.1 Germany
- 1.5.2 France
- 1.5.3 United Kingdom
- 1.5.4 Italy
- 1.5.5 Spain
- 1.5.6 Central and Eastern Europe
- 1.5.7 Rest of Europe
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 79.20 billion → 2035: USD 111.83 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Tire Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Tire Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Tire Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Tire Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Tire Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Tire Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Tire Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Tire Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 79.20 billion → 2035: USD 111.83 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Tire Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Car Tires
- 12.3.7.2 Light Truck Tires
- 12.3.7.3 Truck and Bus Tires
- 12.3.7.4 Motorcycle Tires
- 12.3.7.5 Special Vehicle Tires
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Demand - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Replacement
- 12.4.7.2 OEM
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Tires - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Radial
- 12.5.7.2 Bias
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Germany
- 12.6.7.2 France
- 12.6.7.3 United Kingdom
- 12.6.7.4 Italy
- 12.6.7.5 Spain
- 12.6.7.6 Central and Eastern Europe
- 12.6.7.7 Rest of Europe
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Tire Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Country-Level Shares, 2025
- 13.2 Country Market Size Comparison, 2025
- 13.3 Country Market Forecasts, 2025-2035
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Tire Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Tire Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Michelin
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Continental AG
- 17.4 Bridgestone
- 17.5 Goodyear
- 17.6 Pirelli
- 17.7 Hankook Tire
- 17.8 Nokian Tyres
- 17.9 Sumitomo Rubber Industries
- 17.10 Yokohama Rubber
- 17.11 Apollo Vredestein
- 17.12 Giti Tire
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

