
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europium Market Size 2023 | USD 257.94 Million |
| Europium Market, CAGR | 4.60% |
| Europium Market Size 2032 | USD 369.64 Million |
Market Overview
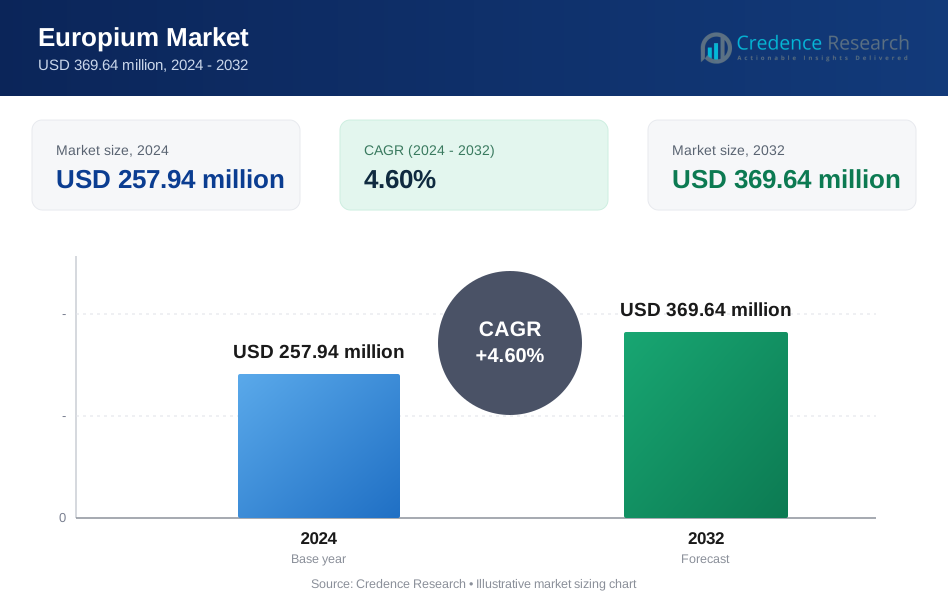
The Europium Market is anticipated to grow from USD 257.94 million in 2024 to USD 369.64 million by 2032, achieving a compound annual growth rate (CAGR) of 4.60%.
The Europium Market is driven by increasing demand in advanced technology sectors, particularly in the production of phosphors for LED lighting and displays, which rely on europium for enhanced brightness and color purity. The expansion of consumer electronics and renewable energy technologies further fuels market growth. Trends include advancements in europium-based materials for improving the efficiency of displays and lighting systems, and rising investments in research for novel applications in quantum computing and medical imaging. Additionally, growing environmental regulations are encouraging the development of more sustainable methods for europium extraction and processing.
The Europium Market exhibits significant regional dynamics, with China dominating global supply due to its vast reserves and production capabilities. Key players such as Avalon Rare Metals, Lynas Corporation, and Rare Element Resources are critical in diversifying supply and addressing geopolitical risks. North America and Europe are also notable for their growing consumption, driven by advanced electronics and automotive applications. These regions are increasingly focusing on developing alternative sources and sustainable practices to mitigate supply constraints and environmental concerns. The presence of diverse key players and shifting regional focuses highlight the evolving landscape of the europium market.
Market Drivers
Growth in Electronics Industry
Europium's significance in the electronics industry is underscored by its crucial role in phosphors, which convert ultraviolet light or electron beams into visible light. Europium is a key component in phosphors used in various electronic displays. For instance, it’s estimated that a typical flat-screen TV contains about 0.5 grams of europium. As the number of electronic devices worldwide continues to grow, the demand for europium is expected to rise accordingly. These phosphors are integral to a range of electronic displays, including televisions, fluorescent lamps, smartphone screens, and wearable device displays. As technology advances and the demand for high-quality displays and lighting solutions grows, so does the need for europium. This trend highlights the essential role of europium in maintaining and enhancing the performance of modern electronic devices, driving sustained demand within the market.
Rising Consumer Electronics Demand
The expanding consumer electronics market, particularly in rapidly developing economies such as China and India, significantly drives europium demand. Increased disposable incomes and technological advancements in these regions lead to a surge in electronics purchases, from smartphones to advanced home entertainment systems. For example, in 2023, it was reported that smartphone users in India reached approximately 760 million, and each smartphone uses europium in its display. As consumer spending on electronics continues to rise, the corresponding demand for europium, used extensively in high-performance displays and lighting, also grows. This burgeoning market provides a substantial impetus for europium, reinforcing its critical role in the electronics sector.
Supply-Side Factors
Europium's market dynamics are influenced by its limited reserves and complex extraction processes. For instance, as of 2020, China was responsible for about 85% of the global rare earth elements production, including europium. Environmental concerns and regulations related to the mining and processing of rare earth elements are also influencing the europium market. As a rare earth element, europium's mineable reserves are geographically concentrated, which can impact pricing and availability. Furthermore, environmental concerns associated with the mining and processing of rare earth elements are prompting stricter regulations and a push towards sustainable practices. These supply-side factors, including resource scarcity and environmental impacts, will shape the future of the europium market, affecting how it is sourced and managed.
Other Applications and Growth Areas
Beyond electronics, europium is pivotal in the nuclear energy sector. Europium-based control rods, renowned for their high neutron absorption capacity, are essential for regulating nuclear reactions in reactors. Additionally, ongoing research and development are uncovering new applications for europium, including magnetic refrigeration, solid-state lasers, and biolabeling for medical research. These emerging uses offer promising growth opportunities for the europium market, potentially broadening its application base and fostering future expansion.
Market Trends
Shift Towards Miniaturization and Efficiency
The electronics industry’s relentless pursuit of miniaturization and enhanced efficiency directly influences the demand for europium-based phosphors. For instance, a modern smartphone might have a display that’s less than 7 inches in size, but it requires a high level of brightness and color accuracy. As devices become smaller and more advanced, the need for phosphors that deliver higher luminescence efficacy becomes paramount. Manufacturers are responding to this trend by developing new phosphor formulations that require less europium to achieve the desired brightness levels. This approach not only helps address the challenges posed by europium’s limited supply but also aligns with the industry’s focus on efficiency. By optimizing phosphor compositions, companies aim to maintain high performance while mitigating the impact of supply constraints, thus supporting the growth and innovation within the electronics sector.
Focus on Alternatives and Recycling
Given the finite nature of europium reserves and the environmental concerns associated with its extraction, there is an increasing emphasis on finding alternatives and enhancing recycling methods. For instance, a study published in the Journal of Sustainable Metallurgy in 2020 demonstrated a method for recovering over 95% of europium from used fluorescent lamps. Research is actively exploring new phosphor materials that use lower quantities of europium or entirely different substances to achieve similar performance. Concurrently, efforts are being made to develop efficient recycling techniques to recover europium from electronic waste, which can reduce dependency on newly mined resources. This dual focus on alternative materials and recycling is crucial for addressing supply challenges and minimizing environmental impacts, ensuring a more sustainable approach to europium use. The drive for alternative solutions and improved recycling practices reflects the broader trend towards sustainability and resource efficiency in the industry.
Market Challenges Analysis
Supply and Geopolitical Challenges
Europium's market faces significant challenges due to its limited supply and geopolitical concentration. As a rare earth element, europium’s mineable reserves are predominantly located in a few countries, with China being the primary source. This concentration creates a vulnerability in the supply chain, leading to potential disruptions and price volatility. The reliance on a single source also exposes the market to political influences and trade policies that can impact supply stability and costs. Such geopolitical risks can result in significant fluctuations in europium prices, complicating production planning for manufacturers. This scenario underscores the need for diversification strategies and geopolitical risk management to ensure a more resilient and stable supply chain.
Environmental and Regulatory Concerns
The extraction and processing of europium are associated with various environmental challenges, including water pollution, radioactive waste, and soil degradation. The mining of rare earth elements has come under increasing scrutiny due to these negative environmental impacts. Stricter environmental regulations and heightened public concern about sustainability are prompting the industry to address these issues more effectively. Compliance with these regulations can lead to increased costs and complexity in the manufacturing process. To mitigate these challenges, there is a growing emphasis on adopting sustainable mining practices and developing innovative technologies to minimize environmental damage. Additionally, efficient recycling methods are being explored to recover europium from electronic waste, reducing the need for new extraction and supporting a more sustainable approach to resource management.
Market Segmentation Analysis:
By End-Use:
The europium market demonstrates significant diversity in its end-use applications, reflecting its versatile properties across various industries. Consumer Electronics remains a major segment, driven by europium’s role in phosphors used in displays, smartphones, and televisions. The Lighting sector also relies heavily on europium, especially in fluorescent and LED lighting, where its luminescent properties are crucial for producing vibrant colors. The Semiconductors industry benefits from europium’s use in specific components that enhance electronic performance. In the Automotive sector, europium is utilized in advanced lighting and electronic systems, which are becoming increasingly sophisticated. Healthcare applications, including diagnostic imaging and medical devices, leverage europium’s radiological properties. Nuclear Labs utilize europium in control rods due to its effective neutron absorption capabilities. The Metallurgy sector employs europium in alloy formulations to improve material properties. Anti-Counterfeiting applications use europium for its distinct luminescent signatures, crucial for secure document and currency verification. Collectively, these end-uses underscore europium's integral role in advancing technology and enhancing various industry functions.
By Application:
Europium's applications further highlight its critical role in a range of specialized fields. Catalysts use europium in reactions that benefit from its unique chemical properties, improving industrial processes. In Metal Alloys, europium is added to enhance strength and durability, contributing to the development of high-performance materials. Glass Polishing benefits from europium’s ability to improve surface finish and clarity in glass products. The use of europium in Permanent Magnets involves its inclusion in high-performance magnetic materials. Phosphors remain a key application, where europium’s luminescence is essential for vibrant displays in electronic devices and lighting solutions. Ceramics incorporate europium to improve color and stability in ceramic products. In Glass Additives, europium enhances the optical and physical properties of glass used in various applications. Other applications reflect ongoing research and development efforts to explore new uses for europium, demonstrating its adaptability and importance across multiple sectors.
Segments:
Based on End-Use:
- Consumer Electronics
- Lighting
- Semiconductors
- Automotive
- Healthcare
- Nuclear Labs
- Metallurgy
- Anti-Counterfeiting
- Others
Based on Application:
- Catalysts
- Metal Alloys
- Glass Polishing
- Permanent Magnets
- Phosphors
- Ceramics
- Glass Additives
- Others
Based on the Geography:
- North America
- Asia-Pacific
- South America
- Europe
- Middle East and Africa
Regional Analysis
Asia Pacific
Asia Pacific dominates the market, commanding a substantial 45% market share. This leadership position is primarily driven by China, which not only possesses significant europium reserves but also boasts a thriving rare earth elements industry. The region's robust electronics manufacturing sector, particularly in countries like Japan, South Korea, and Taiwan, fuels the demand for europium in the production of LED displays, smartphones, and other electronic devices. Additionally, the growing adoption of energy-efficient lighting solutions across the Asia Pacific contributes to the increased consumption of europium-based phosphors.
North America
North America holds a noteworthy 25% market share in the europium market, with the United States leading the region's demand and production efforts. The region's market is primarily driven by its advanced technology sector, particularly in areas such as medical imaging, nuclear reactors, and specialized lighting applications. The US government's initiatives to reduce dependence on foreign rare earth supplies have spurred domestic production and research into europium alternatives. Furthermore, the region's strong focus on renewable energy and energy-efficient technologies contributes to the demand for europium in various applications, including solar panels and wind turbines.
Key Player Analysis
- Avalon Rare Metals
- Great Western Minerals
- Canada Rare Earth
- Rare Element Resources
- Baotou Steel Rare-Earth
- Lynas Corporation
- Indian Rare Earth
- Hastings Technology Metals Ltd
- Arafura Resources
- Neo Performance Materials
Competitive Analysis
The Europium Market is characterized by intense competition among key players who are crucial in shaping market dynamics. Lynas Corporation stands out with its significant production capabilities and efforts to diversify europium supply beyond China. Avalon Rare Metals and Rare Element Resources are notable for their exploration and development projects aimed at expanding europium sources outside traditional regions. Great Western Minerals and Canada Rare Earth focus on refining processes and improving efficiency in europium extraction. Baotou Steel Rare-Earth, a major Chinese player, leverages its extensive reserves to maintain a dominant position in the market. Neo Performance Materials and Hastings Technology Metals Ltd contribute through innovation in high-performance applications. Indian Rare Earth and Arafura Resources are emerging players that enhance market competition through regional production advancements. These companies drive competition through technological innovation, strategic partnerships, and expanding global supply chains, addressing the growing demand for europium across various applications.
Recent Developments
- In 2024, Priya Agrawal Hebbar, Chairperson of Udaipur-based Hindustan Zinc, a subsidiary of the Vedanta Group, addressed the Bank of America Securities Global Metals, Mining and Steel Conference in Miami. She emphasized India's ambition to emerge as a leading and most sustainable producer of critical minerals globally. Hebbar highlighted that Hindustan Zinc is poised to play a pivotal role in advancing the production of clean energy technologies, aligning with the country's strategic vision for a more sustainable future.
- In May 2024, Huang Changgeng, Chairman of Xiamen Tungsten Co., Ltd. (XTC), headquartered in Fujian, revealed details of the company's joint venture with France-based Orano SA. The companies are anticipated to drive cooperation in green technologies between the two nations.
- In April 2024, MMG Limited, a subsidiary company of Minmetals Corporation headquartered in Beijing, finalized the acquisition of Khoemacau Copper Mine in Botswana.
Market Concentration & Characteristics
The Europium Market exhibits a moderate level of market concentration, with a few dominant players significantly influencing market dynamics. Key players such as Lynas Corporation, Avalon Rare Metals, and Rare Element Resources command substantial market share due to their advanced production technologies and strategic initiatives to diversify supply sources. The market is characterized by high entry barriers, including complex extraction processes and significant capital investment, which limits the number of active participants. Additionally, the geographic concentration of europium reserves, primarily in China, further intensifies competition among existing players. The industry faces pressures related to supply chain stability, environmental regulations, and technological advancements. Companies are increasingly focused on improving efficiency, sustainability, and exploring alternative sources to mitigate supply risks. This competitive landscape drives ongoing innovation and strategic partnerships, shaping the market's future trajectory while responding to evolving global demand for europium in various high-tech applications.
Report Coverage
The research report offers an in-depth analysis based on End-Use, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europium Market is expected to grow due to rising demand for advanced electronic devices and high-performance phosphors.
- Increasing investments in research and development will drive innovation in europium-based applications.
- The expansion of consumer electronics and automotive industries will boost europium consumption.
- Sustainable sourcing and recycling practices will become more critical to address environmental concerns.
- The market will benefit from advancements in alternative materials and technologies reducing reliance on europium.
- Regional diversification of supply sources will help mitigate geopolitical risks and stabilize market conditions.
- Emerging applications in medical research and high-tech sectors will create new demand for europium.
- Enhanced regulatory frameworks and environmental regulations will shape production practices and market dynamics.
- Competitive pressures will drive players to focus on cost reduction and efficiency improvements.
- Collaboration between industry stakeholders will be crucial for addressing supply chain challenges and meeting evolving market needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europium Market?
What factors are driving the growth of the Europium Market?
What are the key segments within the Europium Market?
What are some challenges faced by the Europium Market?
Who are the major players in the Europium Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europium Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europium Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 257.94 million → 2032: USD 369.64 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europium Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europium Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europium Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europium Market Drivers
- 3.3 Europium Market Restraints & Challenges
- 3.4 Europium Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europium Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europium Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europium category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europium Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europium Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europium market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europium Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europium Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europium Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europium (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europium Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europium Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europium Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europium Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europium Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europium Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europium Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europium Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europium Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
