
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| France Managed Services Market Size 2023 | USD 13,730.87 million |
| France Managed Services Market, CAGR | 6.85% |
| France Managed Services Market Size 2032 | USD 24,929.66 million |
Market Overview
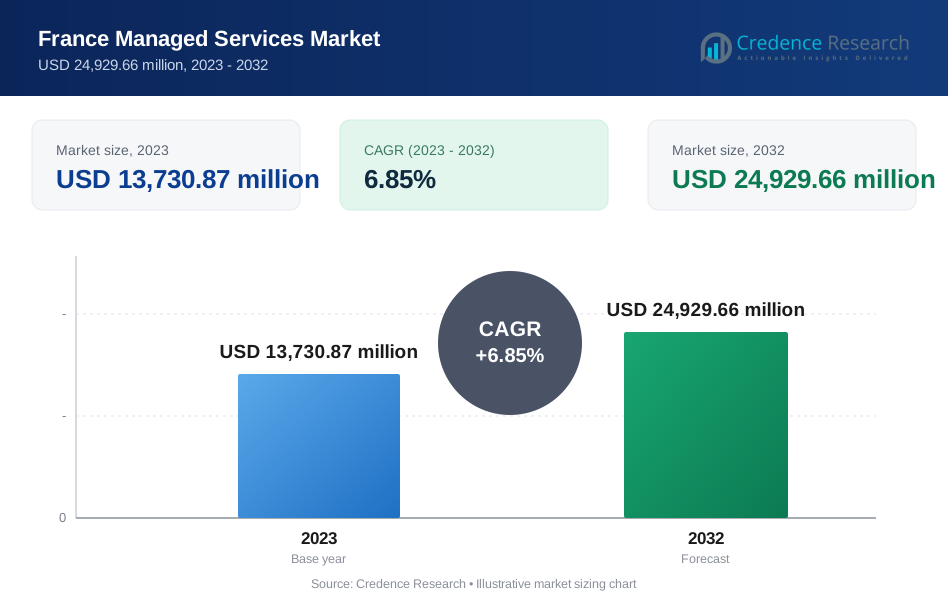
The France Managed Services Market is projected to grow from USD 13,730.87 million in 2023 to USD 24,929.66 million by 2032, at a CAGR of 6.85% during the forecast period.
The France managed services market is driven by the increasing adoption of digital transformation initiatives across industries, as businesses seek to enhance operational efficiency and reduce IT infrastructure costs. Growing reliance on cloud-based solutions and demand for cybersecurity services amid rising cyber threats are fueling market expansion. Small and medium enterprises (SMEs) are increasingly outsourcing IT services to focus on core operations, boosting market growth. Additionally, the rise of hybrid and remote work models has accelerated the need for advanced network management and IT support solutions. Key trends include the integration of artificial intelligence (AI) and automation in managed services, which optimize workflows and enhance service delivery. Furthermore, the adoption of Internet of Things (IoT) solutions and data analytics is driving innovation, enabling businesses to leverage real-time insights for strategic decision-making. These factors collectively support the robust growth of managed services in France over the coming years.
France's managed services market is geographically diverse, with key regions like Northern France, Southern France, Eastern France, and Western France experiencing varying growth driven by local industries. Northern France is home to major industrial hubs, making it a hotspot for IT infrastructure and security services, while Southern France thrives in sectors like healthcare and tourism, spurring demand for network and communication services. Eastern France is witnessing growing adoption of IT modernization, particularly in manufacturing, and Western France focuses on managed security and cloud solutions due to its strong emphasis on digitalization. Key players in the French managed services market include prominent service providers such as Atos, Capgemini, Orange Business Services, and Sopra Steria. These companies offer a range of services including managed IT, network solutions, cybersecurity, and cloud-based services, playing a significant role in supporting the digital transformation of businesses across France.
Market Insights
- The France Managed Services market was valued at USD 13,730.87 million in 2023 and is expected to reach USD 24,929.66 million by 2032, growing at a CAGR of 6.85%.
- Increasing cloud adoption and digital transformation across industries are driving market growth.
- The demand for managed security services is rising due to growing cyber threats and regulatory requirements.
- The integration of AI and automation in managed services is enhancing operational efficiency and reducing costs.
- SMEs are increasingly outsourcing IT services to reduce operational complexities and gain access to specialized expertise.
- Competitive players like Atos, Capgemini, and Orange Business Services are leading the market with comprehensive service offerings.
- Regional markets show varied growth, with Northern France dominating in industrial sectors, and Southern France focusing on network and cloud services for diverse industries.
Market Drivers
Rising Adoption of Digital Transformation Initiatives
The increasing emphasis on digital transformation across various industries is a key driver of the France managed services market. Businesses are increasingly leveraging managed services to modernize their IT infrastructure, streamline operations, and adopt cloud-based solutions. For instance, a survey by the French Ministry of Economy and Finance revealed that a significant number of French companies have implemented digital transformation strategies to enhance productivity and scalability. Companies are outsourcing IT management tasks to specialized service providers, which offer cost-effective and efficient solutions, allowing businesses to focus on their core competencies while ensuring seamless operations. This trend is further accelerated by advancements in technologies such as automation, artificial intelligence (AI), and machine learning, which optimize service delivery and improve operational efficiency.
Increasing Demand for Cybersecurity Solutions
The rising frequency of cyberattacks and data breaches has heightened the demand for robust cybersecurity solutions in France. As businesses become more reliant on digital systems, protecting sensitive data and IT infrastructure has become a top priority. For instance, a report by the French National Cybersecurity Agency (ANSSI) indicated a notable increase in cyberattacks on French businesses over the past year. Managed security services play a crucial role in safeguarding organizations against evolving cyber threats by offering real-time monitoring, threat detection, and incident response. Small and medium-sized enterprises (SMEs), which often lack in-house IT expertise, are particularly turning to managed security providers for comprehensive protection. This growing reliance on managed cybersecurity services is a significant factor driving market growth.
Growing Adoption of Cloud-Based Services
The rapid shift toward cloud computing is another major driver of the managed services market in France. Companies are adopting cloud-based managed services to improve agility, reduce operational costs, and enhance scalability. Cloud platforms provide businesses with the flexibility to access data and applications from anywhere, enabling remote work and boosting overall efficiency. Managed service providers (MSPs) offer expertise in cloud management, ensuring seamless migration, integration, and maintenance of cloud-based solutions. The growing preference for hybrid and multi-cloud environments further strengthens the demand for managed services in the country.
Focus on Cost Optimization and Operational Efficiency
Businesses in France are increasingly seeking ways to optimize operational costs while maintaining high levels of efficiency. Managed services provide a cost-effective alternative to in-house IT management by reducing the need for extensive IT infrastructure and dedicated personnel. For instance, a study by the French Chamber of Commerce and Industry (CCI) highlighted that companies outsourcing IT operations to managed service providers experienced a significant reduction in operational costs. Organizations benefit from predictable pricing models, improved resource allocation, and access to expert support. This approach allows businesses to achieve operational excellence without incurring high capital expenditures, making managed services a strategic choice for long-term growth and competitiveness.
Market Trends
Growing Integration of Artificial Intelligence and Automation
The integration of artificial intelligence (AI) and automation in managed services is transforming service delivery and operational efficiency. For instance, the French AI Strategy Report highlights the government's commitment to AI development, which includes significant investments in AI research and training. This reduces human intervention, accelerates response times, and minimizes operational costs. Additionally, predictive analytics driven by AI helps organizations identify potential issues before they escalate, ensuring seamless IT operations. The growing use of automation and AI-driven tools is enabling service providers to offer smarter, faster, and more efficient solutions to businesses across France.
Rising Focus on Managed Security Services
The growing threat of cyberattacks has fueled the demand for managed security services in France. Organizations are prioritizing advanced cybersecurity solutions to protect sensitive data, ensure compliance with regulatory frameworks, and mitigate risks. Managed service providers are offering comprehensive security solutions, including threat detection, incident response, and vulnerability management. With the rise of remote work and increasing digitalization, businesses are facing complex cybersecurity challenges that require continuous monitoring and proactive defense strategies. This growing emphasis on managed security services is a key trend shaping the French managed services market.
Increasing Demand for IT Outsourcing Among SMEs
Small and medium-sized enterprises (SMEs) in France are increasingly outsourcing their IT functions to managed service providers to reduce operational costs and gain access to specialized expertise. For instance, a study by the French Chamber of Commerce and Industry (CCI) highlighted that many SMEs are turning to managed services to support their digital transformation efforts. SMEs often lack the resources and skilled personnel needed to manage complex IT environments. Managed services offer a cost-effective and scalable solution, allowing SMEs to focus on their core business operations while ensuring reliable IT support. This trend is further driven by the need for digital transformation, cloud adoption, and cybersecurity among SMEs, positioning managed service providers as essential partners for business growth.
Increasing Adoption of Cloud-Based Managed Services
The adoption of cloud-based managed services is a prominent trend in the France managed services market. Businesses are increasingly moving their IT operations to the cloud to gain flexibility, scalability, and cost-efficiency. Managed service providers (MSPs) are offering tailored cloud solutions, including hybrid and multi-cloud models, to meet the unique demands of organizations. This shift allows companies to streamline operations, facilitate remote work, and ensure business continuity. Moreover, advancements in cloud technologies, such as edge computing and serverless architecture, are further driving the adoption of managed cloud services in France.
Market Challenges Analysis
Data Security and Privacy Concerns
One of the significant challenges facing the France managed services market is the growing concern over data security and privacy. As businesses increasingly adopt cloud-based solutions and digital platforms, the risk of data breaches and unauthorized access has intensified. For instance, a report by the French National Cybersecurity Agency (ANSSI) highlighted a notable increase in cyberattacks on French businesses, emphasizing the need for robust security measures. Organizations must comply with stringent regulations, such as the General Data Protection Regulation (GDPR), which mandates the protection of personal data. Ensuring compliance while outsourcing IT operations to managed service providers (MSPs) can be challenging, as it requires businesses to maintain a high level of trust in their service partners. Additionally, companies are often hesitant to share sensitive data with third-party providers due to fears of misuse or lack of control. Addressing these concerns requires MSPs to invest in advanced security protocols, transparent operations, and regular audits to build client confidence.
High Cost of Transition and Skilled Workforce Shortage
The high cost of transitioning to managed services and the shortage of skilled IT professionals present another critical challenge for the market. Migrating IT infrastructure to managed service models often involves substantial upfront investment, which can deter small and medium-sized enterprises (SMEs) from adopting these solutions. Moreover, businesses may face operational disruptions during the transition phase, further complicating the process. At the same time, the managed services industry faces a shortage of skilled IT professionals capable of managing complex networks, cloud systems, and cybersecurity frameworks. This talent gap can limit the ability of service providers to deliver high-quality solutions, particularly in highly technical areas such as artificial intelligence, automation, and cybersecurity. To overcome these challenges, MSPs must focus on offering cost-effective, phased implementation strategies and invest in workforce development through training and upskilling initiatives.
Market Opportunities
Growing Demand for Advanced Cloud Solutions
The increasing adoption of cloud computing presents significant opportunities for the France managed services market. As businesses continue to embrace hybrid and multi-cloud environments, the need for expert management of these complex infrastructures is growing. Managed service providers (MSPs) can capitalize on this demand by offering specialized cloud migration, integration, and maintenance services. Organizations are also seeking advanced cloud solutions that incorporate edge computing and serverless architectures to enhance efficiency and reduce latency. Additionally, as remote and hybrid work models gain traction, MSPs have the opportunity to provide secure, scalable, and cost-effective cloud-based solutions that ensure seamless business continuity and improved collaboration.
Rising Adoption of Managed Security Services
The escalating cyber threat landscape in France creates a strong opportunity for managed security services. With businesses facing increasingly sophisticated cyberattacks, there is a growing need for comprehensive security solutions that offer real-time monitoring, threat detection, and rapid incident response. Managed service providers can position themselves as trusted partners by delivering robust cybersecurity frameworks and compliance-driven solutions tailored to industry regulations like GDPR. Small and medium-sized enterprises (SMEs), in particular, present a lucrative segment as they often lack in-house resources to tackle complex security challenges. By offering cost-effective and scalable managed security services, providers can help businesses safeguard their IT infrastructure, minimize risks, and build resilience in an evolving digital environment. These opportunities position MSPs to play a critical role in driving the growth and digital transformation of businesses in France.
Market Segmentation Analysis:
By Service Type:
The France managed services market is segmented into Managed IT Infrastructure & Data Center, Managed Network, Managed Communication & Collaboration, Managed Information, Managed Security, and Others. Among these, Managed IT Infrastructure & Data Center services hold a significant share as organizations increasingly rely on outsourced infrastructure management to reduce operational costs and enhance efficiency. Managed Security services are witnessing rapid growth due to the rising cyber threat landscape and stringent regulatory requirements, such as GDPR compliance. Businesses are prioritizing advanced security solutions, including real-time threat monitoring and incident response, to safeguard their operations. Meanwhile, Managed Network and Managed Communication & Collaboration services are gaining traction, driven by the need for seamless connectivity and effective remote work environments. Smaller organizations, particularly SMEs, are turning to these services to bridge IT capability gaps, enabling streamlined operations and cost savings. These diverse service segments offer businesses tailored solutions to optimize their IT environments while focusing on their core operations.
By Deployment Type:
By deployment type, the market is categorized into On-premise and Cloud-based managed services. The Cloud-based segment dominates the market as businesses across France increasingly adopt cloud solutions to improve agility, scalability, and operational efficiency. The shift toward hybrid and multi-cloud environments further drives the demand for managed cloud services, as organizations seek expert support for cloud migration, maintenance, and optimization. Cloud-based managed services also facilitate remote work, business continuity, and secure access to applications and data. Meanwhile, the On-premise segment continues to serve businesses with stringent data privacy requirements or those in highly regulated industries. However, the growing preference for digital transformation and cost-efficiency is pushing many organizations to transition from on-premise to cloud-based models. Managed service providers play a crucial role in this transition, offering expertise, security, and seamless integration. The increasing adoption of cloud-based solutions highlights a strong opportunity for providers to cater to evolving business needs across France.
Segments:
Based on Service Type:
- Managed IT Infrastructure & Data Center
- Managed Network
- Managed Communication & Collaboration
- Managed Information
- Managed Security
- Others
Based on Deployment Type:
- On-premise
- Cloud
Based on Enterprise Size:
- Large Enterprises
- SME’s
Based on End User:
- IT & Telecom
- BFSI
- Manufacturing
- Retail
- Government
- Others
Based on the Geography:
- Northern France
- Southern France
- Eastern France
- Western France
Regional Analysis
Northern France
Northern France holds the largest market share in the managed services market, accounting for approximately 35% of the total market. This dominance is largely attributed to the region's concentration of industrial hubs and its advanced technological infrastructure. Major cities like Lille and Rouen act as economic drivers, with industries such as manufacturing, automotive, and logistics increasingly adopting managed services to optimize operations and enhance cybersecurity. The region has witnessed strong demand for Managed IT Infrastructure & Data Center and Managed Security services, as businesses strive for operational efficiency and robust data protection. The expanding adoption of cloud-based solutions further fuels this growth, making Northern France a leader in the managed services sector.
Southern France
Southern France holds a significant share of approximately 25% of the managed services market. The region’s thriving sectors, including tourism, healthcare, and retail, are key drivers of this growth. Cities like Marseille and Nice have become key adoption centers for Managed Network and Managed Communication & Collaboration services, as businesses focus on improving connectivity and collaboration tools, especially due to the rising demand for remote work solutions. With the increasing reliance on cloud infrastructure to support business continuity, Southern France's managed services market is experiencing rapid expansion. Furthermore, rising cyber threats have made Managed Security services a priority, contributing to the region's strong market performance.
Eastern France
Eastern France has seen a steady rise in the managed services market, currently holding around 20% of the market share. The region's industrial base, particularly in sectors like manufacturing, automotive, and energy, is a driving force behind the increasing demand for Managed IT Infrastructure & Data Center and Managed Security services. Cities such as Strasbourg and Mulhouse are gradually adopting digital transformation strategies, with more businesses turning to managed services to streamline operations, reduce costs, and secure their IT infrastructure. The adoption of cloud-based solutions is gaining momentum, providing businesses with scalable, efficient, and secure options to support their operations. As digital modernization accelerates in Eastern France, the market share is expected to grow further.
Western France
Western France, with a market share of approximately 20%, is experiencing strong growth in Managed Security and Cloud-based services. Cities like Nantes and Rennes are emerging as key centers for digital innovation, with businesses in sectors like education, finance, and government increasingly adopting managed services to address rising cybersecurity threats. The growing demand for Managed Security services is driven by the need to comply with regulatory frameworks and protect sensitive data. Additionally, businesses are rapidly adopting cloud-based solutions to enhance agility, manage resources efficiently, and enable remote work. Western France's growing digital infrastructure and focus on cybersecurity position it as a promising region for continued market expansion.
Key Player Analysis
- Cognizant Technology Solutions
- BT
- BAE Systems
- Capgemini
- Claranet Limited
- IBM Corporation
- Accenture
- Google LLC
- Microsoft Corporation
- Cisco Systems Inc.
- Kernix
- DXC Technology
- Tata Consultancy Services
- Infosys
- HCLTech
Competitive Analysis
The competitive landscape of the France Managed Services market is characterized by the presence of several leading players who provide a broad range of IT services to meet the growing demand for digital transformation, security, and cloud solutions. Prominent players include Atos, Capgemini, Orange Business Services, Sopra Steria, DXC Technology, IBM, and T-Systems, among others. These companies offer a variety of managed services, including IT infrastructure management, cybersecurity, cloud solutions, and network services. For instance, the French government has launched initiatives like France 2030, which includes significant investments in digital security and nurturing startups. The market is characterized by the presence of both global and regional service providers who focus on delivering comprehensive managed services, including IT infrastructure management, cybersecurity, cloud solutions, and network services. These companies differentiate themselves through their technological capabilities, offering innovative solutions such as artificial intelligence, automation, and machine learning to enhance service delivery and operational efficiency. Competition is also driven by the increasing adoption of cloud services and the growing need for cybersecurity solutions, which has led to a surge in demand for managed security services. Providers are focusing on offering scalable and cost-effective solutions that meet the diverse needs of industries ranging from manufacturing and healthcare to finance and retail. To maintain a competitive edge, companies are investing heavily in technological advancements and improving customer support to ensure seamless service delivery. Additionally, businesses are increasingly seeking specialized providers to manage their IT infrastructure, which has led to a rise in niche players offering tailored solutions for specific market segments.
Recent Developments
- In January 2024, Accenture acquired NaviSite to strengthen its managed services offerings, particularly in application and infrastructure management. The acquisition will enhance Accenture’s ability to assist US and Canadian clients in modernizing their digital infrastructure, focusing on AI, cloud, and data-driven solutions for digital transformation.
- In September 2024, TCS launched two AI-powered cybersecurity solutions - Managed Detection and Response (MDR) and Secure Cloud Foundation - in collaboration with Google Cloud. The MDR service was intended to offer continuous, managed threat detection and response, while Secure Cloud Foundation aimed to enhance cloud security posture and governance across hybrid environments. Both solutions leverage Google Cloud’s security tools to provide proactive enterprise protection.
- In June 2024, DXC Technology and Dell partnered to establish Enterprise Intelligence Services (EIS). This service aimed to improve managed services by combining artificial intelligence, data analytics, and cloud technology. EIS’s multi-cloud strategy was expected to help organizations streamline operations, make smarter decisions, and improve customer experiences, proving DXC’s position as the leader in managed multi-cloud solutions.
- In October 2023, technology services provider Logicalis launched an Intelligent Connectivity suite that includes solutions such as SASE, SSE, SD-WAN, and Private 5G powered by Cisco Systems, Inc. This will enable Logicalis customers to access digitally managed services developed using Cisco technology and supported by the Logicalis Digital Fabric Platform.
- In September 2023, communications & technology solution provider Cloud5 Communications launched its new managed services division. The division is designed to support the IT-related requirements & challenges in various markets, such as the hospitality industry, student housing, and senior living, among others. This division will assist consumers in efficiently managing IT operations, technology infrastructures, and security.
- In May 2023, Alfar Capital and Walter Capital Partners completed the acquisition of MSP Corp, a managed IT service provider in Canada. The MSP Corp would merge with Groupe Access, an MSP of IT and cybersecurity solutions. The acquisition would help company to deliver cutting-edge solutions and strengthen its position in Canada.
- In January 2023, Rackspace Technology, a multi-cloud technology solutions provider, launched Rackspace Technology Modern Operations, a managed service for public cloud for customers across Azure, AWS, and GCP. The service will provide benefits including 24x7x365 managed support, cloud expertise, cloud resiliency, and innovation with cloud services which help the company’s customers manage complex cloud environments.
Market Concentration & Characteristics
The France Managed Services market is moderately concentrated, with a mix of large global players and regional service providers competing for market share. Major global firms dominate the market, leveraging their extensive resources, technological capabilities, and global reach to offer comprehensive solutions across multiple industries. However, the market also features a growing number of regional players who focus on niche segments, providing specialized services tailored to the specific needs of businesses in France. These regional providers often emphasize personalized customer support, localized expertise, and cost-effective solutions, which are particularly attractive to small and medium-sized enterprises (SMEs).
The market characteristics reflect a trend toward digital transformation, with businesses increasingly relying on managed services for IT infrastructure management, cybersecurity, cloud solutions, and network services. The demand for services that incorporate advanced technologies such as automation, artificial intelligence, and machine learning is growing, as organizations seek to optimize operations, improve security, and reduce costs. Furthermore, the shift toward cloud adoption has intensified competition, as companies strive to offer scalable, flexible, and secure solutions to meet evolving business needs. This competitive landscape is pushing providers to continuously innovate and improve their service offerings to maintain their market position.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Deployment Type, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The France Managed Services market is expected to grow significantly, driven by increasing demand for digital transformation and cloud-based solutions.
- Businesses will continue to prioritize cybersecurity services due to rising cyber threats and regulatory compliance requirements.
- The adoption of automation and artificial intelligence in managed services will increase operational efficiency and reduce costs.
- There will be a shift towards hybrid and multi-cloud environments as businesses seek flexibility and scalability in their IT infrastructure.
- SMEs will increasingly outsource IT services to specialized providers, enhancing their agility and reducing operational complexities.
- Managed services will play a crucial role in supporting the remote work trend by providing secure, scalable, and efficient IT solutions.
- Companies will focus on offering end-to-end solutions, integrating multiple services such as IT infrastructure management, cloud solutions, and network services.
- The demand for data analytics and business intelligence solutions will grow, encouraging managed service providers to incorporate these technologies into their offerings.
- The market will see further consolidation, with larger providers acquiring smaller niche players to expand service portfolios and strengthen market position.
- Sustainability and energy efficiency will become important factors in the managed services offerings, as companies focus on reducing their environmental impact.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the France Managed Services market?
What factors are driving the growth of the France Managed Services market?
What are some challenges faced by the France Managed Services market?
Who are the major players in the France Managed Services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Managed Services Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 France Managed Services Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 13,730.87 million → 2032: USD 24,929.66 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Managed Services Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Managed Services Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Managed Services Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 France Managed Services Drivers
- 3.3 France Managed Services Restraints & Challenges
- 3.4 France Managed Services Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Managed Services Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Managed Services Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Managed Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Managed Services Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. France Managed Services Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to France Managed Services in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Managed Services Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 France Managed Services Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 France Managed Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Managed Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in France Managed Services
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. France Managed Services – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. France Managed Services – Priority Domestic Market 1
Chapter 10. France Managed Services – Priority Domestic Market 2
Chapter 11. France Managed Services – Priority Domestic Market 3
Chapter 12. France Managed Services – Priority Domestic Market 4
Chapter 13. France Managed Services Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
