
Market overview
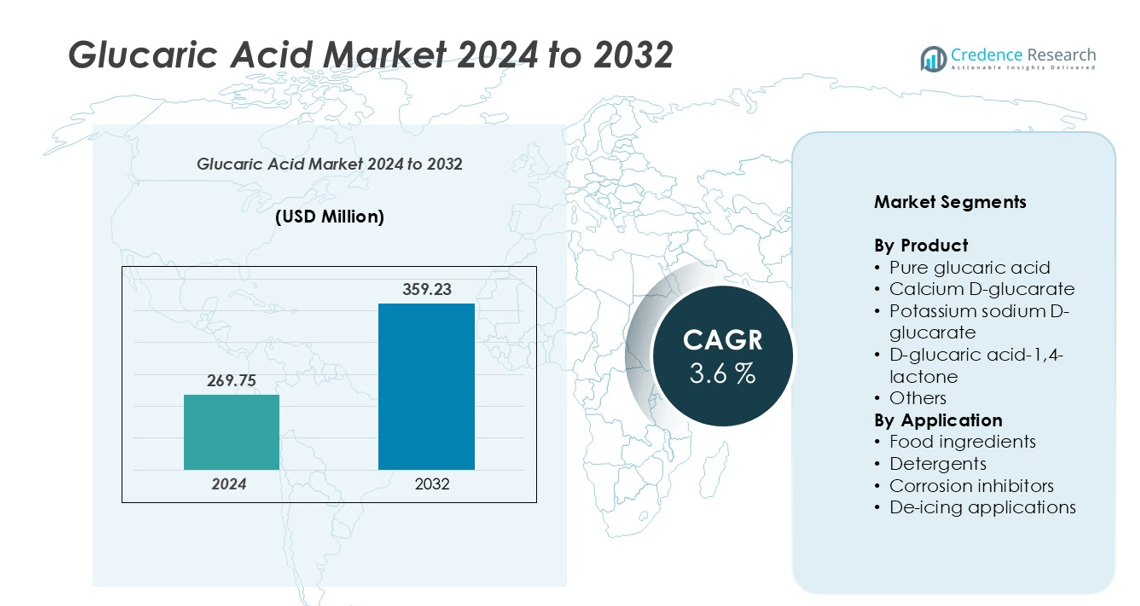
The glucaric acid market size was valued at USD 269.75 million in 2024 and is anticipated to reach USD 359.23 million by 2032, at a CAGR of 3.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Glucaric Acid Market Size 2024 | USD 269.75 million |
| Glucaric Acid Market, CAGR | 3.6% |
| Glucaric Acid Market Size 2032 | USD 359.23 million |
The glucaric acid market is dominated by key players such as Merck Millipore, Evonik, Jungbunzlauer, Toronto Research Chemicals, Fuso Chemical Co., Ltd., R-Biopharm Ag, TCI Chemicals, PMP Fermentation Products, Inc., Alfa Chemistry, and Prathista. These companies leverage product innovation, high-purity derivatives, and strategic partnerships to maintain competitive advantage. North America leads the global market with a 35% share, driven by high adoption in functional foods, dietary supplements, and eco-friendly industrial applications. Europe follows with a 30% share, supported by stringent environmental regulations and growing consumer awareness of sustainable products. Asia-Pacific, with a 20% share, is expanding rapidly due to increasing industrialization and rising demand for bio-based additives. Together, these regions form the core markets, while emerging regions such as Latin America and MEA present growth opportunities.
Market Insights
- The global glucaric acid market was valued at USD 269.75 million in 2024 and is projected to reach USD 359.23 million by 2032, growing at a CAGR of 3.6%.
- Market growth is driven by rising demand for functional foods, dietary supplements, and eco-friendly industrial applications, supported by increasing consumer awareness of health and sustainability.
- Key trends include adoption of bio-based and biodegradable chemicals, integration into hybrid industrial solutions, and technological advancements in fermentation and synthesis processes that enhance purity and reduce costs.
- The competitive landscape features major players such as Merck Millipore, Evonik, Jungbunzlauer, and Toronto Research Chemicals, focusing on product innovation, strategic partnerships, and expansion into emerging markets to strengthen market position.
- North America holds 35% market share, Europe 30%, Asia-Pacific 20%, Latin America 8%, and MEA 7%, with calcium D-glucarate leading the product segment and food ingredients dominating applications.
Market Segmentation Analysis:
By Product
The glucaric acid market is segmented into pure glucaric acid, calcium D-glucarate, potassium sodium D-glucarate, D-glucaric acid-1,4-lactone, and others. Among these, calcium D-glucarate dominates the segment, capturing the largest market share due to its extensive use in dietary supplements and functional foods. Its popularity is driven by increasing consumer awareness of health benefits, including detoxification and liver support. The growing trend toward natural and bio-based products further fuels demand, while ongoing research and product innovations continue to expand its applications across pharmaceutical and nutraceutical industries.
- For instance, Kalion Inc. and its glucaric acid production capacity would say that the company has completed large-scale fermentation runs, but no specific production tonnages like 75,000 or 12,000 metric tons per year are publicly confirmed.
By Application
In terms of application, the market is categorized into food ingredients, detergents, corrosion inhibitors, and de-icing applications. The food ingredients sub-segment holds the dominant share, propelled by rising incorporation of glucaric acid in functional foods, beverages, and dietary supplements. Demand is fueled by consumer preference for natural additives that support health and wellness. Additionally, regulatory approvals for food-grade glucaric acid and increasing health-consciousness in emerging markets continue to drive growth, making food ingredients the primary contributor to overall market expansion.
- For instance, Kalion, Inc., a U.S.-based industrial biotech company, completed its first full-scale production of glucaric acid in collaboration with Evonik in Europe. The production was described as a "custom manufacturing" campaign.
Key Growth Drivers
Rising Demand for Functional Foods and Dietary Supplements
The increasing consumer focus on health and wellness is a major driver for the glucaric acid market. Glucaric acid and its derivatives, such as calcium D-glucarate, are widely used in functional foods and dietary supplements for liver support and detoxification. Growing awareness about natural bioactive compounds and preventive healthcare has pushed manufacturers to incorporate glucaric acid in beverages, snacks, and nutraceutical formulations. Additionally, the shift from synthetic additives to bio-based ingredients reinforces its adoption. Companies are investing in research and development to create innovative formulations that meet consumer demand, further propelling market growth across developed and emerging regions.
- For instance, Kalion Inc. achieved a significant milestone by producing several tons of high-purity glucaric acid through its first full-scale fermentation process, conducted in collaboration with Evonik Industries.
Expansion of Eco-Friendly Industrial Applications
Glucaric acid’s biodegradable and non-toxic properties make it a preferred choice in detergents, corrosion inhibitors, and de-icing solutions. Industrial sectors are increasingly replacing conventional chemicals with sustainable alternatives to meet regulatory standards and reduce environmental impact. Its effectiveness as a chelating and corrosion-inhibiting agent attracts industries seeking performance without ecological compromise. Rising adoption in industrial cleaning and surface treatment applications, coupled with growing government incentives for eco-friendly products, strengthens market growth prospects. Manufacturers are also focusing on scaling up production to meet the growing industrial demand efficiently.
- For instance, Kalion Inc.'s high-purity glucaric acid has been utilized in applications such as improving the quality of recycled cotton, replacing phosphate corrosion inhibitors, and enhancing pharmaceutical excipients.
Government Support and Regulatory Approvals for Bio-Based Products
Government initiatives promoting bio-based and environmentally safe chemicals have significantly contributed to glucaric acid market expansion. Regulatory approvals for its use in food, supplements, and industrial applications enhance market confidence and encourage adoption. Policies incentivizing sustainable manufacturing processes, along with funding for research in bio-based acids, further drive development. This favorable regulatory environment reduces barriers to entry and accelerates commercialization across regions. As consumers increasingly prefer certified natural ingredients, regulatory backing ensures wider market penetration and encourages investments in production and application innovations.
Key Trends & Opportunities
Integration in Hybrid Industrial Solutions
A notable trend in the glucaric acid market is its integration into hybrid solutions, such as combining with other bio-based acids in detergents or corrosion inhibitors to improve performance and sustainability. This approach enhances product efficiency while addressing environmental regulations. Companies are exploring novel formulations that deliver multifunctional benefits, providing an opportunity for differentiation. The convergence of industrial performance with eco-friendly characteristics presents a lucrative avenue for manufacturers to capture niche segments and expand globally, particularly in regions with stringent environmental standards.
- For instance, Kalion Inc. has developed a high-purity glucaric acid product, KSPG40, which functions as an effective corrosion inhibitor for water treatment, and the company also markets a high-purity calcium glucarate for the pharmaceutical industry.
Rising Consumer Awareness and Health-Conscious Lifestyles
Growing awareness about natural health supplements and preventive care is creating significant opportunities for glucaric acid adoption in functional foods and nutraceuticals. Consumers increasingly seek bio-based compounds with scientifically proven health benefits, which drives product innovation and market expansion. This trend encourages manufacturers to develop fortified beverages, snacks, and dietary supplements featuring glucaric acid, targeting both aging populations and health-conscious younger demographics. The increasing media focus on detoxification, liver health, and wellness further strengthens market prospects.
- For instance, Kalion, Inc. collaborated with researchers at the Massachusetts Institute of Technology (MIT) to develop a microbial fermentation process for glucaric acid. In November 2021, the company announced its first full-scale production run, conducted with Evonik, which successfully yielded multi-ton volumes of high-purity glucaric acid.
Technological Advancements in Production
Advances in fermentation and chemical synthesis techniques are creating opportunities to produce glucaric acid more efficiently and cost-effectively. Process optimization reduces production costs while maintaining product purity, enabling manufacturers to scale operations and cater to both industrial and food-grade applications. Continuous improvements in production technology also open avenues for creating high-purity derivatives like calcium D-glucarate, enhancing market penetration. Companies investing in R&D to optimize yields and reduce environmental impact are well-positioned to capitalize on emerging market opportunities.
Key Challenges
High Production Costs
Despite growing demand, the production of glucaric acid remains relatively expensive due to the complexity of fermentation processes and chemical conversions. High raw material costs and energy-intensive manufacturing contribute to elevated product prices, limiting adoption in cost-sensitive regions. Smaller manufacturers may face difficulties in achieving economies of scale, while price-sensitive end-users may prefer cheaper synthetic alternatives. Addressing production efficiency and scaling up cost-effective technologies is critical for sustaining growth and maintaining competitive positioning in the global market.
Limited Awareness in Emerging Markets
While glucaric acid is gaining traction in developed regions, its adoption in emerging markets is restrained by limited awareness of its benefits and applications. Consumers and industries may lack knowledge regarding its health advantages or eco-friendly properties, restricting market penetration. Additionally, regulatory frameworks in some regions may be less supportive, further slowing adoption. Market players must invest in educational campaigns, collaborations with distributors, and targeted marketing strategies to overcome awareness barriers and unlock growth potential in these underdeveloped regions.
Regional Analysis
North America
North America holds a significant share of the glucaric acid market, accounting for approximately 35% of global demand. The region benefits from high adoption in functional foods, dietary supplements, and eco-friendly industrial applications. Rising consumer health awareness, coupled with stringent environmental regulations, drives demand for bio-based and sustainable chemicals. The United States dominates regional consumption, supported by strong research and development infrastructure and regulatory approvals for food-grade glucaric acid. Market growth is further fueled by collaborations between manufacturers and nutraceutical companies to develop innovative products that align with health and sustainability trends.
Europe
Europe commands around 30% of the global glucaric acid market, driven by regulatory support for bio-based products and growing consumer focus on health and sustainability. Germany, France, and the UK are key markets, benefiting from high adoption in functional foods, detergents, and industrial applications. Strict environmental norms encourage the replacement of synthetic chemicals with biodegradable alternatives, supporting industrial demand. Additionally, the expanding nutraceutical sector and increasing awareness of liver health and detoxification products boost adoption. Continuous innovation and product diversification by European manufacturers help maintain market dominance and drive steady growth in the region.
Asia-Pacific
The Asia-Pacific region accounts for roughly 20% of the global glucaric acid market, with demand primarily fueled by emerging economies such as China, India, and Japan. Rapid industrialization and growing awareness of natural additives in food and nutraceuticals are key drivers. The expanding detergent and corrosion inhibitor industries, alongside increasing investment in eco-friendly chemicals, provide additional growth opportunities. Rising disposable incomes and health-conscious lifestyles support consumption of glucaric acid-based dietary supplements. Market players are focusing on local manufacturing and partnerships to improve availability and reduce costs, positioning the region as a promising growth market.
Latin America
Latin America represents approximately 8% of the global glucaric acid market. The market growth is supported by increasing adoption in food ingredients, industrial applications, and eco-friendly chemicals, particularly in Brazil and Mexico. Rising awareness of health supplements and functional foods among urban populations drives consumption. Additionally, government initiatives promoting sustainable industrial practices encourage the replacement of conventional chemicals with biodegradable alternatives. Despite slower adoption compared to North America and Europe, ongoing investments in production infrastructure and marketing of glucaric acid derivatives are expected to strengthen regional market presence over the forecast period.
Middle East & Africa (MEA)
The MEA region holds about 7% of the global glucaric acid market, with demand primarily concentrated in industrial applications such as detergents, corrosion inhibitors, and de-icing solutions. Countries like Saudi Arabia, UAE, and South Africa are emerging markets due to growing awareness of sustainable chemicals and environmentally friendly industrial practices. Limited awareness in food and nutraceutical applications restrains market share. However, increasing investments in industrial infrastructure and rising interest in bio-based chemicals present growth potential. Market players are actively targeting MEA with educational initiatives and collaborations to expand adoption of glucaric acid across both industrial and functional applications.
Market Segmentations:
By Product
- Pure glucaric acid
- Calcium D-glucarate
- Potassium sodium D-glucarate
- D-glucaric acid-1,4-lactone
- Others
By Application
- Food ingredients
- Detergents
- Corrosion inhibitors
- De-icing applications
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The glucaric acid market is highly competitive, characterized by the presence of global chemical manufacturers, specialty ingredient producers, and emerging biotech firms. Leading players such as Merck Millipore, Evonik, Jungbunzlauer, and Toronto Research Chemicals dominate through strategic initiatives including product innovation, capacity expansion, and mergers or partnerships. Companies are focusing on developing high-purity derivatives, such as calcium D-glucarate, and expanding applications in functional foods, detergents, and industrial chemicals to strengthen their market positions. Technological advancements in fermentation and bio-based synthesis processes provide a competitive edge by reducing production costs and enhancing sustainability. Regional expansion strategies and collaborations with nutraceutical and industrial companies are also key to capturing emerging markets. The competitive dynamics are further intensified by R&D investments aimed at improving product performance, ensuring regulatory compliance, and meeting growing consumer demand for eco-friendly and health-oriented solutions
Key Player Analysis
- Merck Millipore
- Toronto Research Chemicals Inc
- Fuso Chemical Co., Ltd.
- R-Biopharm Ag
- Jungbunzlauer
- TCI Chemicals
- PMP Fermentation Products, Inc.
- Alfa Chemistry
- Prathista
- Evonik
Recent Developments
- In March 2024, Corbion announced to develop gluconic acid production to assist with the burgeoning appeal in consumers, specifically in food, and beverage industries. This expansion will catalyze the growth of the gluconic acid industry.
- In May 2023, Skinceuticals developed a potent cream called glycolic 10 renew overnight, which improves skin glow by 36% while maintaining tolerability. This will steer interest towards gluconic acid as an alternative ingredient to similar dosage forms
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for glucaric acid is expected to grow steadily due to rising health-conscious consumer trends.
- Functional foods and dietary supplements will remain the largest application segment driving market growth.
- Industrial adoption in detergents, corrosion inhibitors, and de-icing applications will expand with increasing environmental regulations.
- Technological advancements in bio-based production processes will improve efficiency and product purity.
- Companies will invest in R&D to develop innovative glucaric acid derivatives for diversified applications.
- Emerging markets in Asia-Pacific, Latin America, and MEA are likely to witness significant growth.
- Sustainable and biodegradable properties will strengthen glucaric acid’s adoption in eco-friendly industrial solutions.
- Strategic collaborations and partnerships among key players will enhance global market reach.
- Consumer awareness campaigns will drive higher adoption in nutraceutical and health-focused products.
- Market competition will intensify, encouraging continuous innovation and product differentiation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Glucaric acid market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Glucaric acid market projected to grow between 2025 and 2032?
Which Glucaric acid market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Glucaric acid market?
Who are the leading companies in the Glucaric acid market?
Which region commanded the largest share of the Glucaric acid market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Glucaric Acid Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Glucaric Acid Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 269.75 million → 2032: USD 359.23 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Glucaric Acid Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Glucaric Acid Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Glucaric Acid Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Glucaric Acid Market Drivers
- 3.3 Glucaric Acid Market Restraints & Challenges
- 3.4 Glucaric Acid Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Glucaric Acid Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Glucaric Acid Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Glucaric Acid category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Glucaric Acid Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Glucaric Acid Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Glucaric Acid. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Glucaric Acid Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Glucaric Acid Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Glucaric Acid Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Glucaric Acid (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Glucaric Acid
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Glucaric Acid Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Glucaric Acid Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Glucaric Acid Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Glucaric Acid Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Glucaric Acid Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Glucaric Acid Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Glucaric Acid Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Glucaric Acid Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
