
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
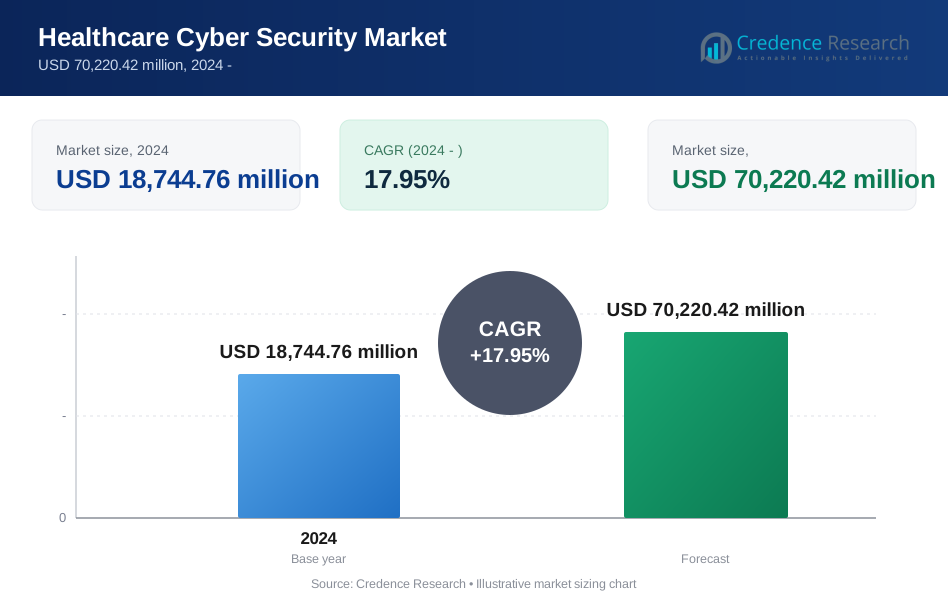
| Healthcare Cybersecurity Market Size 2024 | USD 18744.76 Million |
| Healthcare Cybersecurity Market, CAGR | 17.95% |
| Healthcare Cybersecurity Market Size 2032 | USD 70220.42 Million |
Market Overview:
Healthcare Cybersecurity Market size was valued at USD 18744.76 million in 2024 and is anticipated to reach USD 70220.42 million by 2032, at a CAGR of 17.95% during the forecast period (2024-2032).
Key drivers of the healthcare cybersecurity market include the increasing digitization of healthcare systems, such as Electronic Health Records (EHR), telemedicine, and IoT devices, which have expanded the attack surface for potential cyber threats. As healthcare organizations rely more on digital platforms for patient care and management, the risk of cyberattacks also increases, further driving the demand for cybersecurity solutions. Additionally, the rising frequency and sophistication of cyberattacks, including ransomware and data breaches, have led to heightened awareness and investments in robust security frameworks. Healthcare data, being highly sensitive, has become a prime target for cybercriminals, prompting organizations to prioritize their security infrastructure. Regulatory initiatives, such as the Health Insurance Portability and Accountability Act (HIPAA) and the General Data Protection Regulation (GDPR), also drive market growth by mandating healthcare organizations to comply with stringent data protection standards. Compliance with these regulations is crucial to avoid penalties and protect patient information.
Regionally, North America dominates the healthcare cybersecurity market, accounting for a significant share due to the presence of major healthcare providers, increased cyber threats, and strict regulations in the United States. The region has experienced a series of high-profile cyberattacks, which has led to a significant focus on strengthening cybersecurity frameworks. The Asia Pacific region is expected to experience the fastest growth during the forecast period, driven by increasing healthcare digitization, rising cybercrime incidents, and investments in cybersecurity infrastructure. Governments and private entities in the region are increasingly recognizing the importance of securing healthcare data and are investing in advanced cybersecurity technologies. Europe follows closely, driven by the adoption of cybersecurity technologies across both public and private healthcare sectors, as well as compliance with GDPR data protection regulations. Additionally, Europe’s emphasis on patient privacy and the growing threat landscape continue to accelerate the demand for cybersecurity solutions.
Market Insights:
- The market was valued at USD 18,744.76 million in 2024 and is expected to reach USD 70,220.42 million by 2032, driven by rising digital adoption in healthcare.
- Increasing use of Electronic Health Records (EHR), telemedicine, and IoT devices is expanding the potential attack surface for cyber threats.
- Cyberattacks like ransomware and data breaches are growing in frequency and complexity, making cybersecurity a top priority for healthcare organizations.
- Regulatory frameworks such as HIPAA and GDPR are enforcing strict data protection standards, pushing organizations to invest in robust security solutions.
- Complex IT infrastructure and reliance on legacy systems pose serious vulnerabilities, making integration with modern security tools challenging.
- Shortage of skilled cybersecurity professionals and limited resources among small healthcare providers hinder effective threat management.
- North America leads the market due to strong regulations and high cybersecurity investments, while Asia Pacific is the fastest-growing region, fueled by rapid digitization and increasing cybercrime.
Market Drivers:
Increasing Digitization of Healthcare Systems
The healthcare sector has increasingly adopted digital technologies such as Electronic Health Records (EHR), telemedicine, and Internet of Things (IoT) devices, enhancing both operational efficiency and patient care. However, the digital transformation has also expanded the potential attack surface for cyber threats, making healthcare organizations more vulnerable to cyberattacks. With sensitive patient data being digitized and stored electronically, the risk of data breaches, identity theft, and system hacks has significantly increased. As healthcare systems become more interconnected, the need for robust cybersecurity solutions has grown to protect valuable data and maintain the integrity of healthcare services.
Rise in Cyberattacks Targeting Healthcare Organizations
The healthcare sector has become a prime target for cybercriminals due to the high value of personal health information (PHI) and the critical nature of healthcare services. For instance, MedSecure Health Systems implemented a dedicated Cybersecurity Incident Response Team (CIRT) and advanced machine learning algorithms to detect anomalies in network traffic and prevent data breaches. Cyberattacks, such as ransomware, data breaches, and Distributed Denial of Service (DDoS) attacks, have become more frequent and sophisticated, resulting in significant financial and reputational damage. In particular, ransomware attacks on hospitals and healthcare institutions have skyrocketed, leading to disruptions in patient care and, in some cases, even the loss of life. These incidents highlight the urgency for healthcare organizations to adopt comprehensive cybersecurity frameworks to safeguard patient data and ensure the continuity of care.
Regulatory Compliance and Data Protection Standards
Government regulations and compliance frameworks, such as the Health Insurance Portability and Accountability Act (HIPAA) in the U.S. and the General Data Protection Regulation (GDPR) in Europe, are key drivers of the healthcare cybersecurity market. For instance, Cleveland Clinic has successfully implemented advanced cybersecurity solutions to comply with HIPAA regulations, ensuring robust encryption and secure access controls for patient data. These regulations mandate that healthcare organizations implement strict data protection protocols to safeguard sensitive patient information. Non-compliance with these regulations can result in hefty fines, legal consequences, and a loss of patient trust. Consequently, healthcare providers are increasingly investing in advanced cybersecurity solutions to meet these regulatory requirements and mitigate the risks of non-compliance, ensuring that they meet both legal and ethical obligations.
Growing Awareness and Need for Cybersecurity Investment
As cyber threats continue to escalate, awareness of the importance of healthcare cybersecurity has grown among healthcare providers, policymakers, and patients. Healthcare organizations are increasingly recognizing that investing in cybersecurity is not merely a cost but a critical necessity to protect both patient data and operational infrastructure. As a result, there has been a marked increase in the allocation of resources to cybersecurity technologies, including encryption, multi-factor authentication, and intrusion detection systems. The growing recognition of cybersecurity as a strategic priority has driven healthcare organizations to adopt proactive security measures to prevent cyber incidents before they occur. This shift toward prioritizing cybersecurity is fueling the demand for innovative cybersecurity solutions within the healthcare sector.
Market Trends:
Integration of Advanced Technologies
Healthcare organizations are increasingly adopting Artificial Intelligence (AI) and Machine Learning (ML) to strengthen their cybersecurity frameworks. These technologies enable predictive analytics, helping to identify vulnerabilities before they are exploited. AI and ML tools automate threat detection and response, improving efficiency and response times. However, the implementation of these technologies also brings new challenges. While they offer enhanced security, they can also introduce additional risks if not properly managed or integrated with existing systems.
Rise in Cyberattack Sophistication
The sophistication and frequency of cyberattacks targeting the healthcare sector have significantly increased. For instance, MedSecure Health Systems, a Chicago-based healthcare provider operating over 20 hospitals, successfully thwarted multiple high-risk cyberattacks by implementing advanced machine learning algorithms to detect anomalies in network traffic and upgrading its data encryption methods. Ransomware attacks, in particular, have become more prevalent, with cybercriminals exploiting outdated systems or vulnerabilities in third-party vendors. These attacks can lead to severe disruptions in patient care, financial losses, and damage to reputations. The healthcare sector's reliance on legacy systems and the growing interconnectivity of devices only add to the vulnerability, underscoring the need for stronger and more resilient cybersecurity strategies.
Regulatory Developments and Compliance Challenges
In response to growing cybersecurity threats, regulatory bodies are tightening their oversight and mandating stricter compliance measures for healthcare organizations. For instance, the U.S. Department of Health and Human Services (HHS) is updating the HIPAA Security Rule to include new cybersecurity requirements such as multifactor authentication and encryption, aiming to enhance patient data protection. Regulations such as the Health Insurance Portability and Accountability Act (HIPAA) in the U.S. are evolving to ensure better data protection, with a focus on enforcing practices like multifactor authentication and encryption. While these regulations are crucial for safeguarding patient data, they also present significant challenges for smaller healthcare providers, who may struggle with the financial and resource demands required to meet these stringent security standards.
Expansion of Managed Detection and Response (MDR) Services
As cyber threats become increasingly complex, more healthcare organizations are turning to Managed Detection and Response (MDR) services. MDR providers offer continuous monitoring, threat detection, and rapid response, which help healthcare entities manage risks more effectively. This trend reflects a broader shift toward outsourcing cybersecurity functions to specialized providers, allowing organizations to focus on patient care while benefiting from expert-driven, round-the-clock protection. The increasing adoption of MDR services highlights the growing recognition of the need for comprehensive, proactive security measures in the healthcare sector.
Market Challenges Analysis:
Complex IT Infrastructure and Legacy Systems
One of the primary challenges facing the healthcare cybersecurity market is the complexity of IT infrastructure combined with the continued reliance on outdated legacy systems. For instance, Mayo Clinic successfully transitioned from legacy systems like Cerner and GE solutions to its $1.5 billion Epic electronic health record (EHR) system across multiple locations, including Florida, Arizona, and Minnesota. Many healthcare organizations operate a mix of modern digital platforms alongside older systems that lack the capability to support advanced security protocols. This hybrid environment creates vulnerabilities that are difficult to manage and secure uniformly. Legacy systems often do not receive regular updates or patches, making them susceptible to breaches. Additionally, integrating new technologies with older systems can result in configuration errors, interoperability issues, and security gaps. These challenges significantly hinder the ability of healthcare institutions to implement a comprehensive cybersecurity strategy, thereby increasing their exposure to cyber threats. As cybercriminals increasingly target these weak points, legacy systems become a major liability in maintaining healthcare data integrity.
Resource Constraints and Cybersecurity Talent Shortage
Another critical challenge is the limited availability of skilled cybersecurity professionals within the healthcare sector. Many organizations, particularly small and mid-sized providers, struggle to attract and retain qualified talent due to budget constraints and competition from other industries. As cyber threats grow in complexity and frequency, the demand for specialized knowledge in areas like threat intelligence, incident response, and data encryption continues to outpace supply. In addition, budgetary limitations often restrict the implementation of advanced security solutions and staff training programs. This imbalance between threat readiness and resource availability leaves healthcare providers vulnerable to data breaches and operational disruptions. The widening gap between cybersecurity demand and available expertise places immense pressure on existing teams, increasing the risk of oversight and delayed response to threats.
Market Opportunities:
The healthcare cybersecurity market presents significant growth opportunities driven by the rapid digital transformation of the global healthcare sector. As hospitals, clinics, and other medical facilities continue to adopt Electronic Health Records (EHR), telemedicine, wearable health devices, and Internet of Medical Things (IoMT), the volume of sensitive data generated and transmitted is expanding exponentially. This growing digital ecosystem creates a strong demand for advanced cybersecurity solutions that can protect patient data, ensure regulatory compliance, and maintain operational integrity. The increasing awareness among healthcare providers of the financial and reputational risks associated with data breaches is also prompting proactive investment in cybersecurity infrastructure. Additionally, the rise in value-based care models and cloud-based healthcare platforms offers vendors an opportunity to deliver scalable, cloud-native security solutions tailored to evolving industry needs.
Emerging markets, particularly in Asia Pacific and Latin America, offer untapped potential for cybersecurity solution providers. These regions are witnessing accelerated healthcare digitization, supported by government initiatives, increased funding, and a rising focus on healthcare quality and data protection. As cyber threats grow more sophisticated, there is a clear opportunity for vendors to introduce next-generation security technologies such as AI-driven threat detection, zero-trust architecture, and blockchain-based data management. Furthermore, the growing demand for Managed Security Services (MSS) and cyber insurance in the healthcare domain is expanding the market scope for both established players and new entrants. Companies that can provide cost-effective, compliant, and adaptive cybersecurity solutions will be well-positioned to capitalize on this growing demand across both developed and developing healthcare markets.
Market Segmentation Analysis:
By Type
The healthcare cybersecurity market is segmented into solutions and services. Solutions, including antivirus, intrusion detection systems, encryption, and risk and compliance management, dominate the segment due to the increasing need to safeguard sensitive patient data. Services, such as managed security and consulting, are also gaining traction as healthcare organizations seek expert guidance and 24/7 monitoring.
By Organization Size
Based on organization size, the market is divided into large enterprises and small & medium-sized enterprises (SMEs). Large enterprises lead the market due to their greater IT infrastructure and higher cybersecurity budgets. However, SMEs are witnessing rapid growth as they increasingly adopt digital healthcare tools and face growing cyber threats, prompting investment in cost-effective security solutions.
By Threat
The threat landscape includes malware, ransomware, phishing, DDoS attacks, and advanced persistent threats. Ransomware remains the most prevalent threat, causing significant disruption and financial losses. Healthcare organizations are prioritizing protection against these threats through integrated security frameworks.
By End-User
The key end-users of healthcare cybersecurity solutions include hospitals, diagnostic centers, health insurance companies, and clinics. Hospitals account for the largest market share due to their extensive data volume and critical infrastructure. Diagnostic centers and insurance firms are also investing heavily in cybersecurity to maintain patient trust and regulatory compliance.
Segmentations:
By Type:- Solutions
- Services
- Small & Medium-Sized Enterprises (SMEs)
- Large Enterprises
- Malware
- Ransomware
- Phishing
- Distributed Denial of Service (DDoS) Attacks
- Advanced Persistent Threats (APTs)
- Hospitals
- Clinics
- Diagnostic Centers
- Health Insurance Companies
- Other Healthcare Institutions
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
North America holds the largest share of the global healthcare cybersecurity market, accounting for 46% of total market revenue. This leadership is supported by advanced healthcare infrastructure, high digital adoption, and strict regulatory mandates such as HIPAA. The United States leads the region in both technology adoption and cybersecurity investments. Rising incidents of data breaches and ransomware attacks targeting healthcare providers have pushed organizations to implement robust security frameworks. Additionally, increasing collaborations between healthcare institutions and cybersecurity vendors are fostering innovation in threat detection and prevention solutions. The region benefits from a well-established ecosystem of cybersecurity providers and government initiatives promoting health data protection. A growing trend in the region is the deployment of AI-driven cybersecurity tools to detect real-time threats across healthcare networks.
Europe
Europe accounts for 28% of the global healthcare cybersecurity market, making it the second-largest regional contributor. The region's growth is driven by stringent data protection regulations such as the General Data Protection Regulation (GDPR), which enforce high standards for data privacy and security. Countries including Germany, the United Kingdom, and France are actively adopting advanced cybersecurity tools to strengthen their healthcare systems. The increasing use of digital health services and cross-border data exchange within the EU is accelerating the demand for secure infrastructure. European healthcare providers are integrating AI-powered and cloud-based security solutions to counter evolving threats and ensure compliance with regional laws. The rising use of mobile health apps and remote patient monitoring tools in Europe further increases the need for secure digital environments.
Asia Pacific
Asia Pacific holds a 17% share of the global healthcare cybersecurity market and is recognized as the fastest-growing regional segment. The region's growth is driven by rapid digital transformation, expanding healthcare infrastructure, and increasing adoption of Electronic Health Records (EHR). Nations such as China, India, Japan, and South Korea are investing heavily in cybersecurity to modernize their healthcare systems. Growing awareness among healthcare providers regarding data protection and the rise in cyberattack incidents have increased demand for robust security frameworks. Government-led digital health initiatives and technology partnerships are further accelerating cybersecurity development. A surge in cloud-based healthcare platforms and telemedicine adoption across Asia Pacific is prompting providers to implement advanced data security solutions.
Key Player Analysis:
- IBM
- Marubeni Information Systems Co., Ltd.
- Intel Corporation
- Cisco Systems, Inc.
- AO Kaspersky Lab
- Symantec Corporation
- Trend Micro Incorporated
- Medigate (Claroty)
- Lockheed Martin Corporation
- McAfee, LLC.
- Northrop Grumman
- Imperva; Fortinet, Inc.
Competitive Analysis:
The healthcare cybersecurity market is highly competitive, with both established technology companies and emerging cybersecurity firms actively expanding their presence. Key players include IBM Corporation, Cisco Systems, Palo Alto Networks, Fortinet, and McAfee, which offer comprehensive security solutions tailored to healthcare needs. These companies focus on product innovation, strategic partnerships, and mergers to enhance their market position. Additionally, specialized firms like Claroty and Medigate are gaining traction by offering sector-specific solutions, particularly for securing medical devices and IoT infrastructure. Competitive dynamics are further intensified by increasing demand for AI-driven threat detection, cloud security, and managed security services. Companies are prioritizing scalability, regulatory compliance, and real-time threat intelligence to differentiate their offerings. As the threat landscape evolves, continuous innovation and customized solutions are essential for maintaining a competitive edge in this fast-growing and security-critical market.
Recent Developments:
- In March 2024, Claroty introduced its Advanced Anomaly Threat Detection Module for the Medigate Platform, aiming to strengthen cybersecurity across healthcare organizations. This new module delivers clinically-aware threat detection capabilities designed to identify and prioritize risks associated with connected medical devices, IoT systems, and building management infrastructure within healthcare environments.
- In November 2023, Marubeni Information Systems Co., Ltd. expanded its cybersecurity offerings by collaborating with healthcare organizations to address increasing ransomware attacks and enhance compliance with regulations like HIPAA and GDPR.
- In January 2024, McAfee was recognized by AV-Comparatives for its real-world protection and system performance, showcasing its leadership in online security solutions.
Market Concentration & Characteristics:
The healthcare cybersecurity market exhibits moderate to high market concentration, with a mix of global technology leaders and specialized cybersecurity firms dominating the landscape. Major players such as IBM, Cisco Systems, and Palo Alto Networks hold significant market share due to their broad product portfolios, advanced technologies, and strong global presence. At the same time, niche firms focusing on healthcare-specific solutions—particularly in securing medical devices and IoT systems—are gaining visibility and influence. The market is characterized by rapid technological advancements, regulatory-driven demand, and a rising need for tailored cybersecurity frameworks. Cloud integration, AI-powered threat detection, and managed security services are shaping product innovation across the industry. Vendor differentiation is largely driven by scalability, compliance capabilities, and real-time threat intelligence. As healthcare organizations prioritize data protection and digital resilience, the market continues to evolve with an emphasis on proactive, adaptive, and industry-specific cybersecurity solutions.
Report Coverage:
The research report offers an in-depth analysis based on type, organization size, threat, by end-user and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Healthcare organizations will continue to invest in advanced cybersecurity solutions to address increasing threats to patient data and critical infrastructure.
- The demand for AI- and ML-driven threat detection systems will rise, enabling faster identification and response to emerging cyber threats.
- Cloud-based security solutions will gain significant traction as healthcare providers expand their use of remote care and digital health platforms.
- The integration of zero-trust architecture will become a priority, ensuring secure access across devices, users, and networks.
- Governments and regulatory bodies will enforce stricter compliance standards, pushing healthcare providers to strengthen their cybersecurity frameworks.
- The proliferation of connected medical devices and Internet of Medical Things (IoMT) will drive demand for specialized security solutions.
- Cybersecurity awareness and training programs will increase across healthcare institutions to reduce human error-related breaches.
- Partnerships between healthcare providers and cybersecurity firms will expand, fostering tailored solutions and real-time threat intelligence sharing.
- Small and mid-sized healthcare organizations will adopt cost-effective managed security services to address resource limitations.
- Ongoing technological advancements will continue to reshape the market, with emphasis on automation, threat analytics, and adaptive security systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Healthcare Cybersecurity Market?
What factors are driving the growth of the Healthcare Cybersecurity Market?
What are the key segments within the Healthcare Cybersecurity Market?
What are some challenges faced by the Healthcare Cybersecurity Market?
Who are the major players in the Healthcare Cybersecurity Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Healthcare Cyber Security Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Healthcare Cyber Security Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 18,744.76 million → forecast year: USD 70,220.42 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Healthcare Cyber Security Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Healthcare Cyber Security Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Healthcare Cyber Security Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Healthcare Cyber Security Market Drivers
- 3.3 Healthcare Cyber Security Market Restraints & Challenges
- 3.4 Healthcare Cyber Security Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Healthcare Cyber Security Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Healthcare Cyber Security Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Healthcare Cyber Security category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Healthcare Cyber Security Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Healthcare Cyber Security Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Healthcare Cyber Security market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Healthcare Cyber Security Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Healthcare Cyber Security Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Healthcare Cyber Security Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Healthcare Cyber Security (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Healthcare Cyber Security Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Healthcare Cyber Security Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Healthcare Cyber Security Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Healthcare Cyber Security Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Healthcare Cyber Security Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Healthcare Cyber Security Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Healthcare Cyber Security Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Healthcare Cyber Security Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Healthcare Cyber Security Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
