
Market Overview
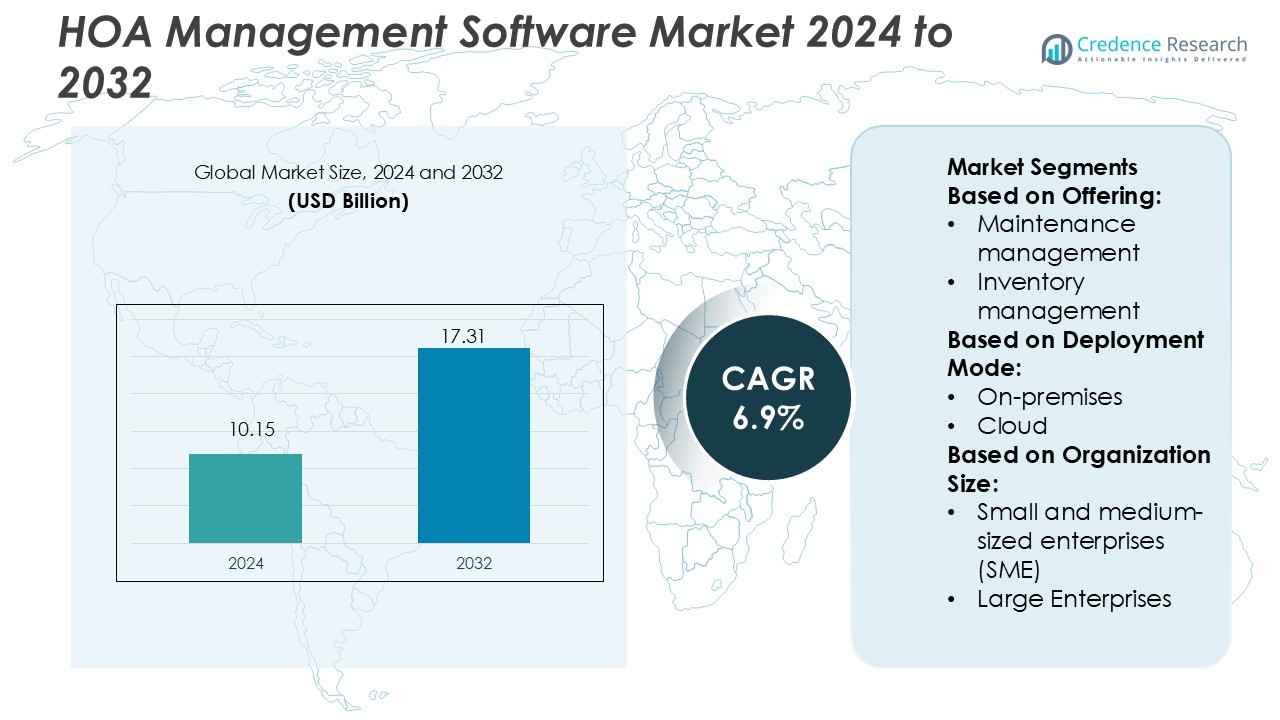
HOA Management Software Market size was valued USD 10.15 billion in 2024 and is anticipated to reach USD 17.31 billion by 2032, at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| HOA Management Software Market Size 2024 | USD 10.15 Billion |
| HOA Management Software Market, CAGR | 6.9% |
| HOA Management Software Market Size 2032 | USD 17.31 Billion |
The HOA Management Software Market features key players such as Block, Inc., Adobe Inc., SAP, Oracle, McAfee Corporation, VMware Inc., Microsoft, IBM Corporation, NortonLifeLock Inc., and Intuit Inc. These companies leverage robust technology portfolios to deliver end‑to‑end community management platforms encompassing billing, resident portals, and cloud‑based services. The leading region is North America, which holds approximately 43.0% of the global market share, driven by a high density of home owners associations, advanced infrastructure, and widespread digital adoption.
Market Insights
- The HOA Management Software Market was valued at USD 10.15 billion in 2024 and is anticipated to reach USD 17.31 billion by 2032, growing at a CAGR of 6.9% during the forecast period.
- Increasing demand for automated billing, maintenance tracking, and resident communication tools is driving market growth, particularly in North America.
- The market is trending toward cloud-based platforms, with modular and subscription models offering flexibility to associations of various sizes.
- The competitive landscape is dominated by players such as Block, Inc., Adobe Inc., and Oracle, who lead with advanced software solutions that cater to diverse community management needs.
- North America leads the market with approximately 43.0% share, followed by Europe and Asia-Pacific, driven by rapid urbanization and increasing adoption of smart community management solutions.
Market Segmentation Analysis:
By Offering
In the offering segment for HOA management software, the software sub‑segment dominates with an estimated 72 % share. This strong position is driven by widespread demand for automated modules such as asset tracking, maintenance management, inventory control, calibration workflows, and inspection management. Services such as consulting, implementation & integration, and support & maintenance complement the core software, yet they fill the remaining share. Customers prioritise integrated software platforms that can unify tracking of community assets and streamline inspections, making the software portion the key revenue driver in this market.
- For instance, WebTMS Limited provides a comprehensive IP management platform with automated docketing capabilities. Its Data Sync tool can access trademark data from over 180 jurisdictions, and the system includes features such as workflow management and automated updates from official registries.
By Deployment Mode
Among the deployment modes, on‑premises solutions currently hold a leading share of approximately 62 %. This dominance stems from associations’ preference for controlling data and maintaining infrastructure within their existing IT environment. On‑premises systems also benefit organisations with strict compliance or data sovereignty needs. Cloud deployments are gaining traction, but legacy preferences and custom integration requirements mean on‑premises remains the dominant choice for now.
- For instance, Oracle’s Cloud Infrastructure offers a unified set of 150+ cloud services in each region to support multi‑module deployment and integration.
By Organization Size
Large enterprises (i.e., associations managing over 1,000 units) lead the market in terms of uptake, commanding around 55 % of the total share. These organisations often require comprehensive modules and support for multiple community sites, which drives their adoption of full‑scale HOA management platforms. SMEs still represent a meaningful market, especially for simplified and modular solutions, but the bulk of revenue and complex implementations originate from large‑scale association groups.
Key Growth Drivers
Growing digital transformation in community associations
Homeowners associations (HOAs) are increasingly adopting digital platforms to replace manual processes. This shift is driven by the need for better billing, maintenance tracking, and resident communication. As many board members now prefer digital tools for managing these tasks, the demand for HOA management software is growing. More communities are moving away from spreadsheets and traditional methods, boosting the software market.
- For instance, VMware Inc. launched its Workspace ONE Intelligence suite-which aggregates and correlates data across users, apps, networks and devices-for a client base spanning more than 53,000 students at one district.
Expansion of planned residential communities and urbanisation
With the rapid growth of cities and the increase in residential developments, the demand for HOA management software is rising. Many new gated communities and apartment complexes are being built, and they need efficient systems to manage operations and resident services. This trend of urbanisation is driving more developers and property managers to adopt HOA software.
- For instance, Microsoft’s Azure IoT platform supports bidirectional communication for millions of connected devices and enables 10–20% savings in energy usage at enterprise campuses through its smart‑building solutions.
Cloud accessibility and scalability of software solutions
Cloud-based HOA software is becoming more popular because it is cost-effective and easy to scale. Smaller associations are finding it easier to adopt these systems because they don't need to invest in expensive infrastructure. The cloud model also allows easy updates and mobile access, making it more convenient for users, which is fueling the market’s growth.
Key Trends & Opportunities
Integration of mobile apps, AI and IoT for smarter community management
Many HOA software providers are now integrating mobile apps, AI, and IoT into their platforms. These technologies help improve communication with residents, automate maintenance requests, and track performance. This trend offers new opportunities for software providers to offer more advanced features that improve the overall community management experience.
- For instance, NortonLifeLock Inc. maintains a portfolio of over 1,000 U.S. and international patents underpinning its IoT‑enabled threat‑detection technology.
Shift toward modular and subscription‑based service delivery models
HOA software is moving towards modular and subscription-based models. This allows associations to choose the specific features they need, making the software more affordable and flexible. Smaller associations are especially drawn to these models because they lower the upfront costs and allow them to pay for only what they use.
- For instance, QuickBooks platform supports integrations across 100s of applications listed in the marketplace, enabling users to selectively add or remove modules based on need.
Emerging‑market penetration and retrofit potential in older associations
In regions like Asia-Pacific and Latin America, rapid urbanisation is driving the need for HOA management software. Many older associations are still using manual methods and outdated systems, creating an opportunity for vendors to offer software upgrades and cloud-based solutions. This trend presents a significant market opportunity for providers to tap into these underserved regions.
Key Challenges
Resistance to change and legacy‑system inertia
Many HOAs are slow to adopt new software due to a reluctance to move away from familiar manual methods. Board members may be hesitant to invest in new systems or worry about the learning curve involved. This resistance to change, particularly in smaller associations, slows the adoption of HOA management software.
Data security and privacy concerns in community platforms
As HOA software handles sensitive resident information, concerns about data security and privacy remain a major challenge. Many associations are cautious about storing personal and financial data online. Providers must ensure that their software is secure and complies with privacy regulations to gain the trust of users and encourage adoption.
Regional Analysis
North America
North America holds approximately 40% of the global HOA management software market share, supported by high digital adoption among associations and advanced infrastructure. The United States leads the region, where many community associations already use management platforms for billing, maintenance tracking, and resident portals. This strong foundation and willingness to invest in technology give the region a competitive edge. With mature market conditions, growth here remains steady, and vendors focus on feature enhancement and service innovation to capture incremental demand.
Europe
Europe commands about 30% of the market and benefits from regulatory focus on transparency and efficiency in homeowners associations. Countries such as the UK, Germany and France drive demand for platforms that meet GDPR compliance and integrate mobile access. Many European associations operate across borders or manage multilingual communities, prompting interest in scalable and customisable solutions. Growth in the European region is supported by an uptick in technology migration and replacement of outdated management systems.
Asia‑Pacific
Asia‑Pacific accounts for roughly 15% of the market share and stands as a fast‑emerging region for HOA management software adoption. Rapid urbanisation, expansion of residential communities and increasing middle‑class home ownership all drive interest in digital association tools. Local vendors and global players are expanding in markets such as India, China and Southeast Asia with cloud‑based solutions tailored to smaller associations. Strong growth prospects here reflect untapped demand and rising technology acceptance.
Latin America
Latin America holds around 8% of market share, with Brazil, Mexico and Argentina emerging as key growth markets for HOA software solutions. Growth in this region is driven by increasing residential development and socio‑economic changes leading to better organised homeowner associations. However, slower technology infrastructure rollout and varying investment capabilities among associations reduce adoption speed. Vendors in Latin America focus on affordable subscription models and regional partnerships to enhance penetration.
Middle East & Africa (MEA)
The Middle East & Africa region contributes about 7% of the total market share and exhibits considerable potential driven by new residential and mixed‑use community developments. Gulf Cooperation Council (GCC) countries, as well as South Africa, are increasingly investing in smart‑community platforms and HOA management solutions. Adoption is supported by infrastructure investment and digital government initiatives. Nonetheless, fragmented markets and varying association maturity levels pose challenges for unified growth.
Market Segmentations:
By Offering:
- Maintenance management
- Inventory management
By Deployment Mode:
- On-premises
- Cloud
By Organization Size:
- Small and medium-sized enterprises (SME)
- Large Enterprises
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the HOA Management Software Market features key players such as Block, Inc., Adobe Inc., SAP, Oracle, McAfee Corporation, VMware Inc., Microsoft, IBM Corporation, NortonLifeLock Inc., and Intuit Inc. The HOA Management Software Market is marked by a diverse range of companies offering a variety of technological solutions aimed at improving the efficiency of community management. These companies are increasingly focusing on cloud-based solutions, leveraging AI, automation, and predictive analytics to enhance operational efficiency, streamline communication, and optimize maintenance workflows. The market is seeing a shift toward modular, subscription-based models that allow smaller associations to access scalable tools without large upfront investments. Additionally, the growing importance of data security and compliance with privacy regulations is driving innovation in secure, user-friendly platforms. Strategic partnerships, acquisitions, and ongoing software enhancements are key strategies for companies looking to capture market share and address the evolving needs of homeowners associations. This highly competitive environment is characterized by continuous innovation and a strong emphasis on customer service and user experience.
Key Player Analysis
- Block, Inc.
- Adobe Inc.
- SAP
- Oracle
- McAfee Corporation
- VMware Inc.
- Microsoft
- IBM Corporation
- NortonLifeLock Inc.
- Intuit Inc.
Recent Developments
- In February 2025, Oracle enhanced its supply chain management platform by integrating AI capabilities. This update enables the automation of various tasks for procurement professionals, such as generating standardized product descriptions and providing supplier recommendations, which can significantly streamline procurement processes.
- In January 2025, Block, a technology, announced the launch of Goose, an open-source AI agent designed to empower developers with customizable tools. Goose allows users to leverage various large language models, providing flexibility in its application across different tasks and industries.
- In November 2024, Microsoft unveiled cloud-connected software that enables customers to deploy Azure computing, networking, storage, and application services across various environments, including edge locations, on-premises data centers, and hybrid cloud setups.
- In February 2024, Schneider Electric launched ECOSTRUXURE plant lean management, a solution aimed at increasing productivity and digitalization in manufacturing. The solution aggregates and collects information across industrial processes to develop key performance indicators (KPIS) for short-interval management meetings.
Report Coverage
The research report offers an in-depth analysis based on Offering, Deployment Mode, Organization Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing number of planned residential communities worldwide will boost demand for HOA management software.
- Growing preference for cloud‑based deployment provides scalability and drives adoption among associations of various sizes.
- Rising expectations for resident engagement and mobile access will push software providers to enhance communication and portal features.
- Integration of AI and automation for tasks like maintenance tracking, billing, and violation management will become more common.
- Modular subscription‑based delivery models that reduce upfront investment will widen access for smaller associations.
- Expansion of associations in emerging markets presents untapped opportunities for software vendors.
- Retrofits of manual or legacy systems in older associations will create a strong market for replacement solutions.
- Partnerships between software providers and service companies (like maintenance or accounting) will grow value‑added offerings.
- Data security and compliance demands will drive investment in secure, auditable platforms for board‑governed communities.
- Increased use of mobile apps, IoT sensors and resident self‑service features will transform how associations operate and demand evolves.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for HOA Management Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the HOA Management Software Market projected to grow between 2025 and 2032?
Which HOA Management Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the HOA Management Software Market?
Who are the leading companies in the HOA Management Software Market?
Which region commanded the largest share of the HOA Management Software Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10.15 billion → 2032: USD 17.31 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global HOA Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global HOA Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global HOA Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global HOA Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global HOA Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global HOA Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global HOA Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global HOA Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10.15 billion → 2032: USD 17.31 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global HOA Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global HOA Management Software Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global HOA Management Software Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global HOA Management Software Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

