
Market Overview:
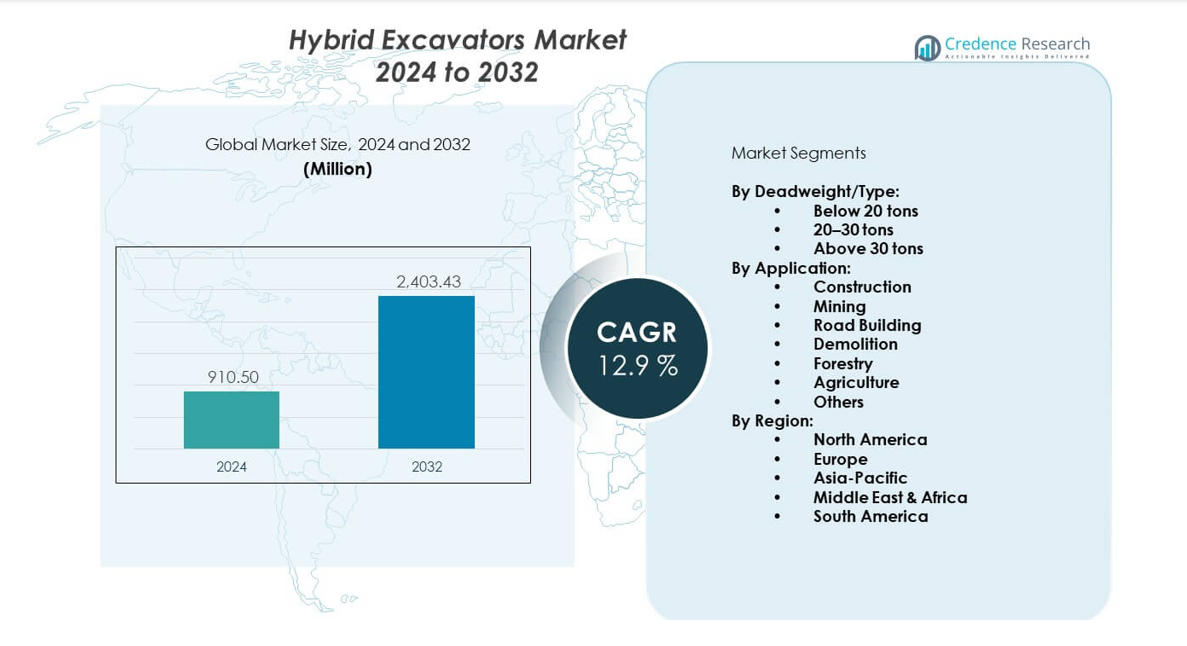
The Hybrid excavators market is projected to grow from USD 910.5 million in 2024 to an estimated USD 2,403.43 million by 2032, with a compound annual growth rate (CAGR) of 12.9% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hybrid Excavators Market Size 2024 | USD 910.5 million |
| Hybrid Excavators Market, CAGR | 12.9% |
| Hybrid Excavators Market Size 2032 | USD 2,403.43 million |
Demand rises due to wider focus on fuel savings, cleaner job sites, and stronger carbon-reduction goals. Builders select hybrid excavators to cut fuel burn during long working cycles. Engine-motor systems support smoother performance in urban zones with noise limits. Project owners prioritize machines that reduce downtime and improve return on investment. Manufacturers push new hybrid platforms to meet sustainability targets. Contractors adopt smart monitoring tools to boost fleet efficiency. Public infrastructure upgrades also lift equipment use. Green policies reinforce industry confidence.
Asia Pacific leads due to rapid construction growth, large fleet replacement needs, and firm sustainability targets. China and Japan adopt advanced hybrid machinery early due to strong domestic production and strict emission norms. Europe shows steady traction as contractors shift toward greener fleets to meet environmental standards. North America records healthy uptake through smart city programs and rising urban redevelopment work. Emerging markets in Southeast Asia and Latin America gain pace as infrastructure spending expands and hybrid options become more accessible
Market Insights:
- The Hybrid excavators market was valued at USD 910.5 million in 2024 and is projected to reach USD 2,403.43 million by 2032, growing at a 12.9% CAGR driven by stricter emission norms and rising fuel-efficiency demands.
- Asia Pacific (45%), Europe (25%), and North America (20%) hold the largest shares due to strong infrastructure spending, mature OEM presence, and firm environmental regulations supporting hybrid adoption.
- Asia Pacific remains the fastest-growing region, supported by urban development, strict emission rules, and accelerated fleet modernization across China, India, and Japan.
- The construction segment holds about 40% share due to its high hybrid deployment across urban and infrastructure projects.
- The 20–30-ton category leads with roughly 50% share as contractors prefer balanced performance and efficiency for mixed civil engineering work.
Market Drivers:
Rising Focus on Fuel Savings and Lower Carbon Emissions
Construction firms raise demand for hybrid machinery to reduce fuel burn and cut greenhouse gas output. Contractors select efficient powertrain systems to control operating expenses on long work cycles. Governments tighten emission norms that push fleets toward greener models. Urban projects favor quieter machines to meet noise rules on dense job sites. Operators value smoother control from electric-assist systems that support better precision. Buyers compare lifetime cost advantages before replacing older diesel units. Manufacturers strengthen hybrid portfolios through steady design upgrades. The Hybrid excavators market gains support from stronger sustainability targets across regions.
- For instance, Komatsu’s HB215LC-3 hybrid excavator reports up to 20% lower fuel consumption verified through multiple field evaluations.
Growing Adoption in Large Infrastructure and Civil Engineering Projects
Governments expand roadwork, metro systems, and city renewal plans that require hybrid fleets for greener execution. Contractors deploy hybrid units to reduce idle fuel loss during long tracking paths. Public agencies frame procurement policies that prioritize reduced-emission machinery. Mining and quarry operators explore hybrid platforms to boost efficiency during heavy digging cycles. Rental companies add hybrid options to meet rising contractor inquiries. Project planners prefer machines that offer steady performance under strict work-hour limits. Buyers evaluate hybrid durability under tough site loads. The Hybrid excavators market benefits from increased investment across major infrastructure corridors.
- For instance, Hitachi’s ZH210-6 hybrid model delivers up to 15% fuel savings in large infrastructure projects, confirmed through real-world contractor testing.
Advancements in Hybrid Powertrain Technology and System Integration
New battery chemistries deliver higher charge retention during demanding site tasks. OEMs refine regeneration systems to capture braking energy for improved efficiency. Control software helps operators shift between engine and motor power with ease. Designers cut component weight to support better power distribution. Cooling systems evolve to handle high electrical loads under warm conditions. Hybrid modules gain reliability due to stronger thermal management. Testing cycles expand to validate performance across varied terrains. The Hybrid excavators market gains momentum through rapid technological upgrades.
Government Incentives and Supportive Environmental Policies
National programs promote low-emission construction equipment to meet climate goals. Authorities offer tax credits and duty relief for hybrid machinery adoption. Local agencies frame rules that restrict diesel-only fleets in urban cores. Energy departments promote hybrid research to cut construction-sector emissions. Compliance schemes reward companies that meet energy-use limits. Buyers align fleet plans with regional green mandates. Hybrid models receive priority in tenders with sustainability scoring. The Hybrid excavators market strengthens through strong regulatory alignment.
Market Trends:
Expansion of Smart Machine Control and Connected Fleet Technologies
Contractors use telematics to track performance and optimize site operations. Fleet managers rely on data insights to plan predictive service windows. Sensor-based monitoring helps detect early faults before heavy downtime. Digital dashboards offer clear visibility for large site teams. Operators gain real-time guidance for better power mode use. Remote diagnostics support quick decision-making during breakdowns. Connectivity tools align multi-machine coordination on complex sites. The Hybrid excavators market embraces connected systems that lift productivity.
- For instance, Volvo CE's ActiveCare telematics monitoring service is designed to improve fleet uptime through predictive maintenance insights that allow for proactive repairs, which is verified in customer deployments and widely recognized for reducing unplanned downtime and improving fleet availability.
Shift Toward Electrified Components in Hybrid Platforms
OEMs integrate stronger electric motors to enhance digging response. Battery packs gain higher energy density for longer task cycles. Designers refine electric swing systems that support smooth motion control. Suppliers expand parts lines for electric-drive modules. New hybrid platforms reduce reliance on large diesel engines. Production lines adapt to mixed powertrain manufacturing. Operators experience better torque feedback during precision tasks. The Hybrid excavators market advances through steady electrification progress.
- For instance, Caterpillar’s 336 Hybrid model uses an electric-hydraulic system that cuts fuel use by up to 25% based on verified Cat job-site data.
Rising Demand from Rental Fleets and Short-Term Project Contractors
Rental firms expand hybrid inventories to meet demand from urban job sites. Contractors prefer renting to test hybrid performance before long-term buying. Fleet operators look for machines that offer lower operating cost per shift. Hybrid units fit well in noise-sensitive applications across cities. Rental firms track machine health closely through connected tools. Hybrid reliability builds confidence for varied site conditions. Short-term projects adopt hybrids to meet green contract clauses. The Hybrid excavators market gains traction across rental ecosystems.
Integration of Autonomous and Semi-Automated Functions
Developers add automated digging modes that reduce operator fatigue. Safety systems use cameras and sensors for clearer site awareness. Semi-autonomous controls guide operators during leveling work. AI tools refine power distribution across hybrid modules. Autonomous-ready platforms attract interest from large contractors. Machine-learning models study load patterns for better task prediction. Remote operation stations improve safety in risky terrain. The Hybrid excavators market moves toward smart automation features.
Market Challenges Analysis:
High Upfront Costs and Limited Awareness Among Small Contractors
Smaller firms hesitate to invest due to higher hybrid pricing. Buyers compare diesel options that appear cheaper at the start. Limited awareness of lifetime savings slows early adoption. Service teams require training to maintain hybrid modules. Rural contractors struggle with access to hybrid parts. Financing options remain uneven across developing regions. Buyers face uncertainty about long-term component durability. The Hybrid excavators market manages cost concerns during early fleet transitions.
Infrastructure Gaps and Technical Complexity Across Key Regions
Charging support for hybrid and electric-assist systems remains limited in many markets. Service networks must expand to handle advanced electrical components. Technicians need stronger skill sets to manage complex powertrains. Component availability varies across countries with weaker supply chains. Import delays affect parts replacement for hybrid systems. Contractors in remote regions face downtime due to technical dependency. Buyers reconsider hybrid choices when support gaps appear. The Hybrid excavators market navigates uneven infrastructure maturity.
Market Opportunities:
Growing Push for Green Construction and Urban Sustainability Targets
Cities plan large projects with strict emission rules that favor hybrids. Contractors seek greener fleets to qualify for public tenders. Hybrid units support noise-controlled operations in dense zones. Governments frame long-term climate mandates that lift hybrid relevance. OEMs adapt offerings to meet expanding green procurement lists. Project owners prefer efficient machinery that improves work output. Fleet operators plan hybrid expansion to meet policy timelines. The Hybrid excavators market gains scope in sustainability-driven regions.
Expansion Potential in Developing Markets Through Fleet Modernization
Developing countries invest in infrastructure that requires modern machinery. Older fleets push buyers toward efficient hybrid models. Import policies evolve to support eco-friendly equipment. Contractors adopt hybrids to reduce lifetime running costs. Training programs help operators manage hybrid controls. Rental chains introduce hybrid options for flexible access. Buyers view hybrid systems as a long-term upgrade path. The Hybrid excavators market finds strong prospects in emerging economies.
Market Segmentation Analysis:
By Deadweight/Type
The Hybrid excavators market expands across three core weight classes that serve varied project demands. Below 20-ton models gain strong use in urban construction due to compact size and higher maneuverability. Contractors prefer 20–30-ton units for balanced power and fuel savings across mixed civil projects. Above 30-ton machines support mining, large earthmoving, and heavy industrial work where high torque and endurance matter. Buyers evaluate performance, maintenance needs, and hybrid efficiency before selecting a suitable weight class. Rental fleets stock mid-range models to address diverse client needs. OEMs refine hybrid systems to support better fuel control across all power bands. Each type strengthens its role based on specific site requirements.
- For instance, Hyundai’s HX220AL mid-range machine reports up to 12% improved fuel efficiency in field assessments due to advanced power-control systems.
By Application
The Hybrid excavators market covers a broad application base driven by infrastructure expansion and sustainability goals. Construction remains the largest segment due to rising project volumes across cities. Mining operators deploy hybrid units to reduce fuel costs during extended digging cycles. Road-building crews prefer hybrids for long duty hours on major corridors. Demolition firms adopt hybrids to meet noise and emission limits in dense areas. Forestry users rely on electric-assist torque for controlled handling. Agriculture applications grow through fleet upgrades in large farms. Other sectors adopt hybrid platforms where efficiency and lower emissions support long-term fleet plans.
- For instance, SANY’s SY215 hybrid model demonstrated up to 15% fuel reduction during road-building and quarry operations as verified in customer case studies.
Segmentation:
By Deadweight/Type:
- Below 20 tons
- 20–30 tons
- Above 30 tons
By Application:
- Construction
- Mining
- Road Building
- Demolition
- Forestry
- Agriculture
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific
The Hybrid excavators market secures the highest share in Asia Pacific, holding over 45% of global demand. Strong construction spending in China, India, and Southeast Asia pushes rapid adoption across major infrastructure corridors. Japan and South Korea advance hybrid deployment through strict emission standards and strong OEM presence. Contractors favor hybrid units to improve fuel savings on long work cycles. Governments support greener machinery to lower construction-related emissions. Rental companies expand hybrid fleets to serve dense urban zones. The region maintains its lead through continuous investment in large public projects.
Europe
Europe accounts for around 25% of the Hybrid excavators market due to strong environmental policies and early hybrid technology adoption. Contractors deploy hybrid models to meet low-emission requirements in major cities. Germany, France, the U.K., and the Nordics show strong interest in hybrid machinery supported by local incentives. Fleet owners upgrade older diesel units to comply with sustainability guidelines. OEMs based in the region introduce advanced hybrid platforms tuned for reduced noise and fuel use. Public infrastructure programs create steady demand across transportation and urban renewal work. The region strengthens its position through firm regulatory alignment.
North America, Middle East & Africa, and South America
North America holds about 20% share driven by urban infrastructure upgrades and rising interest in low-emission equipment. Contractors value hybrid reliability for long shifts on large public projects. The Middle East & Africa captures roughly 6% share supported by selective adoption in mining, construction, and energy-sector developments. South America contributes around 4% share through gradual uptake in Brazil and Argentina. Buyers across emerging markets evaluate hybrid options to cut fuel costs during long operating cycles. Governments introduce targeted sustainability programs that lift regional acceptance. The Hybrid excavators market moves steadily across these regions through mixed infrastructure needs and evolving policy support.
Key Player Analysis:
- Caterpillar
- Komatsu
- Hitachi Construction Machinery
- Volvo Construction Equipment
- Liebherr
- Hyundai Heavy Industries
- JCB
- Kobelco
- SANY
Competitive Analysis:
The Hybrid excavators market features strong competition among global OEMs that invest in cleaner powertrains and advanced control systems. Leading companies such as Caterpillar, Komatsu, Hitachi, Volvo CE, and SANY expand hybrid lines to address rising demand for low-emission machinery. Manufacturers refine battery systems, electric swing motors, and regeneration modules to improve site productivity. Players focus on fuel savings, reliability, and long-duty performance to secure larger fleet contracts. Partnerships with component suppliers help strengthen hybrid integration. Rental chains adopt hybrid units to broaden access for contractors. Product differentiation centers on efficiency gains, smart features, and durable hybrid components. The Hybrid excavators market remains dynamic with continuous innovation cycles.
Recent Developments:
- Komatsu entered a strategic partnership with Cummins in September 2025, focusing on hybrid powertrain development for heavy mining equipment. This alliance targets practical decarbonization and improved efficiency in surface haulage mining trucks, accelerating the industry's shift to low-carbon technologies. This collaboration also includes Komatsu's drive system supplier Wabtec, forming a tripartite effort towards next-generation hybrid mining solutions.
- In 2025, Caterpillar announced significant updates to its hydraulic excavator lineup, including the advanced Cat 395 Front Shovel unveiled at bauma 2025, designed for mining with high digging force and efficiency.
Report Coverage:
The research report offers an in-depth analysis based on By Deadweight/Type and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Hybrid demand rises as contractors prioritize fuel efficiency and sustainability goals.
- OEMs expand hybrid lines with advanced batteries and improved regeneration systems.
- Rental fleets grow hybrid availability across urban and heavy-duty categories.
- Digital tools strengthen hybrid fleet monitoring and uptime planning.
- Noise-restricted cities push wider adoption in dense project zones.
- Mining and quarry operators test high-power hybrids for long excavation cycles.
- Regulations accelerate hybrid adoption across public infrastructure tenders.
- Service networks evolve to support hybrid diagnostics and powertrain parts.
- Emerging markets discover hybrid benefits through fleet modernization.
- Technology integration positions hybrids as a long-term alternative to diesel units.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Focus on Fuel Savings and Lower Carbon Emissions
Construction firms and contractors are increasingly adopting hybrid excavators to reduce fuel consumption and greenhouse gas emissions, driven by stricter government emission norms and the need to control operating expenses on long work cycles.
Growing Adoption in Large Infrastructure and Civil Engineering Projects
Governments and public agencies are expanding infrastructure projects such as roads, metro systems, and city renewal, which require hybrid fleets to meet green procurement policies and reduce idle fuel loss during extended operations.
Advancements in Hybrid Powertrain Technology and System Integration
Continuous improvements in battery chemistries, regeneration systems, and control software are making hybrid excavators more efficient, reliable, and easier to operate, encouraging broader market adoption.
Government Incentives and Supportive Environmental Policies
National and local authorities are offering tax credits, duty relief, and procurement preferences for hybrid machinery, accelerating the shift from diesel-only fleets and supporting the market’s growth.
Expansion of Smart Machine Control and Connected Fleet Technologies
The integration of telematics, predictive maintenance, and digital monitoring tools is enhancing fleet efficiency and uptime, making hybrid excavators more attractive to contractors and rental companies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hybrid excavators market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hybrid excavators market projected to grow between 2025 and 2032?
Which is the leading region of the market for hybrid excavators?
What are the key drivers for the growth of the hybrid excavators market?
Which is the major segment in the hybrid excavators market by application?
Who are the leading companies in the Hybrid excavators market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Construction
- 1.2.2 Mining
- 1.2.3 Road Building
- 1.2.4 Demolition
- 1.2.5 Forestry
- 1.2.6 Agriculture
- 1.2.7 Others
- 1.3 By Deadweight/Type
- 1.3.1 Below 20 tons
- 1.3.2 20–30 tons
- 1.3.3 Above 30 tons
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 910.5 million → 2032: USD 2,403.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hybrid Excavators Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hybrid Excavators Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hybrid Excavators Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hybrid Excavators Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hybrid Excavators Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hybrid Excavators Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hybrid Excavators Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hybrid Excavators Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 910.5 million → 2032: USD 2,403.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hybrid Excavators Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Construction
- 12.3.7.2 Mining
- 12.3.7.3 Road Building
- 12.3.7.4 Demolition
- 12.3.7.5 Forestry
- 12.3.7.6 Agriculture
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deadweight/Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Below 20 tons
- 12.4.7.2 20–30 tons
- 12.4.7.3 Above 30 tons
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hybrid Excavators End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hybrid Excavators Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hybrid Excavators Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hybrid Excavators Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Komatsu
- 18.4 Hitachi Construction Machinery
- 18.5 Volvo Construction Equipment
- 18.6 Liebherr
- 18.7 Hyundai Heavy Industries
- 18.8 JCB
- 18.9 Kobelco
- 18.10 SANY
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

