
Market Overview
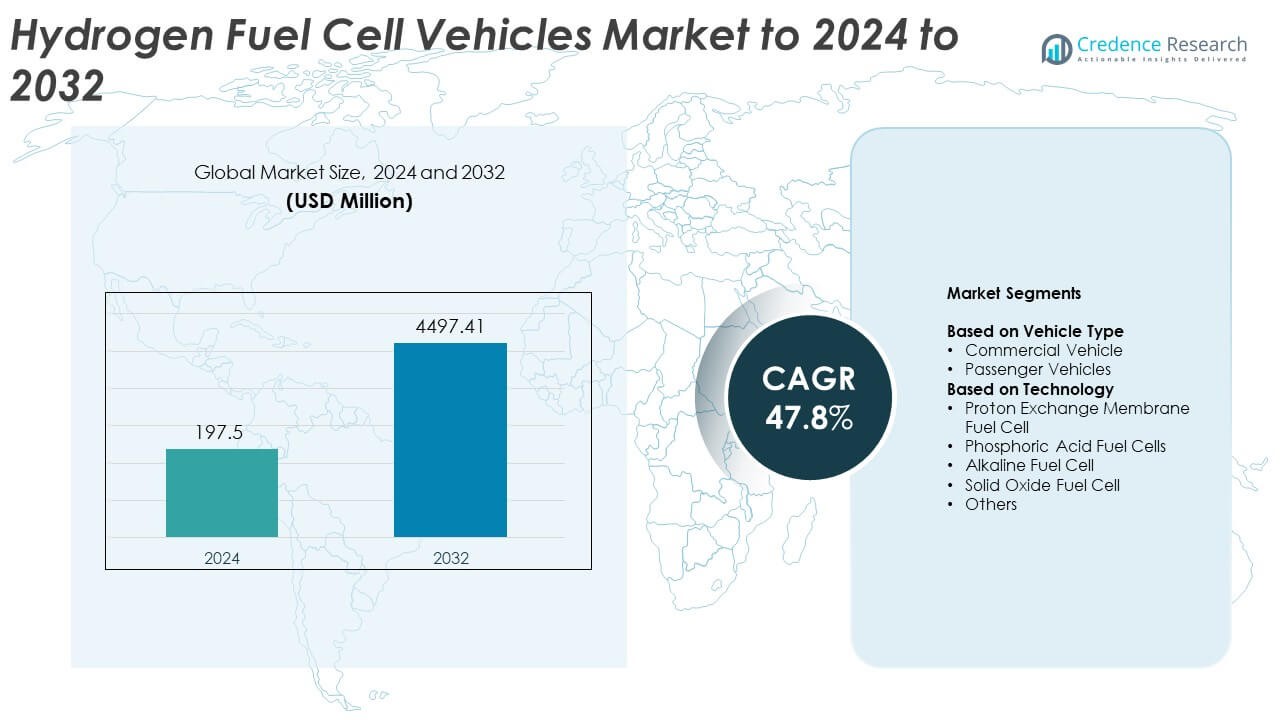
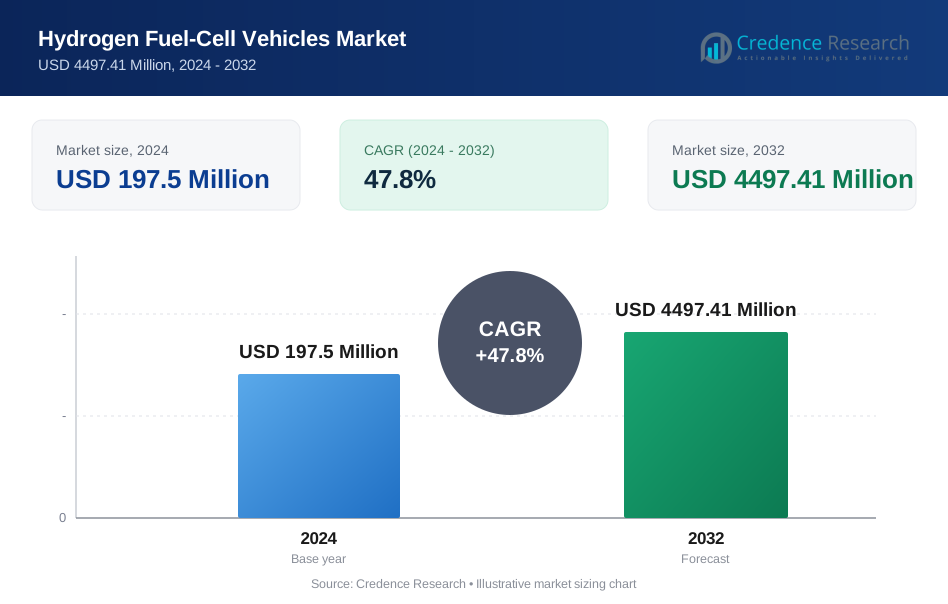
Hydrogen Fuel Cell Vehicles Market size was valued at USD 197.5 Million in 2024 and is anticipated to reach USD 4497.41 Million by 2032, at a CAGR of 47.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydrogen Fuel Cell Vehicles Market Size 2024 | USD 197.5 Million |
| Hydrogen Fuel Cell Vehicles Market , CAGR | 47.8% |
| Hydrogen Fuel Cell Vehicles Market Size 2032 | USD 4497.41 Million |
The Hydrogen Fuel Cell Vehicles Market is shaped by leading companies such as Intelligent Energy Holdings plc, Plug Power, Toyota, Pearl Hydrogen, Panasonic Corporation, Doosan Corporation, Hyundai Motor Company, Ballard Power System, Proton Power System PLC, Delphi Technologies, and ITM Power. These players expand fuel cell stack production, strengthen partnerships with energy providers, and invest in next-generation hydrogen storage systems to support wider commercial and passenger deployment. Asia Pacific leads the market with about 32% share in 2024, driven by large-scale hydrogen programs in China, Japan, and South Korea. North America follows with roughly 34% share, supported by strong fleet adoption and growing hydrogen corridor development.
Market Insights
- Hydrogen Fuel Cell Vehicles Market was valued at USD 197.5 Million in 2024 and is projected to reach USD 4497.41 Million by 2032, growing at a CAGR of 47.8%.
- Strong demand from commercial vehicles, which hold about 61% share in 2024, drives market growth through long-range performance and fast refueling for heavy-duty fleets.
- Proton exchange membrane fuel cells dominate the technology segment with nearly 74% share, shaping key trends such as improved stack efficiency, durability, and integration with green hydrogen supply chains.
- The competitive landscape strengthens as major manufacturers expand fuel cell production, build partnerships with energy firms, and lower system costs, while high hydrogen prices and limited refueling stations remain major restraints.
- North America accounts for about 34% share, Asia Pacific holds nearly 32%, and Europe captures around 30% share, supported by national hydrogen programs, while Latin America and Middle East & Africa together represent about 4% of the market.
Market Segmentation Analysis:
By Vehicle Type
Commercial vehicles lead this segment with about 61% share in 2024, driven by rising fleet adoption across logistics, public transport, and heavy-duty applications. Fleet operators prefer hydrogen fuel cell trucks and buses because they deliver long driving ranges, fast refueling, and strong performance on high-load routes. Governments in Asia, Europe, and North America continue to deploy large hydrogen bus fleets, which further lifts commercial uptake. Passenger vehicles grow steadily as automakers expand hydrogen sedan and SUV models, but adoption remains slower due to higher costs and limited refueling stations.
- For instance, Toyota provided around 3,700 mobility products and vehicles for the Tokyo 2020 Olympic and Paralympic Games, of which approximately 500 were Mirai fuel cell electric vehicles (FCEVs) and the total included other electric vehicles like the e-Palette and APM.
By Technology
Proton exchange membrane fuel cells dominate this segment with nearly 74% share in 2024 due to their high power density, quick start capability, and suitability for both passenger and commercial vehicle platforms. Automakers rely on PEMFC systems because they perform well in varying temperatures and support rapid refueling, making them ideal for daily fleet operations. Solid oxide and alkaline fuel cells gain interest for niche heavy-duty use but remain limited by higher operating temperatures. Phosphoric acid fuel cells hold a smaller share as development focuses on PEMFC advancements in efficiency and durability.
- For instance, Ballard Power Systems' fuel cells have powered buses that have achieved durability records with more than 35,000 hours of revenue service. As of late 2024/early 2025, the company had over 850 vehicles deployed across European cities (and more than 1,700 globally).
Key Growth Drivers
Rapid expansion of hydrogen infrastructure
Growing investment in hydrogen production and refueling stations boosts the adoption of hydrogen fuel cell vehicles. Governments in Asia, Europe, and North America support large-scale hydrogen hubs that supply cleaner fuel for buses, trucks, and passenger fleets. This expansion reduces range anxiety and strengthens confidence among fleet operators. As refueling networks grow across highways and urban areas, commercial and logistics fleets shift toward hydrogen to meet emission rules and operational demands, making infrastructure growth a primary driver of market acceleration.
- For instance, Air Liquide has installed more than 200 hydrogen stations around the world and has key involvement in large stations such as the one in Daxing, China, which has a capacity of nearly 5 tons per day, demonstrating a much larger scale of supply than the 4 tons total mentioned.
Strong government incentives and zero-emission mandates
National policies that promote zero-emission transportation continue to push hydrogen fuel cell deployment. Authorities implement subsidies, tax benefits, and fleet procurement programs that reduce high upfront costs and speed market entry. Commercial operators adopt hydrogen trucks and buses to meet stricter fleet-level emission limits and urban clean-air requirements. These supportive regulations increase investment in fuel cell systems, supply chains, and hydrogen production, positioning policy strength as a major catalyst for long-term adoption across multiple regions.
- For instance, South Korea had a total of 29,733 fuel cell electric vehicles (FCEVs) on the road by the end of 2022.
Growing demand for long-range and heavy-duty mobility
Hydrogen fuel cell vehicles offer long driving ranges, fast refueling, and strong load-bearing capacity, making them ideal for heavy-duty and long-distance applications. Logistics firms adopt fuel cell trucks for stable performance on demanding routes, while transit agencies deploy hydrogen buses for continuous operations. As e-commerce and freight transport expand globally, operators seek solutions that reduce emissions without sacrificing range or uptime. This shift toward heavy-duty decarbonization establishes hydrogen mobility as a key driver of future fleet modernization.
Key Trends and Opportunities
Rising integration of green hydrogen supply chains
The shift toward green hydrogen production creates major opportunities for hydrogen mobility. Renewable-powered electrolysis improves fuel sustainability and helps fleets achieve deeper emission reductions. Automakers collaborate with energy providers to secure long-term green hydrogen supply for commercial operations. This alignment of clean fuel production with vehicle deployment strengthens ecosystem development and positions green hydrogen as a central trend that enhances environmental value and system reliability across the market.
- For instance, Nel Hydrogen has significantly increased its annual manufacturing capacity, with its Herøya facility in Norway achieving 1 GW annual alkaline electrolyzer production capacity.
Advancements in fuel cell durability and cost reduction
New material innovations and manufacturing improvements lower the cost of fuel cell stacks and enhance long-term durability. Companies work on catalysts, membranes, and lightweight components that improve efficiency while reducing maintenance. These advancements increase system lifespan and make ownership more viable for fleet operators. As cost gaps narrow compared with battery-electric and diesel alternatives, technology optimization becomes a major opportunity shaping the next wave of hydrogen vehicle adoption, especially in commercial fleets.
- For instance, Plug Power announced in April 2023 that its Rochester gigafactory was on track to achieve a production rate of 100 megawatts of PEM stack capacity per month by mid-Q2 2023.
Growing OEM partnerships and platform development
Vehicle manufacturers expand strategic partnerships to accelerate fuel cell platform development. Joint ventures between automotive and energy companies help scale production, reduce costs, and standardize components. These alliances enable faster model launches across trucks, buses, and passenger vehicles. As collaboration grows across regions, OEM partnerships create new opportunities for shared technology, broader fleet testing, and accelerated commercialization of hydrogen-powered mobility solutions.
Key Challenges
High production and operational costs
Hydrogen vehicles remain costly due to expensive fuel cell stacks, onboard storage systems, and limited economies of scale. Hydrogen fuel prices also remain higher than diesel or electricity in many regions, affecting operating margins for fleets. These cost pressures slow consumer adoption and delay large-scale deployment. Without continued subsidies, manufacturing expansion, and competitive hydrogen pricing, cost barriers pose a significant challenge to achieving widespread commercial viability.
Slow development of refueling infrastructure
Hydrogen refueling networks grow slower than required for mass adoption. Many countries have limited station availability, and installations involve high capital costs, regulatory delays, and complex safety requirements. This restricts long-distance travel and prevents smooth fleet operations on key routes. The slow pace of infrastructure expansion remains a major challenge that affects reliability, route planning, and overall market confidence, especially in emerging regions transitioning to hydrogen-based mobility.
Regional Analysis
North America North America holds about 34% share in the Hydrogen Fuel Cell Vehicles Market in 2024, supported by strong adoption across commercial fleets and public transit programs. The United States drives most demand due to federal incentives, hydrogen corridor development, and fleet decarbonization goals. Canada expands deployment in heavy-duty trucking and municipal buses, supported by clean-fuel policies. Growing investments in green hydrogen, partnerships between automakers and energy companies, and large-scale truck pilot programs strengthen regional growth. Steady infrastructure expansion along major logistics routes continues to improve long-distance feasibility for hydrogen-powered mobility.
Europe
Europe accounts for nearly 30% market share in 2024, driven by strict emission rules and national hydrogen strategies across Germany, France, the Netherlands, and the Nordic region. Major automakers and energy providers collaborate on hydrogen hubs and large logistics fleet trials. Transit agencies deploy hydrogen buses to meet urban air-quality targets, while long-haul truck programs accelerate adoption on cross-border freight routes. Strong funding from the EU Hydrogen Strategy and growing green hydrogen production create a favorable environment. Expansion of refueling stations along key highways supports continuous growth across commercial and passenger segments.
Asia Pacific
Asia Pacific leads globally with about 32% share in 2024, anchored by major deployments in China, Japan, and South Korea. China scales hydrogen trucks and buses through national demonstration zones, while Japan advances passenger fuel cell vehicles supported by long-term hydrogen roadmaps. South Korea expands domestic manufacturing and invests in nationwide hydrogen corridors. Strong government-backed programs, rapid infrastructure rollout, and robust fuel cell production capacity strengthen regional dominance. Heavy-duty fleets and public transit operators increasingly shift toward hydrogen solutions to meet zero-emission goals across fast-growing urban and industrial centers.
Latin America
Latin America holds around 3% market share in 2024, with early adoption led by Brazil, Chile, and Colombia. Chile’s national green hydrogen strategy drives initial deployments in mining and heavy-duty transport. Brazil explores hydrogen buses and pilot truck programs in major cities as part of long-term decarbonization plans. Limited infrastructure and high costs slow broader uptake, but government interest and international partnerships create early momentum. As renewable energy projects expand, the region positions hydrogen mobility as a future solution for freight-heavy industries and long-distance transportation networks.
Middle East and Africa
Middle East and Africa account for about 1% market share in 2024, driven by emerging hydrogen ecosystem projects in the UAE, Saudi Arabia, and South Africa. Saudi Arabia and the UAE invest in large-scale green hydrogen production, enabling early pilot deployments in logistics and municipal fleets. South Africa explores hydrogen-powered heavy-duty transport supported by strong platinum fuel cell material supply chains. Infrastructure remains limited, but government-backed mobility pilots and expanding clean-energy megaprojects lay the groundwork for future adoption. The region’s strong renewable energy potential positions it for long-term hydrogen mobility growth.
Market Segmentations:
By Vehicle Type
- Commercial Vehicle
- Passenger Vehicles
By Technology
- Proton Exchange Membrane Fuel Cell
- Phosphoric Acid Fuel Cells
- Alkaline Fuel Cell
- Solid Oxide Fuel Cell
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Hydrogen Fuel Cell Vehicles Market features strong participation from Intelligent Energy Holdings plc, Plug Power, Toyota, Pearl Hydrogen, Panasonic Corporation, Doosan Corporation, Hyundai Motor Company, Ballard Power System, Proton Power System PLC, Delphi Technologies, and ITM Power. The competitive landscape continues to evolve as companies scale fuel cell stack production, improve system efficiency, and develop advanced hydrogen storage technologies. Many manufacturers focus on heavy-duty mobility platforms, where long range and rapid refueling offer clear advantages over battery-electric options. Strategic partnerships between automotive firms, hydrogen producers, and infrastructure developers strengthen ecosystem growth and support large fleet deployments. Companies invest in next-generation membranes, catalysts, and lightweight components to reduce costs and extend durability. Several players expand manufacturing footprints across Asia, Europe, and North America to meet rising demand. As green hydrogen production accelerates, competition intensifies around capturing early commercial fleet contracts and securing long-term supply agreements.
Key Player Analysis
- Intelligent Energy Holdings plc
- Plug Power
- Toyota
- Pearl Hydrogen
- Panasonic Corporation
- Doosan Corporation
- Hyundai Motor Company
- Ballard Power System
- Proton Power System PLC
- Delphi Technologies
- ITM Power
Recent Developments
- In 2025, Ballard Power Systems unveiled its new fuel cell module, FCmove-SC, designed for city bus applications
- In 2024, Hyundai Motor Company unveiled its INITIUM hydrogen fuel cell electric vehicle (FCEV) concept at its "Clearly Committed" event in October 2024. The concept previews a new production FCEV planned for the first half of 2025.
- In 2023, Toyota unveiled a prototype of its hydrogen fuel cell electric Hilux pickup truck, developed in collaboration with consortium partners and supported by UK government funding.
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as hydrogen refueling networks grow across major transport corridors.
- Commercial fleets will adopt fuel cell trucks and buses at a faster pace than passenger vehicles.
- Green hydrogen production will increase, improving sustainability and lowering lifecycle emissions.
- Advancements in fuel cell efficiency will reduce ownership costs for fleet operators.
- Heavy-duty logistics and long-range transport will remain the strongest demand drivers.
- Automakers will launch more dedicated fuel cell vehicle platforms for global markets.
- Government incentives and zero-emission policies will continue to accelerate adoption.
- Partnerships between energy providers and OEMs will shape large-scale fleet deployments.
- Asia Pacific will maintain leadership as large national programs scale hydrogen mobility.
- Falling hydrogen fuel prices and better distribution networks will support long-term market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hydrogen Fuel Cell Vehicles Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hydrogen Fuel Cell Vehicles Market projected to grow between 2025 and 2032?
Which Hydrogen Fuel Cell Vehicles Market segment held the largest share in 2024?
Who are the leading companies in the Hydrogen Fuel Cell Vehicles Market?
Which region commanded the largest share of the Hydrogen Fuel Cell Vehicles Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hydrogen Fuel-Cell Vehicles Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hydrogen Fuel-Cell Vehicles Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 197.5 Million → 2032: USD 4497.41 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hydrogen Fuel-Cell Vehicles Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hydrogen Fuel-Cell Vehicles Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hydrogen Fuel-Cell Vehicles Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hydrogen Fuel-Cell Vehicles Market Drivers
- 3.3 Hydrogen Fuel-Cell Vehicles Market Restraints & Challenges
- 3.4 Hydrogen Fuel-Cell Vehicles Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hydrogen Fuel-Cell Vehicles Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hydrogen Fuel-Cell Vehicles Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hydrogen Fuel-Cell Vehicles category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hydrogen Fuel-Cell Vehicles Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Hydrogen Fuel-Cell Vehicles Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Hydrogen Fuel-Cell Vehicles market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hydrogen Fuel-Cell Vehicles Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hydrogen Fuel-Cell Vehicles Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Hydrogen Fuel-Cell Vehicles Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hydrogen Fuel-Cell Vehicles (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Hydrogen Fuel-Cell Vehicles Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hydrogen Fuel-Cell Vehicles Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Hydrogen Fuel-Cell Vehicles Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hydrogen Fuel-Cell Vehicles Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hydrogen Fuel-Cell Vehicles Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hydrogen Fuel-Cell Vehicles Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hydrogen Fuel-Cell Vehicles Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hydrogen Fuel-Cell Vehicles Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hydrogen Fuel-Cell Vehicles Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
