
Implantable Defibrillator Market Overview:
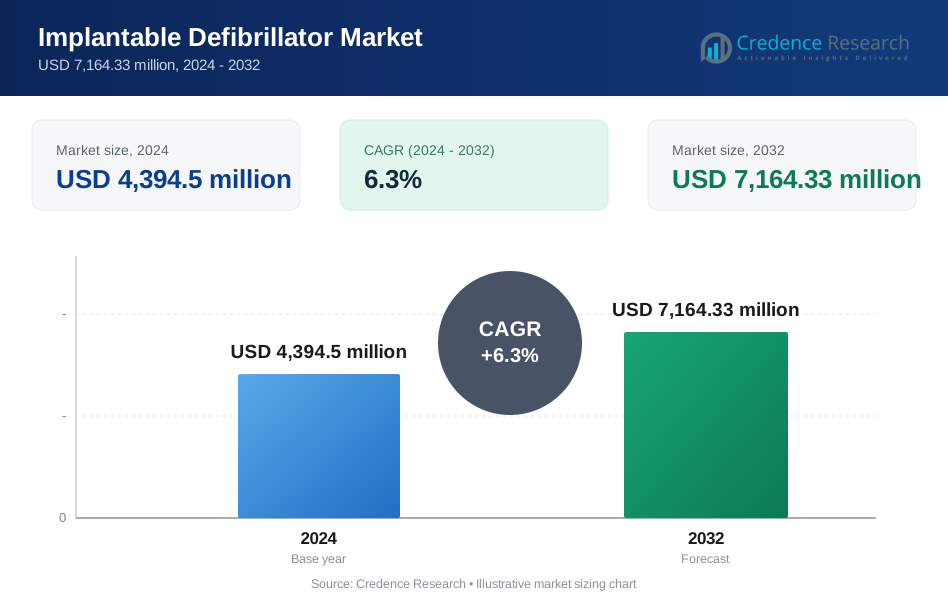
The implantable defibrillator market was valued at USD 4,394.5 million in 2024 and is expected to reach USD 7,164.33 million by 2032, growing at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Implantable Defibrillator Market Size 2024 | USD 4,394.5 million |
| Implantable Defibrillator Market, CAGR | 6.3% |
| Implantable Defibrillator Market Size 2032 | USD 7,164.33 million |
Implantable Defibrillator Market Insights
- Rising cardiovascular disease prevalence drives demand, with implantable cardioverter defibrillators leading the product segment at a 58% share due to strong clinical adoption.
- Key trends include continued preference for transvenous systems, which hold a 72% share, supported by versatility and established implantation practices.
- Competitive analysis shows a concentrated market where leading players focus on battery longevity, remote monitoring, and clinical evidence, while high device costs remain a restraint.
- Regional analysis indicates North America leads with a 38% share, followed by Europe at 29%, Asia Pacific at 21%, Latin America at 7%, and the Middle East and Africa at 5%.

Implantable Defibrillator Market Segmentation Analysis:
By Product Type
By product type, implantable cardioverter defibrillators (ICDs) dominate the implantable defibrillator market with a 58% market share, driven by widespread clinical use in preventing sudden cardiac arrest. ICDs are commonly recommended for patients with ventricular arrhythmias and high-risk cardiac conditions. Strong clinical evidence, long-standing physician familiarity, and continuous device improvements support adoption. Technological advancements such as longer battery life, remote monitoring, and improved sensing accuracy strengthen demand. Cardiac resynchronization therapy defibrillators (CRT-Ds) hold the remaining share, supported by use in heart failure patients requiring both rhythm management and resynchronization therapy.
- For instance, Boston Scientific’s RESONATE CRT-D delivers pacing pulses at 3.5 V and 0.4 ms, improving contractile synchrony during heart failure therapy.
By Implantation Type
By implantation type, transvenous defibrillators lead the market with a 72% market share, supported by established implantation procedures and broad clinical acceptance. These devices provide pacing, defibrillation, and diagnostic capabilities, making them suitable for a wide patient population. Hospitals and cardiologists prefer transvenous systems due to extensive clinical data and versatility. Subcutaneous defibrillators account for the remaining share, driven by rising adoption among patients at risk of infection or vascular complications. Growing awareness of minimally invasive options supports gradual growth of subcutaneous systems.
- For instance, Biotronik transvenous ICDs offer pacing outputs up to 7.5 V and store 100 intracardiac electrogram episodes for diagnostics.
By End User
By end user, hospitals account for a 64% market share, driven by high procedure volumes and availability of specialized cardiac care infrastructure. Hospitals manage complex cardiac cases and emergency interventions, supporting strong device utilization. Advanced imaging, surgical facilities, and post-implantation monitoring capabilities reinforce dominance. Cardiac centers follow, supported by focused expertise in electrophysiology and heart rhythm management. Ambulatory surgical centers hold a smaller share, limited by procedural complexity and regulatory constraints, but benefit from increasing demand for cost-effective and streamlined cardiac interventions.
Key Growth Drivers
Rising Prevalence of Cardiovascular Diseases
The increasing incidence of cardiovascular diseases strongly drives the implantable defibrillator market. Aging populations face higher risk of ventricular arrhythmias and sudden cardiac arrest. Sedentary lifestyles, obesity, and diabetes further raise disease burden. Physicians increasingly recommend implantable defibrillators for high-risk patients to prevent fatal cardiac events. Improved screening and diagnosis rates support earlier intervention. Clinical guidelines continue to favor device-based therapy for long-term rhythm management. This driver sustains consistent demand across hospitals and cardiac centers worldwide.
- For instance, Abbott reported that its ICD therapy significantly reduced the frequency of painful arrhythmic shocks by utilizing advanced antitachycardia pacing to treat rapid heart rhythms before a shock becomes necessary, according to device data.
Technological Advancements in Defibrillator Devices
Continuous innovation significantly supports market growth. Manufacturers enhance battery longevity, sensing accuracy, and device miniaturization. Remote monitoring capabilities improve patient follow-up and reduce hospital visits. Improved lead designs and software algorithms enhance safety and therapy precision. These advancements increase physician confidence and patient acceptance. Integration with digital health platforms supports real-time data access. Technology-driven improvements strengthen long-term adoption across both ICD and CRT-D segments.
- For instance, MicroPort ICD shock output reaches 40 J with sensing accuracy calibrated at 0.9 mV thresholds.
Growing Awareness and Access to Advanced Cardiac Care
Rising awareness of sudden cardiac arrest prevention supports market expansion. Healthcare systems invest in advanced cardiac care infrastructure. Improved access to electrophysiology services increases implantation rates. Training programs expand physician expertise in device implantation. Insurance coverage and reimbursement policies improve patient access in developed regions. This driver supports steady growth, especially in emerging markets upgrading cardiac care capabilities.
Key Trends and Opportunities
Rising Adoption of Subcutaneous Defibrillators
Subcutaneous defibrillators gain attention due to reduced infection and lead-related risks. These systems avoid transvenous leads, improving long-term safety. Physicians increasingly consider these devices for younger and high-risk patients. Ongoing clinical studies expand approved use cases. This trend creates growth opportunities for manufacturers offering differentiated implantation options.
- For instance, MicroPort’s cardiac rhythm management systems have demonstrated high placement precision and stability in clinical evaluations involving their defibrillation leads.
Expansion of Remote Monitoring and Digital Integration
Remote monitoring adoption creates new opportunities. Connected defibrillators enable continuous rhythm tracking and early issue detection. Healthcare providers benefit from reduced readmissions and proactive care. Digital platforms support data-driven decision making. This trend improves patient outcomes and operational efficiency, supporting wider device adoption.
- For instance, Boston Scientific LATITUDE reduced in-person patient checks by 2.3 visits per year using automated wireless monitoring across documented clinical users.
Key Challenges
High Device and Procedure Costs
Implantable defibrillators involve high device and implantation costs. Advanced technology increases pricing pressure on healthcare systems. Cost constraints limit adoption in price-sensitive regions. Reimbursement variability affects hospital purchasing decisions. Managing affordability remains a critical challenge for broader market penetration.
Procedure-Related Risks and Regulatory Requirements
Implantation procedures carry risks such as infection and lead complications. Strict regulatory approval processes extend time to market. Clinical trial requirements increase development costs. These factors slow innovation cycles and limit rapid product launches. Addressing safety concerns remains essential for sustained growth.
Regional Analysis
North America
North America holds 38% market share in the implantable defibrillator market, supported by advanced healthcare infrastructure and high adoption of cardiac implantable devices. Strong prevalence of cardiovascular diseases and well-established clinical guidelines drive steady demand. Hospitals benefit from favorable reimbursement policies and access to skilled electrophysiologists. Continuous technology upgrades and early adoption of remote monitoring solutions further support growth. High patient awareness and regular cardiac screening programs enable early diagnosis and intervention. The presence of leading device manufacturers strengthens innovation, clinical trials, and rapid commercialization across the United States and Canada.
Europe
Europe accounts for 29% market share, driven by aging populations and rising incidence of heart failure and arrhythmias. Strong public healthcare systems support access to implantable defibrillators. Clinical emphasis on preventive cardiac care increases implantation rates. Countries with advanced electrophysiology services show higher adoption. Regulatory frameworks ensure device safety and standardization, supporting physician confidence. Technological innovation and growing acceptance of CRT-D devices contribute to steady demand. Western Europe leads consumption, while Central and Eastern Europe show gradual growth supported by healthcare modernization.
Asia Pacific
Asia Pacific commands 21% market share, supported by improving healthcare access and rising cardiovascular disease burden. Large patient populations and lifestyle-related risk factors increase demand for advanced cardiac therapies. Government investment in hospital infrastructure and cardiac centers supports adoption. Awareness of sudden cardiac arrest prevention continues to rise. Growing medical tourism and expanding insurance coverage strengthen market penetration. Japan, China, and India lead regional demand due to increasing procedural volumes and improving electrophysiology expertise.
Latin America
Latin America holds 7% market share, driven by gradual expansion of cardiac care services. Urban hospitals and private healthcare providers support most implantable defibrillator procedures. Rising awareness of advanced cardiac treatment options improves adoption. Cost sensitivity and limited reimbursement slow widespread penetration. However, increasing investment in tertiary care hospitals supports steady growth. Brazil and Mexico remain key contributors due to improving cardiac infrastructure and specialist availability.
Middle East and Africa
The Middle East and Africa represent 5% market share, supported by growing investment in advanced healthcare facilities. High-income countries drive demand through well-equipped hospitals and cardiac centers. Rising cardiovascular disease prevalence increases long-term need for implantable defibrillators. Limited access and affordability challenges restrict broader adoption. However, government-led healthcare expansion and private sector investment support gradual growth. Medical tourism and specialist training programs improve regional implantation capacity over time.
Implantable Defibrillator Market Segmentations:
By Product Type
- Implantable cardioverter defibrillators (ICDs)
- Cardiac resynchronization therapy defibrillators (CRT-Ds)
By Implantation Type
- Transvenous defibrillators
- Subcutaneous defibrillators
By End User
- Hospitals
- Cardiac centers
- Ambulatory surgical centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights a concentrated implantable defibrillator market led by key players including Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Biotronik SE & Co. KG, MicroPort Scientific Corporation, LivaNova PLC, Zoll Medical Corporation, Medico S.p.A., Lepu Medical Technology, and Osypka AG. These companies compete through advanced device innovation, strong clinical evidence, and global distribution networks. Leading players invest heavily in R&D to improve battery longevity, sensing accuracy, and remote monitoring capabilities. Strategic collaborations with hospitals and cardiac centers support clinical adoption. Regulatory approvals and compliance remain critical for competitive positioning. Market leaders benefit from established physician relationships and broad product portfolios. Smaller players focus on niche applications and regional expansion to strengthen presence. Continuous product upgrades and digital integration shape competitive dynamics across global markets.
Key Player Analysis
- Medtronic plc
- Abbott Laboratories
- Boston Scientific Corporation
- Biotronik SE & Co. KG
- MicroPort Scientific Corporation
- LivaNova PLC
- Zoll Medical Corporation
- Medico S.p.A.
- Lepu Medical Technology
- Osypka AG
Recent Developments
- In November 2025, Boston Scientific launched its CRT-D and ICD devices in Japan to treat heart failure and sudden cardiac death.
- In April 2025, Abbott initiated patient enrollment in the ASCEND CSP pivotal trial for an investigational conduction system pacing ICD lead.
- In March 2025, Medtronic launched the Aurora EV-ICD MRI device and Epsila EV MRI Lead in Japan, expanding extravascular ICD options for ventricular arrhythmias.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Implantation Type, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as cardiovascular disease prevalence increases globally.
- Implantable cardioverter defibrillators will remain the primary therapy choice.
- Remote monitoring integration will improve patient management and follow-up.
- Battery life and device miniaturization will continue to improve.
- Subcutaneous defibrillators will gain wider clinical acceptance.
- Hospitals will remain the dominant end users for implantation procedures.
- Emerging markets will show higher adoption as cardiac care access expands.
- Reimbursement support will influence procedure volumes in developed regions.
- Digital health integration will enhance clinical decision making.
- Continuous innovation will strengthen long-term market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases
The increasing incidence of cardiovascular diseases, particularly among aging populations and those with lifestyle-related risk factors, is driving demand for implantable defibrillators as a preventive measure against sudden cardiac arrest and ventricular arrhythmias.
Technological Advancements in Defibrillator Devices
Continuous innovation in battery longevity, sensing accuracy, device miniaturization, and remote monitoring capabilities is enhancing device performance and patient outcomes, encouraging broader clinical adoption.
Growing Awareness and Access to Advanced Cardiac Care
Improved awareness of sudden cardiac arrest prevention, expanding cardiac care infrastructure, and better access to electrophysiology services are increasing implantation rates, especially in emerging markets.
Expansion of Remote Monitoring and Digital Integration
The integration of remote monitoring and digital health platforms enables continuous patient management, early detection of device or rhythm issues, and reduces the need for in-person follow-ups, making defibrillator therapy more attractive to both providers and patients.
Rising Adoption of Subcutaneous Defibrillators
Subcutaneous defibrillators are gaining traction due to their reduced infection and lead-related risks, offering a safer alternative for certain patient groups and expanding the addressable market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Implantable Defibrillator market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Implantable Defibrillator market projected to grow between 2024 and 2032?
Which Implantable Defibrillator market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Implantable Defibrillator market?
Who are the leading companies in the Implantable Defibrillator market?
Which region commanded the largest share of the Implantable Defibrillator market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Cardiac centers
- 1.2.3 Ambulatory surgical centers
- 1.3 By Product Type
- 1.3.1 Implantable cardioverter defibrillators (ICDs)
- 1.3.2 Cardiac resynchronization therapy defibrillators (CRT-Ds)
- 1.4 By Implantation Type
- 1.4.1 Transvenous defibrillators
- 1.4.2 Subcutaneous defibrillators
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,394.5 million → 2032: USD 7,164.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Implantable Defibrillator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Implantable Defibrillator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Implantable Defibrillator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Implantable Defibrillator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Implantable Defibrillator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Implantable Defibrillator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Implantable Defibrillator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Implantable Defibrillator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,394.5 million → 2032: USD 7,164.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Implantable Defibrillator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Cardiac centers
- 12.3.7.3 Ambulatory surgical centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Implantable cardioverter defibrillators (ICDs)
- 12.4.7.2 Cardiac resynchronization therapy defibrillators (CRT-Ds)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Implantation Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Transvenous defibrillators
- 12.5.7.2 Subcutaneous defibrillators
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Implantable Defibrillator End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Implantable Defibrillator Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Implantable Defibrillator Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Implantable Defibrillator Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Laboratories
- 18.4 Boston Scientific Corporation
- 18.5 Biotronik SE & Co. KG
- 18.6 MicroPort Scientific Corporation
- 18.7 LivaNova PLC
- 18.8 Zoll Medical Corporation
- 18.9 Medico S.p.A.
- 18.10 Lepu Medical Technology
- 18.11 Osypka AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

