
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Implantable Infusion Pumps Market Size 2024 | USD 605.1 million |
| Implantable Infusion Pumps Market, CAGR | 6.00% |
| Implantable Infusion Pumps Market Size 2032 | USD 964.43 Million |
Market Insights
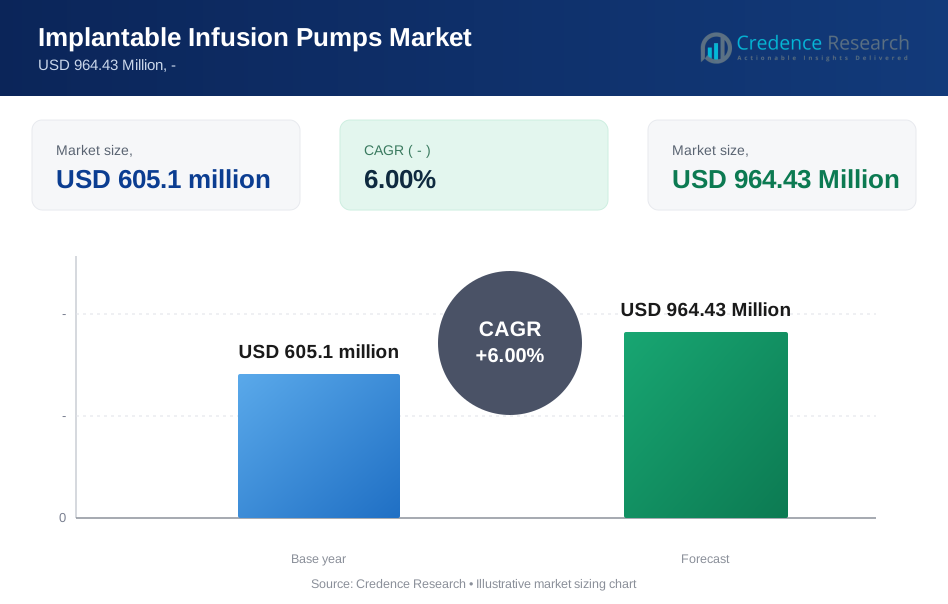
- Between 2024 and 2032, the global market for implantable infusion pumps is projected to expand at a compound annual growth rate (CAGR) of 6.00%, from an estimated USD 605.1 million in 2024 to USD 964.43 Million in 2032.
- The largest category is constant-rate implantable infusion pumps. Variable-rate implantable infusion pumps, on the other hand, are expected to grow at a strong CAGR.
- The pain management category will expand at a rapid rate of growth.
- Throughout the projected period, the CAGR for the hospital is anticipated to be the highest.
- North America controlled the implantable infusion pumps market.
- Regarding the market share of implantable infusion pumps, Europe is expected to come second.
- Asia Pacific is expected to experience the fastest growth in the implantable infusion pumps industry.
- The global market is expanding due to factors such as the rising prevalence of chronic diseases, government support and reimbursement policies, and rising patient and healthcare provider awareness.
- The combination of infusion pumps with digital health technologies, such as telemedicine and remote monitoring, has led to a surge in demand for advanced implanted infusion pumps.
Executive Summary
Market Definition
The implantable infusion pumps market is the area of the medical device industry that deals with the creation, manufacturing, promotion, and distribution of implantable infusion pumps. These devices are surgically inserted inside the body to directly provide controlled dosages of medication to particular regions, like the intrathecal space, spinal cord, or other specified places. The market offers a wide range of implantable infusion pump types to meet diverse medical requirements.
Market Overview
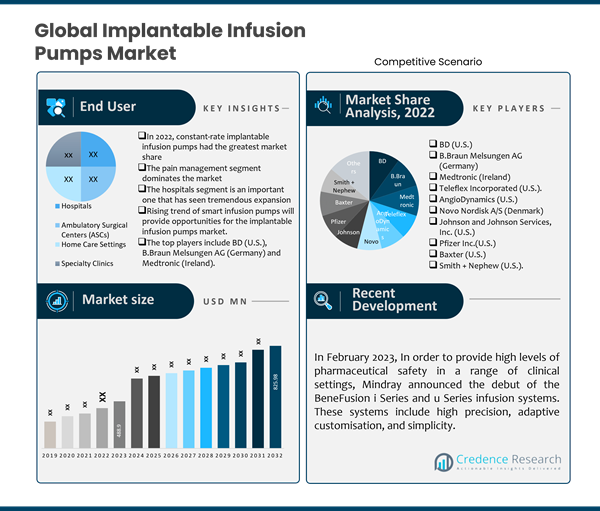
It is predicted that the implantable infusion pumps industry will continue its upward trajectory between 2024 and 2032, growing at a compound annual growth rate (CAGR) of 6.00%. From its projected USD 488.9 million in 2023 to USD 825.98 million in 2032, the market will continue to grow.
The market for implantable infusion pumps is expanding due to the rising incidence of chronic illnesses. Chronic illnesses, which include diabetes, cancer, and heart disease, are long-term ailments that frequently need ongoing care from a doctor. Aging populations, changing lifestyles, and urbanization are some of the reasons contributing to the global rise in the prevalence of these diseases. Medical devices known as implantable infusion pumps are made to administer controlled dosages of medication directly into the body of a patient. Because they offer consistent and targeted medication delivery, which can enhance therapy efficacy and patient compliance, they are especially helpful in controlling chronic diseases.
One popular type of implantable infusion device that helps diabetic people better control their blood sugar levels is an insulin pump. Implantable pumps that distribute painkillers directly to the source of pain or throughout the body can greatly enhance pain management in cancer patients. Implantable pumps are a useful tool because some cardiovascular disorders necessitate ongoing therapy to control symptoms and prevent consequences. The advancement of medical technology has resulted in the creation of increasingly advanced, dependable, and intuitive implanted infusion pumps. These developments improve the safety and efficacy of these devices, increasing their appeal to patients and healthcare professionals alike.
Segmentation by Product Type
- Constant-rate implantable infusion pumps are the market leader in terms of product type. Constant-rate implantable infusion pumps are a special form of implantable infusion pumps designed to give a consistent and continuous flow of medication at a fixed rate. These surgically implanted devices deliver a consistent and dependable dosage of medication directly to a designated target place, such as the bloodstream, spinal cord, or other body parts.
- The variable-rate implantable infusion pumps category will exhibit a sizable CAGR during the projected period. Advanced medical devices, known as variable-rate implanted infusion pumps, are made to precisely and carefully provide medication to a specific location inside the body. Variable-rate infusion pumps enable customizable flow rates based on patient demands and treatment procedures, in contrast to fixed-rate infusion pumps, which give a steady flow of medication.
Segmentation by Application
- The pain management category is projected to develop at a greater CAGR over the forecast period. The market for implantable infusion pumps includes a sizable segment dedicated to pain management. Patients with chronic pain disorders who do not respond to traditional oral or topical treatments can greatly benefit from these devices. To maximize pain relief and reduce systemic adverse effects, implantable infusion pumps deliver a continuous, regulated flow of pain medicine directly to the targeted location, such as the spinal cord or particular nerve sites.
- The cancer treatment category will likely register a significant CAGR during forecasting. Using implantable infusion pumps to provide chemotherapy medications directly to particular body parts, usually those close to tumor locations, is a common practice in the context of the implantable infusion pumps market. Compared to conventional methods of administering chemotherapy, this strategy has a number of benefits.
- Other applications, such as diabetes management, spasticity management, and cardiovascular disease, further enhance the need for implantable infusion pumps.
Segmentation by End User
- The hospitals category is projected to grow faster over the projection period. Hospitals purchase a large number of medical devices, such as implanted infusion pumps. Group Purchasing Organizations (GPOs), competitive bidding processes, direct purchases from manufacturers or distributors, and other channels are the ways in which they obtain these items.
- Other end users, including ambulatory surgical centers (ASCS), home care settings, and specialty clinics, also influence the need for implantable infusion pumps.
Segmentation by Region
- North America leads the implantable infusion pumps industry. This is due to the prevalence of chronic illnesses rising, and customized infusion pumps are being used more often to treat them.
- Europe is estimated to rank second in implantable infusion pumps market size.
- It is anticipated that the implantable infusion pumps market in Asia Pacific will grow quickly.
- The remaining need for implantable infusion pumps is met by regions including Latin America, the Middle East, and Africa.
Due to its potential to improve patient care, increase treatment adherence, and lower healthcare costs, telemedicine, and remote monitoring have emerged as key market drivers for implantable infusion pumps. Patients can obtain follow-ups and consultations with doctors via telemedicine without having to go to a hospital. Patients with chronic diseases who need continuous medication management and monitoring through implanted infusion pumps will benefit most from this. Systems for remote monitoring allow for ongoing patient health status tracking. Remote monitoring technology-enabled implantable infusion pumps allow healthcare providers to receive information on patient vital signs, drug delivery, and pump status. This allows for continued patient treatment without the need for frequent hospital visits.
The implantable infusion pumps market in North America is predicted to grow to be the largest in the globe. The North American region is primarily impacted by the rising prevalence of chronic diseases and the need for healthcare infrastructure. The region's strongholds of major players, the increasing acceptance of pen injectors for a range of applications across numerous nations, and government initiatives aimed at educating the public about the most recent advancements in infusion pump technology and related accessories and consumables are additional factors supporting the growth of the infusion pump market in North America. Data from 2020 reveal that in 2019, 20.4% of adults reported having chronic pain, while 7.4% reported having severe pain that frequently interfered with daily activities or work. Both rose with age, peaking in those 65 years of age and above. Therefore, it is anticipated that the number of chronic pain cases will rise, driving up demand for implantable infusion pumps, which are placed surgically to offer continuous drug administration to patients other than those with cancer in order to treat their pain. Furthermore, the regional implanted infusion pump market is expected to grow as a result of a recent product license granted by the US Food and Drug Administration.
It is projected that the implantable infusion pumps market will develop at the fastest rate in the Asia Pacific region. Numerous players that operate on a regional scale and make substantial contributions to the implantable infusion pump market market are found in the Asia-Pacific region. The market for implanted infusion pumps is also being driven by improved medical infrastructure and gradually rising disposable income in developing nations like China and India, among many others. The rise in economic growth in nations such as China and India has led to an increase in healthcare spending. This makes it possible to invest more in cutting-edge medical technology that can enhance patient outcomes and quality of life, such as implanted infusion pumps.
Key Highlights of the Report
The global implantable infusion pumps market is segmented by product type, application, end-user, and region. Constant-rate implantable infusion pumps are the market spearhead in terms of product type. Pain management is the top application category. Throughout the forecast period, the hospitals category is expected to grow at the greatest CAGR. North America is seeing the most growth in the implantable infusion pumps market.
The market for implantable infusion pumps is driven by integration with digital health because it improves remote monitoring capabilities, makes data-driven insights for personalized medicine easier to obtain, encourages patient adherence and engagement, supports interoperability with current healthcare systems, and conforms to trends in reimbursement and regulation. The ultimate goals of these developments are to lower healthcare expenses, improve patient outcomes, and raise the standard of care generally when it comes to the treatment of chronic illnesses that call for infusion therapy. Healthcare professionals can remotely monitor patients with implanted infusion pumps due to digital health technologies. This makes it possible to track the distribution of medications in real time, identify anomalies or malfunctions, and take prompt action as needed. Additionally, better adherence to treatment plans and early problem detection are made possible by remote monitoring, which enhances patient safety and results.
It is anticipated that North America will hold the most significant global market share for implantable infusion pumps. North America is home to several of the top implantable infusion pump manufacturers and hosts major operations there. The area has a long history of investing in and innovating medical technology. North American businesses are frequently at the forefront of creating cutting-edge implanted infusion pump technologies. By directly injecting drugs, liquids, or nutrients into a patient's body, these pumps provide precise control and enhance patient outcomes. In addition, it is projected that the Asia Pacific market will grow at the quickest rate. Asian nations are making significant investments in medical research and development. As a result, sophisticated implantable infusion pump technologies have been developed and are becoming more widely used in clinical settings due to their effectiveness and affordability.
Which Key Factors Are Driving The Global Implantable Infusion Pumps Market?
The market for implantable infusion pumps is growing as a result of advancements in pump functionality, materials, and design that increase these devices' dependability and efficacy.
What Are The Main Challenges Confronting The Global Implantable Infusion Pumps Market?
Implantable infusion pumps can be prohibitively expensive for many patients and healthcare providers, making them an unaffordable option for them. This factor will restrain the growth of the global implantable infusion pumps market.
What Market Opportunities Exist For Implantable Infusion Pumps Globally?
The development of infusion pumps for revolutionary therapeutic domains like neurological disorders and autoimmune diseases, as well as collaboration with technology companies, healthcare providers, and pharmaceutical firms, are the factors generating opportunities for the implantable infusion pumps market.
Market Drivers
An Increase in the Need for Ambulatory Infusion Pumps in Home Health Environments
Providing medical care in the convenience of patients' homes as opposed to hospitals or clinics has become more and more popular. In order to manage chronic diseases or recuperate from treatments without having to stay in a hospital, ambulatory infusion pumps enable patients to receive continuous medication or fluids while they are mobile. A prolonged duration of continuous infusion of drugs or fluids is necessary for many medical diseases. To provide a consistent and regulated dosage, implantable infusion pumps offer a dependable means of delivering these drugs straight into the patient's bloodstream or to particular organs. For patients who need long-term therapy, this feature is especially helpful. Technological developments have improved the effectiveness, dependability, and user-friendliness of implanted infusion pumps. These pumps now offer features that improve patient safety and comfort in addition to the ability to deliver drugs in exact amounts. Due to technological advancements, they are now a feasible alternative for managing complicated medical disorders outside of conventional healthcare settings.
Market Restraints
The Upfront Costs Involved With Implanted Infusion Pumps
The high initial price of implantable infusion pumps prevents their widespread use. To avoid these large initial costs, many patients and healthcare professionals may choose less effective but less costly non-invasive options. Implantable infusion pumps are expensive devices; they can cost anything from several thousand to tens of thousands of dollars. The pump, catheter, and any additional parts that are required are included in this price. Anesthesia, the operating room, the surgeon, and the hospital stay are all associated with the surgical process needed to implant the infusion pump. The total cost can rise dramatically as a result of these potentially high surgical costs.
Patients frequently require thorough assessments prior to surgery, which may include imaging tests, specialist consultations, and occasionally trial treatments to ensure the pump will be suitable for their needs. These assessments increase the initial cost. The pump must be calibrated and configured after implantation to administer the prescribed dosage of medication. Multiple trips to the doctor may be necessary for this procedure, which would raise the expense of each visit.
Opportunities
Integrating AI and Machine Learning
Implantable infusion pump technology has revolutionary possibilities when AI and machine learning are integrated into it. AI has the potential to greatly improve patient care and operational efficiency by improving personalization, dependability, real-time monitoring, data analytics, security, optimization, remote capabilities, and R&D. A significant chance to enhance results and foster ongoing innovation is presented by these technologies to all parties involved in the healthcare sector. Numerous patient data points, such as genetics, lifestyle, and treatment outcomes, can be analyzed by AI algorithms. Because infusion pumps can be used to customize medicine administration, patients can be guaranteed to receive the right dosage that is customized to their needs. Prior to possible malfunctions or maintenance requirements, machine learning algorithms can identify infusion pump issues. Artificial intelligence-enabled infusion pumps have the capacity to continually track a patient's vitals and instantly modify the pace at which drugs are delivered. Based on their current physiological state, this dynamic response capability guarantees that patients receive the appropriate dosage of medication. Machine learning is capable of analyzing treatment data to find patterns and results for a sizable patient group. Clinical judgments based on this information can result in the creation of new treatment procedures and best practices.
Competitive Landscape
Key Players
A number of significant players dominate the highly competitive global market for implantable infusion pumps. A handful of the top market players are shown below, together with their respective market shares:
- BD (U.S.)
- B.Braun Melsungen AG (Germany)
- Medtronic (Ireland)
- Teleflex Incorporated (U.S.).
- AngioDynamics (U.S.)
- Novo Nordisk A/S (Denmark)
- Johnson and Johnson Services, Inc. (U.S.)
- Pfizer Inc.(U.S.)
- Baxter (U.S.)
- Smith + Nephew (U.S.)
- Hoffmann-La Roche Ltd (Switzerland)
- ZOLL Medical Corporation (U.S.)
- Thermo Fisher Scientific Inc. (U.S.)
- Others
In order to stay competitive, these organizations give priority to product innovation, expansion of their distribution channels, and mergers and acquisitions.
By creating cutting-edge ideas and goods, the foremost manufacturers in the global market for implantable infusion pumps consistently strive to stay one step ahead of the competition.
In August 2023, The FDA has approved ICU Medical, Inc.'s (US) Plum Duo infusion pump, and it will be accessible to US consumers in early 2024.
In April 2023, Vizient, Inc. (US) has awarded a contract for Innovative Technology to Fresenius Kabi (Germany) for its Ivenix Infusion System. The deal lays out terms for hospitals to assess and buy the Ivenix Infusion System.
How are Companies Performing in the Implantable Infusion Pumps Market?
Companies are implementing an array of marketing tactics, including partnerships, collaboration, regional growth, mergers and acquisitions, new product releases, and coordination, in order to gauge the interest of prospective customers and grow their clientele. For example, In phase III clinical trials, XARACOLL, a bupivacaine-collagen-matrix implant created by the Innocoll company, was investigated for postsurgical analgesia as a component of multimodal treatment for patients undergoing hernia repair. In addition, the PMDS drug delivery technology is being developed and commercialized by NanoMedical Systems (NMS), a company created by Randy Goodall, Mauro Ferrari, and Dave Saathoff. Additionally, NanoMedical Systems is creating an implantable nanofluidics device for reliable, long-term drug delivery of different medications.
An important milestone was reached by the German company Fresenius Kabi in March 2022 when their ground-breaking wireless Agilia Connect Infusion System was approved by the US FDA. The sophisticated Vigilant Software Suite-Vigilant Master Med technology is implemented into both the Agilia Syringe Pump and the Agilia Volumetric Pump that are part of this system. This accomplishment reflects a larger trend in the sector, where businesses are putting more of an emphasis on wireless connectivity to improve operational effectiveness and improve the delivery of healthcare through cutting-edge and dependable medical devices.
Prominent companies in the market for implantable infusion pumps are creating new devices, including insulin pumps, to appeal to a wider range of consumers and boost sales and profits. Medical devices called insulin pumps are made to help people with diabetes control their blood sugar levels. For example, the FDA approved the MiniMed 780G System with meal detection technology in April 2023, according to Medtronic, an Irish medical device manufacturer. Among all the automated insulin pumps on the market, this product stands out for having the lowest glucose target (as low as 100 mg/dL), which is comparable to the usual blood sugar levels of people without diabetes. With this configuration, the pump can function as a treat-to-target device, automatically adjusting basal insulin and doing autocorrections to meet a predetermined goal. It also distinguishes itself as the only pump with an infusion set that is comfortable to use for up to seven days. Advanced materials that decrease insulin preservative loss and preserve uniform insulin flow and stability-thus lowering the likelihood of infusion set occlusion-make this prolonged wear time achievable.
Summary of Key Findings
- Implantable infusion pumps are becoming increasingly necessary due to developments in technology.
- The market is segmented by product type, application, end-user, and region.
- In the market, the most prevalent product type is the constant-rate implantable infusion pumps.
- Pain management is the foremost application category.
- The hospitals category is expected to grow the fastest in terms of CAGR during the forecast period.
- In terms of market development, North America is a leader; the market is highly competitive with key players including BD (U.S.), B.Braun Melsungen AG (Germany), Medtronic (Ireland), Teleflex Incorporated (U.S.)., AngioDynamics (U.S.), Novo Nordisk A/S (Denmark), Johnson and Johnson Services, Inc. (U.S.), Pfizer Inc.(U.S.), Baxter (U.S.), Smith + Nephew (U.S.), Hoffmann-La Roche Ltd (Switzerland), ZOLL Medical Corporation (U.S.), Thermo Fisher Scientific Inc. (U.S.), and Others.
Future Outlook
- The implantable infusion pump industry is expected to increase significantly in North America, and its outlook is positive worldwide.
- The industry will continue to be driven by advantageous healthcare policies and insurance coverage for infusion therapies.
- Potential issues that could discourage patients and clinicians from selecting implantable pumps include infections, malfunctioning devices, and bad responses. These are the primary reasons impeding the industry's growth in the implantable infusion pumps sector.
- Developing new products, reaching a wider market, and maintaining competitive prices are all necessary for major businesses to stay ahead of the competition.
How the Credence Research Implantable Infusion Pumps Market Report Can Help CXOs
The Credence Research Implantable Infusion Pumps Market Report provides CXOs with an extensive market overview and comprises the following:
- Market size and growth forecast: The study offers comprehensive market estimations for implantable infusion pumps globally, broken down by product type, application, end-user, and region. Furthermore, the report includes market forecasts through 2032, derived from key drivers and trends.
- Market segmentation: The implantable infusion pumps market is divided into segments by product type, application, end user, and region in the research report. This segmentation helps CXOs understand the market and the opportunities inside each area in great depth.
- Competitive landscape: The study report provides a thorough analysis of the leading businesses in the implantable infusion pumps sector, together with details on their revenue streams, product lines, and business strategies. With this information, CXOs can assess and identify their competitors.
- Key trends and drivers: The study report analyzes and highlights the key developments and elements driving the market for implantable infusion pumps. CXOs can utilize this information to make well-informed choices regarding their plans and investments.
The Credence Research Implantable Infusion Pumps Market Report provides CXOs with insights that they may utilize to:
- Identify growth opportunities: This analysis is likely to help CXOs find fresh growth prospects in the implantable infusion pumps sector. For example, the research recognizes the hospitals' increasing requirement for implantable infusion pumps as a crucial opportunity.
- Make informed investment decisions: The study aids CXOs in making informed decisions about implantable infusion pumps. For example, it delivers information on the key variables to consider while picking solutions and evaluating suppliers.
- Develop competitive strategies: CXOs can utilize the research report to establish competitive strategies for their implantable infusion pump firms. The study paper explores the primary tactics employed by implantable infusion pump providers to set themselves apart from their rivals.
- Track market developments: By tracking market advancements, this research report could assist CXOs in remaining ahead of the curve. For example, it provides information about the latest advancements and patterns in the implantable infusion pumps industry.
The Credence Research Implantable Infusion Pumps Market Report is helpful for CXOs who want to learn more about the market and identify potential opportunities.
Segmentation
-
By Product Type
- Constant-Rate Implantable Infusion Pumps
- Variable-Rate Implantable Infusion Pumps
-
By Application
- Pain Management
- Cancer Treatment
- Diabetes Management
- Spasticity Management
- Cardiovascular Disease
-
By End User
- Hospitals
- Ambulatory Surgical Centers (ASCs)
- Home Care Settings
- Specialty Clinics
-
By Region
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
- North America
Adjacent Markets
Several adjacent markets in the implantable infusion pumps market have high revenue growth opportunities. The key adjacent markets for the implantable infusion pumps market -
Adjacent Markets |
||
| External Infusion Pumps | Wearable Drug Delivery Devices | Medical Implant Devices |
| Diabetes Management Devices | Neurological Devices | Cardiovascular Devices |
| Wound Care Management | Regenerative Medicine | Telehealth and Remote Monitoring |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic conditions such as diabetes, cancer, and cardiovascular diseases is driving demand for implantable infusion pumps, as these devices provide targeted and continuous medication delivery essential for long-term disease management.
Integration with Digital Health and Remote Monitoring
The adoption of digital health technologies, including telemedicine and remote monitoring, enhances the functionality of implantable infusion pumps by enabling real-time tracking and data-driven adjustments, improving patient adherence and outcomes.
Technological Advancements in Pump Design
Continuous innovations in pump materials, miniaturization, and programmable features have improved the safety, reliability, and usability of implantable infusion pumps, making them more attractive to both healthcare providers and patients.
Supportive Government Policies and Reimbursement
Favorable healthcare policies and reimbursement frameworks in key markets, particularly in North America and Europe, are facilitating wider adoption of implantable infusion pumps by reducing the financial burden on patients and providers.
Expansion of Home and Ambulatory Care
The shift towards home-based and ambulatory care settings is increasing the need for implantable infusion pumps, as these devices allow patients to receive continuous therapy outside of traditional hospital environments, improving quality of life and reducing hospital stays.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for implantable infusion pumps?
What is the implantable infusion pump market's projected growth rate between 2024 and 2032?
In terms of the product type, which market category is leading?
Regarding the application, which market category is in the lead?
Which end-user segment is estimated to have the highest CAGR throughout the forecast period?
In which region is the market for implantable infusion pumps expanding?
Who are the main players in the global implantable infusion pumps industry?
Which market factors are the primary drivers of the implantable infusion pumps industry?
What main market challenges prevent the growth of the implantable infusion pumps sector?
What are the main market opportunities for the implantable infusion pumps sector?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers (ASCs)
- 1.2.3 Home Care Settings
- 1.2.4 Specialty Clinics
- 1.3 By Application
- 1.3.1 Pain Management
- 1.3.2 Cancer Treatment
- 1.3.3 Diabetes Management
- 1.3.4 Spasticity Management
- 1.3.5 Cardiovascular Disease
- 1.4 By Product Type
- 1.4.1 Constant-Rate Implantable Infusion Pumps
- 1.4.2 Variable-Rate Implantable Infusion Pumps
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 605.1 million → 2032: USD 964.43 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Implantable Infusion Pumps Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Implantable Infusion Pumps Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Implantable Infusion Pumps Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Implantable Infusion Pumps Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Implantable Infusion Pumps Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Implantable Infusion Pumps Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Implantable Infusion Pumps Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Implantable Infusion Pumps Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 605.1 million → 2032: USD 964.43 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Implantable Infusion Pumps Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers (ASCs)
- 12.3.7.3 Home Care Settings
- 12.3.7.4 Specialty Clinics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pain Management
- 12.4.7.2 Cancer Treatment
- 12.4.7.3 Diabetes Management
- 12.4.7.4 Spasticity Management
- 12.4.7.5 Cardiovascular Disease
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Constant-Rate Implantable Infusion Pumps
- 12.5.7.2 Variable-Rate Implantable Infusion Pumps
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Implantable Infusion Pumps End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Implantable Infusion Pumps Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Implantable Infusion Pumps Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Implantable Infusion Pumps Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BD (Becton, Dickinson and Company)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 B. Braun Melsungen AG
- 18.4 Medtronic
- 18.5 Teleflex Incorporated
- 18.6 AngioDynamics
- 18.7 Novo Nordisk A/S
- 18.8 Johnson & Johnson Services, Inc.
- 18.9 Pfizer Inc.
- 18.10 Baxter International Inc.
- 18.11 Smith+Nephew
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

