
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
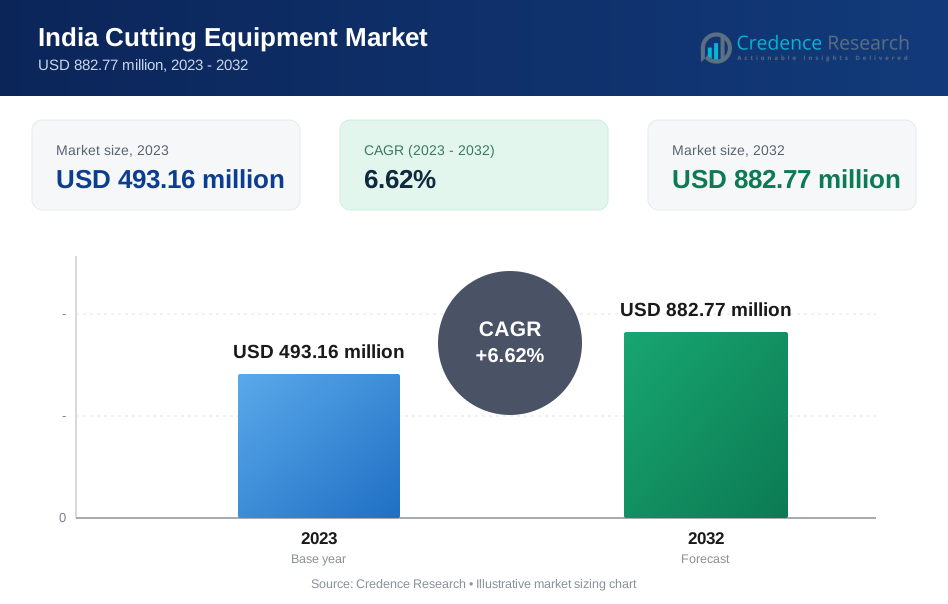
| India Cutting Equipment Market Size 2023 | USD 493.16 Million |
| India Cutting Equipment Market, CAGR | 6.62% |
| India Cutting Equipment Market Size 2032 | USD 882.77 Million |
Market Overview
The India Cutting Equipment Market is projected to grow from USD 493.16 million in 2023 to an estimated USD 882.77 million by 2032, with a compound annual growth rate (CAGR) of 6.62% from 2024 to 2032. This significant growth reflects the increasing demand for cutting equipment across various industries, including automotive, aerospace, and construction.
Key market drivers include the growing industrialization and infrastructure development in India, which demand high-quality cutting equipment for efficient operations. Additionally, technological advancements, such as the integration of automation and robotics in cutting processes, are further propelling market growth. Trends in the market indicate a shift towards eco-friendly and energy-efficient cutting solutions, driven by stringent environmental regulations and the need for sustainable manufacturing practices.
Geographically, we segment the market into North, South, East, and West India, with the western region holding the largest market share due to its industrial hubs and strong economic activity. Key players in the India Cutting Equipment Market include ESAB India Limited, Ador Welding Ltd., and Hypertherm India, among others. These companies are focusing on product innovation and strategic collaborations to strengthen their market position and cater to the evolving demands of the Indian market.
Market Drivers
Rapid Industrialization and Infrastructure Development
India is undergoing a significant transformation driven by rapid industrialization and infrastructure development. The government's focus on initiatives like "Make in India" and infrastructure development projects such as smart cities, highways, and industrial corridors is boosting demand for cutting equipment. For instance, the “Bharatmala Pariyojana” project, which aims to construct 34,800 km of highways, is one such initiative that requires high precision and efficient cutting tools for constructing and manufacturing components, leading to a surge in demand. The construction sector, in particular, needs advanced cutting equipment to handle various materials such as steel, concrete, and composites, ensuring structural integrity and quality. Additionally, industrial growth in sectors like automotive, aerospace, and heavy machinery is further driving the need for cutting equipment. As these industries expand, they invest in state-of-the-art cutting tools to enhance productivity, meet quality standards, and reduce production costs.
Technological Advancements and Automation
The cutting equipment market in India is experiencing a technological revolution. Innovations in cutting technology, such as laser cutting, plasma cutting, and waterjet cutting, are significantly enhancing precision, speed, and efficiency. For instance, the introduction of fiber laser cutting machines, which are known for their precision and speed, has revolutionized the metal fabrication industry in India. The integration of automation and robotics into cutting processes is a key driver for market growth. Automated cutting systems reduce human error, increase productivity, and enable manufacturers to achieve complex cuts with high accuracy. Moreover, advancements in computer numerical control (CNC) machines are revolutionizing the industry. CNC machines offer unparalleled precision and repeatability, making them indispensable in modern manufacturing. These technological advancements cater to various industries, including automotive, electronics, and aerospace, where intricate and precise cuts are crucial. The ability to program and control cutting operations remotely through software also improves efficiency and reduces downtime.
Rising Demand for Precision and Quality in Manufacturing
The manufacturing sector in India is increasingly emphasizing precision and quality, driving the demand for advanced cutting equipment. As industries strive to meet global standards and deliver high-quality products, the need for cutting tools that offer superior accuracy and clean finishes has become paramount. Sectors such as automotive, aerospace, electronics, and consumer goods rely heavily on cutting equipment to achieve intricate designs and maintain tight tolerances. For instance, in the automotive industry, cutting equipment is essential for manufacturing components such as engine parts, body panels, and exhaust systems. The aerospace sector demands cutting tools for producing aircraft components that meet stringent safety and performance standards. Additionally, the electronics industry requires precise cutting for circuit boards and electronic components. The emphasis on precision and quality is driving manufacturers to invest in cutting-edge cutting equipment to enhance their competitive edge.
Increasing Adoption of Sustainable and Energy-Efficient Solutions
Sustainability has become a critical consideration for industries worldwide, including India. The growing awareness of environmental issues and the need to reduce carbon footprints are driving the adoption of sustainable and energy-efficient cutting solutions. Traditional cutting methods often involve significant energy consumption and material wastage. However, modern cutting equipment, such as laser and waterjet cutting, offers energy-efficient alternatives that minimize waste and reduce environmental impact. Laser cutting, for instance, uses focused laser beams to cut materials with high precision, reducing material wastage and energy consumption. Waterjet cutting, on the other hand, uses high-pressure water to cut materials without generating heat, eliminating the risk of thermal distortion and reducing energy usage. The push for sustainability is also prompting manufacturers to explore eco-friendly materials and processes, further boosting the demand for advanced cutting equipment. Companies that prioritize sustainability not only comply with environmental regulations but also gain a competitive advantage by appealing to environmentally conscious consumers.
Market Trends
Adoption of Advanced Cutting Technologies
The India Cutting Equipment Market is witnessing a significant shift towards the adoption of advanced cutting technologies. Industries are increasingly incorporating technologies such as laser cutting, plasma cutting, and waterjet cutting into their operations. For instance, laser cutting, which is gaining traction due to its ability to provide high precision and clean cuts, is being used in the automotive industry for cutting body panels and engine components with minimal material wastage. Plasma cutting is favored for its efficiency in cutting thick materials like steel and aluminum, while waterjet cutting is appreciated for its versatility and ability to cut a wide range of materials without generating heat, thus avoiding thermal distortion. The integration of computer numerical control (CNC) systems with these cutting technologies is further enhancing operational efficiency and accuracy, allowing manufacturers to achieve higher productivity and consistency in their production processes. This trend is driven by the need to stay competitive in a global market that demands high-quality products and rapid turnaround times.
Emphasis on Automation and Industry 4.0
Automation and the principles of Industry 4.0 are transforming the cutting equipment market in India. Companies are increasingly adopting automated cutting systems that integrate robotics and artificial intelligence (AI) to streamline operations and reduce manual intervention. These systems not only enhance precision and repeatability but also significantly reduce production time and labor costs. For instance, automated laser cutting machines equipped with AI can optimize cutting paths, detect and correct errors in real-time, and adjust parameters to ensure consistent quality. This automation trend is aligned with the broader movement towards smart manufacturing, where interconnected machines and data analytics enable real-time monitoring and optimization of production processes. Furthermore, the use of Internet of Things (IoT) technology in cutting equipment enables predictive maintenance, reduces downtime, and extends the machinery's lifespan. By leveraging these advanced technologies, manufacturers can improve their operational efficiency, reduce costs, and enhance their overall competitiveness. The emphasis on automation and Industry 4.0 is not only reshaping the cutting equipment market but also driving the broader industrial transformation in India, positioning the country as a hub for advanced manufacturing.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
One of the significant restraints in the India Cutting Equipment Market is the high initial investment and ongoing maintenance costs associated with advanced cutting technologies. While laser, plasma, and waterjet cutting machines offer high precision and efficiency, they also require substantial capital expenditure for acquisition and setup. Small and medium-sized enterprises (SMEs), which form a large part of India’s manufacturing sector, often find it challenging to allocate the necessary funds for these advanced machines. Additionally, the sophisticated nature of these technologies necessitates regular maintenance and specialized training for operators, further increasing operational costs. These financial barriers can slow down the adoption rate of advanced cutting equipment among smaller manufacturers, limiting market growth. The challenge is compounded by the need for continuous upgrades to keep pace with technological advancements, which can be financially burdensome for many companies.
Lack of Skilled Workforce and Training
Another critical challenge facing the India Cutting Equipment Market is the shortage of a skilled workforce proficient in operating and maintaining advanced cutting technologies. The integration of cutting-edge equipment such as CNC machines, laser cutters, and automated systems requires specialized knowledge and technical expertise. However, there is a significant skills gap in the industry, with many workers lacking the necessary training to handle these sophisticated machines effectively. This skills deficit can lead to suboptimal use of cutting equipment, increased downtime, and higher chances of operational errors, ultimately affecting productivity and quality. Moreover, the rapid pace of technological innovation demands continuous training and upskilling of the workforce, which can be both time-consuming and costly for companies. Addressing this challenge requires concerted efforts from industry stakeholders, including investments in education and training programs, partnerships with technical institutes, and on-the-job training initiatives to build a competent and adaptable workforce capable of leveraging advanced cutting technologies effectively.
Market Segmentation Analysis
By Technology
Plasma cutting technology is widely used for its efficiency in cutting thick materials like steel and aluminum, favored for its speed and versatility in heavy industrial applications, driven by growing demand in the automotive and construction sectors. Waterjet cutting is gaining popularity for its precision and ability to cut a variety of materials without generating heat, making it ideal for intricate designs in the aerospace, automotive, and electronics industries. Flame cutting, or oxy-fuel cutting, remains a cost-effective and simple method for cutting thick steel plates and heavy metals, commonly used in construction and heavy machinery manufacturing. Additionally, laser cutting is appreciated for its precision and minimal material wastage in complex shapes, while mechanical cutting tools like saws and shears are preferred for their simplicity and low cost in specific applications.
By End User
The India Cutting Equipment Market serves a diverse array of industries, with the automotive sector being one of the largest consumers due to its need for high-precision tools for manufacturing components like body panels, engine parts, and exhaust systems. The aerospace and defense industries demand cutting equipment capable of handling high-strength materials with stringent specifications, often utilizing advanced technologies such as laser and waterjet cutting. In the rapidly growing electrical and electronics sector, precise tools are essential for producing intricate components like circuit boards and connectors. The construction industry relies on cutting equipment for applications involving steel bars, concrete, and other building materials, driven by ongoing infrastructure development projects. Additionally, other end-users, including shipbuilding, furniture manufacturing, and general fabrication, require a variety of cutting technologies to meet their diverse material and design needs.
Segments
Based on Technology
- Plasma Cutting
- Waterjet Cutting
- Flame Cutting
- Other Technologies
Based on End User
- Automotive
- Aerospace and Defense
- Electrical and Electronics
- Construction
- Other End-Users
Based on Region
- North India
- South India
- East India
- West India
Regional Analysis
North India (28%):
North India holds a significant share of the India Cutting Equipment Market, accounting for approximately 28% of the market. The region's dominance stems from its robust industrial base, especially in the automotive and electronics manufacturing sectors. Major cities like Delhi, Gurgaon, and Noida serve as industrial hubs, attracting investments in advanced manufacturing technologies. The presence of numerous automotive manufacturers and component suppliers necessitates the use of cutting-edge cutting equipment to maintain high production standards and efficiency. Additionally, North India's burgeoning construction sector, supported by government initiatives for infrastructure development, further fuels the demand for robust cutting tools and technologies.
South India (24%):
South India accounts for approximately 24% of the India Cutting Equipment Market. This region is emerging as a significant player due to its growing aerospace and defense sectors, particularly in cities like Bengaluru, Chennai, and Hyderabad. These cities are home to major aerospace and defense companies, research institutions, and innovation centers, driving the need for advanced cutting technologies such as laser and waterjet cutting. The region's focus on high-tech industries, coupled with its robust manufacturing infrastructure, supports the adoption of state-of-the-art cutting equipment. Additionally, South India's electronics manufacturing sector contributes to the demand for precision cutting tools, essential for producing intricate electronic components.
Key players
- The Lincoln Electric Company
- Messer Cutting Systems
- Colfax Corporation
- Linde Group
- Struers
- Ador Welding Ltd.
- GCE Group
- Amada Miyachi
- Koike Aronson, Inc.
- Bystronic Laser AG
Competitive Analysis
The India Cutting Equipment Market is characterized by intense competition among leading players who strive to innovate and expand their market presence. The Lincoln Electric Company and Messer Cutting Systems lead the market with advanced technologies and comprehensive product portfolios. Colfax Corporation and Linde Group leverage their global reach and extensive experience to maintain a competitive edge. Struers and Ador Welding Ltd. are known for their high-quality products and strong customer relationships. GCE Group and Amada Miyachi emphasize precision and efficiency in their cutting solutions, catering to niche markets. Koike Aronson, Inc. and Bystronic Laser AG focus on technological advancements and automation to meet the evolving demands of the industry. These key players continually invest in R&D, strategic partnerships, and acquisitions to enhance their product offerings and strengthen their market position in the competitive landscape.
Recent Developments
Founded in 1871 in Chiyoda-ku, Tokyo, Japan, Mitsubishi Materials Corporation (MMC) is a prominent Japanese manufacturing company. MMC produces a diverse range of products, including cement, copper and aluminum products, electronic materials, and cemented carbide tools. In April 2022, the Mitsubishi Materials Corporation Metalworking Solutions Company expanded its product portfolio by introducing two double-sided inserts: a wiper type and a precision grade M class type. These new inserts aim to enhance the company's offerings and provide more precise and efficient solutions for various industrial applications.
In July 2022, Lincoln Electric launched the POWER MIG 215 MPi multi-process welder. This lightweight, dual-input voltage machine features a new ergonomic design, making it user-friendly and versatile for different welding tasks. The innovative design of the POWER MIG 215 MPi aims to provide improved comfort and efficiency for welders, catering to a wide range of applications. This introduction highlights Lincoln Electric's commitment to developing advanced welding solutions that meet the evolving needs of the industry.
In February 2022, Messer Cutting Systems acquired Flame Technologies, Inc. (Flame Tech), a US-based manufacturer specializing in oxyfuel products, through an affiliate company. This acquisition strengthens Messer Cutting Systems' position as a leading international provider of oxyfuel, steel mill, and pre-heating solutions. By integrating Flame Tech's expertise and product range, Messer Cutting Systems aims to enhance its global offerings and deliver more comprehensive solutions to its customers in the metalworking industry.
In July 2022, Lincoln Electric introduced the lightweight, dual-input voltage POWER MIG 215 MPi multi-process welder. Featuring a new ergonomic design, this machine is designed to provide improved user comfort and versatility for various welding applications. The POWER MIG 215 MPi highlights Lincoln Electric's dedication to innovation and customer-focused solutions, offering a state-of-the-art welder that meets the demands of modern welding professionals.
Market Concentration and Characteristics
The India Cutting Equipment Market is characterized by a moderate-to-high level of market concentration, dominated by a few key players such as The Lincoln Electric Company, Messer Cutting Systems, and Ador Welding Ltd. These companies leverage their extensive experience, technological innovations, and robust distribution networks to maintain a competitive edge. The market is marked by a diverse range of cutting technologies including plasma, waterjet, flame, and laser cutting, catering to various industrial applications such as automotive, aerospace, construction, and electronics. Increasing demand for precision, efficiency, and automation in manufacturing processes drives continuous innovation and product development in this sector.
Report Coverage
The research report offers an in-depth analysis based on Technology, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness ongoing innovations in cutting technologies, such as laser and waterjet cutting, enhancing precision, efficiency, and material versatility.
- The growth of the automotive and aerospace sectors in India will drive demand for advanced cutting equipment to meet stringent manufacturing standards.
- The integration of automation and robotics in cutting processes will become more prevalent, reducing manual intervention, increasing productivity, and ensuring higher accuracy.
- Government initiatives for infrastructure development, such as smart cities and industrial corridors, will boost the demand for robust and efficient cutting tools.
- There will be a rising focus on sustainable and energy-efficient cutting solutions to comply with environmental regulations and reduce the industry's carbon footprint.
- The need for a skilled workforce proficient in advanced cutting technologies will drive investments in training and education programs, enhancing operational efficiency.
- Indian manufacturers will expand their capabilities by adopting cutting-edge cutting equipment to compete globally and meet the demands of international markets.
- The adoption of Industry 4.0 principles, including IoT and data analytics, will enable real-time monitoring and optimization of cutting processes, improving overall efficiency.
- The market will see intensified competition as both domestic and international players strive to innovate and capture larger market shares through strategic partnerships and acquisitions.
- Different regions in India will experience varied growth rates, with North and West India leading due to their established industrial bases, while South India will emerge rapidly with its focus on high-tech industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the India Cutting Equipment Market?
What are the key drivers of growth in the India Cutting Equipment Market?
Which industries are major consumers of cutting equipment in India?
What technological trends are shaping the India Cutting Equipment Market?
Who are the leading players in the India Cutting Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Cutting Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Cutting Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 493.16 million → 2032: USD 882.77 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Cutting Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Cutting Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Cutting Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Cutting Equipment Market Drivers
- 3.3 India Cutting Equipment Market Restraints & Challenges
- 3.4 India Cutting Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Cutting Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Cutting Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Cutting Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Cutting Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Cutting Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Cutting Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Cutting Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Cutting Equipment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Cutting Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Cutting Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Cutting Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Cutting Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Cutting Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Cutting Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Cutting Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Cutting Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Cutting Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Cutting Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Cutting Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
