
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2026-2032 |
| India Managed Services Market Size 2024 | USD 7,578.13 million |
| India Managed Services Market, CAGR | 10.05% |
| India Managed Services Market Size 2032 | USD 16,270.76 million |
Market Overview
The India Managed Services Market is projected to grow from USD 7,578.13 million in 2024 to USD 16,270.76 million by 2032, with a compound annual growth rate (CAGR) of 10.05%.
The India Managed Services market is driven by the increasing demand for cost-effective IT solutions, enabling businesses to optimize operations and reduce overhead costs. As organizations adopt digital transformation strategies, the need for managed services in areas such as cloud computing, cybersecurity, and data management is rising. The growing adoption of artificial intelligence (AI) and machine learning (ML) technologies further boosts the demand for specialized IT management services. Additionally, the shift towards remote work and hybrid models has increased reliance on managed service providers to ensure seamless IT infrastructure management. The market is also benefiting from the rise in small and medium-sized enterprises (SMEs) leveraging managed services for enhanced scalability and operational efficiency. Trends such as automation, the proliferation of Internet of Things (IoT) devices, and the increased focus on data security are driving innovation and fueling market growth in India.
India's Managed Services market is geographically diverse, with key regions including the Northern, Western, Southern, and Eastern parts of the country, each experiencing different levels of growth and demand. Northern India, home to major business hubs like Delhi and Noida, leads the market with a strong focus on IT services and infrastructure management. The Western region, with cities like Mumbai and Pune, is known for its robust financial and technology sectors. Southern India, particularly Bengaluru, is emerging as a hotspot for startups and SMEs adopting managed IT services. Eastern India, though smaller in market size, is seeing growth in sectors like manufacturing and healthcare. Key players in India’s Managed Services market include global giants such as Microsoft Corporation, Accenture, Cisco Systems, Google LLC, IBM, and regional leaders like TCS, HCLTech, Infosys, and Wipro. These companies drive innovation and provide a wide range of IT solutions to businesses across the country.
Market Insights
- The India Managed Services market is valued at USD 7,578.13 million in 2024 and is expected to reach USD 16,270.76 million by 2032, growing at a CAGR of 10.05%.
- Increasing adoption of cloud-based services and IT outsourcing drives demand for managed services across various industries.
- The integration of AI and automation technologies is improving service delivery, efficiency, and scalability.
- Data security and regulatory compliance concerns are pushing businesses to adopt managed security services.
- The competitive landscape includes major players like Microsoft, Accenture, Cisco, and TCS, with regional players also gaining traction.
- High dependence on skilled talent and the complexity of managing diverse IT infrastructures pose challenges for service providers.
- Northern and Western India dominate the market, while Southern and Eastern regions show growing demand due to digital transformation and government initiatives.
Market Drivers
Adoption of Digital Transformation
India’s push towards digital transformation is significantly driving the demand for managed services. As organizations across industries adopt cloud computing, big data analytics, and other digital technologies, they require expert IT management to ensure seamless integration and operation. For instance, the Digital India initiative has been instrumental in promoting digital transformation across the country, with significant investments in digital infrastructure and services. Managed services providers offer the necessary infrastructure and support to facilitate these transitions, helping businesses implement and maintain advanced technologies without the need for extensive in-house expertise. This ongoing digital transformation is creating a growing market for managed IT services across India.
Growing Cybersecurity Threats
With the increasing number of cyber threats, data breaches, and security risks, businesses are turning to managed services for enhanced cybersecurity solutions. Managed services providers are equipped to offer robust security measures, including real-time monitoring, threat detection, and data protection. For instance, a report by the Data Security Council of India (DSCI) highlighted the significant rise in cyberattacks, emphasizing the need for advanced cybersecurity measures. As cybersecurity becomes a top priority for organizations, especially with the rise in digital transactions and remote work, managed services help ensure that businesses are well-protected from emerging cyber risks, creating a demand for more specialized IT services.
Increasing Demand for Cost-Effective IT Solutions
The growing need for cost-effective IT solutions is one of the key drivers of the India Managed Services market. Businesses are increasingly looking to optimize their IT infrastructure without incurring high capital expenditures. Managed services provide a flexible, subscription-based model that helps organizations reduce the costs associated with in-house IT management, hardware, and software maintenance. This cost-saving potential makes managed services particularly appealing to small and medium-sized enterprises (SMEs), which are seeking to scale efficiently while maintaining a competitive edge.
Rise of Remote Work and Hybrid Models
The shift towards remote and hybrid work models has accelerated the adoption of managed services in India. As organizations embrace flexible work environments, they need reliable IT infrastructure and support to ensure smooth communication, collaboration, and security. Managed services providers offer tailored solutions to support remote work by managing cloud-based platforms, ensuring data security, and offering continuous IT support. This trend is further driving the growth of managed services as businesses adapt to new work dynamics and seek expert management of their IT environments.
Market Trends
Rise of Cloud-Based Managed Services
One of the most prominent trends in the India Managed Services market is the increasing adoption of cloud-based services. As businesses migrate to cloud environments, the demand for managed cloud services is growing. Managed service providers are offering tailored cloud solutions that ensure scalability, flexibility, and enhanced performance. With cloud computing becoming a critical part of digital transformation, organizations are turning to managed services to oversee cloud migration, management, and optimization. This trend is helping businesses reduce the complexity of maintaining their cloud infrastructure while focusing on core operations.
Automation and Artificial Intelligence Integration
The integration of automation and artificial intelligence (AI) into managed services is another significant trend. Providers are using AI and automation to streamline processes, reduce human error, and improve service delivery. For instance, an IBM report highlighted that 59% of Indian enterprises have actively deployed AI in their operations. Automated IT management solutions, such as network monitoring, data backup, and threat detection, are increasingly being incorporated into managed services. These advancements allow businesses to enhance operational efficiency while minimizing downtime. The ability to leverage AI for predictive analytics and proactive problem-solving is driving innovation in the sector and meeting the growing demand for faster, more effective IT management.
Focus on Data Security and Compliance
With data privacy regulations becoming more stringent, businesses in India are placing a greater emphasis on data security and compliance. Managed services providers are offering specialized solutions that ensure compliance with local and international data protection laws, such as the General Data Protection Regulation (GDPR). These services are designed to protect sensitive information, maintain security standards, and support businesses in meeting regulatory requirements. As organizations face increasing pressure to safeguard their data and avoid penalties, managed services providers are evolving to meet the heightened demand for robust security and compliance solutions.
Adoption of Edge Computing
Edge computing is emerging as a key trend in the India Managed Services market. As the Internet of Things (IoT) devices proliferate, businesses are moving towards edge computing to process data closer to the source, reducing latency and improving performance. Managed service providers are offering solutions that support the deployment and management of edge computing infrastructure. This trend is gaining traction across industries like manufacturing, healthcare, and retail, where real-time data processing is crucial for operational success. Edge computing is shaping the future of managed services by enabling businesses to make faster, data-driven decisions and enhance operational capabilities.
Market Challenges Analysis
Talent Shortage and Skill Gaps
One of the significant challenges facing the India Managed Services market is the shortage of skilled professionals. As businesses increasingly rely on advanced technologies such as cloud computing, AI, and cybersecurity, the demand for qualified IT personnel has outpaced supply. Managed services providers are struggling to find employees with the necessary expertise to deliver high-quality services across these complex domains. This talent gap hampers the ability of providers to scale their operations and meet the growing market demands effectively. To address this challenge, providers need to invest in training and development programs to bridge the skills gap and ensure the availability of a competent workforce.
Data Privacy and Regulatory Compliance Issues
As data privacy concerns continue to grow, navigating regulatory compliance has become a major challenge for managed services providers in India. Organizations are under increasing pressure to meet the stringent data protection regulations enforced by the government and international bodies. For instance, the Digital Personal Data Protection Act, 2023, has introduced new compliance requirements for businesses operating in India. Managed services providers must ensure their solutions align with these regulatory requirements, which can vary across industries and regions. Failing to comply with these regulations not only exposes businesses to legal risks but also damages their reputation. Ensuring proper data handling, storage, and security while maintaining compliance with evolving regulations is a complex challenge that providers must continuously address to maintain trust and avoid costly penalties.
Market Opportunities
Expansion of Small and Medium-Sized Enterprises (SMEs)
The growing number of small and medium-sized enterprises (SMEs) in India presents a significant opportunity for the Managed Services market. As these businesses seek to scale operations while controlling costs, managed services offer a cost-effective alternative to in-house IT management. SMEs can leverage managed IT services to enhance productivity, improve cybersecurity, and support digital transformation without the need for significant capital investment in IT infrastructure. As the Indian SME sector continues to expand, the demand for outsourced managed services is expected to grow, creating new avenues for providers to tap into this untapped market segment.
Growth in Digital Transformation and Cloud Adoption
India’s accelerating digital transformation provides a considerable opportunity for the Managed Services market. With more businesses shifting to cloud-based solutions, data analytics, and automation technologies, the demand for expert management and support services is intensifying. Managed services providers can capitalize on this trend by offering customized solutions that help businesses smoothly transition to cloud environments, optimize their operations, and maintain robust cybersecurity protocols. The expansion of Internet of Things (IoT) devices and edge computing also presents new growth avenues. By providing managed services that cater to these advanced technologies, service providers can meet the evolving needs of businesses across sectors like manufacturing, healthcare, and retail, positioning themselves for long-term growth in this dynamic market.
Market Segmentation Analysis:
By Service Type:
The India Managed Services market is segmented into several service types, each addressing specific business needs. Managed IT Infrastructure & Data Center services are essential for organizations seeking efficient management of their IT assets, servers, and storage infrastructure. Managed Network services focus on providing seamless connectivity, network optimization, and ensuring high-performance networking solutions. Managed Communication & Collaboration services enable businesses to enhance their internal and external communication, including email, voice, and collaboration tools, essential for efficient operations. Managed Information services assist organizations in managing their data, ensuring accurate storage, and enabling secure data access. Managed Security services are in high demand due to the increasing need for cybersecurity, offering solutions like threat detection, firewall management, and vulnerability assessments. Additionally, the 'Others' segment includes specialized services that cater to unique business requirements, contributing to the market's diversification.
By Deployment Type:
The deployment type segment of India Managed Services is categorized into on-premise and cloud-based solutions. On-premise deployment refers to the management of IT services and infrastructure within the organization’s physical premises, providing greater control and security for businesses with specific regulatory needs. Cloud-based deployment is experiencing significant growth, driven by the increasing adoption of cloud computing among businesses in India. Cloud deployment offers businesses flexibility, scalability, and reduced upfront capital investment, making it attractive to enterprises of all sizes. The shift towards cloud solutions is further fueled by the rise in digital transformation and remote work, leading to an increased demand for cloud-based managed services. This segmentation highlights the growing shift toward cloud adoption, as businesses seek cost-effective, scalable, and secure solutions to manage their IT infrastructure.
Segments:
Based on Service Type:
- Managed IT Infrastructure & Data Center
- Managed Network
- Managed Communication & Collaboration
- Managed Information
- Managed Security
- Others
Based on Deployment Type:
- On-premise
- Cloud
Based on Enterprise Size:
- Large Enterprises
- SME’s
Based on End User:
- IT & Telecom
- BFSI
- Manufacturing
- Retail
- Government
- Others
Based on the Geography:
- Northern
- Western
- Southern
- Eastern
Regional Analysis
Northern region
The Northern region of India holds the largest market share in the Managed Services sector, accounting for approximately 35% of the total market. This is primarily driven by the presence of major business hubs such as Delhi, Gurgaon, and Noida, which house numerous multinational corporations, IT firms, and government institutions that require managed IT services for their operations. The rapid pace of digital transformation, coupled with increasing demand for cloud, network, and security services, is propelling market growth in this region. As businesses in Northern India continue to scale, the need for efficient and cost-effective IT solutions further supports the demand for managed services. This region's dominance is expected to persist, with strong market growth projected in the coming years.
Western Region
The Western region, including Maharashtra, Gujarat, and Rajasthan, accounts for around 30% of the Managed Services market in India. This region is home to key business centers like Mumbai, Pune, and Ahmedabad, where industries such as finance, technology, and manufacturing have a strong presence. Mumbai, in particular, serves as the financial capital of India and is a major driver of managed IT services, especially for cloud technologies, network management, and cybersecurity solutions. As businesses in Western India continue to expand, the demand for managed services is expected to grow, maintaining the region's significant market share. The consistent growth of sectors like banking, e-commerce, and IT services in this region is a key factor in this expansion.
Southern Region
Southern India, encompassing states like Karnataka, Tamil Nadu, Telangana, and Andhra Pradesh, holds around 25% of the total market share in the Managed Services sector. Bengaluru, a prominent tech hub, is driving demand as startups and SMEs increasingly rely on managed services for their IT infrastructure, cloud solutions, and cybersecurity needs. The region’s thriving IT ecosystem and rising adoption of digital technologies contribute to the growing market share in this segment. As more businesses in Southern India move towards automation and digital transformation, the demand for managed IT services will continue to rise, ensuring this region remains a key player in the market.
Eastern Region
The Eastern region, comprising states like West Bengal, Odisha, Bihar, and Jharkhand, currently holds around 10% of the Managed Services market share. While historically it has lagged behind other regions in terms of digital adoption, Eastern India is beginning to experience a surge in the need for managed services, especially as local industries like manufacturing, healthcare, and education seek to modernize their IT infrastructures. Government initiatives to promote technological advancements and improve digital infrastructure are contributing to this shift. Although Eastern India’s market share is smaller compared to other regions, it is expected to grow steadily, driven by increasing digital adoption and the region’s expanding IT ecosystem. As more businesses in Eastern India embrace cloud computing and data management solutions, the demand for managed services is set to increase in the near future.
Key Player Analysis
- Microsoft Corporation
- Accenture
- Cisco Systems, Inc.
- Google LLC
- IBM Corporation
- Atos
- TCS
- Deloitte
- HCLTech
- Infosys
- Capgemini
- Ericsson
- NTT DATA
- Wipro
- Others
Competitive Analysis
The competitive landscape of India’s Managed Services market is dominated by global and regional players offering a wide range of IT solutions. Leading players such as Microsoft Corporation, Accenture, Cisco Systems, Google LLC, IBM Corporation, Atos, TCS, Deloitte, HCLTech, Infosys, Capgemini, Ericsson, NTT DATA, and Wipro have a strong presence across various service segments, including IT infrastructure management, network solutions, cybersecurity, and cloud services. Companies in this space are increasingly focusing on providing integrated services like IT infrastructure management, cloud solutions, network optimization, and cybersecurity to cater to the growing needs of businesses. For example, the Data Security Council of India (DSCI) reported an increase in investments in cybersecurity solutions by managed service providers to meet the growing demand. As digital transformation accelerates, service providers are capitalizing on the demand for cloud-based solutions and automation technologies to help businesses streamline operations and reduce costs. The competition in the market is intense, with both global and regional players vying for market share. Established firms with a global presence are leveraging their extensive resources and expertise to offer comprehensive services across sectors such as healthcare, finance, and manufacturing. On the other hand, regional players are concentrating on delivering customized solutions tailored to local market needs, allowing them to differentiate themselves. The rise in demand for managed security services and the increasing focus on data protection is further intensifying competition, prompting service providers to enhance their service offerings and invest in advanced technologies. To stay competitive, many companies are also forming strategic partnerships and alliances, fostering innovation and improving service delivery.
Recent Developments
- In January 2024, Accenture acquired NaviSite to strengthen its managed services offerings, particularly in application and infrastructure management. The acquisition will enhance Accenture’s ability to assist US and Canadian clients in modernizing their digital infrastructure, focusing on AI, cloud, and data-driven solutions for digital transformation.
- In September 2024, TCS launched two AI-powered cybersecurity solutions - Managed Detection and Response (MDR) and Secure Cloud Foundation - in collaboration with Google Cloud. The MDR service was intended to offer continuous, managed threat detection and response, while Secure Cloud Foundation aimed to enhance cloud security posture and governance across hybrid environments. Both solutions leverage Google Cloud’s security tools to provide proactive enterprise protection.
- In June 2024, DXC Technology and Dell partnered to establish Enterprise Intelligence Services (EIS). This service aimed to improve managed services by combining artificial intelligence, data analytics, and cloud technology. EIS’s multi-cloud strategy was expected to help organizations streamline operations, make smarter decisions, and improve customer experiences, proving DXC’s position as the leader in managed multi-cloud solutions.
- In October 2023, technology services provider Logicalis launched an Intelligent Connectivity suite that includes solutions such as SASE, SSE, SD-WAN, and Private 5G powered by Cisco Systems, Inc. This will enable Logicalis customers to access digitally managed services developed using Cisco technology and supported by the Logicalis Digital Fabric Platform.
- In September 2023, communications & technology solution provider Cloud5 Communications launched its new managed services division. The division is designed to support the IT-related requirements & challenges in various markets, such as the hospitality industry, student housing, and senior living, among others. This division will assist consumers in efficiently managing IT operations, technology infrastructures, and security.
- In May 2023, Alfar Capital and Walter Capital Partners completed the acquisition of MSP Corp, a managed IT service provider in Canada. The MSP Corp would merge with Groupe Access, an MSP of IT and cybersecurity solutions. The acquisition would help company to deliver cutting-edge solutions and strengthen its position in Canada.
- In January 2023, Rackspace Technology, a multi-cloud technology solutions provider, launched Rackspace Technology Modern Operations, a managed service for public cloud for customers across Azure, AWS, and GCP. The service will provide benefits including 24x7x365 managed support, cloud expertise, cloud resiliency, and innovation with cloud services which help the company’s customers manage complex cloud environments.
Market Concentration & Characteristics
The market concentration of India’s Managed Services sector is moderate, with both global and regional players operating in the space, though a few large companies dominate the landscape. The sector is characterized by a mix of established multinational corporations and rapidly growing regional providers, each offering a variety of services, including IT infrastructure management, cloud solutions, cybersecurity, and network optimization. While global players leverage their vast resources, technological advancements, and broad service portfolios to cater to large enterprises, regional players often focus on more localized, customized services for small and medium-sized businesses (SMBs). The market is highly competitive, with companies continuously innovating to stay ahead by adopting emerging technologies such as automation, AI, and machine learning. The rise in digital transformation, cloud adoption, and the increasing need for robust cybersecurity solutions are key drivers fueling market dynamics. Furthermore, the growing demand for cost-effective, scalable solutions has led to the emergence of new business models, such as as-a-service offerings, enabling flexibility for clients. Companies are also responding to customer needs for more personalized services by focusing on niche markets. The evolving demand for managed services, coupled with ongoing technological advancements, ensures a dynamic and competitive market environment where providers must consistently innovate to retain their position.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Deployment Type, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The India Managed Services market is expected to experience robust growth, driven by the increasing adoption of cloud-based solutions.
- Demand for managed cybersecurity services will rise as businesses prioritize data protection and compliance.
- The growing trend of digital transformation across industries will continue to fuel the need for IT outsourcing and automation.
- More companies will shift to hybrid cloud models, driving increased demand for managed cloud services.
- The adoption of AI, machine learning, and automation will enhance service delivery and operational efficiency.
- Small and medium-sized businesses (SMBs) will increasingly embrace managed services due to their cost-effectiveness and scalability.
- Managed services providers will expand their offerings to include more specialized solutions, such as managed security and data analytics.
- The increasing focus on enterprise mobility and remote work will drive demand for managed communication and collaboration services.
- The market will see further consolidation, with larger players acquiring smaller firms to broaden their service portfolios.
- Government initiatives promoting digital adoption and infrastructure development will create new opportunities for managed services providers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India Managed Services market?
What factors are driving the growth of the India Managed Services market?
What are the key segments within the India Managed Services market?
What are some challenges faced by the India Managed Services market
Who are the major players in the India Managed Services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Managed Services Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 India Managed Services Snapshot
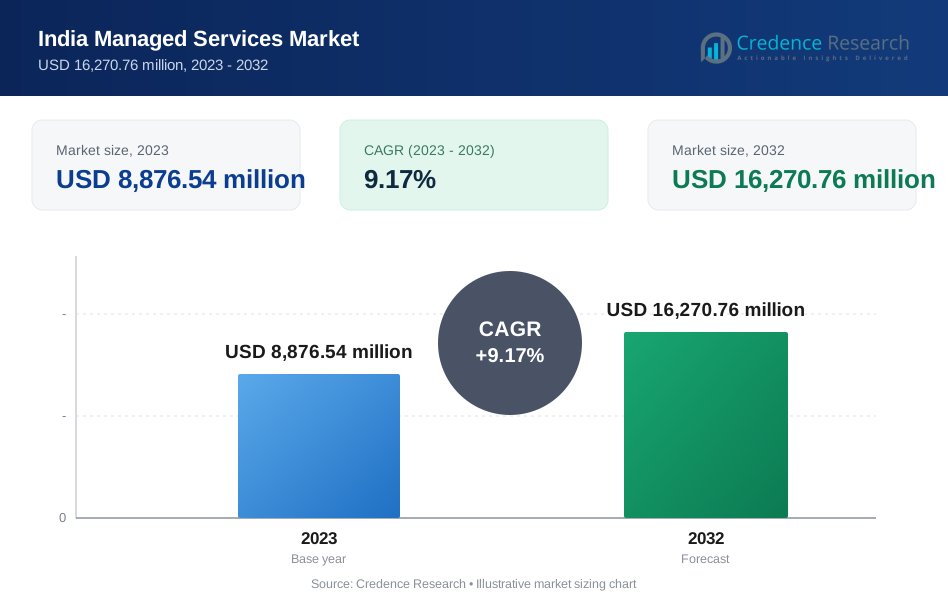
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 8,876.54 million → 2032: USD 16,270.76 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Managed Services Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Managed Services Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Managed Services Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 India Managed Services Drivers
- 3.3 India Managed Services Restraints & Challenges
- 3.4 India Managed Services Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Managed Services Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Managed Services Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Managed Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Managed Services Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. India Managed Services Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to India Managed Services in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Managed Services Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 India Managed Services Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 India Managed Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Managed Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in India Managed Services
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. India Managed Services – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. India Managed Services – Priority Domestic Market 1
Chapter 10. India Managed Services – Priority Domestic Market 2
Chapter 11. India Managed Services – Priority Domestic Market 3
Chapter 12. India Managed Services – Priority Domestic Market 4
Chapter 13. India Managed Services Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
