
Replacement buyers and radial capacity shape tire demand
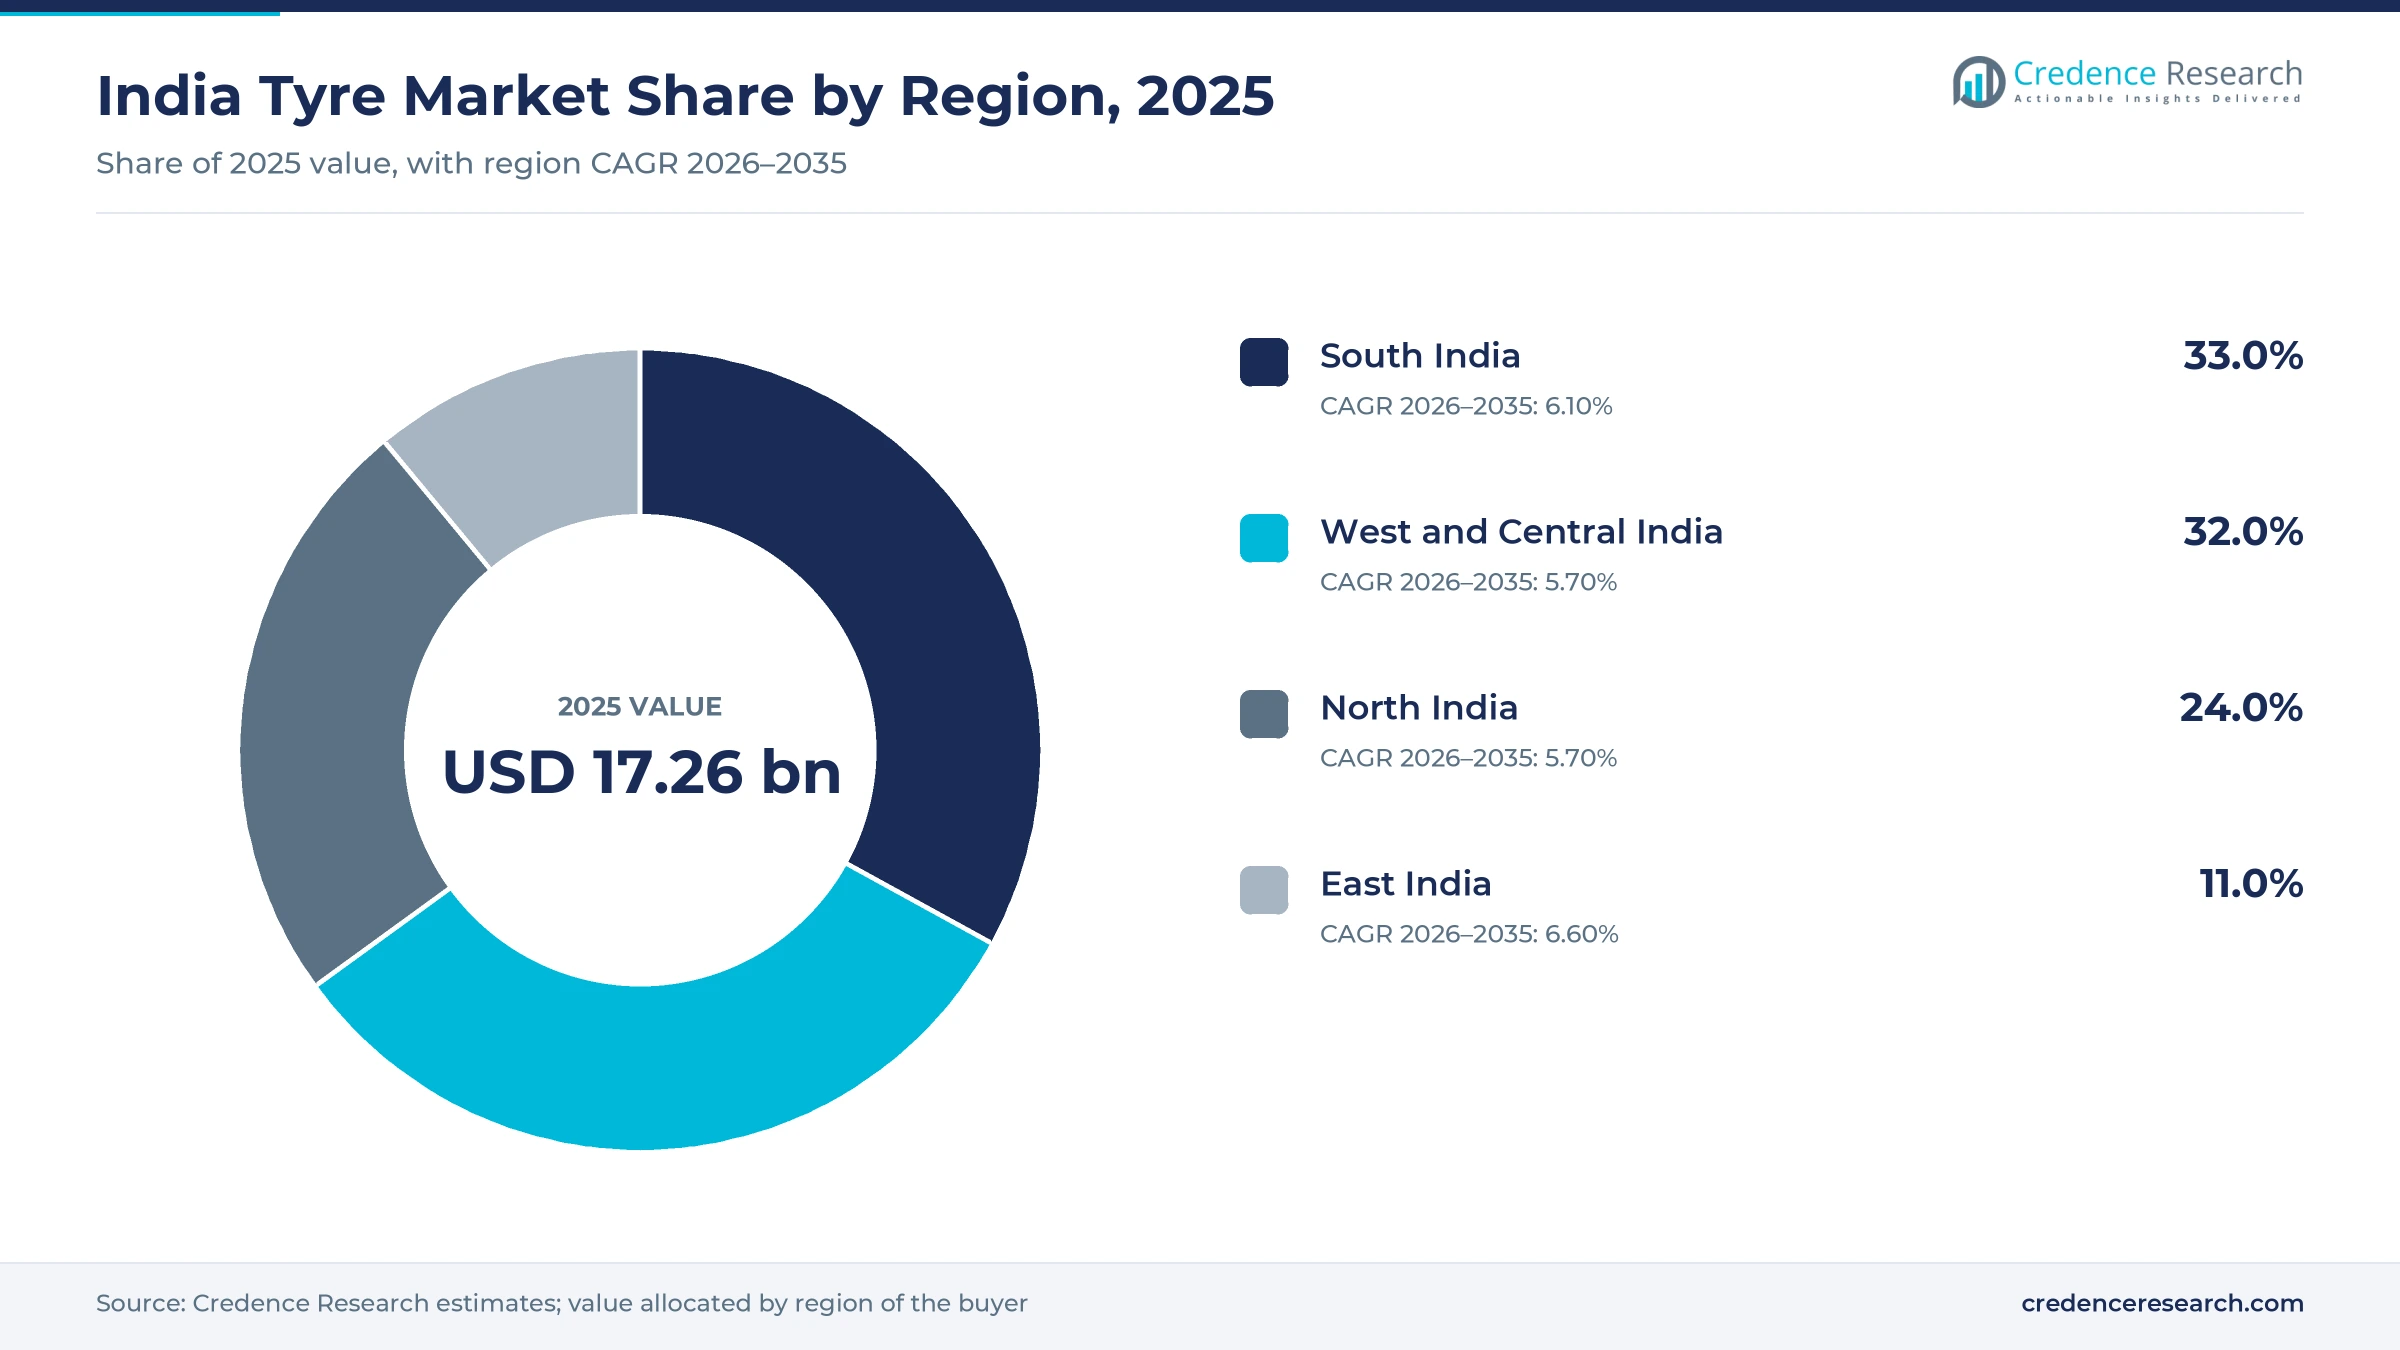
The India tyre market was valued at USD 17.26 billion in 2025 and is projected to increase from USD 18.29 billion in 2026 to USD 30.71 billion by 2035, registering a CAGR of 5.93% during 2026–2035. Demand rests on a vehicle base that added a record 28.3 million domestic wholesales in fiscal 2026, and on replacement buying, which remains the larger part of tire spending. South India held the largest regional share, 33.0% in 2025, because plants and dense vehicle ownership overlap there. East India is the fastest-growing region at 6.60% a year as distribution reaches smaller markets. The GST cut on new tires in September 2025 lowered shelf prices across vehicle classes, and it arrived just before a crude-linked jump in input costs during 2026. Makers are now running plants close to full and adding radial lines, while exports already absorb more than a quarter of output.
What does the India tyre market include and who buys?
The market counts new pneumatic tires sold in India for trucks, buses, cars, light trucks, motorcycles and special vehicles, whether fitted by vehicle makers or bought later from dealers, fleet contracts or online sellers. Buyers range from vehicle assembly plants on supply contracts to transport fleets and individual owners visiting a neighborhood tire shop.
Retreaded casings, tubes, exports and bicycle tires sit outside the value. The chain runs from natural rubber, synthetic rubber and carbon black suppliers through domestic and foreign tire makers to multi-brand dealers and exclusive outlets. Tire makers pass cost changes faster to replacement buyers than to vehicle makers.

India Tyre Market Insights
- The India tyre market rises from USD 17.26 billion in 2025 to USD 30.71 billion by 2035, a 5.93% CAGR built on replacement buying and new radial capacity.
- South India led with 33.0% of 2025 value, supported by plants around Chennai and new commitments such as the Sivaganga project in Tamil Nadu.
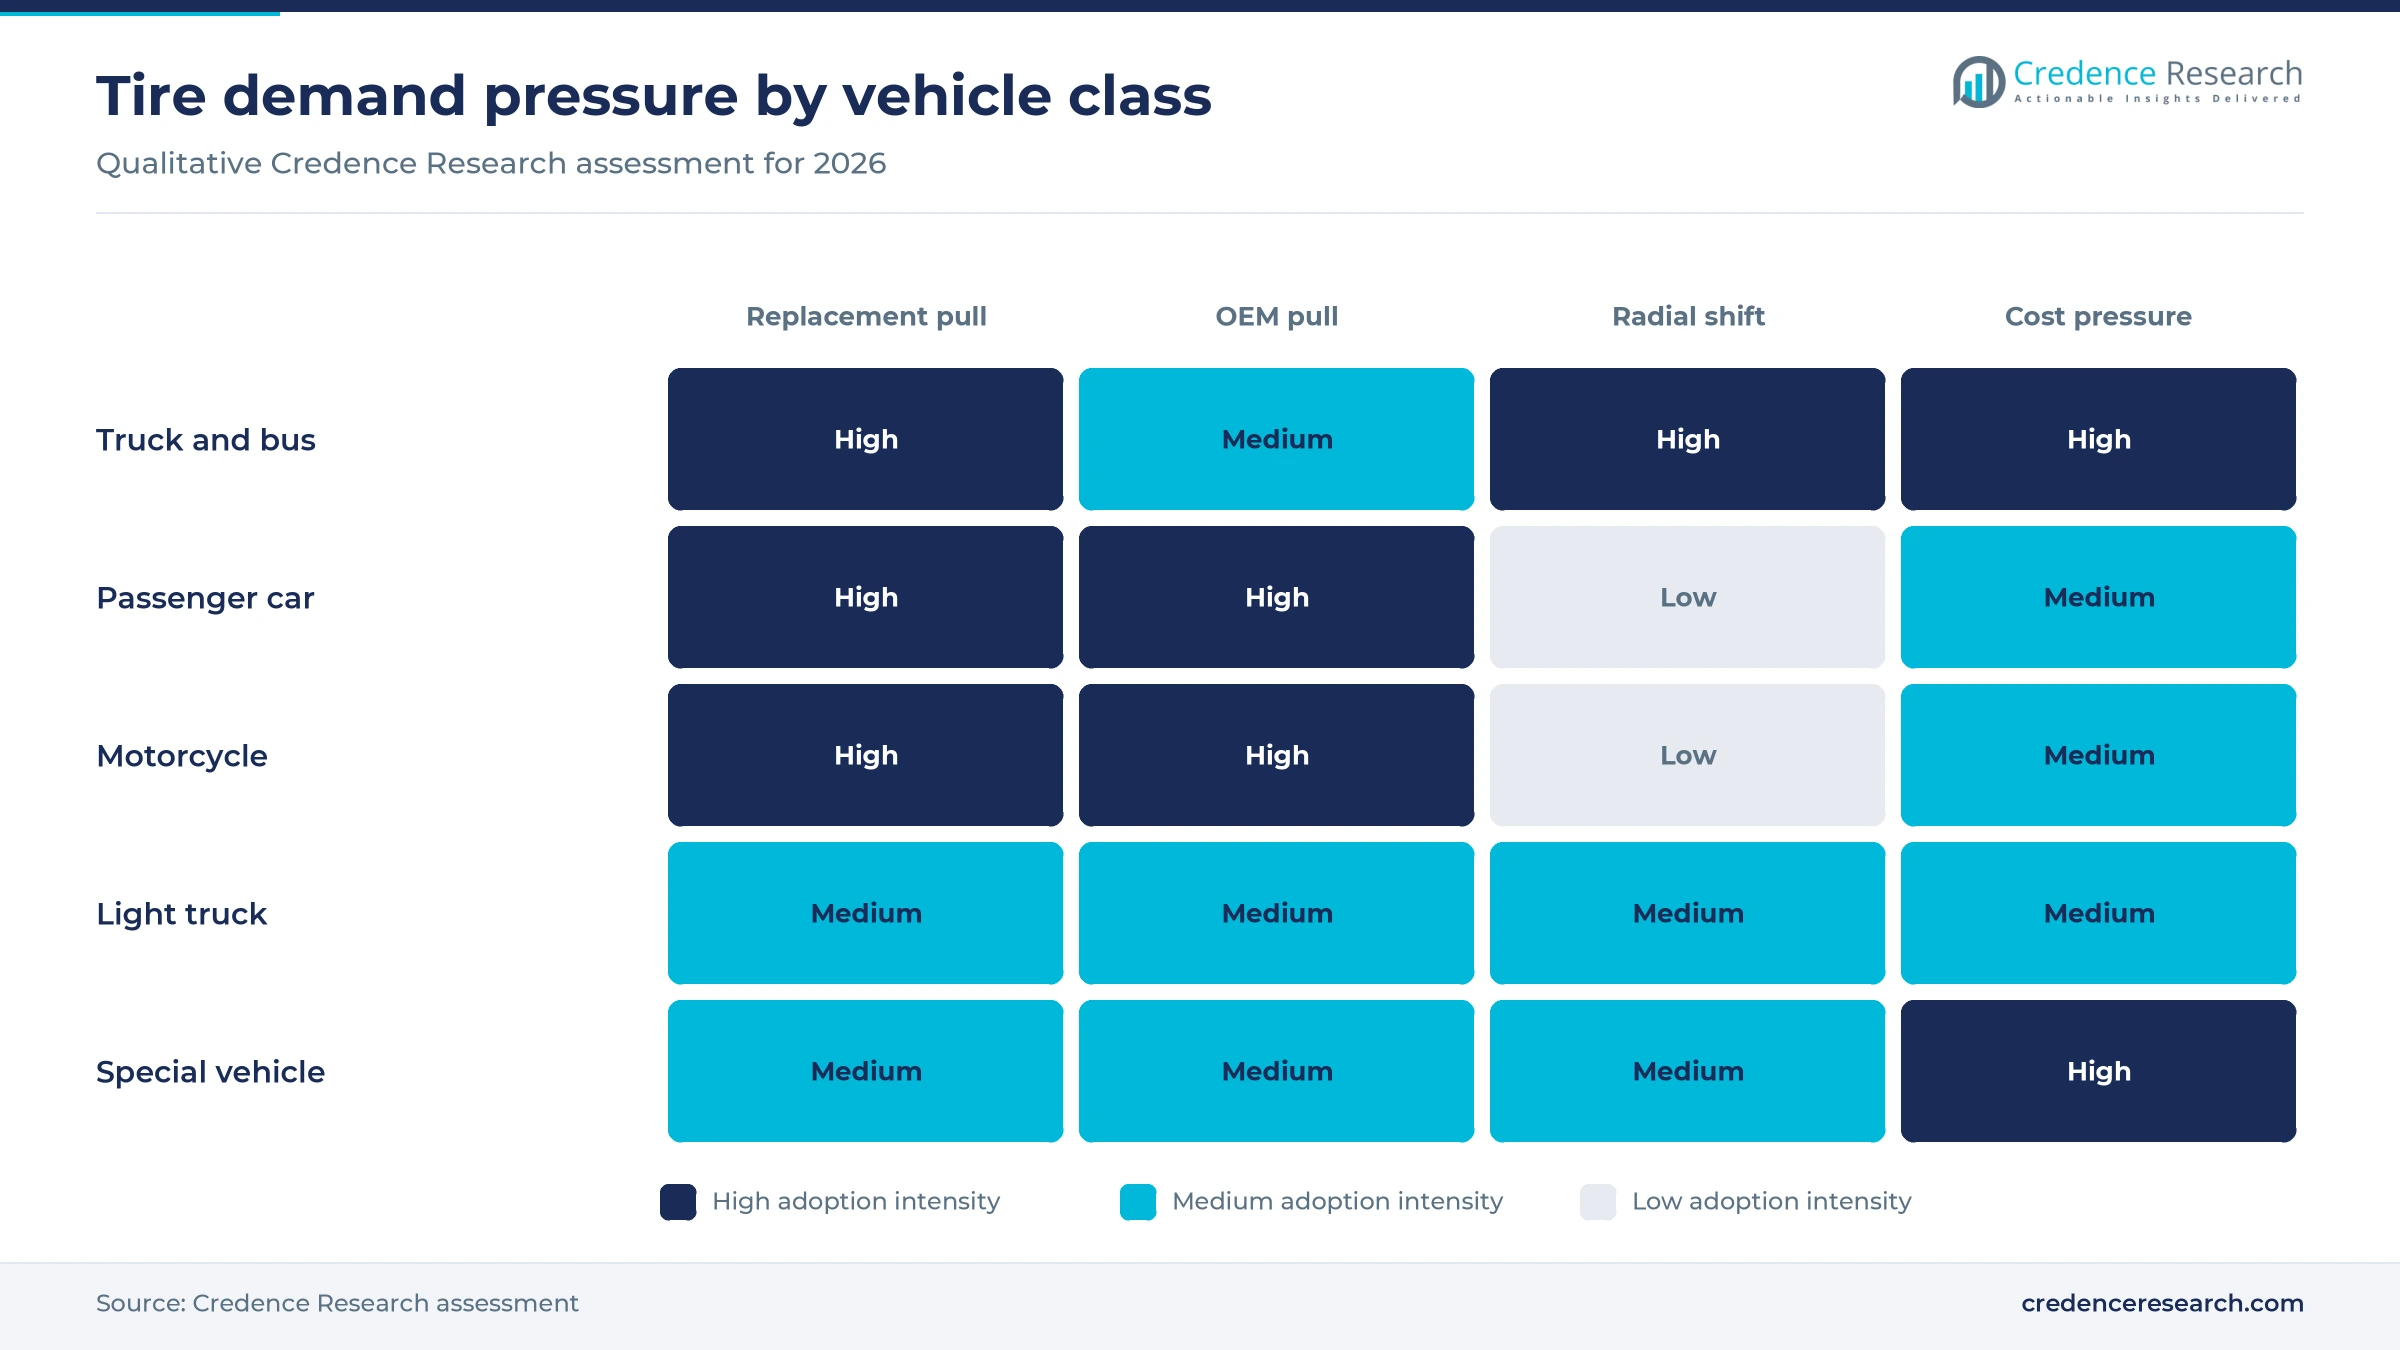
- Truck and Bus Tires led with 36.0% of 2025 value because higher prices per tire and fleet mileage outweigh the larger motorcycle unit count.
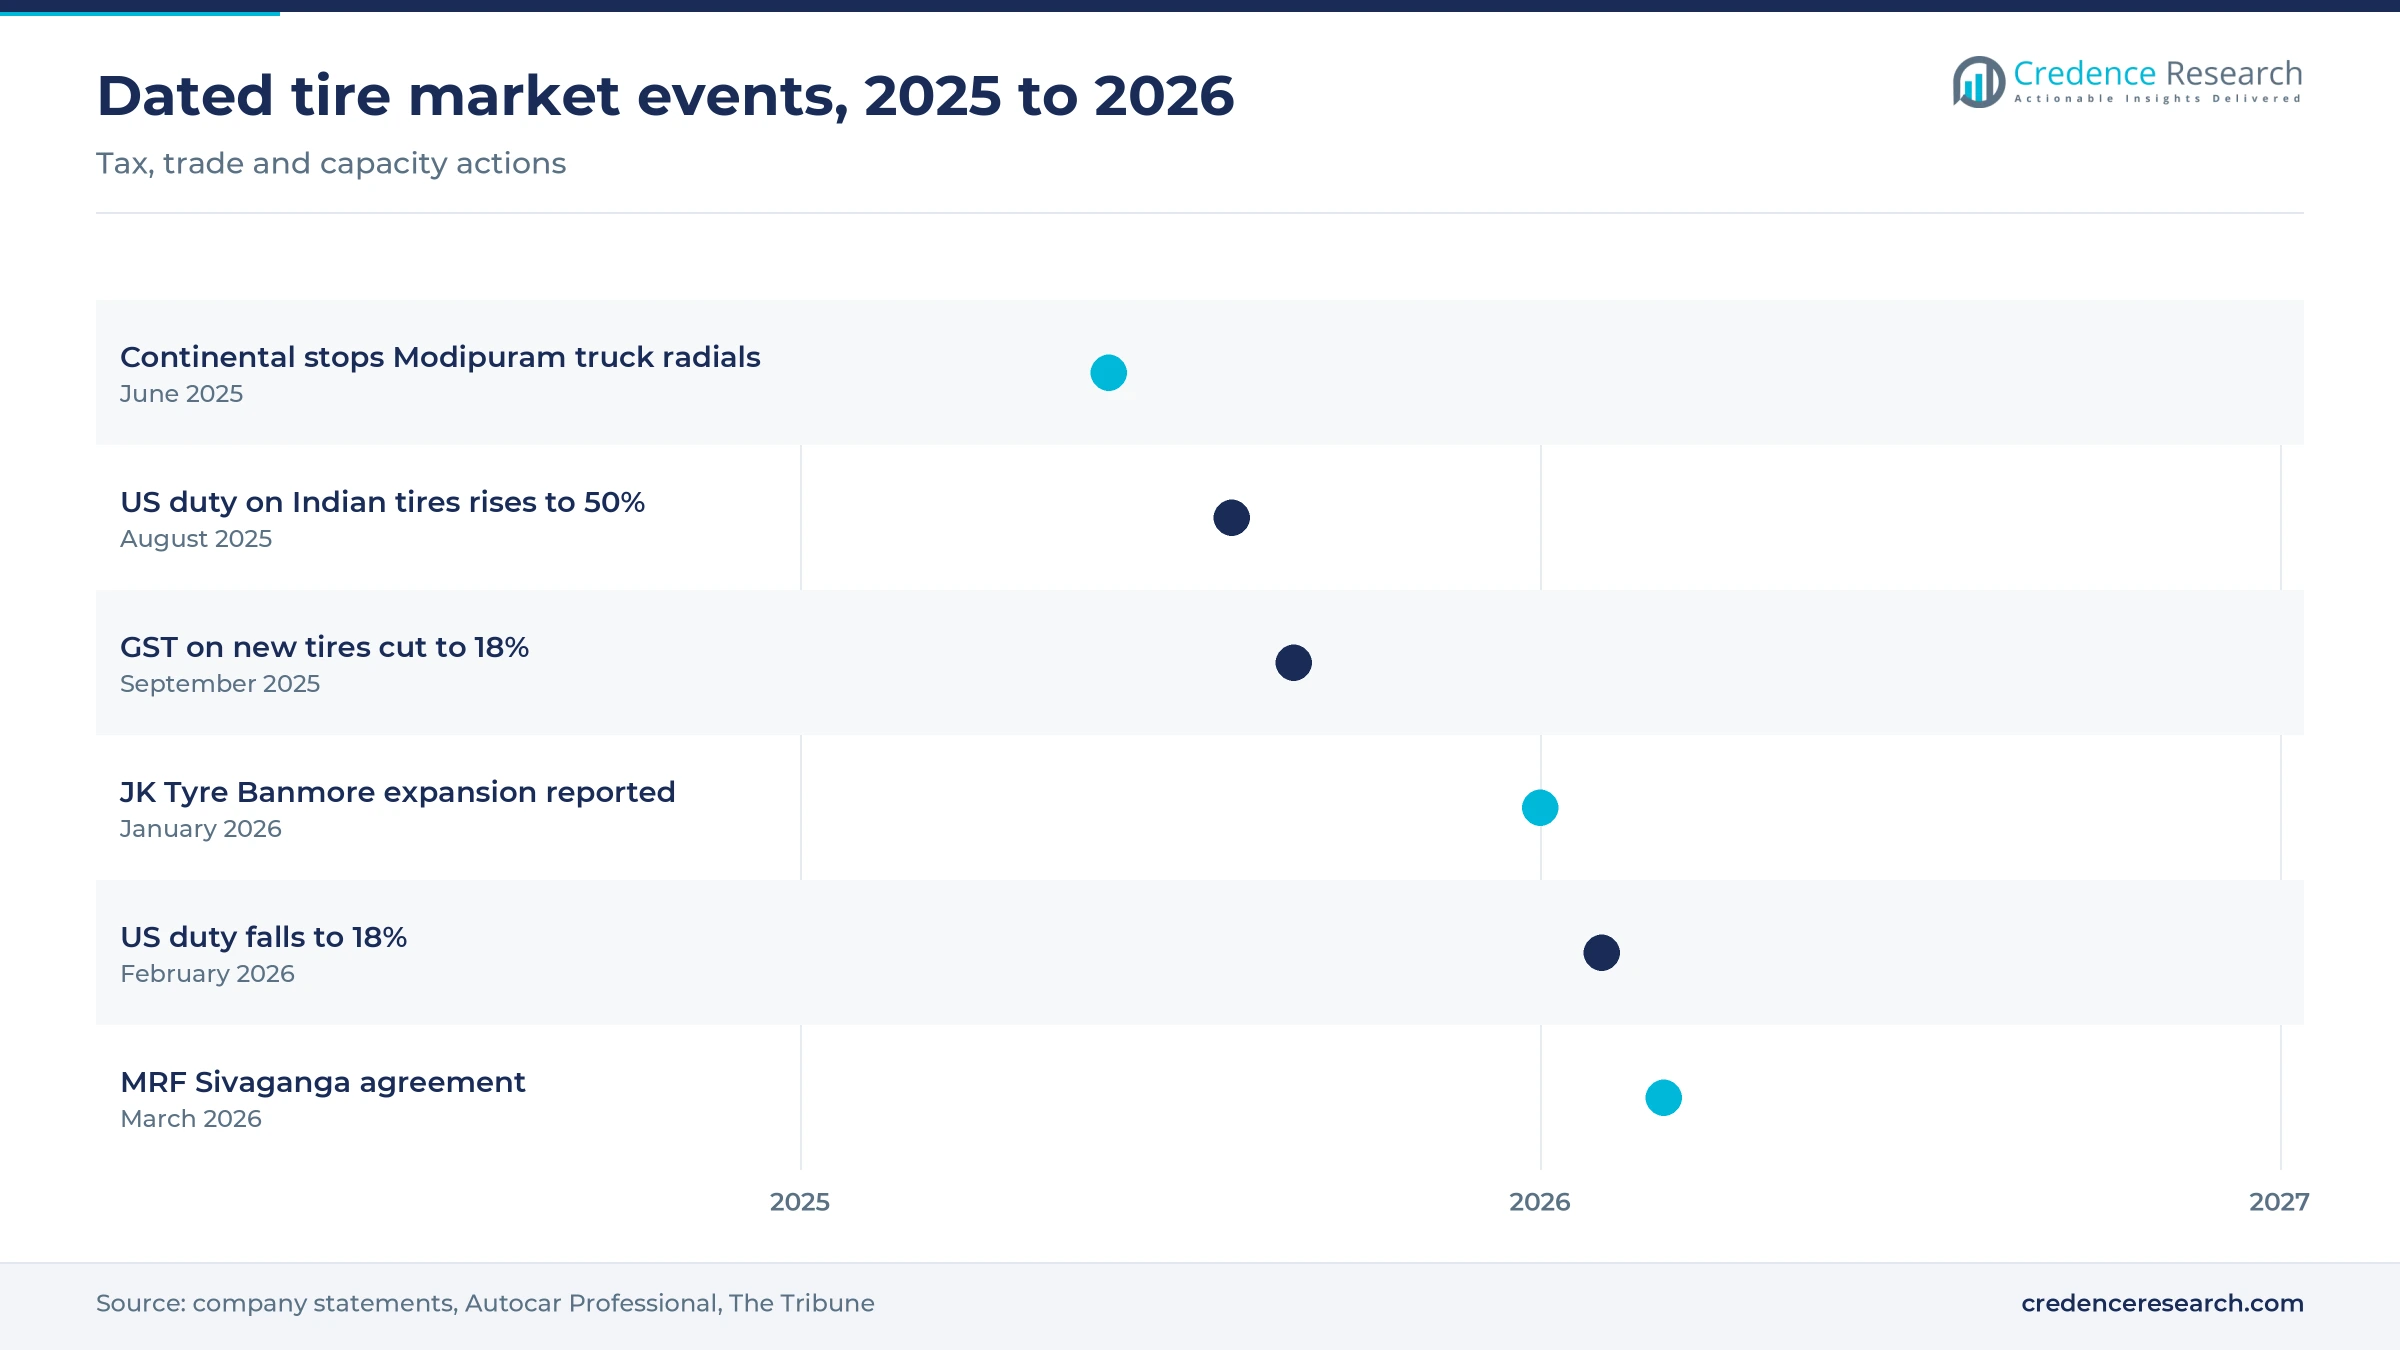
- GST on new tires fell to 18% from 28% on Sept. 22, 2025, which cut shelf prices before crude-linked input costs climbed during 2026.
- JK Tyre, Apollo Tyres and CEAT have all approved plant expansion, with JK Tyre alone planning Rs 6,110 crore of projects phased through 2029.
Truck tires lead value while car radials add the most
Why do truck and bus tires lead value while car tires grow fastest?
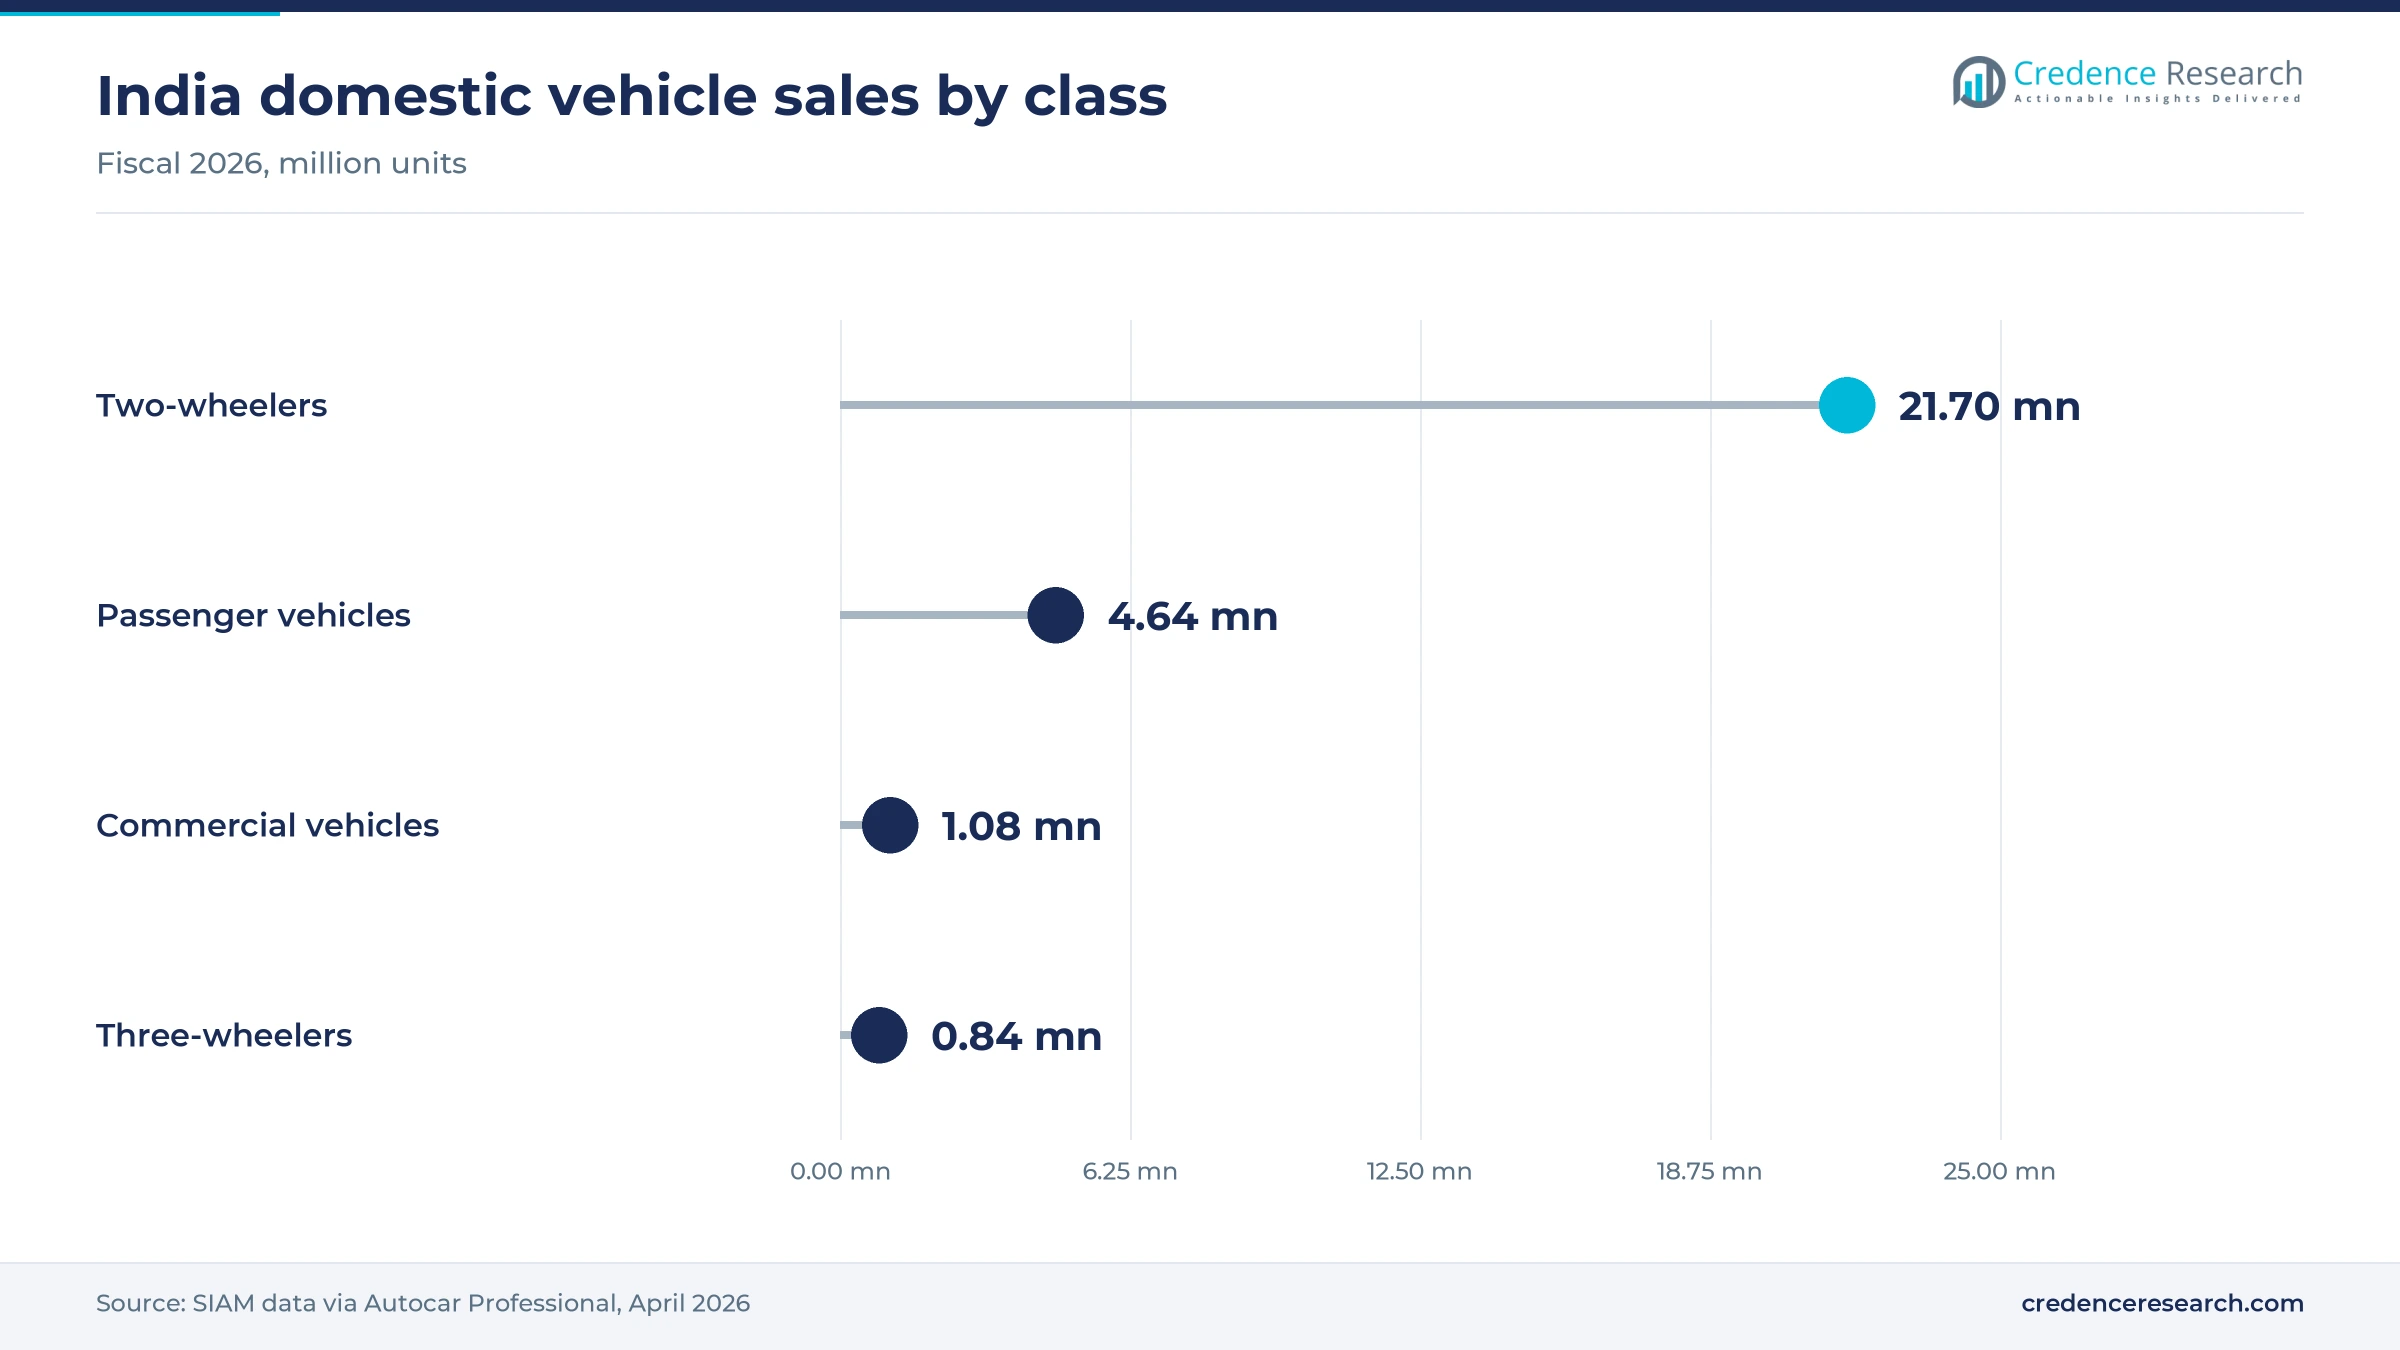
Based on vehicle type, the market is categorized into truck and bus tires, passenger car tires, motorcycle tires, light truck tires and special vehicle tires. Truck and Bus Tires led with 36.0% of 2025 value because fleets replace costly casings often, and SIAM recorded 1.08 million domestic commercial vehicle sales in fiscal 2026, up 12.6%. Passenger Car Tires grow fastest at 6.69% a year as JK Tyre lifted its radial capacity for cars to about 16 million units annually at Banmore, Autocar Professional reported in January 2026. Motorcycle tires follow a base of 21.7 million two-wheelers sold, up 10.7%.
How much of tire demand is replacement rather than OEM?
Based on demand, the market is categorized into replacement and OEM. Replacement led with 68.0% of 2025 value because the running vehicle base drives repeat purchases, and Bridgestone told Autocar Professional in March 2026 that about 65% of its passenger sales come from the aftermarket. CEAT also called replacement its largest contributor in its fiscal 2026 management discussion. OEM grows fastest at 6.34% a year as fitment contracts follow record vehicle output, and Bridgestone expects its OEM portion to reach about 40%, while Yokohama India aims to lift its single-digit OEM portion.
How far has radial construction replaced bias tires?
Based on type of tires, the market is categorized into radial and bias. Radial led with 72.0% of 2025 value because new investment goes there, as JK Tyre approved Rs 4,980 crore of truck and car radial expansion in 2026. Radial also grows fastest at 6.66% a year as Balkrishna Industries adds a Rs 750 crore commercial radial line of 800 tires a day. Apollo Tyres describes commercial radialization as a significant opportunity in its fiscal 2026 report. Bias tires keep work in farm and compact off-highway uses, the line CEAT bought from Michelin in 2025.
How do dealers, exclusive outlets and online sellers split sales?
Based on distribution channel, the market is categorized into dealer/exclusive outlets, online and others, which covers direct supply to vehicle makers and fleets. Dealer/Exclusive Outlets led with 64.3% of 2025 value because fitment needs a physical bay, and Bridgestone alone counts over 4,000 dealers including about 900 Select outlets. Online grows fastest at 14.84% a year from a small base, since Tyresnmore chief executive Rakesh Tatikonda told Autocar Professional in May 2026 that online sales remain below 1% of replacement, far under the levels seen in Western markets.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Vehicle Type | Truck and Bus Tires | 36.0% | Passenger Car Tires | 6.69% |
| By Demand | Replacement | 68.0% | OEM | 6.34% |
| By Type of Tires | Radial | 72.0% | Radial | 6.66% |
| By Distribution Channel | Dealer/Exclusive Outlets | 64.3% | Online | 14.84% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Record vehicle sales and tax cuts lift tire volumes
Record vehicle sales widen the tire base
Vehicle sales set the base for both first fitment and later replacement, so the fiscal 2026 record matters across the market. SIAM data published by Autocar Professional on April 14, 2026, showed domestic wholesales of 28.3 million units, up 10.4%. Passenger vehicles reached 4.64 million, two-wheelers 21.7 million, three-wheelers 836,000 and trucks and buses 1.08 million. The international manufacturers body OICA said in April 2026 that India's output rose to 6.49 million vehicles, naming the country the second major growth story in Asia. As a result, each new vehicle cohort enters the replacement pool within a few years, which supports the 68.0% replacement share.
The September 2025 GST cut lowered shelf prices
Tax reform changed the price a buyer pays almost overnight, which encouraged owners to replace worn tires sooner. Under the GST Council decision, GST on new pneumatic tires fell from 28% to 18% on Sept. 22, 2025, while tractor tires and tubes fell to 5%. Apollo Tyres then cut prices by Rs 300 to Rs 2,000, with truck and bus radials down about Rs 2,000 each. JK Tyre's fiscal 2026 report credits the cut with supporting both OEM and replacement demand, and it records tractor sales up 22% to 1.16 million units. Apollo Tyres also describes stronger replacement growth in the second half of that year.
Makers add radial lines as plants near full use
Plants running close to capacity have pushed the largest makers to approve new lines, which keeps radial supply growing. Autocar Professional reported in June 2026 that Apollo Tyres runs at about 90% across India and Europe and CEAT slightly lower, while JK Tyre described itself as almost full. Apollo Tyres planned Rs 3,500 crore of fiscal 2027 spending, with about Rs 3,000 crore for India. JK Tyre approved Rs 4,980 crore on top of Rs 1,130 crore already underway, lifting truck and car radial capacity by 24% through 2029. Bridgestone will add about 1.1 million tires a year at Pune by 2029 under its Rs 709.75 crore plan.
Export earnings fund scale for domestic plants
Exports let Indian plants run longer lines and spread fixed cost, which benefits domestic pricing and product range. Commerce Ministry data reported by The Tribune in June 2026 put fiscal 2026 tire exports at a record Rs 27,312 crore, up 9%, and exports now exceed one-fourth of output on an estimated Rs 1 lakh crore turnover. The same report cites about Rs 30,000 crore invested in greenfield and brownfield capacity over four to five years. Tire Business ranked MRF 13th, Apollo Tyres 14th, JK Tyre 19th and CEAT 20th globally on 2024 sales, according to Tyre News Media in November 2025.
Premium sizes, sensors and EV fitments reshape the mix
Shift to larger rim sizes and premium SUV tires
A shift toward utility vehicles is raising average tire value, because larger rims command higher prices. Continental Tires India stopped truck radial production at Modipuram on June 2, 2025, and is spending Rs 100 crore over 18 to 24 months to convert the line for 20-inch to 23-inch car and SUV tires, Autocar Professional reported. Yokohama India can now make tires up to 24 inches and has lifted car radial capacity to about 4.5 million units from 0.7 million in 2014. JK Tyre's fiscal 2026 report adds an 18-inch Mahindra Thar fitment. As a result, Passenger Car Tires reach 6.69% annual growth.
Rise of electric fitments in scooters and three-wheelers
Electric vehicles are emerging as a distinct fitment class, and official counts now show the volumes at stake. In 2025, the International Energy Agency counted almost 800,000 electric three-wheelers sold in India, nearly 70% of all three-wheeler sales, while battery scooters and motorcycles reached just under 1.3 million units, about 6% of that class. The same outlook counts over 4,000 electric bus sales, with PM E-Drive aiming for up to 14,000 buses across 2024 to 2026. MRF says in its fiscal 2026 report that monthly electric two-wheeler sales held near 100,000 units, and JK Tyre puts electric penetration at about 4% in passenger vehicles.
Opportunity in embedded sensors for smart tires
Smart tires offer makers an opening to sell a service alongside rubber, particularly to car owners and fleets that want early leak warnings. JK Tyre launched embedded smart tires for passenger vehicles in sizes from 14 to 17 inches, Autocar Professional reported on Nov. 10, 2025, with sensors tracking pressure, temperature and air leaks in real time. That launch builds on a 2019 product pairing pressure monitors with cloud analytics. TUV Rheinland notes that the AIS-154 standard aligns India with UN R 141 for M1 and N1 vehicles fitted with such systems, and tests them at 0 to 50 degrees Celsius. Formal standards therefore give fitment programs a clear test route.
Opportunity in rural distribution and off-highway tires
Rural markets and off-highway categories offer room beyond the crowded urban car segment, which suits makers with wide networks. JK Tyre launched a Rural Business vertical in fiscal 2026, entered more than 400 unrepresented markets and added over 700 dealers to reach more than 6,000 partners. CEAT completed its purchase of the CAMSO compact line from Michelin in September 2025, gaining plants at Midigama and Kotugoda in Sri Lanka and access to more than 40 global OEMs. Tractor tires now carry 5% GST, which improves farm affordability. JK Tyre's dealer additions are the more direct support for the faster growth estimated for East India through 2035, although zone-level sales are not published.
Crude-linked inputs and tariffs squeeze tire margins
Crude-linked input costs outrun price increases
Raw materials make up almost 60% of sales for TVS Srichakra, so input swings reach margins quickly. CEAT told Autocar Professional in October 2026 that inputs rose about 9% in a single quarter and that a further 7% to 8% price rise would be needed for full recovery. JK Tyre expected a 16% to 20% rise in the quarter before that. Replacement buyers absorb increases first, while fixed OEM indexation lags. Makers respond with staggered price hikes and wider raw material sourcing.
Natural rubber output still trails consumption
Domestic natural rubber does not cover demand, which leaves tire makers exposed to import prices and freight. Rubber Board panel figures from May 2026 show fiscal 2026 production of 905,000 tons against consumption of 1.427 million tons, with auto tires taking nearly 64%. Imports were 459,000 tons, while compounded rubber imports climbed to 349,000 tons from 245,000. Auto tire use of natural rubber fell 4.0% in 2025-26 in the same report, and new planting in non-traditional areas will take years to yield latex.
U.S. tariff swings disturb export planning
Exports support plant loading, so abrupt U.S. duty changes unsettle the output plan for truck and car lines. The Tribune reported in June 2026 that U.S. duties on Indian tires rose to 50% from 25% in August 2025 and fell to 18% in February 2026. The U.S. share of exports slipped to 15% from 17%, or Rs 4,082 crore. Makers are spreading sales toward Germany, Italy, Brazil and France to limit that exposure.
Retreading tax and casing reuse limit new sales
Fleets stretch budgets by reusing casings, which delays some new truck tire purchases and complicates demand forecasts. Retreading kept its existing GST rate after the September 2025 reform, and Tyre Trends reported that trucks account for most of that work. JK Treads alone reached over 90 centers and 450 customers in fiscal 2026. Tire makers therefore compete with their own casings, so many now sell retreading alongside new radials to retain fleet accounts.
South and West hold the plants and the largest demand
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South India | 5.70 | 33.0% | 6.10% |
| West and Central India | 5.52 | 32.0% | 5.70% |
| North India | 4.14 | 24.0% | 5.70% |
| East India | 1.90 | 11.0% | 6.60% |
South India pairs rubber belts with new plants
South India held 33.0% of 2025 value and grows at 6.10% a year. MRF signed a non-binding agreement on March 4, 2026, for a Rs 5,300 crore plant at Sivaganga, with spending projected over 12 years and about 1,000 direct jobs. CEAT is also adding Chennai capacity within Rs 495 crore of second-quarter fiscal 2027 spending, and Yokohama India operates at Vizag in Andhra Pradesh.
West and Central India anchor radial and carbon black output
West and Central India held 32.0% of 2025 value and grows at 5.70% a year as industrial clusters feed plants and fleets. Bridgestone runs Chakan and Pithampur at 90% to 95% use, with over 30,000 tires a day. JK Tyre's Banmore plant in Madhya Pradesh makes about 10.5 million car radials annually, CEAT builds at Halol, Ambernath and Nagpur, and Balkrishna Industries is lifting Bhuj carbon black capacity to 360,000 tons from 265,000.
North India mixes premium car demand with fleets
North India held 24.0% of 2025 value and grows at 5.70% a year, supported by the car and fleet density of the National Capital Region and Uttar Pradesh. Continental Tires India is reworking Modipuram near Meerut for larger car and SUV tires, while Yokohama India produces at Bahadurgarh in Haryana. Tyresnmore offers doorstep fitment in Delhi-NCR among six metro markets, which shows the online model starting where premium ownership is densest.
East India grows from a smaller distribution base
East India held 11.0% of 2025 value and grows fastest at 6.60% a year, because dealers and rural distributors are still filling gaps. Natural rubber planting in non-traditional areas including the North-East and Odisha could add local supply over time. JK Tyre's expansion into more than 400 unrepresented markets across India shows how makers are reaching such towns, though zone-level sales data is not published.
Capacity pledges and tax changes marked 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In October 2026, CEAT said inputs rose about 9% in a quarter and that it needed a further 7% to 8% in prices. | Margin pressure continues across fiscal 2027, while Chennai and Nagpur capacity spending proceeds. |
| In March 2026, MRF signed a Rs 5,300 crore agreement with Tamil Nadu for a greenfield tire plant at Sivaganga. | Non-binding, with incentives and clearances pending, and spending projected over 12 years. |
| In January 2026, JK Tyre expanded its Banmore plant to about 10.5 million car radials a year. | Completed phase that lifts company car radial capacity in India to about 16 million units. |
| In September 2025, GST on new pneumatic tires fell to 18% from 28%, effective Sept. 22. | In force, and makers including Apollo Tyres passed the cut through to buyers. |
| In June 2025, Continental Tires India stopped truck radial production at Modipuram to focus on passenger and light truck tires. | Conversion under way, with a Rs 100 crore budget and an 18 to 24 month timeline. |
Radial lines, embedded sensors and larger rim sizes
- Radial construction continues to replace bias in commercial tires, and Balkrishna Industries' first phase commercial line alone adds 800 tires a day.
- Embedded sensors move pressure and temperature tracking inside the tire structure, as JK Tyre did in sizes from 14 to 17 inches during November 2025.
- Large rim production now reaches 24 inches at Yokohama India and 23 inches in Continental's Modipuram plan, which reduces reliance on imports for luxury SUVs.
- Local carbon black gives Balkrishna Industries its own supply from Bhuj, which shows makers integrating upstream as input costs climbed during 2026.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Four domestic makers face premium global challengers
Competition centers on four domestic makers with national dealer reach, and on foreign brands that concentrate on premium car tires. Tire Business placed MRF, Apollo Tyres, JK Tyre and CEAT among the 20 largest global producers on 2024 sales. MRF signed for a new Tamil Nadu site in March 2026 and reports strong two-wheeler fitment across new model launches. TVS Srichakra, which sells TVS Eurogrip tires, says it sustained its replacement share. Bridgestone claims about 20% of the passenger car aftermarket, and it plans about 30% more dealers within five years. Yokohama India earns about 95% of its sales from replacement across 3,300 touchpoints. Continental left truck radial production in June 2025 after intense price competition, which shows how hard the commercial segment has become. Balkrishna Industries, long focused on off-highway tires, is now entering commercial and passenger radials with a car tire launch targeted by the end of 2026.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| MRF Limited | Domestic full-line maker | Signed for a Rs 5,300 crore Sivaganga plant in March 2026 and supplies two-wheeler OEMs |
| Apollo Tyres | Domestic full-line maker | Plans about Rs 3,000 crore of fiscal 2027 India spending on truck and car tires |
| CEAT Limited | Domestic full-line maker | Expanding Chennai and Nagpur, and bought the CAMSO compact line in September 2025 |
| JK Tyre & Industries | Domestic truck and car radial maker | Rs 6,110 crore radial expansion through 2029, plus embedded smart tires |
| TVS Srichakra (TVS Eurogrip) | Two-wheeler and off-highway specialist | Supplies two-wheeler OEMs just in time and serves replacement through depots |
| Bridgestone India | Foreign premium car and truck maker | Runs Chakan and Pithampur, with over 4,000 dealers and a Rs 709.75 crore plan |
| Continental Tires India | Foreign premium car maker | Converting Modipuram for 20-inch to 23-inch car and SUV tires |
| Yokohama India | Foreign car radial maker | Operates Bahadurgarh and Vizag, with about 4.5 million units of car radial capacity |
| Balkrishna Industries | Off-highway specialist entering radials | Commercial radial line and a car radial launch, with carbon black at Bhuj |
Cost pass-through will decide who gains share by 2030
Credence Research's view is that volume is not the main question for this market through 2030, since record vehicle sales and a growing replacement pool already support demand. The deciding factor is who can pass on crude-linked costs without losing dealers. Replacement-heavy brands recover cost faster than those tied to quarterly OEM indexation, yet new capacity arriving by 2029 could limit pricing power. As a result, companies with captive inputs, premium rim sizes and wide rural reach look better placed than those relying on commercial tires alone, where Continental has already withdrawn from local truck radial production.
How the 2025 value and estimates were built
The report uses 2025 as the base year and 2035 as the forecast year, with 2026–2035 as the CAGR period. The earlier 2024 estimate was brought to 2025 with its own growth rate. It sits above a rough cross-check from industry turnover, which gives about USD 12-13 billion for domestic sales once dealer margins and GST are added, so it should be read as the upper end of plausible estimates. Segment and regional splits are Credence Research estimates built from public data, including SIAM vehicle sales, OICA output, Rubber Board statistics, International Energy Agency data, company management discussions and trade press. No interviews or surveys were conducted for this edition of the report.
Radial capacity and exports support growth to 2035
The market is forecast to reach USD 30.71 billion by 2035, growing at a 5.93% CAGR over 2026–2035. Radial lines approved in 2026 should come on stream through 2029, which leaves supply well matched to fleet demand and the shift to larger car tires. Electric scooters and three-wheelers will add a growing fitment class, while online sales should expand from a very small base. The main swing factors remain crude-linked input prices and U.S. tariffs, because either can quickly change margins and export volumes. Domestic rubber supply will also remain short unless new planting yields latex on schedule.
Frequently Asked Questions
How big is the India tyre market?
What is the size of the India automotive tire market in 2026?
Who are the leading tire manufacturers in India by market share?
Which segment holds the largest share of the Indian tyre market?
What supports two-wheeler and motorcycle tire demand in India?
What is driving the smart tires market in India?
How much did GST change tire prices in India?
How much does the Indian tyre industry export?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle Type
- 1.2.1 Truck and Bus Tires
- 1.2.2 Passenger Car Tires
- 1.2.3 Motorcycle Tires
- 1.2.4 Light Truck Tires
- 1.2.5 Special Vehicle Tires
- 1.3 By Demand
- 1.3.1 Replacement
- 1.3.2 OEM
- 1.4 By Type of Tires
- 1.4.1 Radial
- 1.4.2 Bias
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 17.26 billion → 2035: USD 30.71 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Tyre Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Tyre Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Tyre Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Tyre Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Tyre Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Tyre Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Tyre Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Tyre Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 17.26 billion → 2035: USD 30.71 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Tyre Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Truck and Bus Tires
- 12.3.7.2 Passenger Car Tires
- 12.3.7.3 Motorcycle Tires
- 12.3.7.4 Light Truck Tires
- 12.3.7.5 Special Vehicle Tires
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Demand - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Replacement
- 12.4.7.2 OEM
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Tires - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Radial
- 12.5.7.2 Bias
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 India Tyre Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Tyre Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Tyre Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 MRF Limited
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Apollo Tyres
- 17.4 CEAT Limited
- 17.5 JK Tyre & Industries
- 17.6 TVS Srichakra (TVS Eurogrip)
- 17.7 Bridgestone India
- 17.8 Continental Tires India
- 17.9 Yokohama India
- 17.10 Balkrishna Industries
- 17.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

