
Market Overview
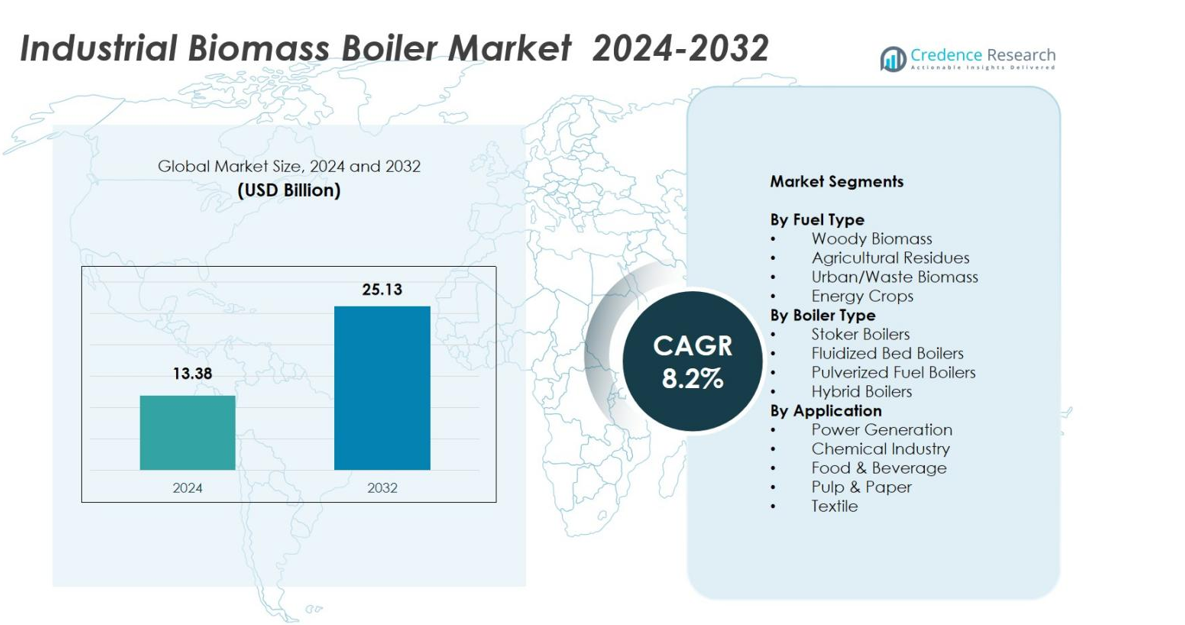
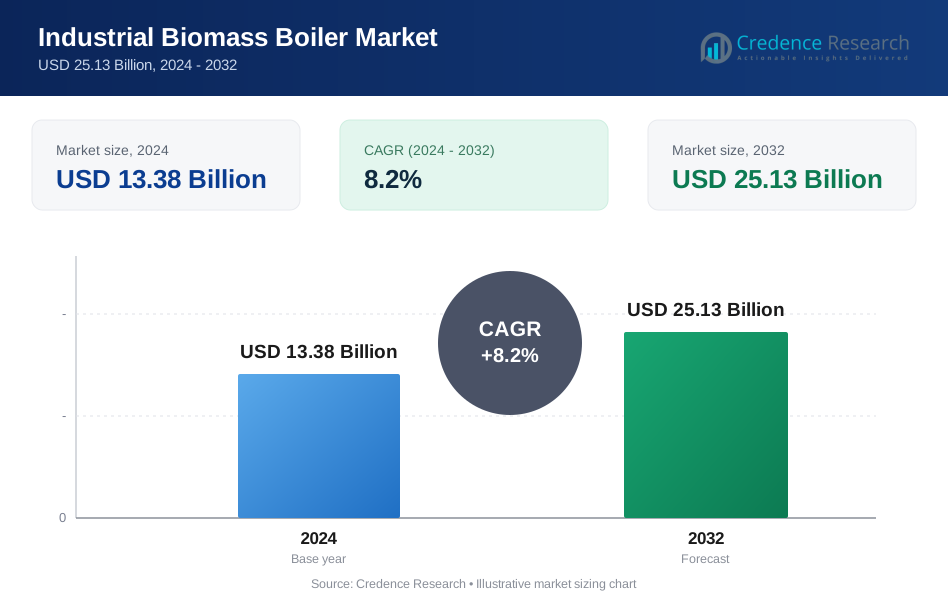
Industrial Biomass Boiler Market size was valued at USD 13.38 Billion in 2024 and is anticipated to reach USD 25.13 Billion by 2032, at a CAGR of 8.2% during the forecast period
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Biomass Boiler Market Size 2024 | USD 13.38 Billion |
| Industrial Biomass Boiler Market, CAGR | 8.2% |
| Industrial Biomass Boiler Market Size 2032 | USD 25.13 Billion |
Industrial Biomass Boiler Market is shaped by leading players such as Andritz AG, Valmet Oyj, Doosan Heavy Industries, Babcock & Wilcox, Thermax Ltd., General Electric Co., Isgec Heavy Engineering Ltd., and Bharat Heavy Electricals Ltd., all of which focus on advanced combustion technologies, high-efficiency systems, and multi-fuel boiler solutions. These companies strengthen their presence through technology upgrades, EPC capabilities, and strategic industrial partnerships. Europe remained the leading region in 2024 with a 36.8% market share, driven by stringent emission regulations, mature biomass supply chains, and large-scale adoption of bioenergy-based industrial heating systems.
Market Insights
- Industrial Biomass Boiler Market reached USD 13.38 Billion in 2024 and will grow at a CAGR of 8.2% through 2032, reaching USD 25.13 Billion.
- Market overview highlights strong adoption across industrial sectors as biomass systems replace fossil-fuel boilers, with woody biomass leading the fuel type segment at 44.6% share.
- The market is driven by industrial decarbonization, stringent emission norms, and expanding biomass supply chains that enhance feedstock reliability and affordability.
- Key players such as Andritz AG, Valmet Oyj, Thermax Ltd., and Doosan Heavy Industries strengthen market presence through technology innovation, high-efficiency boiler solutions, and digital monitoring capabilities.
- Regional analysis shows Europe leading with 36.8% share, followed by North America at 27.4% and Asia-Pacific at 24.6%, while power generation remains the top application segment with 41.2% market share.
Market Segmentation Analysis:
By Fuel Type:
In the Industrial Biomass Boiler Market, the fuel type segment is dominated by woody biomass, which accounted for 44.6% market share in 2024. Its leadership stems from abundant global availability, higher calorific value, and strong adoption across large-scale industrial heating systems. Agricultural residues captured 27.8% share, supported by rising waste-to-energy initiatives, while urban/waste biomass held 18.5% due to growing municipal waste valorization. Energy crops represented 9.1%, driven by emerging bioenergy plantations. The dominance of woody biomass is further propelled by stable supply chains, consistent combustion efficiency, and favorable policies promoting renewable heat generation.
- For instance, Fonterra installed a 30 MWth bubbling fluidized bed boiler at its Waitoa site, firing woody biomass with high moisture and ash content for process heat in dairy operations.
By Boiler Type:
The boiler type segment is led by fluidized bed boilers, holding a 39.7% market share in 2024 due to their superior fuel flexibility, high combustion efficiency, and lower emissions. Stoker boilers followed with 31.4% share, supported by cost-effective deployment in small and medium industries. Pulverized fuel boilers accounted for 17.6%, mainly used in high-capacity power and process applications. Hybrid boilers captured 11.3% with increasing adoption for multi-fuel operations. The leadership of fluidized bed boilers is driven by stringent emission regulations and industries’ shift toward efficient large-scale renewable heat systems.
- For instance, Valmet delivered a CFB boiler to Shanying Huazhong Paper's thermal power plant, utilizing 260,000 tons of annual mill waste including paper rejects, pulp rejects, and pulp sludge to generate electricity and steam for mill operations.
By Application:
Among applications, power generation dominated the Industrial Biomass Boiler Market with a 41.2% market share in 2024, supported by the accelerating transition toward renewable baseload energy and biomass co-firing in thermal plants. The chemical industry accounted for 21.7% as companies integrate biomass boilers to reduce carbon footprints and energy expenses. Food & beverage held 16.8% driven by process steam requirements, while pulp & paper captured 13.4% due to the sector’s strong use of biomass-derived fuels. Textile applications comprised 6.9%. The leadership of power generation is fueled by supportive renewable energy mandates and improved biomass supply infrastructure.
Key Growth Drivers
Rising Industrial Decarbonization Targets
Industrial decarbonization remains a primary driver for the Industrial Biomass Boiler Market as manufacturers actively transition from fossil-fuel-based heat systems to renewable, low-carbon alternatives. Biomass boilers enable substantial CO₂ reductions while supporting high-temperature industrial processes, making them a strategic fit for sectors such as chemicals, pulp & paper, and food processing. Growing policy mandates, carbon taxation, and net-zero commitments further accelerate adoption. Companies increasingly invest in biomass solutions to meet ESG requirements, stabilize long-term energy costs, and reduce dependency on volatile fossil fuel markets.
- For instance, Bulleh Shah Packaging installed a biomass-fired energy plant at its Pakistan paper factory, using wheat straw, cotton stalks, corn, rice, and river grass residues to produce 150 t/h steam at 530°C and 98 bara, replacing fossil fuels for reliable mill operations.
Expansion of Biomass Supply Chains and Feedstock Availability
The rapid improvement in biomass collection, processing, and distribution networks significantly boosts market growth by ensuring reliable and cost-effective feedstock availability. Enhanced logistics for woody biomass, structured procurement of agricultural residues, and increased production of dedicated energy crops strengthen the fuel ecosystem for industrial boilers. Government incentives for biomass cultivation and waste-to-energy initiatives also widen the feedstock base. This expanded supply chain ecosystem reduces operational bottlenecks and encourages industries to adopt large-scale biomass boiler systems with confidence.
- For instance, PRESPL in India aggregates and processes agricultural residues like those from Punjab and Haryana into biomass briquettes and pellets, partnering with firms such as PepsiCo and Cipla to supply renewable energy inputs across over 100 districts.
Supportive Regulatory Frameworks and Renewable Heat Incentives
Government-backed renewable heat programs, emissions regulations, and incentive schemes strongly support biomass boiler installations across industrial facilities. Policies promoting clean energy adoption, such as renewable heat incentives, bioenergy subsidies, and carbon credit eligibility, make biomass systems financially attractive. Stricter emission norms push industries to replace coal-fired boilers with cleaner biomass alternatives. Public–private partnerships and funding for green infrastructure projects further stimulate market expansion, creating a favorable regulatory environment that accelerates the shift toward sustainable industrial heat generation.
Key Trends & Opportunities
Technological Advancements in High-Efficiency Boiler Systems
A major trend in the Industrial Biomass Boiler Market is the rapid development of advanced combustion technologies, including next-generation fluidized bed systems, automated feedstock handling, and improved emission control units. These innovations enhance combustion efficiency, reduce particulate emissions, and support multi-fuel operations. Opportunities arise from the integration of digital monitoring and predictive maintenance tools, enabling industries to optimize performance and reduce downtime. As efficiency improves, biomass boilers become more economically attractive, expanding their adoption across diverse industrial applications.
- For instance, Valmet's CFB Boiler employs circulating fluidized bed technology that circulates bed material with flue gas through the furnace for even combustion temperatures, handling varied fuel properties like moisture and ash content while ensuring low primary emissions.
Growing Adoption of Circular Bioeconomy and Waste-to-Energy Models
Expanding circular bioeconomy initiatives create strong opportunities as industries increasingly convert agricultural residues, organic waste, and by-products into usable biomass fuel. Waste-to-energy facilities strengthen local fuel security while helping companies achieve waste reduction goals. This trend is especially prominent in food processing, pulp & paper, and municipal operations. Industries benefit from lower fuel expenses, reduced landfill burden, and enhanced sustainability performance. The shift toward circular operations positions biomass boilers as a central technology supporting resource efficiency and renewable heat production.
- For instance, McCain's Timaru plant converted its 14 MWth traveling grate boiler to burn biomass woodchips, replacing lignite coal for potato processing steam.
Key Challenges
Feedstock Supply Variability and Quality Inconsistencies
Despite expanding biomass supply chains, fluctuations in feedstock quality and seasonal availability remain a major challenge for market expansion. Variability in moisture content, calorific value, and contamination affects combustion performance and increases maintenance requirements. Agricultural residues and urban waste streams often face inconsistent supply volumes, complicating long-term procurement planning. These challenges drive up operational costs and limit adoption among industries requiring stable, high-efficiency heat generation. Developing standardized feedstock processing systems remains essential for overcoming these limitations.
High Capital Cost and Complex Installation Requirements
The high upfront investment associated with industrial biomass boiler installation poses a significant challenge, especially for small and mid-sized enterprises. Costs involve not only the boiler system but also fuel storage, handling equipment, emission control units, and retrofitting infrastructure. Complex site preparation and permitting regulations further extend project timelines. While operational savings may offset these expenses over time, the initial financial burden often delays adoption. Access to financing solutions and government subsidies is crucial to reducing these barriers and encouraging broader market penetration.
Regional Analysis
North America
North America accounted for 27.4% market share in 2024, driven by strong decarbonization initiatives across industrial sectors and the rising adoption of biomass-based heat systems to reduce reliance on natural gas and coal. The U.S. leads the region due to supportive renewable heat policies, tax credits, and expansion of woody biomass supply chains. Canada contributes significantly with its robust forest residue resources and sustainability-focused industrial operations. Increasing investments in renewable heat infrastructure and emission-compliance strategies continue to fuel market expansion across power generation, food processing, and chemicals industries.
Europe
Europe dominated the Industrial Biomass Boiler Market with 36.8% market share in 2024, supported by stringent emissions regulations and long-term climate neutrality targets. Countries such as Germany, Sweden, Finland, and the U.K. show strong adoption due to mature biomass supply chains and established district heating networks. The region benefits from extensive government incentives promoting bioenergy deployment and the replacement of coal-fired systems. Industrial users adopt biomass boilers to comply with carbon reduction frameworks and leverage abundant forestry residues. Ongoing investments in waste-to-energy facilities and advanced boiler technologies further reinforce Europe’s leadership.
Asia-Pacific
Asia-Pacific held 24.6% market share in 2024, driven by rapid industrialization, rising energy demand, and strong government focus on renewable heat solutions. China leads the region with expanding biomass power capacity and large-scale utilization of agricultural residues. India shows accelerating growth due to supportive waste-to-energy policies and rising adoption of biomass boilers in textiles, food processing, and manufacturing. Southeast Asian countries leverage abundant palm, rice husk, and coconut waste as feedstock. The region’s growing industrial base and increasing pressure to curb industrial emissions position Asia-Pacific as a major high-growth market.
Latin America
Latin America captured 6.4% market share in 2024, primarily fueled by extensive agricultural activity and abundant availability of biomass residues such as sugarcane bagasse and forestry by-products. Brazil dominates due to its strong bioenergy ecosystem and industrial transition toward renewable heat. Chile, Argentina, and Colombia also show growing adoption as industries seek cost-efficient alternatives to fossil fuels. Supportive government programs for energy diversification and sustainable industrial practices further accelerate market penetration. Expansion of biomass-based cogeneration plants in the food & beverage and paper industries enhances the region’s long-term growth outlook.
Middle East & Africa
Middle East & Africa accounted for 4.8% market share in 2024, with growth driven by emerging industrial diversification efforts and increasing emphasis on sustainable energy solutions. South Africa leads adoption due to strong agro-processing industries and rising investments in biomass-based heating systems. Gulf countries are gradually exploring biomass solutions as part of long-term renewable energy strategies, particularly for industrial clusters seeking carbon reduction. Limited feedstock availability and infrastructural gaps currently restrict large-scale deployment, but expanding waste-to-energy projects and policy shifts toward decarbonization present emerging opportunities in the region.
Market Segmentations
By Fuel Type
- Woody Biomass
- Agricultural Residues
- Urban/Waste Biomass
- Energy Crops
By Boiler Type
- Stoker Boilers
- Fluidized Bed Boilers
- Pulverized Fuel Boilers
- Hybrid Boilers
By Application
- Power Generation
- Chemical Industry
- Food & Beverage
- Pulp & Paper
- Textile
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Industrial Biomass Boiler Market features prominent players such as Andritz AG, Babcock & Wilcox Enterprises Inc., Bharat Heavy Electricals Ltd., Dongfang Electric Corp., Doosan Heavy Industries & Construction Co. Ltd., General Electric Co., Isgec Heavy Engineering Ltd., Thermax Ltd., Valmet Oyj, and Xizi United Holdings Ltd. The market is characterized by strong emphasis on technological innovation, energy efficiency, and emission reduction capabilities. Leading manufacturers focus on expanding their portfolios of fluidized bed and hybrid biomass boilers to meet evolving industrial decarbonization requirements. Companies increasingly invest in R&D to develop advanced combustion systems, automation-integrated operations, and multi-fuel flexibility. Strategic collaborations, EPC contracts, and long-term service agreements strengthen market positioning, particularly in Europe and Asia-Pacific. Additionally, players compete on performance reliability, lifecycle cost optimization, and integration of digital monitoring solutions, enabling industrial users to enhance operational efficiency while shifting toward renewable heat systems.
Key Player Analysis
- Doosan Heavy Industries & Construction Co. Ltd.
- Thermax Ltd.
- Xizi United Holdings Ltd.
- Bharat Heavy Electricals Ltd.
- Andritz AG
- Valmet Oyj
- Isgec Heavy Engineering Ltd.
- General Electric Co.
- Babcock & Wilcox Enterprises Inc.
- Dongfang Electric Corp.
Recent Developments
- In September 2025, Saica Group inaugurated a new biomass boiler at its Champblain-Laveyron containerboard mill in France, replacing a natural gas unit and enabling recovery of 105,000 tonnes of end-of-life wood annually.
- In 2024, Miura Co. from Japan acquired Cleaver-Brooks, a major U.S. boiler manufacturer, to integrate modular high-efficiency technologies across steam and hot water systems.
- In September 2024, Boccard acquired Leroux & Lotz Technologies (LLT), a French industrial boiler manufacturer specializing in biomass systems, to lead in renewable thermal energy.
Report Coverage
The research report offers an in-depth analysis based on Fuel Type, Boiler Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as industries intensify decarbonization efforts and transition from fossil-fuel boilers to renewable heat systems.
- Advancements in fluidized bed and hybrid boiler technologies will enhance efficiency, emissions control, and multi-fuel flexibility.
- Biomass supply chains will expand with improved collection, processing, and logistics infrastructure, strengthening long-term fuel security.
- Adoption will rise in emerging economies as governments promote waste-to-energy and bioenergy-based industrial heating.
- Digitalization through automation, remote monitoring, and predictive maintenance will optimize boiler performance and reduce downtime.
- Circular bioeconomy initiatives will increase the use of agricultural residues, organic waste, and by-products as reliable biomass feedstock.
- Industrial sectors such as chemicals, food processing, and pulp & paper will accelerate investment in biomass boilers to reduce carbon footprints.
- Policy support through incentives, renewable heat programs, and carbon compliance regulations will continue to drive installations.
- Integration of biomass boilers into cogeneration and district heating systems will expand operational efficiency and energy diversification.
- Global collaborations and EPC partnerships will grow as manufacturers expand their presence in high-growth regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Industrial Decarbonization Targets
Manufacturers are transitioning from fossil-fuel-based heat systems to renewable, low-carbon alternatives to meet stringent decarbonization and net-zero commitments. Biomass boilers enable significant CO₂ reductions while supporting high-temperature industrial processes, making them attractive for sectors like chemicals, pulp & paper, and food processing.
Expansion of Biomass Supply Chains and Feedstock Availability
Improved collection, processing, and distribution networks for biomass feedstocks ensure reliable and cost-effective fuel supply. Enhanced logistics and government incentives for biomass cultivation and waste-to-energy initiatives are expanding the feedstock base, reducing operational risks and encouraging large-scale adoption.
Supportive Regulatory Frameworks and Renewable Heat Incentives
Government-backed renewable heat programs, emissions regulations, and incentive schemes make biomass boiler installations financially attractive. Stricter emission norms and public–private partnerships are accelerating the replacement of coal-fired boilers with cleaner biomass alternatives.
Technological Advancements in High-Efficiency Boiler Systems
Innovations in combustion technologies, such as advanced fluidized bed systems and digital monitoring, are improving efficiency, reducing emissions, and enabling multi-fuel operations. These advancements lower lifecycle costs and make biomass boilers more appealing for diverse industrial applications.
Growing Adoption of Circular Bioeconomy and Waste-to-Energy Models
Industries are increasingly converting agricultural residues and organic waste into usable biomass fuel, supporting circular bioeconomy initiatives. This trend reduces landfill burden, lowers fuel expenses, and enhances sustainability, driving further adoption of biomass boilers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Industrial Biomass Boiler Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Industrial Biomass Boiler Market projected to grow between 2024 and 2032?
What is the major growth driving factors for global Industrial Biomass Boiler market?
What are the primary factors fueling the growth of the Industrial Biomass Boiler Market?
Who are the leading companies in the Industrial Biomass Boiler Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel Type
- 1.2.1 Woody Biomass
- 1.2.2 Agricultural Residues
- 1.2.3 Urban/Waste Biomass
- 1.2.4 Energy Crops
- 1.3 By Application
- 1.3.1 Power Generation
- 1.3.2 Chemical Industry
- 1.3.3 Food & Beverage
- 1.3.4 Pulp & Paper
- 1.3.5 Textile
- 1.4 By Boiler Type
- 1.4.1 Stoker Boilers
- 1.4.2 Fluidized Bed Boilers
- 1.4.3 Pulverized Fuel Boilers
- 1.4.4 Hybrid Boilers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13.38 Billion → 2032: USD 25.13 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industrial Biomass Boiler Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industrial Biomass Boiler Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industrial Biomass Boiler Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industrial Biomass Boiler Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industrial Biomass Boiler Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industrial Biomass Boiler Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industrial Biomass Boiler Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industrial Biomass Boiler Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13.38 Billion → 2032: USD 25.13 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industrial Biomass Boiler Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Woody Biomass
- 12.3.7.2 Agricultural Residues
- 12.3.7.3 Urban/Waste Biomass
- 12.3.7.4 Energy Crops
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Power Generation
- 12.4.7.2 Chemical Industry
- 12.4.7.3 Food & Beverage
- 12.4.7.4 Pulp & Paper
- 12.4.7.5 Textile
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Boiler Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Stoker Boilers
- 12.5.7.2 Fluidized Bed Boilers
- 12.5.7.3 Pulverized Fuel Boilers
- 12.5.7.4 Hybrid Boilers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industrial Biomass Boiler End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Industrial Biomass Boiler Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Industrial Biomass Boiler Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Industrial Biomass Boiler Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Andritz AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Valmet Oyj
- 18.4 Doosan Heavy Industries & Construction Co. Ltd.
- 18.5 Babcock & Wilcox Enterprises Inc.
- 18.6 Thermax Ltd.
- 18.7 General Electric Co.
- 18.8 Isgec Heavy Engineering Ltd.
- 18.9 Bharat Heavy Electricals Ltd.
- 18.10 Dongfang Electric Corp.
- 18.11 Xizi United Holdings Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

