
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| IoT ASIC Market Size 2024 | USD 11,245.12 million |
| IoT ASIC Market, CAGR | 13.74% |
| IoT ASIC Market Size 2032 | USD 33,798.42 million |
Market Overview:
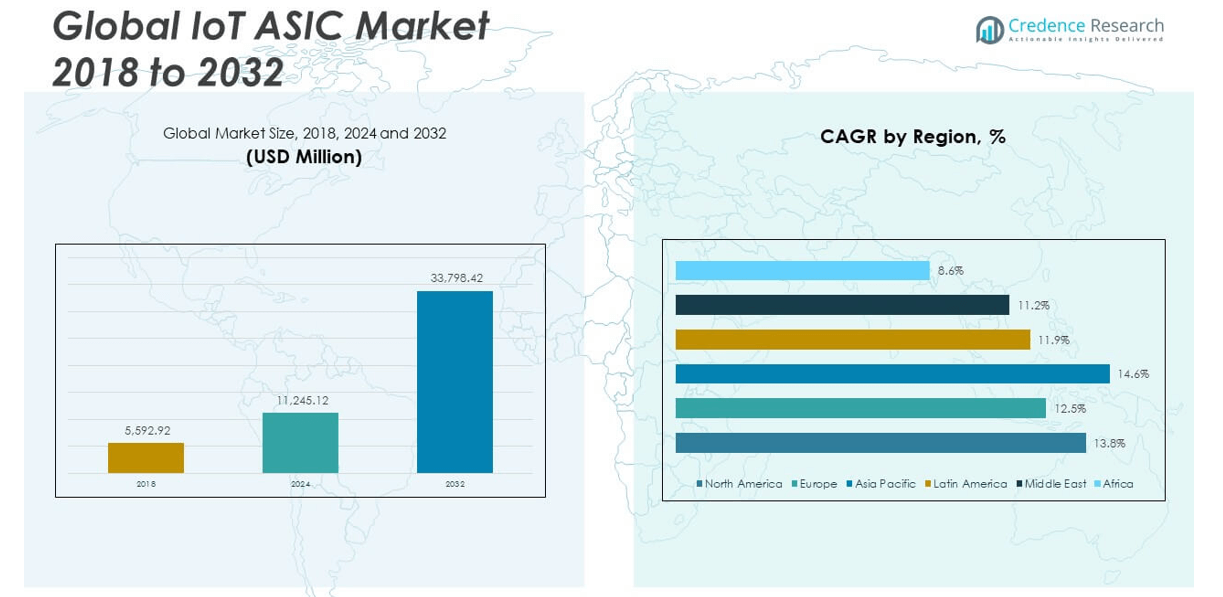
The Global IoT ASIC Market size was valued at USD 5,592.92 million in 2018 and reached USD 11,245.12 million in 2024. It is projected to grow to USD 33,798.42 million by 2032, expanding at a CAGR of 13.74% during the forecast period.
The rising trend of edge computing is a major driver accelerating the growth of the Global IoT ASIC Market. Enterprises increasingly process data locally on edge devices to minimize latency and offload cloud infrastructure. This trend demands custom ASICs that are energy-efficient and capable of performing high-speed processing in low-power environments. IoT ASICs facilitate seamless integration with sensors, microcontrollers, and communication modules in constrained embedded systems. Another key driver includes the miniaturization and low-power consumption of chips for battery-operated wearables, healthcare monitors, smart meters, and mobile IoT applications. The market is also responding to heightened cybersecurity needs by embedding encryption, secure boot mechanisms, and tamper-resistance directly into ASICs. As demand for real-time data analytics, AI integration, and sensor fusion grows, the development of advanced, application-specific chips is gaining urgency across sectors such as manufacturing, healthcare, transportation, and consumer electronics.
In terms of regional dynamics, Asia Pacific holds the largest share of the Global IoT ASIC Market, supported by strong manufacturing infrastructure, increasing investment in IoT development, and a thriving consumer electronics sector. Countries such as China, Japan, and South Korea are aggressively integrating smart technologies in urban infrastructure and industrial automation, creating high-volume demand for ASIC-based IoT solutions. North America follows, driven by robust investments from cloud service providers and early adoption of smart devices, particularly in healthcare, smart homes, and autonomous vehicles. Europe is bolstered by government initiatives for smart cities and sustainability-focused IoT projects. Latin America and the Middle East & Africa are emerging markets, gradually expanding their IoT infrastructure with rising telecom connectivity and growing adoption of industrial automation.
Market Insights:
- The Global IoT ASIC Market grew from USD 5,592.92 million in 2018 to USD 11,245.12 million in 2024 and is projected to reach USD 33,798.42 million by 2032, registering a CAGR of 13.74%.
- Edge computing adoption is accelerating the need for custom ASICs that support localized data processing with low power consumption and high-speed performance.
- Demand for compact and energy-efficient ASICs is rising across wearable healthcare devices, smart meters, and mobile IoT applications.
- ASIC integration with 5G modules is enabling advanced IoT solutions in smart infrastructure, autonomous systems, and industrial automation.
- High development costs and long design cycles pose barriers for small and mid-sized players, limiting market flexibility and time-to-market.
- Access to advanced semiconductor foundries remains limited, with geopolitical tensions and supply chain disruptions impacting production timelines.
- Asia Pacific leads the market share due to strong manufacturing capacity and rapid IoT deployment, followed by North America and Europe with growing investments in smart cities and connected technologies.
Market Drivers:
Rising Demand for Edge Computing and Real-Time Processing Capabilities
Edge computing continues to gain traction across industries due to the need for localized data processing and reduced latency. The Global IoT ASIC Market benefits significantly from this shift, as custom chips offer the speed and efficiency required at the edge. Enterprises seek ASIC-based IoT devices to manage and analyze vast amounts of data generated at remote sites without relying heavily on cloud infrastructure. This demand drives investment in purpose-built chips that integrate processing, sensing, and communication functions into compact form factors. Edge-focused applications in industrial automation, smart cities, and logistics require low-power, high-performance solutions, which ASICs deliver efficiently. As real-time decision-making becomes a priority, it compels manufacturers to prioritize custom silicon design in their IoT deployments.
- For example, NVIDIA has expanded its Jetson platform, delivering edge AI accelerators capable of real-time AI processing for robotics, autonomous vehicles, and smart cities. The Jetson AGX Orin module, for example, delivers up to 275 trillion operations per second (TOPS) of AI performance in a compact 100 x 87 mm form factor, enabling high-speed, low-latency analytics at the edge.
Growing Adoption of IoT Across Industrial, Healthcare, and Consumer Sectors
IoT adoption has expanded rapidly beyond consumer electronics into critical sectors such as healthcare, manufacturing, and utilities. The Global IoT ASIC Market aligns with this trend by offering customized functionality to meet diverse operational requirements. In healthcare, ASICs support advanced patient monitoring systems and wearable devices, providing energy efficiency and data accuracy. In manufacturing, ASICs power predictive maintenance tools and connected machinery that improve productivity and safety. Consumer devices like smart home assistants and fitness trackers also rely on ASICs for responsive interaction and efficient power usage. As industries continue to digitize their operations, the need for application-specific chips that optimize performance and cost becomes more pronounced.
- For instance, in healthcare, Medtronic’s IoT-enabled cardiac devices utilize application-specific integrated circuits (ASICs) to support remote patient monitoring, delivering reliable data transmission and multi-year battery life for implantable devices.
Push for Energy-Efficient and Compact IoT Devices
The demand for smaller, battery-efficient IoT devices is driving innovation in ASIC design. The Global IoT ASIC Market is responding with chips tailored to minimize power consumption while maximizing computational output. Battery-powered sensors and wearables require processors that can operate continuously on limited energy resources. ASICs provide a competitive edge by combining multiple functions-such as signal processing, connectivity, and control-into a single chip, thereby reducing footprint and energy draw. Companies focused on sustainable design are turning to ASICs to meet green standards and lower total cost of ownership. The shift toward portable, long-lasting IoT devices across sectors reinforces the relevance of custom, energy-conscious silicon.
Expansion of 5G Networks and IoT Ecosystem Integration
Widespread deployment of 5G networks is unlocking new possibilities for high-speed, low-latency IoT applications. The Global IoT ASIC Market is well-positioned to support this shift through silicon solutions that enable seamless connectivity and enhanced processing. With 5G, IoT devices require ASICs that can handle higher data throughput while maintaining security and reliability. Integration of ASICs with 5G modules accelerates smart infrastructure, autonomous systems, and industrial IoT growth. Telecom operators and equipment manufacturers are investing in ASICs to optimize hardware for next-generation network demands. The convergence of connectivity, intelligence, and performance reinforces the strategic role of ASICs in scaling the IoT ecosystem.
Market Trends:
Increasing Integration of AI and ML Capabilities in ASIC Designs
Chipmakers are embedding artificial intelligence (AI) and machine learning (ML) functions directly into ASICs to support intelligent IoT devices. The Global IoT ASIC Market is witnessing a shift toward intelligent edge hardware that processes data locally with minimal reliance on cloud computing. These AI-enabled ASICs allow devices to identify patterns, detect anomalies, and make decisions autonomously. Sectors such as smart surveillance, industrial inspection, and healthcare diagnostics increasingly depend on such embedded intelligence. It enhances device performance while improving response time and bandwidth efficiency. Manufacturers are prioritizing ASICs that enable real-time inference for faster and more secure IoT operations.
- For example, MICROIPand MediaTek have achieved a significant milestone in embedding AI and ML directly into ASICs for industrial IoT. At CES 2025, MICROIP unveiled its Genio AI IoT platform, built on TSMC’s 6nm NPU process, which delivers a balance of high performance and low power tailored for edge intelligence.
Proliferation of Application-Specific Chips for Niche Use Cases
Demand for highly customized ASICs tailored to specific functions is shaping the product development landscape. The Global IoT ASIC Market reflects this trend through the emergence of niche chips built for vertical-specific requirements. Developers are designing silicon optimized for narrowband IoT, environmental monitoring, agriculture automation, and asset tracking. These chips integrate only the necessary logic and interface blocks, reducing cost, energy use, and unnecessary complexity. Companies are no longer relying on one-size-fits-all SoCs but are instead deploying ASICs that deliver optimal efficiency for unique operating conditions. It supports innovation across fragmented IoT verticals by enabling low-cost, purpose-driven hardware.
- For example, NXP’s QN9090 Bluetooth Low Energy microcontroller is designed for asset tracking and environmental monitoring applications. It integrates essential logic blocks, including an Arm® Cortex®-M4 core and Bluetooth 5.0 stack, within a compact package. The device features a deep power-down current as low as 250 nA and a peak transmit current of approximately 7.4 mA at 0 dBm. It supports ultra-low-power operation with multiple sleep modes and fast wake-up times, making it ideal for battery-operated IoT devices.
Shift Toward Open-Source Hardware Design Platforms
Open-source hardware initiatives are influencing how companies approach ASIC development for IoT applications. The Global IoT ASIC Market is experiencing a transition where start-ups and mid-sized firms use open hardware platforms like RISC-V to design cost-effective custom chips. These platforms lower entry barriers and reduce licensing costs, making ASIC development more accessible and flexible. Engineers gain greater control over hardware architecture, allowing for improved security, optimization, and scalability. The trend aligns with the growing demand for transparent, auditable systems in mission-critical IoT use cases. It encourages innovation by reducing dependence on proprietary instruction sets and fostering broader collaboration.
Adoption of Advanced Packaging and Heterogeneous Integration Techniques
Advancements in chip packaging technologies are enabling compact yet powerful ASIC solutions. The Global IoT ASIC Market benefits from techniques such as system-in-package (SiP), 2.5D integration, and chiplets that combine different dies within a single module. These approaches allow for improved thermal management, reduced latency, and enhanced functionality in space-constrained IoT devices. Companies use these innovations to pack processing units, memory, RF components, and sensors into compact form factors. It helps meet design requirements in wearables, medical implants, and smart sensors. The shift toward heterogeneous integration is redefining performance benchmarks for custom silicon in the IoT domain.
Market Challenges Analysis:
High Development Costs and Lengthy Design Cycles Restrain Adoption
Custom ASIC development involves significant upfront investment in design, prototyping, and fabrication. The Global IoT ASIC Market faces constraints from these high entry barriers, particularly for startups and small-to-mid-sized enterprises. Unlike general-purpose chips, ASICs demand tailored engineering, specialized tools, and extensive validation, all of which increase time-to-market. These factors slow innovation and limit flexibility when product requirements evolve. Many companies struggle to justify the cost without guaranteed high-volume deployment. It creates a dependency on large-scale applications to achieve a viable return on investment.
Complexity of Supply Chain and Limited Access to Advanced Foundries
The reliance on advanced semiconductor fabrication facilities presents a critical bottleneck. The Global IoT ASIC Market experiences delays and design compromises due to constrained access to cutting-edge process nodes offered by leading foundries. Global chip shortages and geopolitical tensions further disrupt supply chain continuity, increasing lead times and development risks. Companies developing IoT ASICs must compete for production slots with high-demand sectors like consumer electronics and automotive. It puts pressure on timelines and cost efficiency, making it harder to scale production rapidly. The need for geographic diversification and stable sourcing strategies continues to challenge market expansion.
Market Opportunities:
Expansion of Smart Infrastructure and Connected Ecosystems Creates Growth Potential
The acceleration of smart city initiatives and connected infrastructure projects presents a significant opportunity. The Global IoT ASIC Market stands to benefit from increasing deployments of intelligent transportation systems, utility management networks, and public safety platforms. These applications require energy-efficient, high-performance chips capable of supporting real-time data exchange and low-power operation. Governments and private stakeholders are investing in localized, sensor-rich environments, creating demand for customized silicon solutions. It enables optimized device operation tailored to specific urban and industrial use cases. The need for scalable, secure, and reliable ASICs will grow as cities become more connected.
Emerging Demand in Low-Power Wearables and Medical IoT Devices
The rise of digital health and fitness technologies creates new demand for compact, low-power ASICs. The Global IoT ASIC Market is well-positioned to serve this segment, where precise sensing and extended battery life are critical. Medical wearables, remote diagnostic tools, and biosensors rely on ASICs for real-time monitoring and secure data handling. These devices require custom chips that can meet strict regulatory and performance standards. It allows companies to differentiate products through efficiency, accuracy, and design flexibility. The expanding role of personalized healthcare reinforces the need for application-specific ASIC innovation.
Market Segmentation Analysis:
The Global IoT ASIC Market is segmented
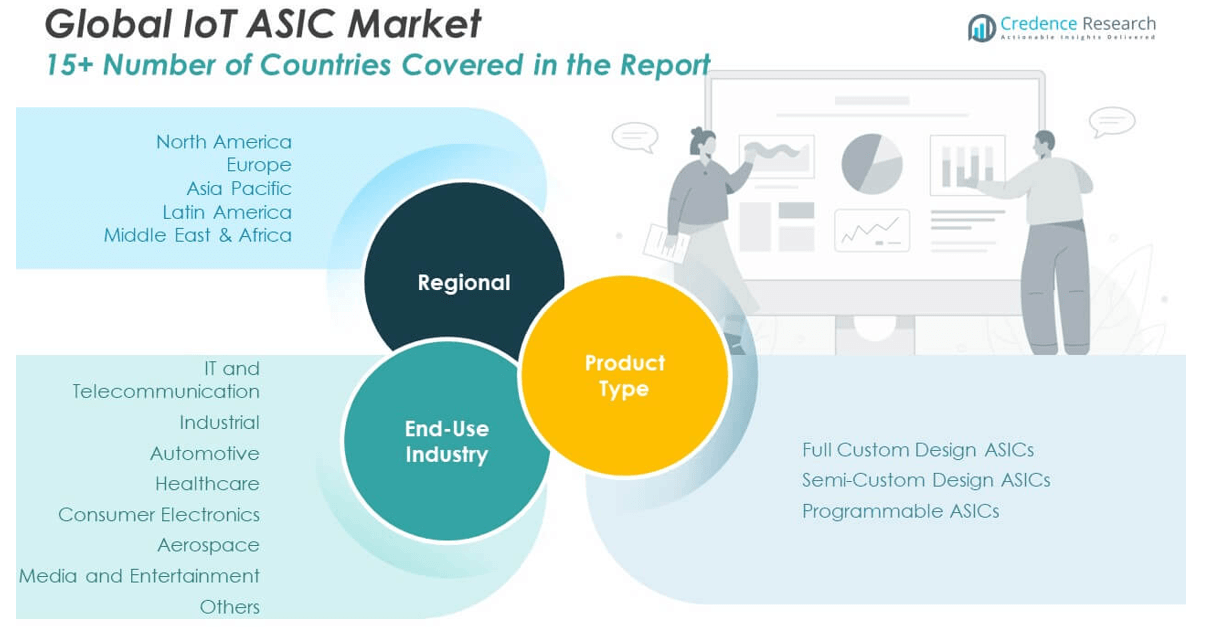
By product type into Full Custom Design ASICs, Semi-Custom Design ASICs, and Programmable ASICs. Full Custom Design ASICs lead the segment in high-volume applications due to their superior performance and optimized power efficiency. Semi-Custom Design ASICs offer flexibility and cost advantages, making them suitable for mid-scale deployments across various industries. Programmable ASICs serve niche and evolving use cases, allowing faster time-to-market and adaptability in dynamic IoT environments.
- Barefoot Networks’ Tofino™ programmable switch ASIC is a leading example. Unlike fixed-function ASICs, Tofino can be reprogrammed using high-level languages to define custom packet processing pipelines. This allows network operators to adapt to new protocols and requirements without hardware changes, enabling rapid deployment in data centers and evolving IoT environments.
By end-use industry, the market is segmented into IT and Telecommunication, Industrial, Automotive, Healthcare, Consumer Electronics, Aerospace, Media and Entertainment, and Others. The IT and Telecommunication segment holds a significant share, driven by demand for network optimization and cloud-edge integration. The industrial segment follows, with growing use of ASICs in automation, predictive maintenance, and asset tracking. Automotive applications are expanding, supported by electrification and autonomous driving technologies. Healthcare and consumer electronics continue to adopt ASICs for wearable devices, remote monitoring, and smart home solutions. Aerospace and media segments present emerging opportunities driven by secure, high-performance edge processing.
- For example, Swindon Silicon Systems’ custom ASICs for industrial control systems enhance automation, predictive maintenance, and asset tracking by integrating sensing, data processing, and communication in a single chip.
Segmentation:
By Product Type
- Full Custom Design ASICs
- Semi-Custom Design ASICs
- Programmable ASICs
By End-Use Industry
- IT and Telecommunication
- Industrial
- Automotive
- Healthcare
- Consumer Electronics
- Aerospace
- Media and Entertainment
- Others
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America IoT ASIC Market size was valued at USD 1,657.43 million in 2018 to USD 3,281.44 million in 2024 and is anticipated to reach USD 9,903.28 million by 2032, at a CAGR of 13.8% during the forecast period. North America holds the largest share of the Global IoT ASIC Market, driven by strong demand from sectors such as industrial automation, smart homes, healthcare, and automotive. The region benefits from a mature IoT ecosystem and robust investment in AI-driven edge devices. Major tech companies in the United States are leading the development of custom ASICs to support hyperscale data centers and 5G-enabled applications. It also gains from established semiconductor manufacturing capabilities and R&D infrastructure. The region’s focus on cybersecurity and energy-efficient devices further boosts the adoption of ASICs across smart infrastructure and consumer electronics. Government funding and strategic public-private partnerships continue to reinforce North America's leadership in IoT innovation.
The Europe IoT ASIC Market size was valued at USD 1,098.11 million in 2018 to USD 2,092.86 million in 2024 and is anticipated to reach USD 5,749.54 million by 2032, at a CAGR of 12.5% during the forecast period. Europe commands a significant share of the Global IoT ASIC Market, with strong growth in automotive, healthcare, and smart manufacturing sectors. Countries such as Germany, France, and the Netherlands are investing in Industry 4.0 and digital health infrastructure, driving demand for application-specific chips. European companies are adopting ASICs to meet region-specific regulatory and efficiency standards. It also benefits from strong collaboration between research institutions and semiconductor firms. The focus on sustainable technology and green energy solutions encourages the use of energy-efficient ASICs in industrial and utility networks. European Union policies supporting semiconductor independence and digital transformation contribute to long-term market expansion.
The Asia Pacific IoT ASIC Market size was valued at USD 2,378.30 million in 2018 to USD 4,963.25 million in 2024 and is anticipated to reach USD 15,851.76 million by 2032, at a CAGR of 14.6% during the forecast period. Asia Pacific represents the fastest-growing regional market, driven by mass-scale IoT deployments in China, Japan, South Korea, and India. The Global IoT ASIC Market gains momentum in this region due to high consumer demand for smart devices and significant government investment in digital infrastructure. Leading semiconductor foundries and electronics manufacturers provide strong support for ASIC production. It benefits from cost advantages, rapid industrialization, and a competitive manufacturing ecosystem. Smart city initiatives, connected transportation systems, and large-scale adoption of wearables are fueling chip-level innovation. Local startups and global players continue to expand their footprint across Asia Pacific, reinforcing its role in global IoT growth.
The Latin America IoT ASIC Market size was valued at USD 252.97 million in 2018 to USD 502.01 million in 2024 and is anticipated to reach USD 1,327.70 million by 2032, at a CAGR of 11.9% during the forecast period. Latin America is experiencing steady growth in the Global IoT ASIC Market, supported by rising demand in agriculture, logistics, and energy sectors. Countries such as Brazil, Mexico, and Argentina are deploying IoT-based solutions to improve productivity and sustainability. It is seeing increasing interest in custom silicon to address connectivity limitations and reduce power consumption in rural and remote areas. Regional investments in smart metering, supply chain automation, and urban mobility create opportunities for tailored ASIC solutions. Local governments and businesses are gradually embracing IoT technologies to modernize legacy systems. Although infrastructure gaps remain, the potential for transformation continues to attract attention.
The Middle East IoT ASIC Market size was valued at USD 151.70 million in 2018 to USD 277.94 million in 2024 and is anticipated to reach USD 700.20 million by 2032, at a CAGR of 11.2% during the forecast period. The Middle East region shows strong potential in the Global IoT ASIC Market, led by smart city projects, oil and gas automation, and infrastructure modernization. Countries like the UAE and Saudi Arabia are driving initiatives that integrate IoT across government services, utilities, and transportation networks. It demands highly reliable and secure ASICs to support mission-critical operations in extreme environments. National visions focused on digital transformation and economic diversification are accelerating adoption. Public-private partnerships are investing in semiconductors and IoT innovation hubs to localize technology development. The region’s focus on 5G connectivity and industrial modernization continues to support long-term growth.
The Africa IoT ASIC Market size was valued at USD 54.41 million in 2018 to USD 127.62 million in 2024 and is anticipated to reach USD 265.95 million by 2032, at a CAGR of 8.6% during the forecast period. Africa holds a modest share of the Global IoT ASIC Market but shows emerging potential in energy, agriculture, and mobile healthcare. IoT adoption is gaining momentum in regions where connectivity and power supply are limited, prompting demand for low-power, cost-effective ASICs. It supports initiatives aimed at improving agricultural yield, water management, and remote patient care. Partnerships with international tech firms and development agencies are helping bridge technology access gaps. Mobile-first strategies and growth in renewable energy systems are aligning with the need for tailored silicon solutions. The gradual rollout of digital infrastructure will continue to shape the market landscape across the continent.
Key Player Analysis:
- Analog Devices
- Maxim Integrated Products
- ON Semiconductor
- Qualcomm
- Intel
- Texas Instruments
- Broadcom
- Infineon Technologies
- STMicroelectronics
- NXP Semiconductors
Competitive Analysis:
The Global IoT ASIC Market features intense competition among established semiconductor firms and emerging players focused on custom silicon design. Key companies such as Intel Corporation, NXP Semiconductors, STMicroelectronics, Broadcom Inc., and Infineon Technologies AG dominate through strong portfolios and global manufacturing capabilities. It sees rising activity from specialized design houses and fabless companies addressing niche IoT use cases with tailored ASIC solutions. Strategic partnerships, acquisitions, and vertical integration are common tactics to enhance design agility and supply chain control. Companies are prioritizing energy efficiency, security, and integration to meet evolving IoT requirements. Startups leveraging open-source hardware and AI-driven architectures are gaining traction, intensifying innovation cycles across the value chain. Competitive advantage increasingly depends on the ability to deliver scalable, low-power, and application-specific chipsets that meet industry-specific demands. The market remains dynamic, with technological leadership and ecosystem collaboration playing a central role in shaping future growth.
Recent Developments:
- In January 2025, Infineon Technologies announced the launch of its EiceDRIVER isolated gate driver ICs, specifically designed for traction inverters in electric vehicles. This product aims to enhance the efficiency and safety of EV powertrains, addressing the growing demand for advanced ASIC solutions in the automotive sector.
- In June 2025, Analog Devices launched ADVentures, a new corporate venture capital fund with an initial size of $80 million. This initiative aims to foster innovation and strategic investments in emerging technologies, including IoT and edge computing. The company also introduced an expanded CodeFusion Studio™ solution in March 2025, designed to accelerate product development and enhance data security for intelligent edge applications.
- In May 2025, Qualcomm confirmed it will launch its next-generation Snapdragon 8 Elite chip at a dedicated event in September 2025. This new chip, designed for high-performance smartphones and IoT devices, is expected to deliver significant improvements in AI and connectivity, reinforcing Qualcomm’s leadership in the IoT ASIC market.
Market Concentration & Characteristics:
The Global IoT ASIC Market exhibits moderate to high market concentration, with a few major players holding significant shares due to their strong design capabilities, manufacturing infrastructure, and global reach. It is characterized by high entry barriers, long development cycles, and a strong emphasis on innovation and customization. The market favors companies that can deliver application-specific performance, low power consumption, and integration across diverse IoT environments. Demand spans across industrial, consumer, automotive, and healthcare sectors, each requiring tailored solutions. It supports both large-scale, high-volume production and niche applications through flexible chip architectures. The market also reflects rapid technological advancement, encouraging continuous investment in R&D and strategic alliances to maintain competitiveness.
Report Coverage:
The research report offers an in-depth analysis based on Product Type and End-Use Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of smart city projects will drive demand for energy-efficient and application-specific ASICs.
- Increasing deployment of 5G networks will enhance the need for high-performance, low-latency IoT chipsets.
- Growth in wearable healthcare and remote monitoring devices will create new opportunities for compact ASICs.
- Rising emphasis on data privacy and security will push the development of ASICs with built-in encryption features.
- Advances in edge AI will support wider adoption of ASICs capable of real-time local data processing.
- Proliferation of connected consumer electronics will sustain volume growth for cost-optimized custom chips.
- Development of open-source architectures will encourage broader participation in ASIC design innovation.
- Integration of ASICs in industrial automation and predictive maintenance tools will strengthen demand in manufacturing.
- Collaboration between semiconductor firms and IoT platform providers will shape future ecosystem standards.
- Environmental regulations and demand for sustainable electronics will influence ASIC design strategies and material choices.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Edge Computing and Real-Time Processing
The shift toward edge computing is driving demand for custom IoT ASICs that can process data locally with low latency and high energy efficiency, reducing reliance on cloud infrastructure and enabling real-time analytics in industrial, healthcare, and smart city applications.
Miniaturization and Low-Power Consumption
The proliferation of battery-operated wearables, healthcare monitors, and mobile IoT devices is fueling the need for ASICs that offer compact form factors and ultra-low power consumption, supporting longer device lifespans and enabling new use cases in portable and remote environments.
Integration with 5G and Advanced Connectivity
The rollout of 5G networks is accelerating the adoption of IoT ASICs capable of handling high data throughput and low-latency communication, which is essential for smart infrastructure, autonomous vehicles, and industrial automation.
Rising Security and Data Privacy Requirements
Increasing concerns over cybersecurity in connected devices are pushing manufacturers to embed encryption, secure boot, and tamper-resistance features directly into ASICs, making them more attractive for mission-critical and regulated IoT deployments.
Industry-Specific Customization and AI Integration
Growing demand for application-specific functionality and embedded AI/ML capabilities is leading to the development of highly customized ASICs tailored for verticals such as healthcare, manufacturing, and automotive, enabling smarter, more efficient, and differentiated IoT solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global IoT ASIC Market?
What are the key segments within the Global IoT ASIC Market?
What are some challenges faced by the Global IoT ASIC Market?
Who are the major players in the Global IoT ASIC Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Full Custom Design ASICs
- 1.2.2 Semi-Custom Design ASICs
- 1.2.3 Programmable ASICs
- 1.3 By End-Use Industry
- 1.3.1 IT and Telecommunication
- 1.3.2 Industrial
- 1.3.3 Automotive
- 1.3.4 Healthcare
- 1.3.5 Consumer Electronics
- 1.3.6 Aerospace
- 1.3.7 Media and Entertainment
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,245.12 million → 2032: USD 33,798.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global IoT ASIC Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global IoT ASIC Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global IoT ASIC Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global IoT ASIC Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global IoT ASIC Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global IoT ASIC Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global IoT ASIC Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global IoT ASIC Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,245.12 million → 2032: USD 33,798.42 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global IoT ASIC Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Full Custom Design ASICs
- 12.3.7.2 Semi-Custom Design ASICs
- 12.3.7.3 Programmable ASICs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 IT and Telecommunication
- 12.4.7.2 Industrial
- 12.4.7.3 Automotive
- 12.4.7.4 Healthcare
- 12.4.7.5 Consumer Electronics
- 12.4.7.6 Aerospace
- 12.4.7.7 Media and Entertainment
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global IoT ASIC End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global IoT ASIC Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global IoT ASIC Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global IoT ASIC Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Analog Devices
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Maxim Integrated Products
- 18.4 ON Semiconductor
- 18.5 Qualcomm
- 18.6 Intel
- 18.7 Texas Instruments
- 18.8 Broadcom
- 18.9 Infineon Technologies
- 18.10 STMicroelectronics
- 18.11 NXP Semiconductors
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

