
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Italy Automotive Air Filter Market Size 2024 | USD 125.194 million |
| Italy Automotive Air Filter Market, CAGR | 4.78% |
| Italy Automotive Air Filter Market Size 2032 | USD 181.940 million |
Market Overview
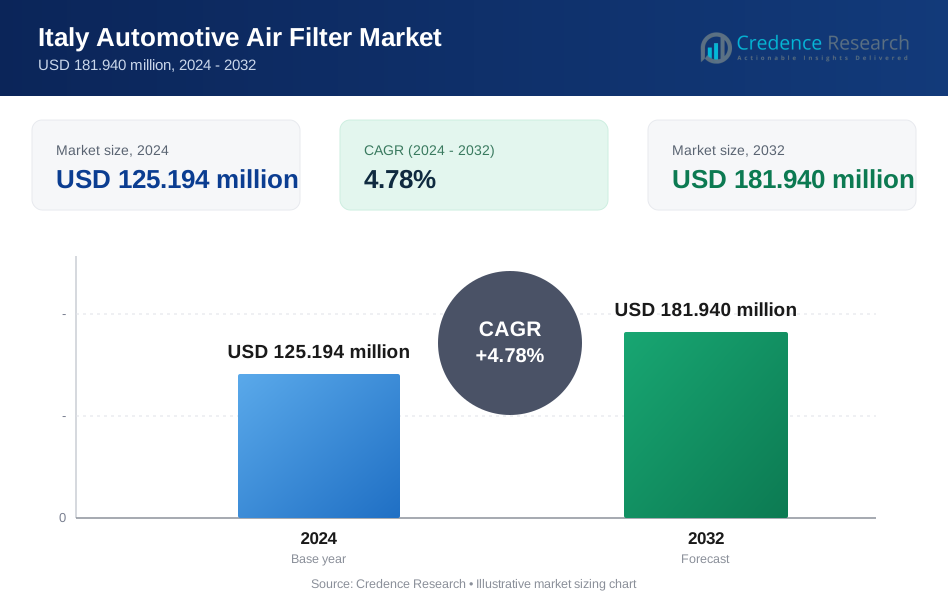
Italy Automotive Air Filter market size was valued at USD 125.194 million in 2024 and is anticipated to reach USD 181.940 million by 2032, at a CAGR of 4.78% during the forecast period (2024-2032).
The Italy automotive air filter market is driven by increasing vehicle production, growing consumer awareness of engine efficiency, and stringent emission regulations aimed at reducing air pollution. Rising demand for fuel-efficient vehicles and advancements in filtration technologies, such as nano-fiber filters, are further boosting market growth. The aftermarket segment is expanding due to frequent filter replacements driven by maintenance requirements and urban pollution levels. Additionally, the growing adoption of electric vehicles (EVs) is influencing product innovation, with manufacturers focusing on high-efficiency particulate air (HEPA) filters to enhance cabin air quality. The rising trend of sustainable and eco-friendly filters, incorporating biodegradable materials, aligns with Italy’s environmental policies. Furthermore, increasing e-commerce penetration is streamlining filter distribution and sales, enhancing accessibility for consumers.
The Italy automotive air filter market is geographically diverse, with strong demand across Northern, Central, and Southern Italy, as well as the Islands. Northern Italy, home to major automotive manufacturers and industrial hubs, leads in both OEM and aftermarket sales, while Central Italy sees high demand due to urban vehicle density. Southern Italy and the Islands contribute through growing vehicle ownership and tourism-related transportation needs. Key players driving market growth include Mann+Hummel Group, Mahle GmbH, Sogefi S.p.A., Robert Bosch GmbH, Freudenberg Filtration Technologies, Valeo S.A., A.L. Filter, Hengst SE, Filtration Group, and UFI Filters. These companies focus on technological advancements, sustainable air filters, and strategic partnerships to enhance product efficiency and market reach. With rising demand for high-performance and eco-friendly filtration solutions, these key players are investing in R&D, smart filtration technologies, and expanding their distribution networks, ensuring continued market evolution in Italy’s dynamic automotive sector.
Market Insights
- The Italy automotive air filter market was valued at USD 125.194 million in 2024 and is projected to reach USD 181.940 million by 2032, growing at a CAGR of 4.78%.
- Increasing vehicle production and stringent emission regulations are driving the demand for high-efficiency air filters in both OEM and aftermarket segments.
- Growing consumer awareness of cabin air quality and rising urban pollution levels are boosting demand for HEPA and activated carbon filters.
- The market is witnessing technological advancements, including smart air filters with real-time monitoring sensors and eco-friendly biodegradable materials.
- Intense competition and the presence of low-cost alternatives create pricing challenges, while counterfeit products in the aftermarket segment affect brand credibility.
- Northern Italy dominates due to strong automotive manufacturing, while Central and Southern Italy see rising demand for replacement filters in densely populated areas.
- Leading companies focus on R&D, sustainable solutions, and digital sales channels to maintain competitiveness and expand market reach.
Market Drivers
Stringent Emission Regulations and Environmental Concerns
Italy's automotive air filter market is significantly driven by strict emission regulations imposed by the European Union and national authorities. These regulations aim to reduce vehicular emissions and improve air quality, necessitating advanced filtration technologies. For instance, the European Commission's proposal to reduce air pollution levels from new vehicles aligns with the European Green Deal’s zero-pollution target, driving the demand for high-performance air filters. Additionally, Italy’s commitment to sustainability and carbon neutrality goals encourages manufacturers to develop eco-friendly and recyclable filter materials. As regulatory bodies continue enforcing cleaner mobility solutions, the demand for high-performance air filters is expected to rise, positively influencing market growth.
Increasing Vehicle Production and Growing Aftermarket Demand
Italy is home to a well-established automotive manufacturing sector, including brands like Ferrari, Lamborghini, and Fiat. The rising production of passenger and commercial vehicles directly impacts the demand for air filters, as these components are essential for engine efficiency and longevity. For example, the European Automobile Manufacturers’ Association reported a significant growth in car sales across the EU, highlighting the strong recovery in the automotive sector. Additionally, the expanding aftermarket segment plays a crucial role in market growth. Air filters require periodic replacements due to clogging and wear, leading to a steady demand for aftermarket products. Urban pollution levels and frequent maintenance schedules further drive filter replacements, particularly in cities with high vehicle density. The presence of a well-structured automotive service network and increasing e-commerce sales channels also contribute to the ease of filter replacement, fostering aftermarket growth.
Technological Advancements in Filtration Systems
Innovation in air filtration technologies is a key driver for the Italian market. Traditional filters are being replaced with high-efficiency particulate air (HEPA) filters, activated carbon filters, and nanofiber-based filtration systems, which offer superior performance in trapping fine particles and pollutants. Automakers are focusing on enhanced cabin air filters to improve passenger health by filtering allergens, bacteria, and harmful gases. Additionally, advancements in synthetic and biodegradable filter materials contribute to sustainability efforts while ensuring higher filtration efficiency. The demand for smart air filtration systems, integrated with sensors for real-time air quality monitoring, is also increasing, particularly in luxury and electric vehicles. These innovations not only align with environmental policies but also enhance overall vehicle performance and consumer satisfaction.
Growing Adoption of Electric Vehicles (EVs) and Sustainable Solutions
The increasing shift towards electric vehicles (EVs) in Italy is reshaping the automotive air filter market. While traditional engine air filters are not required in EVs, the demand for cabin air filters is rising due to enhanced focus on passenger comfort and health. Automakers are incorporating multi-layered air filters with anti-bacterial and anti-viral properties to meet consumer expectations. Additionally, the push for sustainable and recyclable filter materials is driving R&D investments in the sector. With Italy’s government offering incentives for EV adoption and promoting eco-friendly vehicle components, manufacturers are leveraging sustainable innovations to maintain market competitiveness. As the automotive industry moves towards greener mobility solutions, air filter manufacturers are adapting to new demands, ensuring continued market growth.
Market Trends
Rising Demand for High-Efficiency Filtration Systems
The Italy automotive air filter market is witnessing a growing demand for high-efficiency filtration systems, driven by increasing awareness of air quality and stricter emission standards. Consumers are prioritizing vehicles equipped with advanced air filtration technologies, such as HEPA (High-Efficiency Particulate Air) filters and activated carbon filters, which provide superior filtration of dust, allergens, and harmful pollutants. For instance, companies like Eurogielle are specializing in designing and producing high-quality cabin air filters that cater to all vehicle categories, emphasizing the importance of advanced filtration in maintaining in-cabin air quality. Automakers are integrating these technologies into both engine and cabin air filters to enhance vehicle performance and passenger health. As air pollution remains a concern in urban areas, the shift towards high-performance and long-lasting filters continues to shape market trends.
Growth of the Aftermarket Segment and E-Commerce Expansion
The aftermarket segment is expanding rapidly due to the rising demand for replacement air filters, which require periodic changes to maintain vehicle efficiency. Increasing vehicle ownership and longer vehicle lifespans are further driving the need for frequent air filter replacements, especially in commercial and passenger vehicles. For example, the Italian e-commerce market for vehicle parts has seen significant growth, with platforms offering a wide range of air filters at competitive prices, making it easier for consumers to access high-quality products online. Additionally, the rise of e-commerce platforms has transformed the way consumers purchase automotive parts, including air filters. Online marketplaces and direct-to-consumer sales channels are offering convenience, competitive pricing, and a wide variety of products, enabling consumers to access high-quality filters without relying solely on traditional brick-and-mortar stores.
Integration of Smart Filtration Technologies
The trend of smart air filtration systems is gaining traction in Italy’s automotive sector, with manufacturers integrating sensor-based technologies to monitor air quality in real-time. These smart filters provide alerts for replacements and ensure optimal performance by adapting to environmental conditions. Advanced filtration systems with AI-driven functionalities are also being developed to improve energy efficiency and extend filter lifespan. This innovation aligns with the increasing demand for connected vehicles and enhances user experience by offering proactive maintenance solutions. As automakers continue to adopt IoT-based filtration technologies, the market is expected to see sustained growth in smart air filter solutions.
Shift Toward Eco-Friendly and Sustainable Materials
Sustainability is a key trend shaping the Italy automotive air filter market, with manufacturers investing in biodegradable and recyclable materials for filter production. Traditional synthetic filters are being replaced by eco-friendly alternatives, such as plant-based fiber filters and reusable air filters, to reduce environmental impact. The push for sustainable mobility solutions, combined with Italy’s focus on green automotive technologies, is accelerating the adoption of environmentally friendly filtration products. Automakers and suppliers are also exploring ways to reduce manufacturing emissions and energy consumption by incorporating low-carbon production processes. As Italy advances its carbon neutrality goals, the shift toward sustainable air filter solutions will remain a dominant market trend.
Market Challenges Analysis
Rising Competition and Price Pressure
The Italy automotive air filter market faces intense competition from both established manufacturers and emerging low-cost suppliers. The presence of global and regional players has led to price pressure, compelling companies to offer cost-effective solutions without compromising quality. For instance, Mann+Hummel has expanded its aftermarket offerings by introducing new part numbers to cater to a broader range of vehicles, emphasizing the need for manufacturers to balance cost with quality to remain competitive. While premium air filters with advanced filtration technologies are in demand, many consumers and fleet operators prioritize affordability, leading to increased competition among manufacturers. Additionally, the rise of counterfeit and low-quality air filters in the aftermarket segment poses challenges for brand credibility and consumer safety. To remain competitive, companies must focus on product differentiation, innovation, and strategic pricing while maintaining high-performance standards.
Impact of Electric Vehicle (EV) Adoption on Traditional Air Filters
The growing adoption of electric vehicles (EVs) in Italy presents a significant challenge for manufacturers of engine air filters. Unlike internal combustion engine (ICE) vehicles, EVs do not require traditional engine air filters, which could lead to a decline in demand for these components. As Italy continues to promote EV adoption through incentives and infrastructure development, manufacturers must adapt by shifting their focus toward cabin air filtration systems and advanced air purification technologies. The industry must also invest in R&D for smart and sustainable air filters that align with evolving vehicle technologies. Companies that fail to diversify their product offerings risk losing market share as the automotive sector transitions toward cleaner and greener mobility solutions.
Market Opportunities
The Italy automotive air filter market presents significant growth opportunities driven by advancements in filtration technologies and increasing consumer demand for high-performance air filters. With growing awareness of air quality and vehicle efficiency, manufacturers have the opportunity to develop next-generation filtration systems, such as HEPA filters, activated carbon filters, and nanofiber-based filters, which provide superior air purification. Additionally, the expansion of the electric vehicle (EV) market opens doors for specialized cabin air filtration solutions, catering to the increasing emphasis on passenger health and comfort. Automakers and suppliers investing in smart filtration technologies, including sensor-equipped air filters for real-time monitoring, can gain a competitive edge in the market.
Sustainability initiatives further create opportunities for manufacturers to innovate with eco-friendly and biodegradable filter materials that align with Italy’s environmental goals and carbon neutrality targets. The rising demand for aftermarket air filters, driven by frequent replacements and increasing vehicle longevity, also offers potential for business expansion, particularly through e-commerce and direct-to-consumer sales channels. Companies that leverage digital platforms to enhance product accessibility, pricing transparency, and customer engagement can strengthen their market position. Additionally, collaborations between automotive OEMs and filtration technology providers can drive the development of customized, high-efficiency filters, ensuring long-term growth in the evolving automotive landscape.
Market Segmentation Analysis:
By Type:
The Italy automotive air filter market is segmented into cabin air filters and engine air filters, both of which play a critical role in vehicle performance and passenger safety. Cabin air filters are experiencing growing demand due to increasing consumer awareness of airborne pollutants, allergens, and harmful gases inside vehicles. The rise in urban pollution levels, along with the adoption of electric vehicles (EVs), has further accelerated the need for high-efficiency cabin air filtration systems, such as HEPA and activated carbon filters. Automakers are integrating advanced multi-layered cabin filters to improve in-car air quality, making this segment a key area for growth. On the other hand, engine air filters remain essential for internal combustion engine (ICE) vehicles, ensuring optimal airflow to the engine while preventing dust, debris, and contaminants from affecting performance. However, as EV adoption increases, demand for engine air filters may decline. To address this shift, manufacturers are innovating with longer-lasting, high-performance engine filters to maintain relevance in the market.
By Material:
Based on material, the Italy automotive air filter market is categorized into paper, foam, and synthetic filters, each offering distinct advantages. Paper-based air filters are the most widely used due to their cost-effectiveness, ease of replacement, and efficient filtration capabilities. They are commonly used in both cabin and engine applications, making them a preferred choice in the aftermarket segment. However, their limited lifespan and disposal concerns are driving interest in more durable alternatives. Foam air filters provide enhanced airflow and durability, making them suitable for high-performance and off-road vehicles. These filters are reusable and offer longer service life, catering to consumers looking for cost-effective and environmentally friendly solutions. Meanwhile, synthetic air filters, known for their high-efficiency filtration and extended lifespan, are gaining popularity, particularly in premium and luxury vehicles. With advancements in nanofiber and electrostatic filtration technologies, synthetic filters are emerging as a preferred choice for both engine and cabin applications, ensuring sustained market growth in the coming years.
Segments:
Based on Type:
- Cabin Air Filter
- Engine Air Filter
Based on Material:
- Paper
- Foam
- Synthetic
Based on Vehicle:
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
Based on Distribution Channel:
- OEMs
- Aftermarket
Based on the Geography:
- Northern Italy
- Milan
- Turin
- Venice
- Southern Italy
- Naples
- Palermo
- Bari
- Central Italy
- Rome
- Florence
- Bologna
Regional Analysis
Northern Italy
Northern Italy dominates the market with a share of approximately 42%, driven by its strong automotive manufacturing sector and high vehicle ownership rates. The presence of major automotive brands and industrial hubs in Milan, Turin, and Venice fuels demand for high-quality air filtration systems. Turin, as the home of Fiat and other automotive manufacturers, plays a crucial role in both OEM and aftermarket sales. Additionally, Milan’s dense urban traffic increases the need for frequent air filter replacements, especially for cabin air filters. Venice, with its unique environmental conditions, also contributes to the demand for high-efficiency filtration solutions in both passenger and commercial vehicles.
Central Italy
Central Italy holds a market share of approximately 25%, with Rome, Florence, and Bologna being key contributors. Rome, the capital and one of the most populated cities in Italy, has a high vehicle density, leading to increased air filter consumption in the aftermarket segment. Florence and Bologna, known for their strong industrial and commercial activities, further boost the market by driving demand for both engine and cabin air filters. Additionally, Central Italy's focus on sustainable urban mobility and the adoption of electric vehicles (EVs) is shifting market trends toward advanced cabin filtration technologies. The presence of key automotive suppliers and service centers in this region enhances the availability and distribution of premium and eco-friendly air filters.
Southern Italy
Southern Italy accounts for around 18% of the market share, with major contributions from Naples, Palermo, and Bari. The region has a growing automotive sector, with an increasing number of passenger vehicles and light commercial vehicles. Naples, as one of Italy’s busiest metropolitan areas, experiences high pollution levels, leading to greater demand for high-efficiency cabin air filters. Palermo and Bari, with their expanding urban populations, are also witnessing a rise in the aftermarket segment, as consumers prioritize regular vehicle maintenance. However, economic challenges in this region sometimes limit the adoption of premium air filters, making cost-effective options more popular.
Key Player Analysis
- Mann+Hummel Group
- Mahle GmbH
- Sogefi S.p.A.
- Robert Bosch GmbH
- Freudenberg Filtration Technologies
- Valeo S.A.
- A.L. Filter
- Hengst SE
- Filtration Group
- UFI Filters
Competitive Analysis
The Italy automotive air filter market is highly competitive, with leading players such as Mann+Hummel Group, Mahle GmbH, Sogefi S.p.A., Robert Bosch GmbH, Freudenberg Filtration Technologies, Valeo S.A., A.L. Filter, Hengst SE, Filtration Group, and UFI Filters driving market growth through innovation and strategic expansion. These companies focus on product development, advanced filtration technologies, and sustainability initiatives to strengthen their market position. Leading manufacturers invest in advanced filtration technologies, such as HEPA filters, activated carbon filters, and smart air filtration systems, to meet growing consumer demand for high-efficiency and eco-friendly solutions. The industry is also witnessing a shift towards biodegradable and reusable filter materials, aligning with Italy’s sustainability goals.
Market players are strengthening their positions through strategic partnerships, acquisitions, and digital sales platforms, enhancing product accessibility and customer reach. The rising importance of aftermarket sales due to increasing vehicle longevity is driving competition in replacement air filters, with companies offering cost-effective and durable solutions. Additionally, OEM collaborations and investments in automated manufacturing processes are improving product quality and reducing costs. As electric vehicle adoption grows, companies are adapting by focusing on cabin air filtration systems, ensuring long-term market sustainability.
Recent Developments
- In January 2025, Donaldson Company, Inc. partnered with Daimler Truck North America to feature its advanced air filter technology in the Freightliner SuperTruck III, a hydrogen fuel cell truck project.
- In January 2025, Freudenberg Filtration Technologies introduced the "micronAir Gas Shield" line, a premium activated carbon selection for automotive cabin air filters, offering regionally customized options to adsorb harmful gases and odors.
- In July 2024, Mann+Hummel launched nanofiber-based cabin air filters, known as Mann-Filter FreciousPlus, which effectively filter ultra-fine particles and pollutants.
- In January 2024, Robert Bosch GmbH replaced the FILTER+ cabin air filter with the enhanced FILTER+pro, offering improved filtration performance and reduced germ transmission.
Market Concentration & Characteristics
The Italy automotive air filter market exhibits a moderate to high market concentration, with a mix of global leaders and regional manufacturers dominating the industry. Established players leverage their strong distribution networks, advanced filtration technologies, and OEM partnerships to maintain a competitive edge. The market is characterized by continuous innovation, with a focus on high-efficiency, eco-friendly, and smart filtration systems that meet evolving consumer and regulatory demands. Additionally, the growing aftermarket segment presents opportunities for smaller manufacturers, as vehicle longevity and maintenance awareness drive demand for replacement filters. The industry is also influenced by price competition and the rise of counterfeit products, requiring brands to emphasize quality assurance and brand differentiation. As Italy transitions towards electric mobility and sustainable automotive solutions, manufacturers are adapting by developing next-generation cabin air filters and investing in digital sales platforms to enhance accessibility and market reach.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Vehicle, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for high-efficiency cabin air filters will rise due to increasing concerns about air pollution and passenger health.
- The shift towards electric vehicles (EVs) will reduce demand for traditional engine air filters while boosting cabin air filtration technologies.
- Manufacturers will focus on sustainable and biodegradable filter materials to align with Italy’s environmental regulations.
- Advancements in smart air filtration systems with real-time monitoring sensors will enhance air quality management in vehicles.
- The aftermarket segment will continue to expand as vehicle longevity and maintenance awareness drive frequent filter replacements.
- Companies will strengthen digital sales platforms and e-commerce strategies to improve product accessibility and customer engagement.
- Growing investments in research and development will lead to innovative filtration technologies with improved efficiency and durability.
- Strategic collaborations with OEMs and automotive suppliers will help manufacturers expand their market presence.
- The rise of counterfeit products will push companies to focus on brand protection and quality assurance measures.
- Government regulations on vehicle emissions and air quality standards will influence future product development and innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Italy Automotive Air Filter market?
What factors are driving the growth of the Italy Automotive Air Filter market?
What are some challenges faced by the Italy Automotive Air Filter market?
Who are the major players in the Italy Automotive Air Filter market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Italy Automotive Air Filter Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Italy Automotive Air Filter Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 125.194 million → 2032: USD 181.940 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Italy Automotive Air Filter Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Italy Automotive Air Filter Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Italy Automotive Air Filter Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Italy Automotive Air Filter Market Drivers
- 3.3 Italy Automotive Air Filter Market Restraints & Challenges
- 3.4 Italy Automotive Air Filter Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Italy Automotive Air Filter Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Italy Automotive Air Filter Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Italy Automotive Air Filter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Italy Automotive Air Filter Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Italy Automotive Air Filter Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Italy Automotive Air Filter market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Italy Automotive Air Filter Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Italy Automotive Air Filter Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Italy Automotive Air Filter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Italy Automotive Air Filter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Italy Automotive Air Filter Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Italy Automotive Air Filter Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Italy Automotive Air Filter Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Italy Automotive Air Filter Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Italy Automotive Air Filter Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Italy Automotive Air Filter Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Italy Automotive Air Filter Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Italy Automotive Air Filter Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Italy Automotive Air Filter Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
