
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan Artificial Intelligence in Retail Market Size 2023 | USD 460.71 million |
| Japan Artificial Intelligence in Retail Market, CAGR | 31.66% |
| Japan Artificial Intelligence in Retail Market Size 2032 | USD 5,480.14 million |
Market Overview
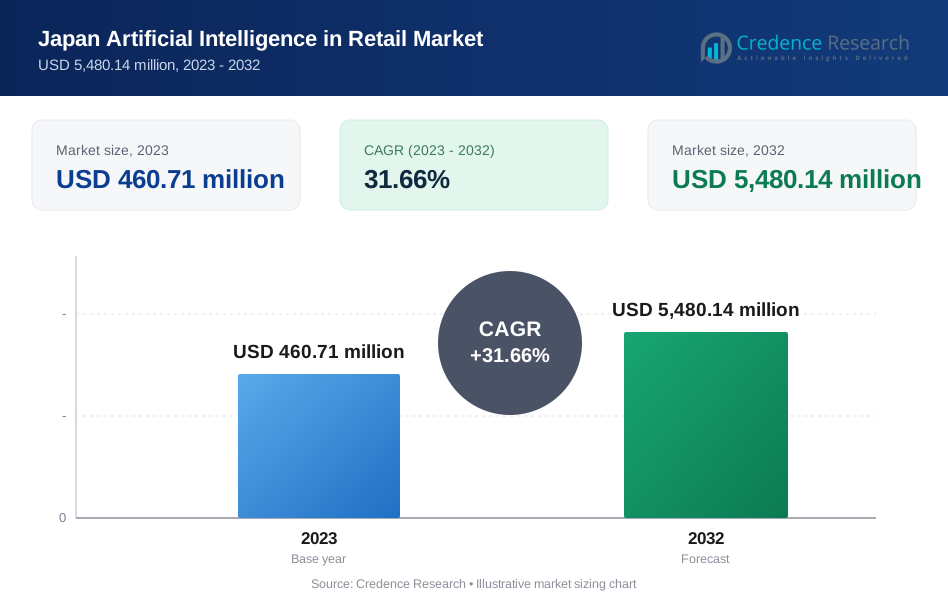
The Japan artificial intelligence in retail market is projected to grow significantly from USD 460.71 million in 2023 to USD 5,480.14 million by 2032, registering a robust CAGR of 31.66% during the forecast period.
The Japan artificial intelligence in retail market is driven by the increasing adoption of AI-powered solutions to enhance customer experience, optimize supply chain operations, and enable personalized marketing strategies. Retailers are leveraging AI technologies such as machine learning, computer vision, and natural language processing to streamline inventory management, reduce operational costs, and improve decision-making processes. The growing integration of AI in e-commerce platforms to offer tailored product recommendations and predictive analytics further boosts market growth. Additionally, advancements in robotics and automated checkout systems are reshaping traditional retail environments, providing enhanced convenience and efficiency. Key trends include the rising use of AI-driven chatbots for customer service, adoption of visual recognition systems for seamless shopping experiences, and the implementation of predictive analytics for demand forecasting. Supportive government initiatives promoting digital transformation and innovation in AI technologies also contribute to the rapid expansion of the market.
The geographical analysis of the Japan artificial intelligence in retail market highlights the adoption of AI technologies across key regions such as Kanto, Kansai, Chubu, and Kyushu. These regions are witnessing significant growth driven by advancements in technology, robust digital infrastructure, and government initiatives promoting AI integration. Major urban areas like Tokyo and Osaka are at the forefront, utilizing AI for personalized marketing, inventory optimization, and automated customer interactions. The market also features prominent global and domestic players such as Infosys, TCS, Google LLC, IBM Corporation, Accenture, NVIDIA, Salesforce, Microsoft Corporation, SAP SE, Oracle Corporation, Amazon, ServiceNow, and Bloomreach, Inc. These companies are driving innovation by offering AI-powered solutions tailored to the retail sector, including predictive analytics, robotics, and customer service tools. Their strategic focus on product development, partnerships, and investments in AI research is further propelling the growth of AI adoption in Japan’s retail industry.
Market Insights
- The Japan Artificial Intelligence in Retail market is valued at USD 460.71 million in 2023 and is projected to reach USD 5,480.14 million by 2032, growing at a CAGR of 31.66%.
- Increasing adoption of AI technologies to enhance customer experience and streamline retail operations is a key market driver.
- Retailers are leveraging AI for personalized marketing, inventory management, and predictive analytics to optimize supply chains.
- AI-driven solutions like automated checkout systems and robotics are transforming traditional retail environments.
- The market is highly competitive with key players such as Infosys, TCS, Google LLC, IBM Corporation, and Accenture dominating the space.
- High implementation costs and data privacy concerns are major market restraints hindering widespread AI adoption.
- The Kanto and Kansai regions are leading the market, driven by strong technological infrastructure and government support for AI integration.
Market Drivers
Enhanced Customer Experience Through Personalization
The demand for personalized shopping experiences is a key driver of the Japan artificial intelligence in retail market. Retailers are increasingly leveraging AI technologies, such as machine learning and natural language processing, to analyze customer preferences, purchasing behavior, and browsing patterns. This enables them to deliver tailored product recommendations, targeted promotions, and customized offers, enhancing customer satisfaction and loyalty. For instance, a report by Google revealed that Japanese consumers expect streamlined, intuitive shopping experiences, with AI playing a central role in meeting these demands. AI-powered chatbots and virtual assistants also play a pivotal role in improving customer interactions, providing instant support, and resolving queries efficiently. As consumers seek more personalized and seamless shopping experiences, the adoption of AI in retail continues to gain momentum.
Optimization of Supply Chain and Inventory Management
AI is revolutionizing supply chain operations and inventory management in the retail sector. Retailers are utilizing AI-driven predictive analytics to forecast demand accurately, optimize inventory levels, and reduce stockouts or overstocking issues. These capabilities help minimize operational costs and improve supply chain efficiency. For instance, AI Smiley reported that Japanese companies are primarily using AI for predictive analytics, automated customer support, and demand forecasting. Additionally, AI-powered solutions enable retailers to monitor real-time data, analyze market trends, and adapt quickly to changing consumer demands. With Japan’s focus on innovation and operational efficiency, AI-driven supply chain optimization is a significant growth driver in the market.
Advancements in Automated Retail Solutions
The increasing adoption of automated retail technologies, such as self-checkout systems and AI-enabled robotics, is transforming the shopping experience in Japan. Automated checkout systems powered by AI allow for faster and more convenient transactions, reducing wait times and enhancing customer satisfaction. Similarly, robotics is being employed for tasks like shelf stocking, product delivery, and store maintenance, improving operational efficiency and reducing labor costs. These advancements align with Japan’s technological leadership and growing emphasis on automation in retail operations.
Government Support for AI Adoption
Supportive government initiatives aimed at fostering digital transformation and innovation in AI technologies further propel market growth. The Japanese government actively promotes the integration of AI across industries, including retail, through funding programs, research collaborations, and policy support. These efforts encourage retailers to adopt advanced AI solutions, driving innovation and enabling the sector to remain competitive in a rapidly evolving digital landscape.
Market Trends
Adoption of Computer Vision for Visual Recognition
The use of computer vision in retail is on the rise, with applications ranging from facial recognition to automated inventory tracking. Retailers in Japan are increasingly deploying AI-driven visual recognition systems to enable seamless checkout experiences, enhance store security, and analyze customer behavior within physical stores. For instance, AI-powered cameras can monitor foot traffic and heat maps, helping retailers optimize store layouts and improve customer flow. This trend aligns with Japan’s reputation as a leader in technology adoption and innovation, particularly in industries that benefit from advanced AI capabilities.
Growing Integration of AI in E-Commerce Platforms
The increasing integration of AI technologies into e-commerce platforms is a significant trend shaping the Japan artificial intelligence in retail market. Retailers are leveraging AI-driven tools such as predictive analytics and recommendation engines to enhance customer engagement and boost sales. These tools analyze user data, including browsing patterns and purchase history, to deliver tailored product suggestions and personalized marketing campaigns. Additionally, AI-powered search functionalities enable customers to find products more easily, improving their overall shopping experience. As Japan’s e-commerce sector continues to expand, the adoption of AI in this space is becoming indispensable.
Expansion of AI-Driven Customer Service Tools
AI-powered customer service tools, such as chatbots and virtual assistants, are gaining prominence in Japan’s retail sector. These solutions help retailers provide 24/7 support, answer customer queries, and resolve complaints efficiently. AI-driven tools also use sentiment analysis to better understand customer emotions, enabling businesses to respond more empathetically and improve brand loyalty. As Japanese consumers increasingly expect quick and personalized interactions, the adoption of AI in customer service is expected to grow rapidly.
Focus on Sustainable Retail Practices
Sustainability is emerging as a key trend in Japan’s retail sector, with AI playing a critical role in promoting eco-friendly practices. Retailers are using AI to optimize energy consumption, reduce waste, and implement efficient logistics solutions. For example, AI-powered forecasting tools help minimize overproduction and excess inventory, contributing to a more sustainable supply chain. As environmental concerns become more prominent, the focus on integrating AI to achieve sustainable retail operations is expected to intensify in Japan.
Market Challenges Analysis
High Implementation Costs and Technical Complexity
The high costs associated with implementing AI technologies pose a significant challenge for the Japan artificial intelligence in retail market. Developing and deploying AI-driven solutions require substantial investments in infrastructure, advanced hardware, software, and skilled personnel. Small and medium-sized retailers often face financial constraints, making it difficult to adopt these cutting-edge technologies. Additionally, the technical complexity of integrating AI into existing retail systems, such as supply chain management and point-of-sale solutions, can be daunting. Many retailers lack the expertise to manage AI implementation, further delaying its adoption. These challenges highlight the need for cost-effective solutions and robust support systems to facilitate AI integration in the retail sector.
Data Privacy Concerns and Regulatory Compliance
Data privacy and regulatory compliance present another major hurdle for the adoption of AI in Japan’s retail market. AI systems rely heavily on collecting and analyzing vast amounts of customer data to deliver personalized experiences. However, increasing consumer awareness and concerns about data security have raised questions about the ethical use of AI and the risk of data breaches. For instance, a report by CBRE Japan noted that data privacy and security are top concerns for retailers when implementing AI technologies. Retailers must comply with stringent privacy regulations, such as Japan’s Act on the Protection of Personal Information (APPI), which adds to the complexity of deploying AI solutions. Ensuring transparency, secure data handling, and adherence to privacy laws is critical for retailers to build consumer trust and fully realize the potential of AI technologies.
Market Opportunities
Growing Demand for Advanced Retail Technologies
The rising demand for advanced retail technologies presents significant opportunities for the Japan artificial intelligence in retail market. Retailers are increasingly adopting AI-driven tools to enhance operational efficiency, improve customer experiences, and gain a competitive edge. Opportunities lie in leveraging AI for predictive analytics, enabling accurate demand forecasting and optimized inventory management. Additionally, AI-powered solutions such as automated checkout systems, robotics for in-store operations, and personalized marketing tools are gaining traction, creating avenues for innovation. The growing e-commerce sector in Japan further boosts the demand for AI technologies, as retailers seek to integrate sophisticated algorithms to analyze consumer behavior, offer tailored recommendations, and streamline the online shopping experience.
Expansion into Untapped Segments and Sustainability Initiatives
Untapped retail segments, including small and medium-sized enterprises (SMEs), provide a lucrative growth avenue for AI solution providers. With the increasing availability of cost-effective and scalable AI technologies, SMEs are better positioned to adopt these solutions to enhance their operations and customer engagement. Furthermore, the emphasis on sustainability in Japan’s retail sector offers opportunities to integrate AI in promoting eco-friendly practices. AI can be utilized for energy optimization, waste reduction, and sustainable logistics, aligning with Japan's commitment to environmental responsibility. These opportunities underscore the potential for AI to drive innovation and reshape the retail landscape in Japan.
Market Segmentation Analysis:
By Component:
The Japan artificial intelligence in retail market is segmented into solutions and services. The solution segment dominates due to the rising adoption of AI-powered tools, such as machine learning algorithms, natural language processing, and computer vision systems, which enhance operational efficiency and improve customer experiences. These solutions enable retailers to optimize inventory management, streamline supply chain operations, and offer personalized shopping experiences. The services segment, encompassing consulting, integration, and maintenance services, is also gaining traction. Retailers are increasingly seeking professional expertise to implement and manage AI-driven technologies effectively, contributing to the steady growth of this segment.
By Business Function: The market is further segmented based on business functions, including marketing & sales, human resources, finance & accounting, operations, and cybersecurity. Marketing & sales lead the segment due to the increasing use of AI for targeted promotions, customer behavior analysis, and personalized recommendations. AI in operations is transforming supply chain management, inventory optimization, and automated checkout systems. In cybersecurity, AI is crucial for fraud detection and safeguarding sensitive data. Meanwhile, human resources and finance are adopting AI for talent acquisition, payroll management, and predictive financial modeling, making AI an integral part of retail business processes.
Segments:
Based on Component:
- Solution
- Services
Based on Business Function:
- Marketing & Sales
- Human Resources
- Finance & Accounting
- Operations
- Cybersecurity
Based on Technology:
- Machine Learning
- Natural Language Processing
- Chatbots
- Image and Video Analytics
- Swarm Intelligence
Based on Sales Channel:
- Omnichannel
- Brick and Mortar
Based on the Geography:
- Kanto Region
- Kansai Region
- Chubu Region
- Kyushu Region
- Other Regions
Regional Analysis
Kanto Region
The Kanto region holds the largest market share in the Japan artificial intelligence in retail market, accounting for over 35% in 2024. This dominance is attributed to the presence of Tokyo, a global hub for technology and innovation, and several leading retail companies that are early adopters of AI-driven solutions. Retailers in the Kanto region extensively use AI for customer behavior analysis, personalized marketing, and inventory optimization. The region also benefits from a highly urbanized population, increased consumer spending, and strong digital infrastructure, which support the implementation of advanced AI technologies. The government’s initiatives promoting digital transformation further strengthen the adoption of AI in retail across the Kanto region.
Kansai Region
The Kansai region, comprising cities like Osaka and Kyoto, holds approximately 25% of the market share and is expected to witness rapid growth during the forecast period. The region is known for its technological advancements and manufacturing expertise, making it a key contributor to AI innovation. Retailers in Kansai are increasingly leveraging AI for automation, including robotics for in-store operations and automated checkout systems. Additionally, the region’s focus on improving operational efficiency and customer experiences is driving the adoption of AI-powered tools. Growing investments in digital infrastructure and government support for AI research and development further bolster the market in Kansai.
Chubu Region
The Chubu region accounts for around 15% of the market share and is emerging as a promising area for AI adoption in retail. Cities like Nagoya, known for their industrial significance, are witnessing an increased focus on digital transformation. Retailers in this region are utilizing AI for predictive analytics, supply chain optimization, and real-time inventory management. The region’s robust manufacturing sector and access to technological resources contribute to the growing use of AI in retail. Moreover, the Chubu region is experiencing a rise in e-commerce platforms adopting AI technologies to enhance customer engagement and streamline operations, further driving market growth.
Kyushu Region
The Kyushu region holds a market share of approximately 10%, reflecting steady adoption of AI technologies in retail. Retailers in cities like Fukuoka are gradually embracing AI-powered solutions to improve customer experiences and operational efficiency. AI applications in this region primarily focus on personalized marketing, chatbots for customer service, and automated logistics systems. The region’s expanding retail sector, coupled with supportive government policies and investments in digital infrastructure, is expected to accelerate the adoption of AI in the coming years. Kyushu’s growing interest in sustainability initiatives also opens opportunities for AI integration to promote eco-friendly retail practices.
Key Player Analysis
- Infosys
- TCS
- Google LLC
- IBM Corporation
- Accenture
- NVIDIA
- Salesforce
- Microsoft Corporation
- SAP SE
- Oracle Corporation
- Amazon
- ServiceNow
- Bloomreach, Inc.
- Company 14
- Company 15
- Others
Competitive Analysis
The competitive landscape of the Japan Artificial Intelligence in Retail market is shaped by several leading players, including Infosys, TCS, Google LLC, IBM Corporation, Accenture, NVIDIA, Salesforce, Microsoft Corporation, SAP SE, Oracle Corporation, Amazon, ServiceNow, and Bloomreach, Inc. These companies are at the forefront of AI innovation, providing a diverse range of solutions tailored to the retail sector. Companies are focused on offering advanced solutions such as machine learning algorithms, data analytics, and cloud-based platforms that help retailers enhance customer experiences, streamline operations, and improve supply chain efficiency. A significant emphasis is placed on personalized marketing, predictive analytics, and AI-based automation to enable real-time decision-making and optimize inventory management. Additionally, retailers are adopting AI-powered customer service tools, including chatbots and virtual assistants, to improve customer interaction and engagement. Innovation is a key factor driving competition, with firms striving to differentiate themselves through the development of scalable, cost-effective AI technologies that cater to the specific needs of retail businesses. For instance, a report by The Asahi Shimbun highlighted that 41% of major Japanese companies are already using generative AI, with many focusing on improving operational efficiency and customer engagement. Companies are also leveraging partnerships, mergers, and acquisitions to expand their AI portfolios and increase market share. The growing demand for AI solutions in areas like automated checkout systems, robotics, and AI-driven security measures further intensifies the competitive environment in Japan's retail sector. As a result, technological advancements and ongoing investment in AI research and development remain critical for maintaining a competitive edge.
Recent Developments
- In January 2025, NVIDIA announced the NVIDIA AI Blueprint for retail shopping assistants, designed to transform shopping experiences both online and in stores. This blueprint helps developers create AI-powered digital assistants that can deliver personalized shopping experiences, drive higher conversion rates, and lower product return rates.
- In April 2024, Oracle introduced new AI capabilities within Oracle Fusion Cloud Customer Experience (CX) to help marketers, sellers, and service agents accelerate deal cycles. These capabilities automate time-consuming tasks and enable more precise targeting, engagement, and service of buyers.
- In January 2024, Microsoft unveiled new generative AI and data solutions at NRF 2024 to transform shopping experiences. These solutions span the retail shopper journey, from personalized shopping experiences to empowering store associates and unifying retail data.
- In January 2024, Salesforce announced new data and AI-powered tools at NRF 2024 to transform shopping experiences. These tools, powered by the Einstein 1 Platform, include AI content creation, digital storefronts, and shopper insights to enhance customer interactions, increase loyalty, and drive revenue.
- In January 2024, IBM reported at NRF 2024 that generative AI can bridge the consumer expectation gap by creating unified, integrated shopping experiences. The study showed dissatisfaction with current retail experiences and emphasized the role of AI in meeting consumer demands.
Market Concentration & Characteristics
The market concentration of Japan’s Artificial Intelligence in Retail industry is characterized by a blend of both global and local players, with a few key companies dominating the landscape while smaller firms contribute to innovation and niche developments. Large multinational corporations with strong technological capabilities, such as those providing AI-powered cloud platforms, machine learning solutions, and analytics tools, account for a significant portion of the market share. These major players focus on providing comprehensive, scalable solutions to large retailers, driving efficiencies in inventory management, personalized marketing, and customer service. At the same time, the market exhibits characteristics of rapid innovation, as smaller, specialized firms bring forward cutting-edge AI applications, such as robotics and AI-driven checkout systems, which cater to the evolving needs of retailers. The overall market structure is evolving, with a high degree of collaboration and partnership between tech providers and retailers. This fosters a dynamic environment where technological advancements and customer-centric AI solutions are rapidly introduced. As the demand for AI in retail continues to grow, the market is likely to become more concentrated, with a few dominant players maintaining strong market positions while smaller, innovative firms push the boundaries of AI technology. The combination of large-scale adoption and rapid innovation makes the market highly competitive and constantly evolving.
Report Coverage
The research report offers an in-depth analysis based on Component, Business Function, Technology, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Japan Artificial Intelligence in Retail market is expected to witness continued strong growth, driven by increasing demand for AI-powered automation and personalization.
- AI will increasingly play a central role in transforming the customer shopping experience through personalized recommendations and seamless interactions.
- The adoption of AI for supply chain optimization and demand forecasting will lead to more efficient inventory management and reduced operational costs.
- Retailers will continue investing in AI-driven customer service tools like chatbots and virtual assistants to improve customer engagement and reduce operational workloads.
- Automation through AI technologies will significantly impact in-store operations, with the widespread use of robotics and AI-driven checkout systems.
- Enhanced data analytics capabilities will empower retailers to make real-time decisions and improve marketing strategies, further boosting sales and customer loyalty.
- The rise of AI in cybersecurity will address growing concerns over data privacy and fraud, creating secure digital retail environments.
- AI solutions tailored to small and medium-sized retailers will become more affordable, leading to wider adoption across the sector.
- The integration of AI with other emerging technologies like IoT and 5G will further enhance the functionality and effectiveness of retail operations.
- Government initiatives and regulatory frameworks are expected to support AI development, ensuring a balanced approach to innovation and data privacy concerns in retail.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Japan Artificial Intelligence in Retail market?
What factors are driving the growth of the Japan Artificial Intelligence in Retail market?
What are the key segments within the Japan Artificial Intelligence in Retail market?
What are some challenges faced by the Japan Artificial Intelligence in Retail market?
Who are the major players in the Japan Artificial Intelligence in Retail market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Artificial Intelligence in Retail Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Japan Artificial Intelligence in Retail Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 460.71 million → 2032: USD 5,480.14 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Artificial Intelligence in Retail Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Artificial Intelligence in Retail Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Artificial Intelligence in Retail Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Japan Artificial Intelligence in Retail Drivers
- 3.3 Japan Artificial Intelligence in Retail Restraints & Challenges
- 3.4 Japan Artificial Intelligence in Retail Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Artificial Intelligence in Retail Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Artificial Intelligence in Retail Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Artificial Intelligence in Retail category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Artificial Intelligence in Retail Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Japan Artificial Intelligence in Retail Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Japan Artificial Intelligence in Retail in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Artificial Intelligence in Retail Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Japan Artificial Intelligence in Retail Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Japan Artificial Intelligence in Retail Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Artificial Intelligence in Retail (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Japan Artificial Intelligence in Retail
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Japan Artificial Intelligence in Retail – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Japan Artificial Intelligence in Retail – Priority Domestic Market 1
Chapter 10. Japan Artificial Intelligence in Retail – Priority Domestic Market 2
Chapter 11. Japan Artificial Intelligence in Retail – Priority Domestic Market 3
Chapter 12. Japan Artificial Intelligence in Retail – Priority Domestic Market 4
Chapter 13. Japan Artificial Intelligence in Retail Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
